
 Norway Aquaculture Market | 2026-2036
Norway Aquaculture Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Aquaculture Market Intelligence
Buyer concentration among European retail chains is decoupling from traditional spot-market purchasing toward long-term supply contracts. Mowi leverages its integrated value chain from feed to distribution to secure shelf space with continental supermarket groups. SalMar anchors its competitive position through offshore farming capacity at Ocean Farm 1 and Arctic Offshore Farming. Lerøy differentiates via its Lerøy Aurora brand strength in premium smoked salmon segments across German and French retail channels.
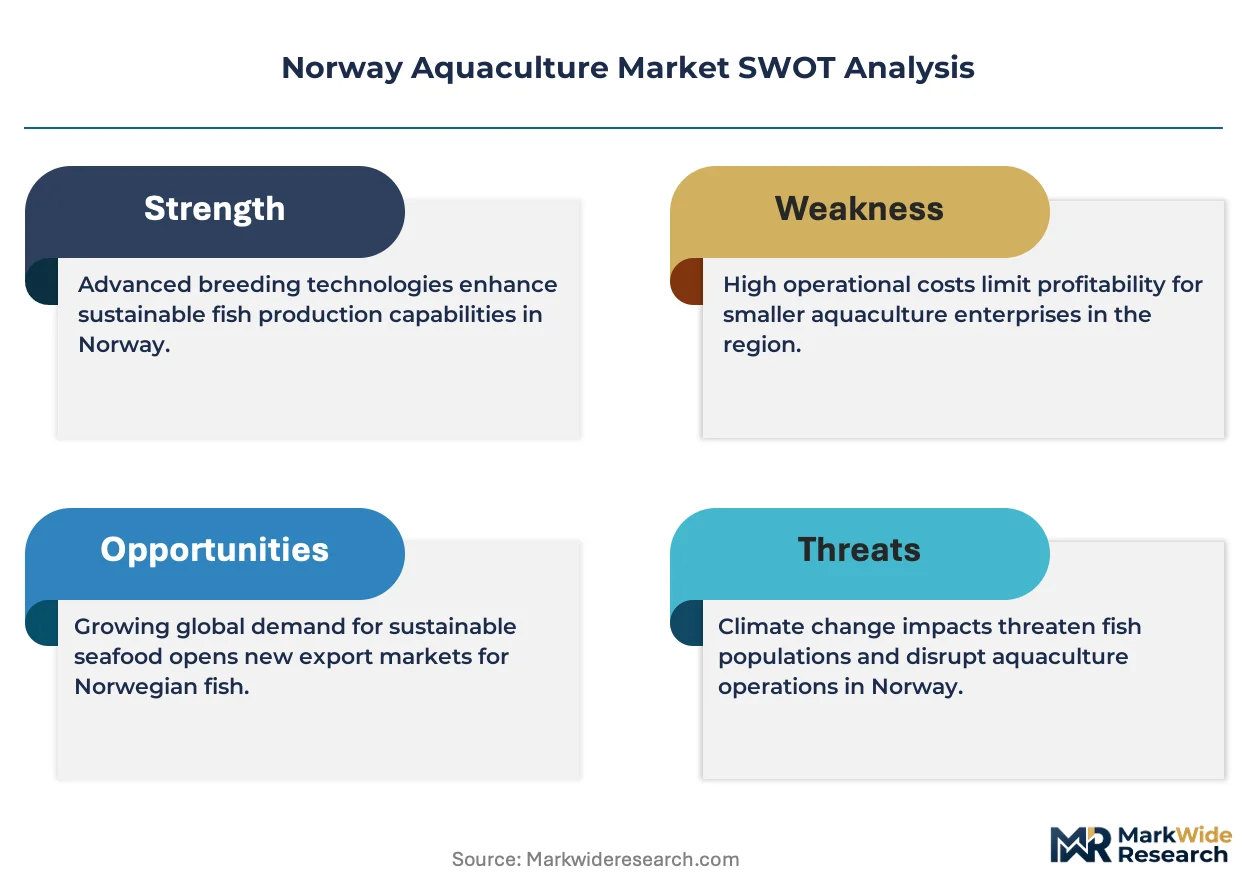
Norway aquaculture denotes the commercial cultivation of finfish and shellfish in controlled marine or land-based systems, typically operating at water temperatures between 4°C and 14°C and salinity levels matching coastal Norwegian fjords. The industry's primary purpose centers on producing protein for human consumption through biologically efficient conversion of feed to edible biomass. Salmon dominates volume output and margin capture across Norwegian production zones, while recirculating aquaculture systems represent the fastest-growing technology segment as land-based cod and trout ventures attract capital for disease containment and escape prevention. Shellfish cultivation remains structurally marginal despite favorable coastline access, constrained by limited processing infrastructure and weaker price formation relative to finfish alternatives.
Norwegian Food Safety Authority (Mattilsynet) enforces strict maximum allowable biomass limits per production site, directly constraining license holders' expansion trajectory and intensifying M&A activity for unused capacity. The EU Green Deal's sustainability benchmarks for imported seafood, combined with Norway's national escape prevention regulations, shape product standards and market access for exporters serving continental European buyers. Stakeholders must monitor licensing reform debates and offshore technology approval timelines to calibrate capital deployment between conventional cage systems and next-generation production platforms.
Market Dynamics
Norway's aquaculture sector operates under intensifying biomass constraints as Mattilsynet tightens site licensing through the traffic light system, forcing producers toward consolidation and alternative production platforms.
Growth Catalysts
- EU Green Deal sustainability benchmarks:Continental retail chains now mandate certified low-carbon seafood sourcing, pulling Norwegian salmon into premium shelf positions across German and French distribution networks.
- Offshore farming platforms:Floating closed-containment systems enable production beyond traditional fjord sites, unlocking capacity expansion in exposed coastal waters previously inaccessible for licensing.
- Recirculating aquaculture systems (RAS):Land-based smolt production is reducing marine phase duration and disease transfer risk, improving biological performance metrics across Nordland and Trøndelag operations.
Market Restraints
- Feed input cost volatility:Marine protein and vegetable oil price swings compress margin predictability for integrated producers dependent on formulated feed supply.
- Biomass limit scarcity:Mattilsynet's maximum allowable biomass caps per license create structural supply ceilings, inflating M&A premiums for unused production rights in high-performing zones.
- Sea lice chemical resistance:Parasite treatment efficacy decline is elevating operational complexity and forcing capital diversion toward mechanical and thermal delousing infrastructure.
Strategic Opportunities
- Trøndelag county expansion:Underutilized coastal zones in central Norway offer license aggregation potential as smaller operators face technical compliance cost pressures.
- Post-smolt RAS-to-sea transfer:Larger smolt deployment at sea is shortening time-to-harvest and reducing exposure to early-stage marine mortality events.
- Carbon-neutral certification premiums:EU Green Deal-aligned carbon accounting is creating price stratification between certified and conventional supply in continental retail procurement.
Industry Challenges
- Offshore platform engineering talent:Specialist expertise in subsea mooring, remote feeding systems, and vessel-scale husbandry remains concentrated among marine engineering contractors.
- Mattilsynet compliance documentation:Real-time biomass reporting, escape incident protocols, and veterinary audit trails impose administrative burden on mid-scale license holders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Aquaculture Market |
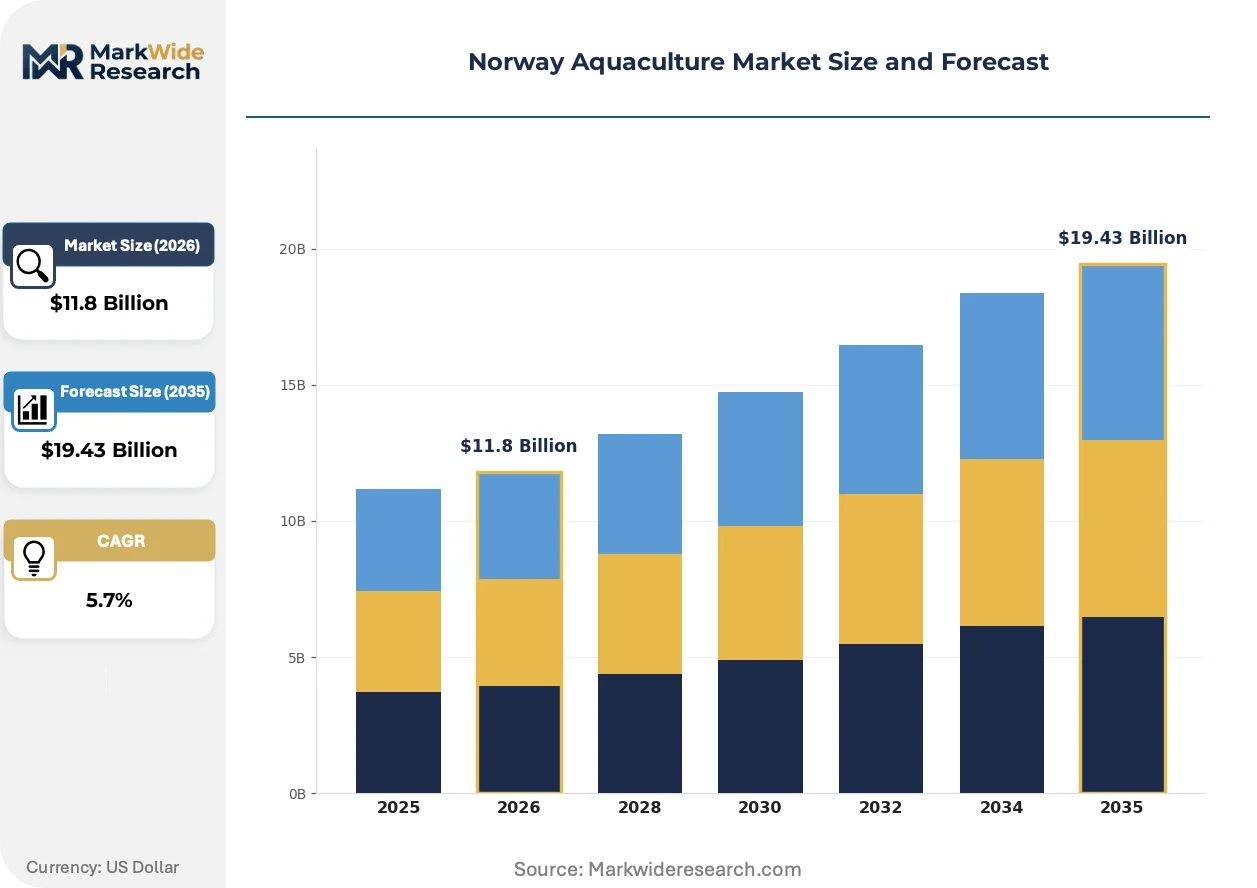
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salmon, Trout, Shellfish, Cod Technology: Recirculating Aquaculture Systems, Cages, Integrated Multi-Trophic Aquaculture, Floating Ocean Farms End User: Retail, Food Service, Exporters, Direct Sales Distribution Channel: Online, Wholesale, Supermarkets, Fish Markets |
| Companies Covered | Ode, Helgeland Smolt, Mowi, Ellingsen Seafood, Trøndersmolt, SalMar, Norcod, Steinvik, Lerøy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Aquaculture Market Strategic Shifts & Innovations
Biological risk management and production platform diversification are redefining capital allocation across Norwegian coastal zones, with technology convergence and regulatory stringency forcing operational model evolution.
Semi-closed containment systems are consolidating investment attention among producers seeking to reconcile escape prevention mandates with biological performance. Nordland-based operators are deploying these platforms at commercial scale to satisfy Mattilsynet lice-count thresholds while maintaining harvest weights. The technology is consolidating production into fewer, larger-capacity units that integrate mechanical delousing with controlled water exchange.
Mattilsynet's real-time biomass monitoring requirements are reshaping data infrastructure obligations across license holders. Automated cage sensors and cloud-based reporting portals now constitute baseline compliance architecture rather than operational optimization tools. Smolt-to-harvest integrators in Trøndelag are absorbing these fixed costs fastest, while smaller independent operators face disproportionate compliance burden.
Continental retail procurement is pivoting toward multi-year volume commitments with embedded sustainability audit rights. German and French supermarket groups are displacing spot-market purchasing with contract structures that transfer traceability verification obligations upstream to Norwegian exporters. This concentration of buyer power is visible in Lerøy Aurora and Mowi contract negotiations, where shelf-space access now trades against carbon-footprint disclosure granularity.
Norway Aquaculture Market Segmentation
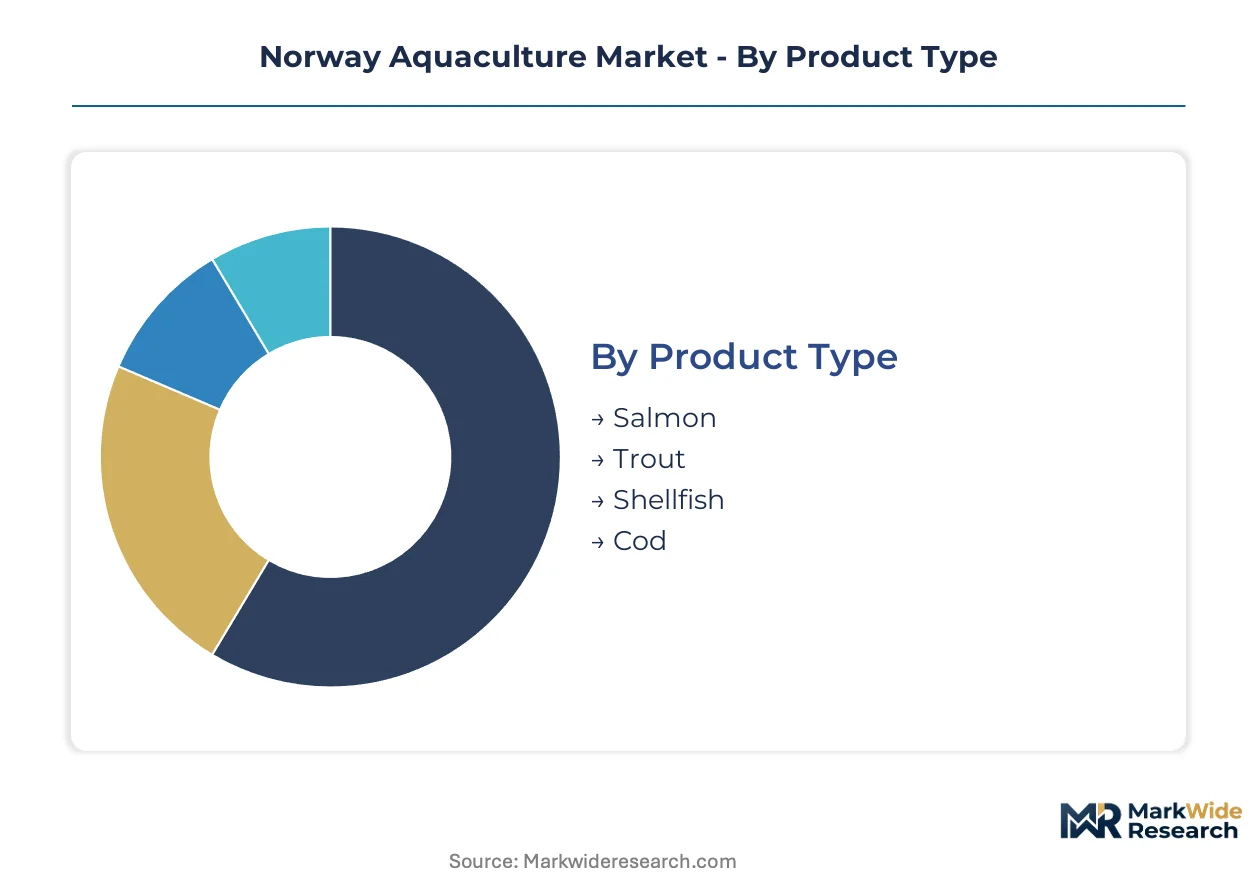
Segmentation in Norwegian aquaculture reveals how production constraints reshape competitive positioning across species, technologies, and buyer channels. Mattilsynet's biomass limits force operators to optimize within narrower strategic windows than global peers.
Product Type:
Standalone finfish operations dominate license utilization, while integrated multi-species ventures embed shellfish or cod within diversified portfolios.
- Salmon:Atlantic salmon accounts for the overwhelming share of Norwegian biomass allocation and export revenue. Nordland and Trøndelag counties concentrate smolt-to-harvest operations serving German and French retail procurement.
- Trout:Rainbow trout occupies secondary license capacity, often in freshwater lake systems or coastal zones with lower temperature profiles. Domestic consumption and select export markets absorb output, constrained by weaker price formation relative to salmon alternatives.
- Shellfish:Mussel and oyster cultivation remains marginal despite extensive coastline access.
- Cod:Land-based and marine cod farming attracts RAS investment for disease containment and escape prevention compliance.
Salmon leads volumes today; cod farming is gaining share fastest.
Technology:
Cost tier stratification separates capital-intensive closed systems from conventional open-cage infrastructure.
- Recirculating Aquaculture Systems:Land-based closed containment enables full lifecycle production or post-smolt conditioning before sea transfer. Trøndelag operators deploy RAS to shorten marine phase duration and satisfy Mattilsynet lice-count thresholds.
- Cages:Traditional open-net pen systems retain lowest capital cost per kilogram but face tightening escape prevention and chemical treatment regulations.
- Integrated Multi-Trophic Aquaculture:Co-cultivation of finfish with extractive species like kelp or mussels remains experimental in Norwegian waters.
- Floating Ocean Farms:Exposed-site platforms extend production beyond fjord shelter, requiring subsea mooring engineering and remote feeding infrastructure.
Cage systems retain volume dominance; floating ocean farms are climbing the fastest.
End User:
Customer type concentration drives contract structure divergence between spot-market liquidity and long-term supply commitments.
- Retail:Continental European supermarket chains now mandate multi-year volume agreements with embedded carbon-footprint audit rights.
- Food Service:Restaurant and hospitality procurement is consolidating among larger buyers seeking consistent quality grading.
- Exporters:Third-party trading houses handle spot-market arbitrage between Norwegian production and global demand nodes.
- Direct Sales:Local consumption and regional distribution bypass consolidated wholesale channels.
Retail channels lead volumes today; direct sales are expanding most quickly.
Distribution Channel:
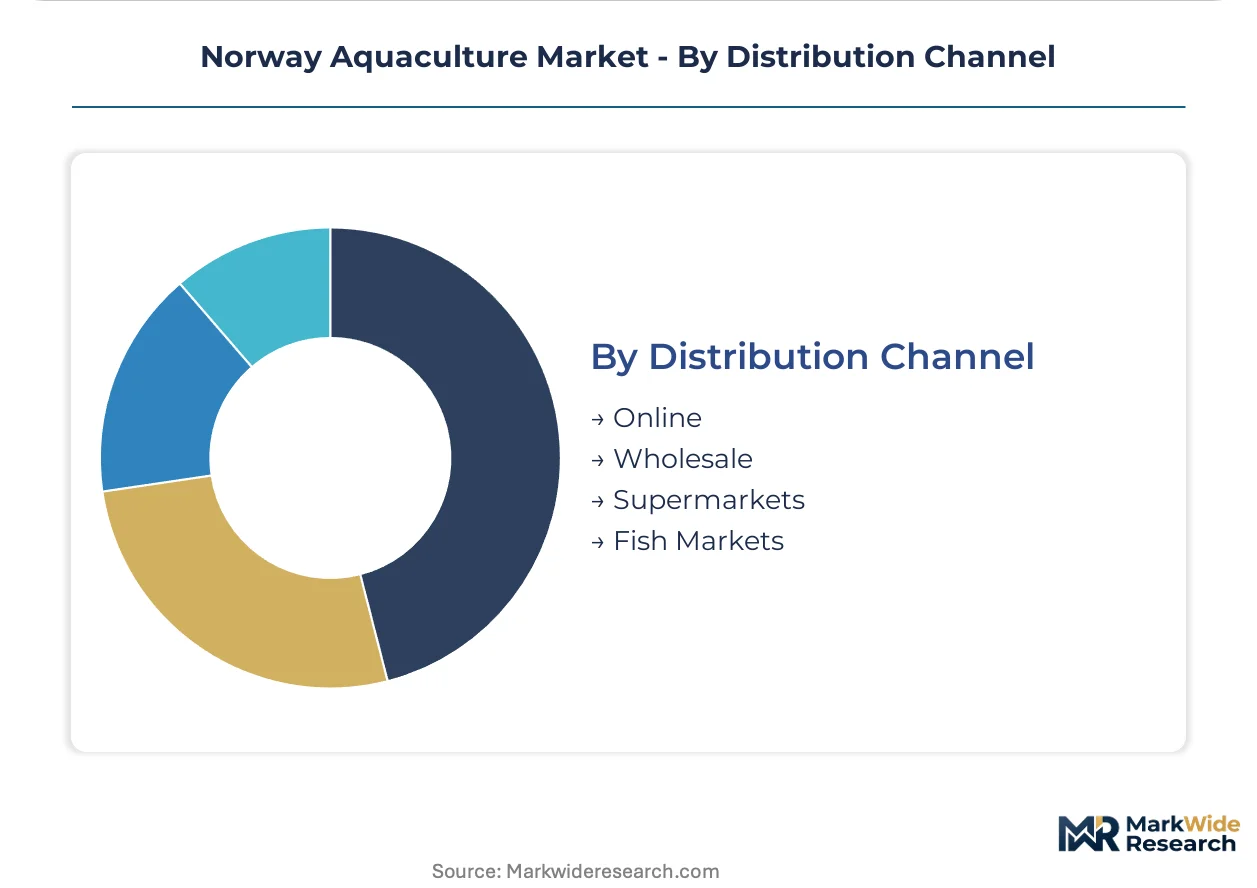
Supply concentration favors wholesale intermediaries, while digital platforms fragment final-mile access.
- Online:E-commerce penetration in fresh seafood remains limited by cold-chain logistics complexity and consumer quality verification preferences.
- Wholesale:Centralized distribution through Bergen and Ålesund hubs feeds continental European processing and retail networks.
- Supermarkets:German and French retail groups source through direct supplier relationships with integrated Norwegian producers.
- Fish Markets:Traditional auction and terminal markets handle spot-price discovery for smaller independent harvesters.
Wholesale channels lead volumes today; online distribution is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and France import comparable salmon volumes from Norway, yet German retail chains impose stricter carbon-footprint audit requirements on their Norwegian suppliers. This divergence in procurement standards is reshaping exporter strategies across continental Europe.
Germany
German supermarket groups source Norwegian salmon through multi-year contracts with embedded sustainability verification. The EU Green Deal's carbon benchmarks for imported seafood shape procurement specifications. Hamburg and Bremen processing hubs handle volume consolidation for Rewe and Edeka distribution networks.
France
French retail buyers prioritize Lerøy Aurora and Mowi brands for premium smoked salmon shelf placement. EFSA guidelines on aquaculture residue limits inform import inspection protocols. Rungis wholesale market near Paris serves as the primary clearinghouse for Norwegian fresh salmon entering the French food service channel.
United Kingdom
UK food service buyers consolidate procurement through larger distributors seeking consistent quality grading. The UK's post-Brexit border inspection regime adds documentation layers for Norwegian exporters. Scottish salmon farming competes directly with Norwegian supply in London and Southeast retail channels.
Spain
Spanish processors absorb Norwegian raw material for value-added product export to Latin American markets. EU IUU fishing regulation compliance certificates are mandatory for customs clearance. Vigo and Barcelona harbor zones concentrate cold-storage infrastructure for Atlantic salmon redistribution.
Poland
Polish smoking and processing facilities purchase Norwegian salmon for re-export to Central European markets. EU food safety authority inspections govern facility approval for Norwegian supplier relationships. Gdańsk and Szczecin processing clusters expand capacity to serve German and Czech retail buyers.
Norway Aquaculture Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across Norwegian coastal zones. The sector exhibits moderate consolidation, with integrated smolt-to-harvest operators commanding premium valuations for unused biomass capacity. Three archetypes dominate: vertically integrated salmon producers, land-based RAS technology ventures, and regional smolt specialists supplying third-party growers. M&A activity targets license aggregation in Nordland and Trøndelag counties, while capital flows toward offshore platform engineering capabilities.
Among Norwegian-integrated producers, Mowi, SalMar, and Lerøy occupy positions that exemplify scale-driven competitive positioning. Mowi represents the diversified conglomerate archetype with feed-to-distribution integration. SalMar anchors the offshore technology vector through floating ocean farm deployment. Lerøy sits within the premium brand differentiation tier, leveraging Aurora-label recognition in continental retail channels.
| Leading Market Players |
|---|
| Ode |
| Helgeland Smolt |
| Mowi |
| Ellingsen Seafood |
| Trøndersmolt |
| SalMar |
| Norcod |
| Steinvik |
| Lerøy |
| Others |
Cost & Logistics Intelligence
Post-smolt RAS-to-sea transfer protocols are compressing marine phase duration while simultaneously concentrating production economics among operators with capital access for integrated land-based conditioning facilities. This technology shift feeds directly into supply consolidation as smaller license holders face technical compliance cost barriers.
Pricing Analysis
Capacity additions in Trøndelag county are reshaping price floors for Atlantic salmon as post-smolt deployment shortens time-to-harvest cycles. Three-tier pricing structure across premium certified, standard commercial, and economy-grade segments stratifies around EU Green Deal carbon-footprint verification and Mattilsynet lice-count compliance. Cost compression in the economy tier is intensifying because feed input volatility and biomass limit scarcity inflate operational leverage for non-integrated operators. Retail procurement teams at continental European supermarket groups exhibit lowest price sensitivity, while spot-market exporters and third-party trading houses absorb highest margin pressure.
Supply Chain Analysis
Specialist engineering talent availability in Norway, Scotland, and Denmark constrains deployment velocity for floating ocean farm platforms and subsea mooring systems. The Norwegian supply chain draws from Chilean and Scottish marine protein sources for formulated feed, alongside vegetable oil inputs from European and South American agricultural processors. Single-source vulnerability sits with concentrated engineering contractors capable of exposed-site platform construction. Distribution runs through Bergen and Ålesund wholesale hubs feeding continental European processing and retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through carbon-neutral certification premiums as continental retail procurement shifts toward verified low-carbon supply contracts. RAS technology adoption compresses biological risk costs while opening premium-tier positioning.
For Market Incumbents: Hedge biomass limit exposure through license aggregation in Nordland and Trøndelag counties before Mattilsynet tightens traffic light system allocations further. Prioritize backward integration into post-smolt RAS capacity to shorten marine phase duration and reduce early-stage mortality exposure. Secure multi-year supply contracts with embedded sustainability audit rights to lock in shelf-space access against emerging offshore platform competitors. For New Entrants and Emerging Players: Floating closed-containment systems offer a technology-first wedge into exposed coastal waters beyond traditional fjord licensing constraints. Target underutilized central Norway coastal zones for license aggregation as smaller operators face technical compliance cost pressures. Pursue carbon-neutral certification pathways early to access premium procurement channels at German retail chains. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale independent license holders with unused biomass capacity in high-performing production zones. Five-to-ten year viability hinges on successful navigation of offshore technology approval timelines and Mattilsynet compliance documentation automation. Watch for traffic light system recalibration announcements as inflection indicators for license value appreciation.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Smolt RAS Capacity Expansion | Shortens marine phase duration and satisfies Mattilsynet lice-count thresholds for premium certification access. |
| Offshore Platform Engineering Partnership | Unlocks production capacity in exposed coastal waters beyond traditional fjord licensing constraints. |
| Carbon-Neutral Certification Program | Aligns supply contracts with EU Green Deal procurement specifications at German and French retail chains. |
| License Aggregation in Trøndelag | Consolidates unused biomass capacity as smaller operators face technical compliance cost pressures. |
| Mechanical Delousing Infrastructure Deployment | Addresses sea lice chemical resistance through capital investment in thermal and mechanical treatment systems. |
Research Approach
Multiple input streams — executive interviews with integrated salmon producers, regulatory consultation with Mattilsynet compliance officers, and procurement dialogue with continental European retail buyers — were reconciled against customs trade data, Norwegian Seafood Council export statistics, and EU IUU fishing regulation compliance records. Bottom-up volume modeling across production sites was cross-validated with top-down revenue estimates derived from export value disclosures.
Historical harvest volume trajectories were cross-referenced against expert panel assessments of technology adoption curves and regulatory approval timelines. Segmentation modeling spanned species type, production technology platform, end-user channel, and geographic export destination. CAGRs were derived through iterative reconciliation of biological performance metrics, biomass limit constraints, and buyer concentration trends. Industry-specific forecast inputs included Mattilsynet traffic light system recalibration schedules and EU Green Deal carbon accounting implementation progress.
The model holds under stable regulatory enforcement and continued continental retail procurement consolidation; deviation in offshore platform approval delays or feed input cost spikes would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Vietnam Aquafeed Market
Aquaculture Innovations
Global Precision Aquaculture Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market
Aquaculture Innovations
Kuwait Fisheries and Aquaculture Market
Aquaculture Innovations
Fish Farming Equipment Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
APAC Aquafeed Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Global Aquaculture Vaccine Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Sandfish Market
Aquaculture Innovations
Fish Breeding Tank Market