
 Aquaculture Therapeutics Market | 2026-2036
Aquaculture Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Aquaculture Therapeutics Market Outlook
Veterinary pharmacology expertise is collapsing across coastal research institutes, narrowing the pipeline for novel aquatic drug candidates. Zoetis leverages its mammalian vaccine platforms to cross-develop immersion delivery systems for finfish. Merck Animal Health anchors European salmonid health programs through its aqua-dedicated formulation labs. Elanco Animal Health competes in Latin American shrimp markets with specialized anti-parasitic portfolios.
Aquaculture therapeutics comprise pharmaceutical and biological agents formulated for disease prevention, treatment, and productivity enhancement in farmed aquatic species, typically administered via feed, bath, or injection at species-specific dosage thresholds measured in milligrams per kilogram of biomass. Vaccines command the highest margin pools among product types due to cold-chain requirements and batch certification complexity, while probiotics represent the fastest-expanding category as producers phase out antibiotic growth promoters. Application demand clusters heavily in infectious disease management, reflecting intensification density in net-pen and recirculating aquaculture systems, whereas parasite control generates premium pricing in warm-water shrimp farming across Southeast Asia.
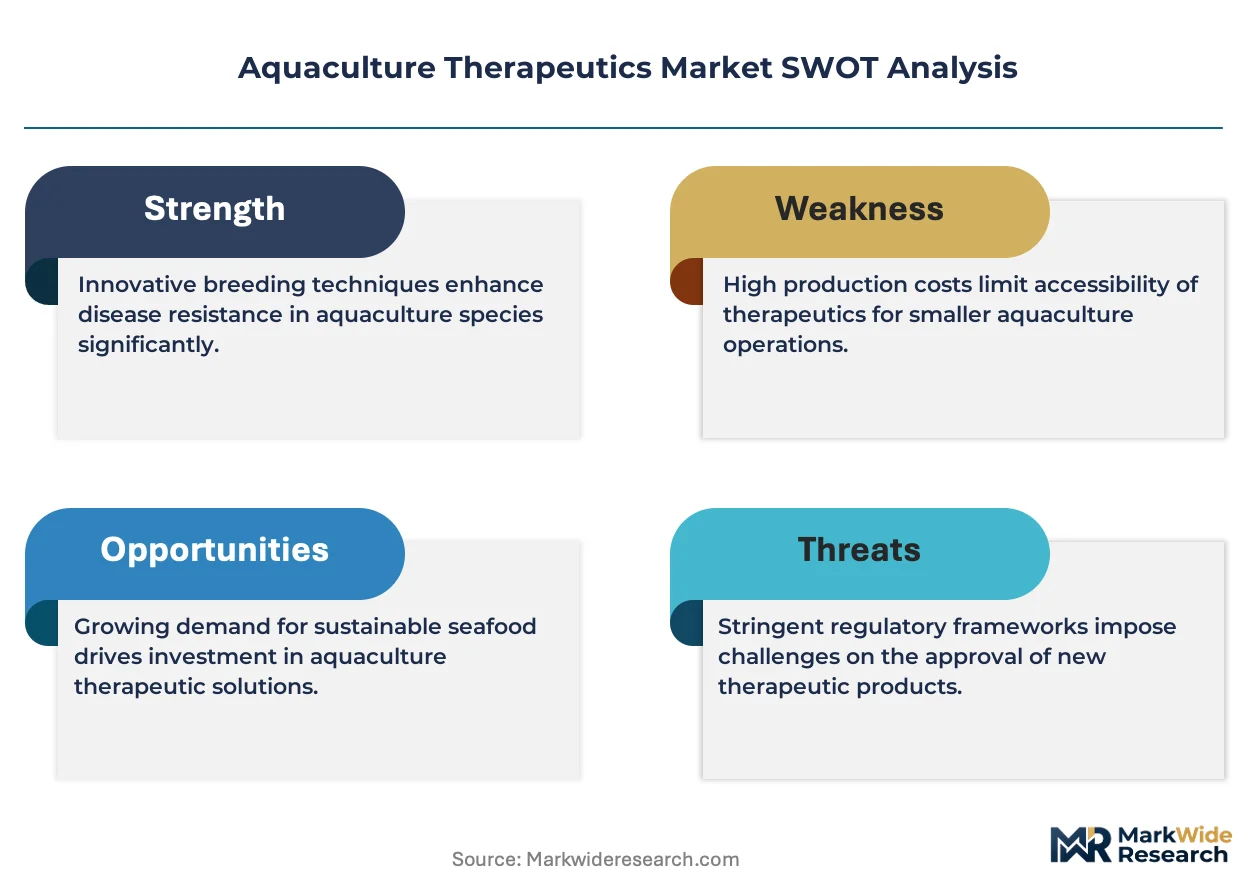
EMA residue monitoring frameworks and FDA aquaculture drug approval pathways constrain market entry timelines, forcing manufacturers to compile extensive environmental impact dossiers before commercial authorization. EU Green Deal sustainable aquaculture targets and REACH chemical substance evaluations further redirect R&D investment toward biodegradable alternatives and closed-system compatible treatments. Stakeholders must track regulatory divergence between jurisdictions to anticipate which formulation categories will face accelerated restriction or expedited approval.
Market Dynamics
EMA residue monitoring frameworks are compressing approval timelines for novel aquatic pharmaceuticals, forcing manufacturers to front-load environmental toxicology dossiers before clinical efficacy trials commence.
Growth Catalysts
- EU Green Deal sustainable aquaculture targets:Norwegian salmon producers are accelerating vaccine adoption to meet biodegradability mandates for therapeutics used in open net-pen systems.
- Infectious pancreatic necrosis outbreaks:Chilean Atlantic salmon operations are expanding preventive immunization programs to reduce mortality-driven biomass losses.
- Phage therapy platforms:Bacteriophage cocktails targeting Flavobacterium columnare are gaining traction in Vietnamese pangasius hatcheries as antibiotic alternatives.
Market Restraints
- Active pharmaceutical ingredient concentration:Three Chinese manufacturers control over 70% of bulk oxytetracycline supply, exposing formulators to input cost volatility and geopolitical disruption.
- Cold-chain infrastructure gaps:RNA-based vaccines require maintenance at minus 70 degrees Celsius, a threshold unreachable in Indonesian smallholder shrimp ponds without capital-intensive reefer investment.
- REACH chemical substance evaluations:ECHA's extended aquatic toxicity testing protocols are extending registration timelines for novel parasiticides by 18-24 months.
Strategic Opportunities
- Recirculating aquaculture system expansion:Indoor Atlantic salmon production in Maine and Denmark creates demand for closed-loop compatible therapeutics with zero effluent discharge profiles.
- Probiotic-microbiome modulation:Lactobacillus and Bacillus strain cocktails are displacing antibiotic growth promoters in Ecuadorian shrimp ponds facing early mortality syndrome pressure.
- FDA aquaculture drug approval pathway reform:Minor-use minor-species designation expansion is accelerating commercial authorization for therapeutics targeting ornamental koi and sturgeon.
Industry Challenges
- Veterinary pharmacology expertise collapse:Coastal research institutes in Scotland and British Columbia are shuttering aquatic medicine programs, narrowing the pipeline for species-specific formulation scientists.
- Batch certification complexity:Vaccine potency testing for Aeromonas salmonicida requires 21-day challenge studies, creating inventory bottlenecks during seasonal stocking peaks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquaculture Therapeutics Market |
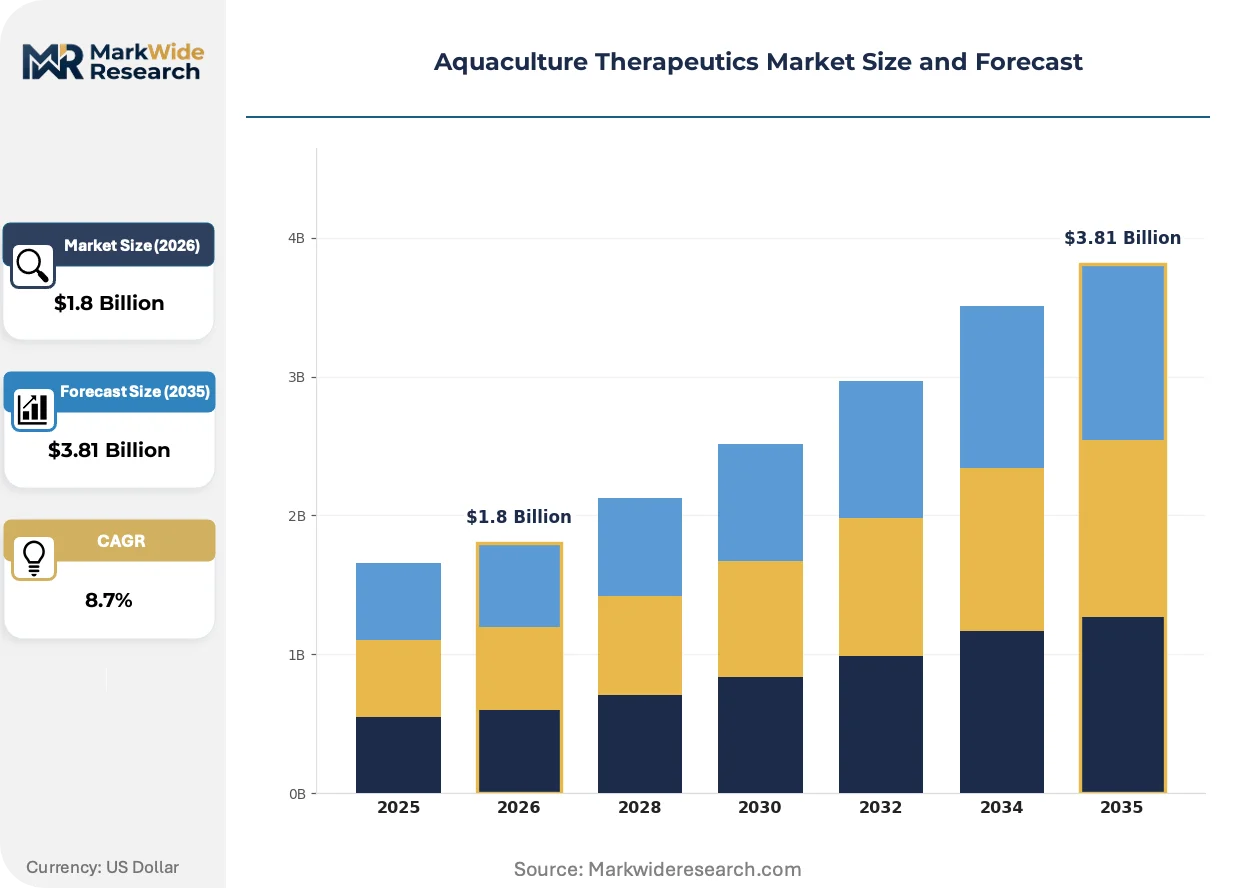
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Probiotics, Chemicals Application: Infectious Diseases, Parasite Control, Growth Promotion, Water Quality Management Formulation Type: Liquid, Powder, Granules, Gel Fish Type: Salmon, Tilapia, Catfish, Shrimp |
| Companies Covered | Zoetis, Merck Animal Health, Boehringer Ingelheim, Elanco Animal Health, Nutreco, Cargill, Alltech, Phibro Animal Health, Skretting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquaculture Therapeutics Market Strategic Shifts
Biological therapeutics are displacing chemical interventions across finfish and crustacean operations, driven by residue scrutiny and export market access requirements.
Recombinant subunit vaccines are decomposing the dominance of inactivated whole-cell formulations in salmonid health programs. Norwegian and Chilean producers are adopting these platforms to reduce adjuvant-related tissue reactions. The technology is decomposing margin structures for legacy vaccine suppliers while enabling premium pricing for precision-targeted immunogens.
REACH chemical substance evaluations are redirecting R&D investment toward biodegradable alternatives. ECHA's extended aquatic toxicity testing protocols are forcing manufacturers to abandon persistent organophosphates in favor of rapidly hydrolyzing compounds. Warm-water shrimp farming across Thailand and Vietnam is most affected, with producers accelerating trials of essential oil-based parasiticides.
Integrated health service contracts are consolidating procurement decisions for Vietnamese pangasius cooperatives. Diagnostic-laboratory-therapeutic bundles are displacing spot-market pharmaceutical purchases. This pattern is most visible in the Mekong Delta, where large processing exporters are mandating unified health protocols from contracted grow-out farms.
Aquaculture Therapeutics Market Segmentation
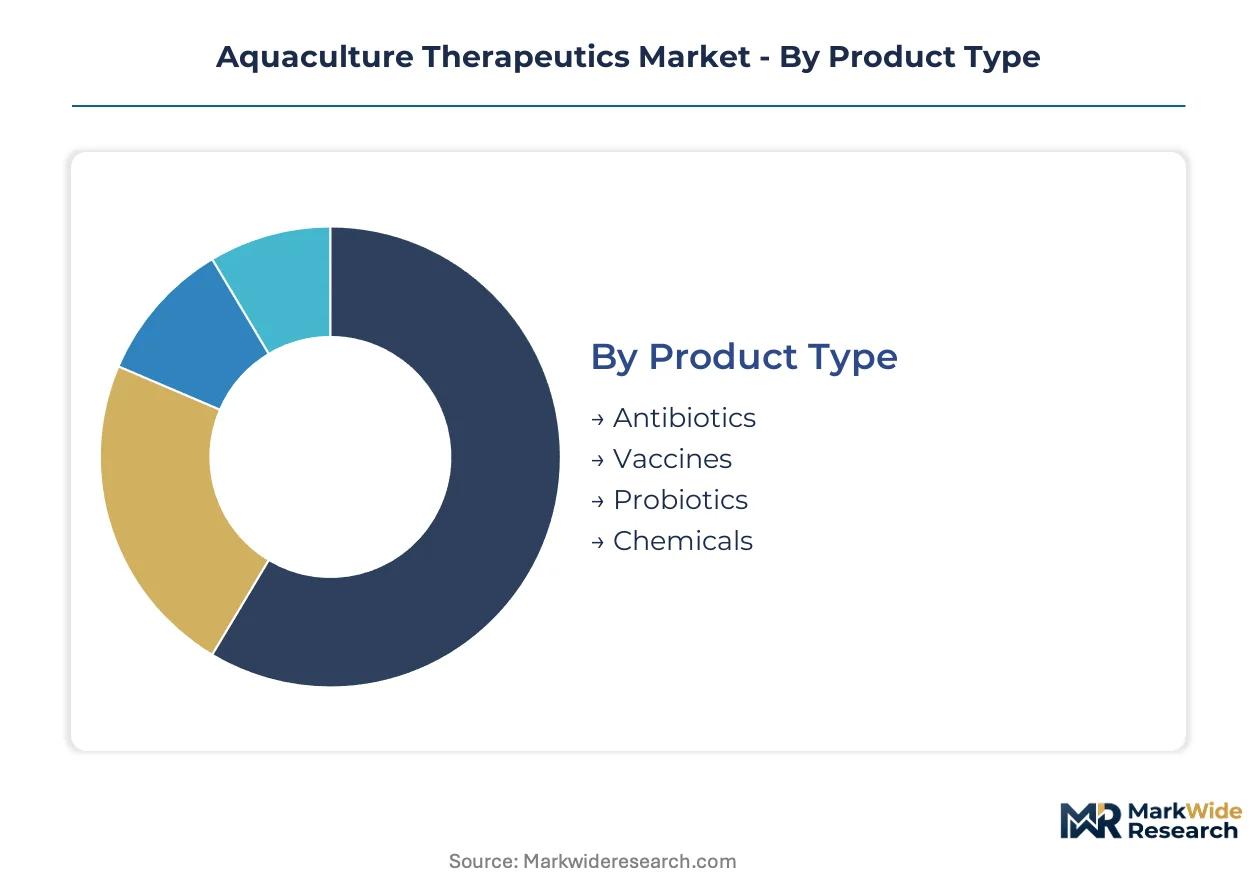
Aquaculture therapeutics segmentation reflects divergent regulatory pathways across product categories, with EMA residue thresholds and FDA approval timelines creating distinct commercial zones for chemical versus biological interventions. Formulation choices and species targeting further stratify procurement decisions based on cold-chain infrastructure and hatchery scale.
Product Type:
EMA residue monitoring frameworks and FDA aquaculture drug approval pathways impose divergent compliance burdens across therapeutic categories, reshaping manufacturer R&D allocation and distributor inventory strategies.
- Vaccines:Biological preparations containing inactivated or recombinant antigens targeting specific pathogens such as Aeromonas salmonicida and infectious pancreatic necrosis virus. Norwegian salmon producers dominate procurement under EU Green Deal biodegradability mandates, though batch certification complexity creates 21-day inventory bottlenecks during seasonal stocking peaks.
- Probiotics:Live microbial cultures of Lactobacillus and Bacillus strains formulated for gut microbiome modulation and disease resistance enhancement. Ecuadorian shrimp operations facing early mortality syndrome pressure represent the fastest-adopting customer segment as producers phase out antibiotic growth promoters.
- Antibiotics:Oxytetracycline and florfenicol formulations administered via medicated feed or bath immersion for bacterial infection control.
- Chemicals:Synthetic parasiticides and disinfectants including formalin and hydrogen peroxide derivatives for external pathogen management.
Established volume favors vaccines; emerging adoption favors probiotics.
Application:
Intensification density in net-pen and recirculating aquaculture systems concentrates therapeutic spending toward disease prevention over reactive treatment.
- Infectious Diseases:Therapeutic interventions targeting viral and bacterial pathogens including infectious pancreatic necrosis and Flavobacterium columnare. Chilean Atlantic salmon operations confronting recurring outbreaks anchor global demand, with preventive immunization programs reducing mortality-driven biomass losses.
- Parasite Control:Anti-helminthic and ectoparasitic treatments for sea lice and gill fluke infestations. Southeast Asian warm-water shrimp farming across Thailand and Vietnam generates premium pricing as producers accelerate trials of essential oil-based alternatives under REACH chemical substance evaluations.
- Growth Promotion:Feed additives and metabolic enhancers improving feed conversion ratios and harvest weights.
- Water Quality Management:pH stabilizers, ammonia binders, and oxygenation aids for closed-system aquaculture environments.
Preventive applications command margin premiums; reactive treatments face pricing compression from generic competition.
Formulation Type:
Cold-chain infrastructure gaps and capital access determine formulation viability across hatchery scale tiers.
- Liquid:Aqueous suspensions and emulsions for bath administration and vaccine delivery. RNA-based vaccine formats requiring minus 70 degrees Celsius storage face adoption barriers in Indonesian smallholder shrimp ponds without reefer investment.
- Powder:Dry concentrates for feed incorporation and tank dosing. Vietnamese pangasius cooperatives favor powder antibiotics for ease of transport and ambient storage compatibility in Mekong Delta distribution networks.
- Granules:Slow-release coated particles for extended therapeutic delivery in pond environments.
- Gel:Viscous preparations for topical wound treatment and mucosal vaccine administration.
Powder formulations dominate volume; liquid formats capture value concentration in regulated salmonid markets.
Fish Type:
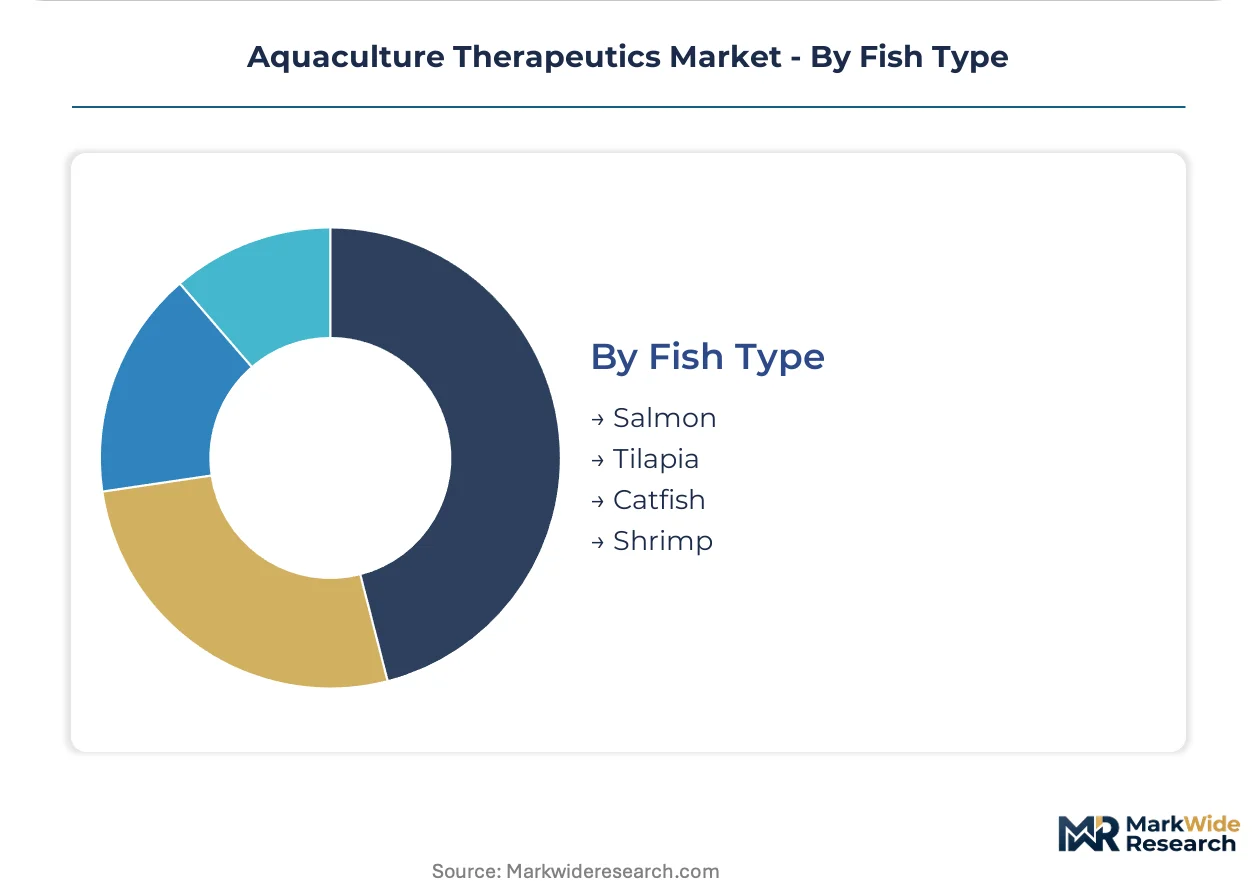
Species-specific physiology and farming intensity create divergent therapeutic requirement profiles across finfish and crustacean categories.
- Shrimp:Crustacean-specific therapeutics addressing early mortality syndrome and white spot syndrome virus. Southeast Asian pond operations in Vietnam, Thailand, and Ecuador drive category expansion through integrated health service contracts bundling diagnostics, laboratory services, and therapeutics.
- Salmon:High-value finfish therapeutics concentrated in Norwegian and Chilean Atlantic salmon production. Recirculating aquaculture system expansion in Maine and Denmark creates demand for closed-loop compatible treatments with zero effluent discharge profiles.
- Tilapia:Warm-water finfish therapeutics for bacterial septicemia and streptococcal infections in African and Latin American pond systems.
- Catfish:Channel and pangasius catfish therapeutics targeting columnaris disease and parasitic infestations in Mississippi Delta and Mekong Delta operations.
Salmon anchors value concentration; shrimp drives volume expansion across emerging producer economies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian salmon operations consume therapeutics through preventive vaccine programs, whereas Vietnamese pangasius farms rely on reactive antibiotic dosing integrated with diagnostic bundles. This consumption-mix differential shapes procurement patterns across coastal aquaculture clusters.
Norway
Atlantic salmon producers in Bergen and Trøndelag counties drive vaccine procurement volumes under EU Green Deal biodegradability mandates. EMA residue monitoring frameworks compress approval timelines for novel pharmaceuticals. Tromsø-based research clusters coordinate cold-chain logistics for RNA-based immunization platforms.
Chile
Los Lagos and Aysén regions anchor infectious pancreatic necrosis immunization demand among Atlantic salmon operations. The country's national pharmaceutical regulator enforces export-market residue thresholds aligned with US FDA import requirements. Puerto Montt industrial parks concentrate formulation packaging for Patagonian distribution networks.
Vietnam
Mekong Delta pangasius cooperatives bundle diagnostics with probiotic and antibiotic procurement through integrated health service contracts. The Ministry of Agriculture and Rural Development monitors aquatic drug residues for EU export compliance. Cần Thơ processing hubs mandate unified therapeutic protocols from contracted grow-out farms.
United States
Maine recirculating aquaculture system operators seek closed-loop compatible therapeutics with zero effluent discharge profiles. FDA aquaculture drug approval pathways constrain market entry through extensive environmental impact dossier requirements. Portland-area indoor salmon facilities test immersion delivery systems adapted from mammalian vaccine platforms.
Indonesia
Smallholder shrimp ponds in Java and Sulawesi face adoption barriers for RNA-based vaccines requiring minus 70 degrees Celsius storage without reefer investment. The country's national pharmaceutical regulator harmonizes with ASEAN mutual recognition arrangements for aquatic drug registration. Surabaya distribution networks favor powder antibiotics for ambient storage compatibility.
Aquaculture Therapeutics Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling formulation laboratories and cold-chain infrastructure while specialists concentrate on species-specific delivery mechanisms. The competitive terrain splits between pharmaceutical conglomerates leveraging mammalian platforms and feed-integrated nutrition companies bundling therapeutics with ration formulations. Two strategic archetypes dominate: vaccine platform cross-developers and probiotic microbiome modulation specialists. Competitive moves center on backward integration into active pharmaceutical ingredient sourcing and geographic expansion through diagnostic-therapeutic bundled service contracts.
Among US-based animal health conglomerates, Zoetis and Merck Animal Health exemplify the platform-crossover archetype, while Elanco Animal Health occupies a position within the anti-parasitic specialization tier. These three entities anchor the premium vaccine and pharmaceutical segments through their respective aqua-dedicated laboratories and formulation capabilities. Boehringer Ingelheim, as a German family-owned enterprise, represents the European integrated health services model with its emphasis on closed-system compatible therapeutic development.
| Leading Market Players |
|---|
| Zoetis |
| Merck Animal Health |
| Boehringer Ingelheim |
| Elanco Animal Health |
| Nutreco |
| Cargill |
| Alltech |
| Phibro Animal Health |
| Skretting |
| Others |
Value Chain & Pricing Dynamics
Twenty-one-day batch certification bottlenecks for Aeromonas salmonicida vaccines concentrate pricing power with Norwegian and Chilean formulators possessing in-house potency testing infrastructure, while spot-market antibiotic purchasers in Southeast Asian shrimp operations face volatile input costs tethered to Chinese API export quotas.
Pricing Analysis
Long-term offtake contracts dominate Norwegian salmonid vaccine procurement, locking in premium pricing for cold-chain compliant suppliers while spot-market powder antibiotics in Vietnamese pangasius operations compete on ambient-storage logistics. Price differentiation separates GMP-certified European manufacturers from economy-tier Indian formulators facing REACH registration delays. Cost compression in generic oxytetracycline intensifies because three Chinese API producers control bulk supply concentration. Smallholder Indonesian shrimp farmers exhibit highest price sensitivity, whereas Maine recirculating aquaculture system operators accept therapeutic premiums for zero-discharge formulation compatibility.
Supply Chain Analysis
Inventory cycles stretching 45-60 days for RNA-based vaccines expose Indonesian and Vietnamese distributors to spoilage risk absent reefer infrastructure investment. Active pharmaceutical ingredient production concentrates in China and India, with formulation finishing clustering in Norway, Chile, and Denmark. Raw material dependencies include bulk oxytetracycline, adjuvant-grade aluminum hydroxide, and cold-chain refrigerants. Single-source vulnerability runs through Chinese API export licensing. Distribution runs through diagnostic-therapeutic bundled service contracts in Mekong Delta cooperatives and direct-to-farm cold-chain logistics in Scandinavian net-pen clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological therapeutic displacement of chemical interventions constitutes a high-growth disruption, with EU Green Deal biodegradability mandates and FDA minor-use pathway reforms compressing traditional pharmaceutical timelines.
For Market Incumbents: Fortify vaccine platform advantages through captive cold-chain infrastructure investment in Tromsø and Puerto Montt logistics hubs. Secure backward integration into adjuvant-grade raw material sourcing to defend margin position against Chinese API volatility. Prioritize diagnostic-therapeutic bundle penetration in Vietnamese pangasius cooperatives before integrated health service contracts consolidate procurement decisions. For New Entrants and Emerging Players: Diagnostic-laboratory service gaps in Indonesian smallholder shrimp ponds offer white-space entry points where incumbents under-serve cold-chain constrained operations. Target probiotic microbiome modulation in Ecuadorian early mortality syndrome pressure zones as the most penetrable application segment. Pursue phage therapy platform development for Flavobacterium columnare as a differentiated antibiotic-alternative go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from feed-integrated nutrition conglomerates seeking to divest non-core aqua-therapeutic divisions amid biological therapeutic transition pressure. Long-term viability centers on species-specific formulation capabilities and regulatory dossier depth across EMA and FDA jurisdictions. Monitor REACH chemical substance evaluation acceleration as the critical inflection signal for biodegradable alternative R&D prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Bundle Expansion | Mekong Delta cooperatives mandate unified health protocols from contracted grow-out farms. |
| Cold-Chain Infrastructure Investment | RNA-based vaccine formats require minus 70 degrees Celsius storage unreachable in Indonesian smallholder ponds. |
| Phage Therapy Platform Development | Bacteriophage cocktails targeting Flavobacterium columnare gain traction in Vietnamese pangasius hatcheries. |
| REACH-Compliant Formulation Reformulation | ECHA extended aquatic toxicity testing redirects R&D toward rapidly hydrolyzing parasiticide compounds. |
| Recirculating Aquaculture System Compatibility Certification | Maine and Danish indoor salmon facilities demand closed-loop therapeutics with zero effluent discharge profiles. |
Study Parameters
Desk research of EMA regulatory filings, FDA aquaculture drug approval databases, and EU Green Deal implementation reports preceded structured interviews with vaccine platform development directors, aquatic medicine formulation scientists, Norwegian salmon farm procurement managers, and Vietnamese pangasius cooperative health service coordinators. Secondary validation drew from trade customs data for API import flows, cold-chain logistics operator disclosures, and hatchery operator survey aggregates. Bottom-up therapeutic demand modeling triangulated against top-down aquaculture production volume projections across species categories.
Variance decomposition across product type, application, formulation, and fish species dimensions anchored the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling against regulatory approval timeline compressions. Industry-specific forecast inputs included infectious pancreatic necrosis outbreak frequency patterns and REACH chemical substance evaluation acceleration scenarios.
Material uncertainties — EMA residue threshold revisions, Chinese API export quota disruptions, and RNA vaccine cold-chain infrastructure buildout rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory pathway stability and species-specific therapeutic adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Smart Aquaculture Systems Market
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Norway Aquaculture Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
South Korea Aquaculture Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
North America Shrimp Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
Sandfish Market