
 Oilseed Processing Market | 2026-2036
Oilseed Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Oilseed Processing Market Analysis
The oilseed processing industry is pivoting toward divergent quality tiers as premium cold-pressed and identity-preserved oils command widening margins over commodity bulk shipments. Cargill, Incorporated leverages its global origination network to secure non-GMO soybean streams for European food manufacturers. Wilmar International Limited anchors its position through integrated palm oil refining complexes in Southeast Asia. Bunge Limited competes by dominating South American crush capacity and export logistics.
Oilseed processing encompasses the mechanical and chemical extraction of oils from soybeans, rapeseed, sunflower seeds, and palm fruits, typically yielding crude oil with 0.5-3% residual moisture and free fatty acid levels below 2% before refining. Solvent extraction using hexane achieves oil recovery rates exceeding 98%, while mechanical pressing preserves phospholipid content for food-grade lecithin production. Soybean oil leads volume throughput due to its dominance in food industry frying and hydrogenated shortening applications. Biofuel production represents the fastest-expanding end user segment as renewable diesel facilities absorb distiller-grade soybean and canola oils. Mechanical pressing technology occupies a profitable niche serving nutraceuticals and cold-pressed culinary markets with premium positioning.
The EPA's Renewable Fuel Standard and the EU Green Deal's deforestation regulation jointly reshape sourcing compliance requirements for oilseed processors serving transatlantic markets. FDA food safety modernization rules and EFSA novel food assessments further constrain ingredient approval pathways for emerging oil variants. Stakeholders must monitor evolving biodiesel blending mandates and sustainability certification schemes to align crush capacity investments with policy-driven demand shifts.
Market Dynamics
Biodiesel blending mandates in Brazil and the EU are redirecting crush capacity toward fuel-grade oil streams, compressing food-grade supply availability and widening the premium between identity-preserved and commodity grades.
Growth Catalysts
- EU Green Deal Deforestation Regulation:Processors securing certified deforestation-free palm and soybean streams gain preferential access to European food and biofuel buyers, accelerating investment in traceability infrastructure.
- Renewable Diesel Facility Construction:Distiller-grade soybean and canola oil offtake from North American renewable diesel plants is absorbing surplus crush output and stabilizing processor margins through long-term supply agreements.
- Brazilian Biodiesel Mandates:Domestic blending requirements rising toward B15 are anchoring South American crush expansion, with surplus capacity targeting Asian export markets.
Market Restraints
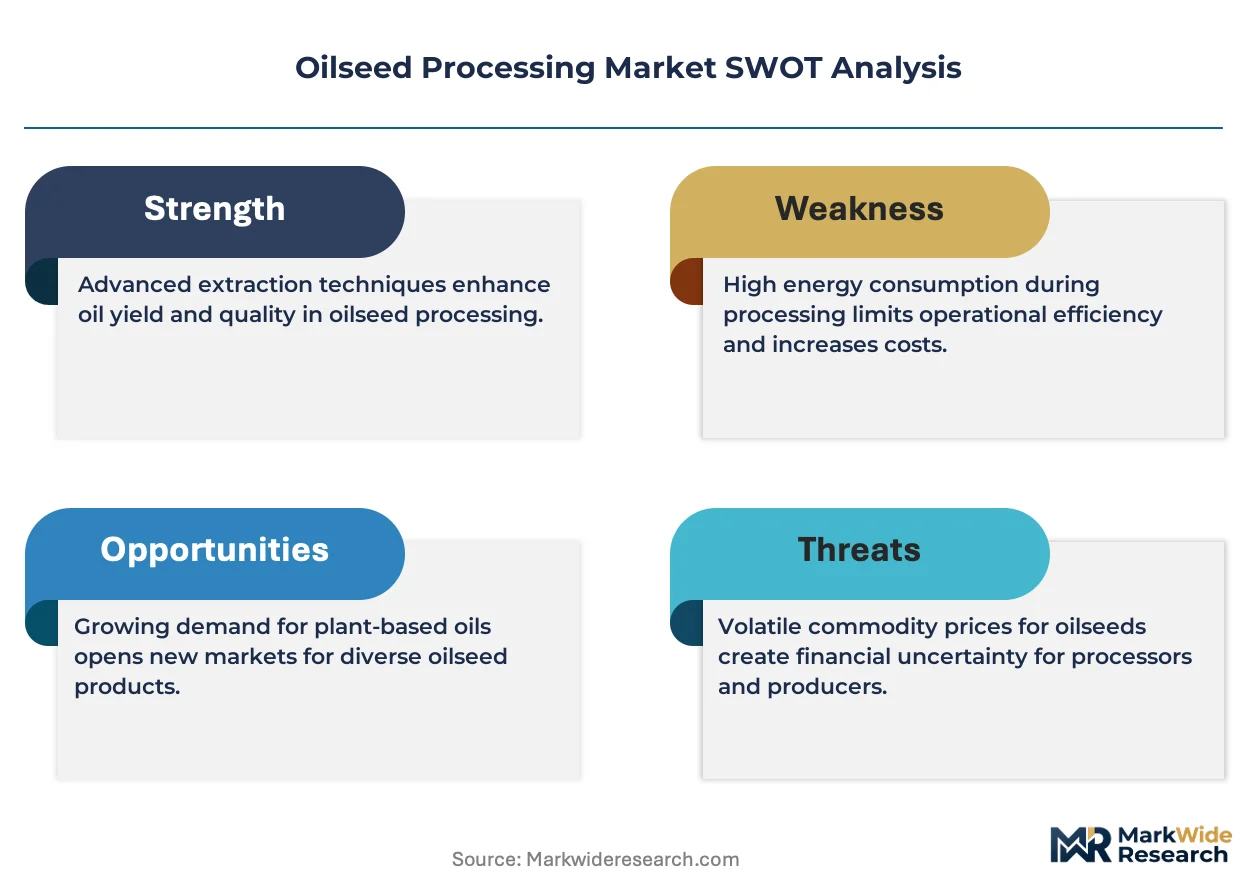
- Hexane Price Volatility:Solvent extraction economics fluctuate with petrochemical feedstock costs, squeezing margins for commodity processors lacking integrated chemical production.
- Southeast Asian Palm Concentration:Indonesian and Malaysian production dominance creates single-origin risk for European refiners facing EUDR compliance deadlines.
- Mechanical Pressing Yield Ceiling:Cold-press extraction caps at 90-92% oil recovery versus 98%+ for solvent methods, limiting scale economics for premium positioning.
Strategic Opportunities
- Indian Edible Oil Deficit:Domestic crush capacity expansion targets palm oil import substitution, with processors leveraging PLI scheme incentives for integrated refining investments.
- Phospholipid Isolation Technology:Advanced membrane filtration converging with enzymatic degumming is enabling food-grade lecithin extraction as a standalone profit center.
- Direct-to-Restaurant Distribution:Cold-pressed oil producers are bypassing traditional wholesale channels through e-commerce platforms targeting specialty culinary buyers.
Industry Challenges
- EFSA Novel Food Pathways:Emerging oil variants from novel oilseeds face 18-24 month safety assessment timelines, delaying product commercialization.
- Legacy ERP Integration:Traceability systems for deforestation compliance must interface with decades-old crush facility control architectures, creating data architecture friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilseed Processing Market |
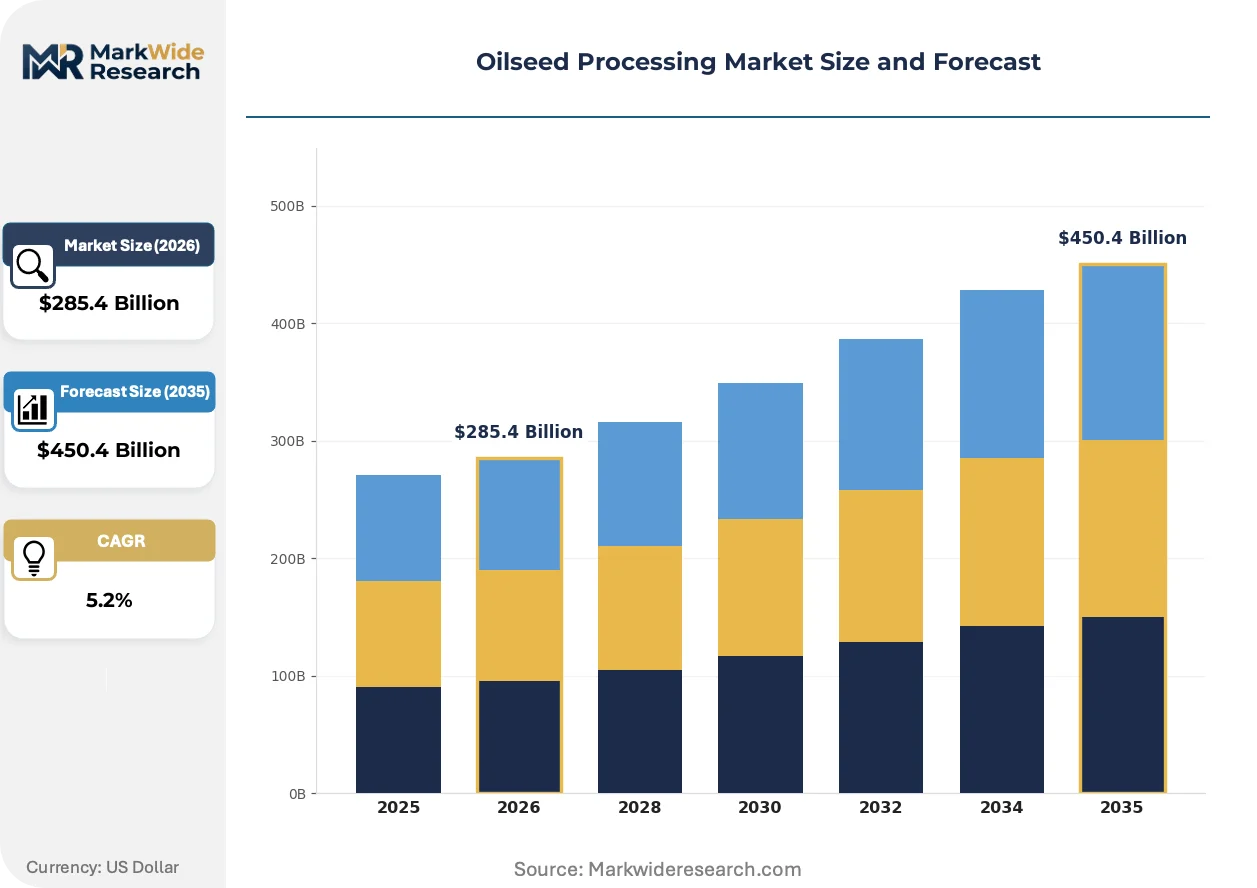
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $450.4 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybean Oil, Canola Oil, Sunflower Oil, Palm Oil Technology: Solvent Extraction, Mechanical Pressing, Degumming, Refining End User: Food Industry, Biofuel Production, Animal Feed, Personal Care Application: Cooking, Industrial Use, Nutraceuticals, Food Ingredients |
| Companies Covered | Louis Dreyfus Company, COFCO International Limited, Cargill, Incorporated, Viterra Inc., Olam International Limited, Archer Daniels Midland Company, Wilmar International Limited, Richardson International Limited, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilseed Processing Market Emerging Trajectories
Processing technology is bifurcating between high-throughput solvent systems for fuel markets and precision mechanical methods capturing food and nutraceutical premiums.
Enzymatic interesterification is absorbing capital investment from hydrogenation retrofits as food manufacturers eliminate trans-fat labeling liabilities. Bakery and confectionery buyers in North America and Western Europe are specifying enzymatically modified oils for shortening applications. This technology is absorbing market share from partial hydrogenation while preserving functional properties without trans-fat generation.
The EPA's Renewable Fuel Standard expansion to renewable diesel pathways is restructuring soybean oil demand qualification. Fuel producers must now document lifecycle greenhouse gas reductions through certified sourcing. Crush facilities with carbon capture integration or renewable energy procurement are capturing preferential offtake terms from compliance buyers.
Clean-label procurement is compressing switching cycles for identity-preserved oils as food brands consolidate supplier bases to reduce audit burden. Restaurant chains and packaged food manufacturers are demanding batch-level traceability from crush origin through refining. This pattern is most visible in European and North American markets where EUDR and FDA Food Safety Modernization Act requirements overlap.
Oilseed Processing Market Segmentation
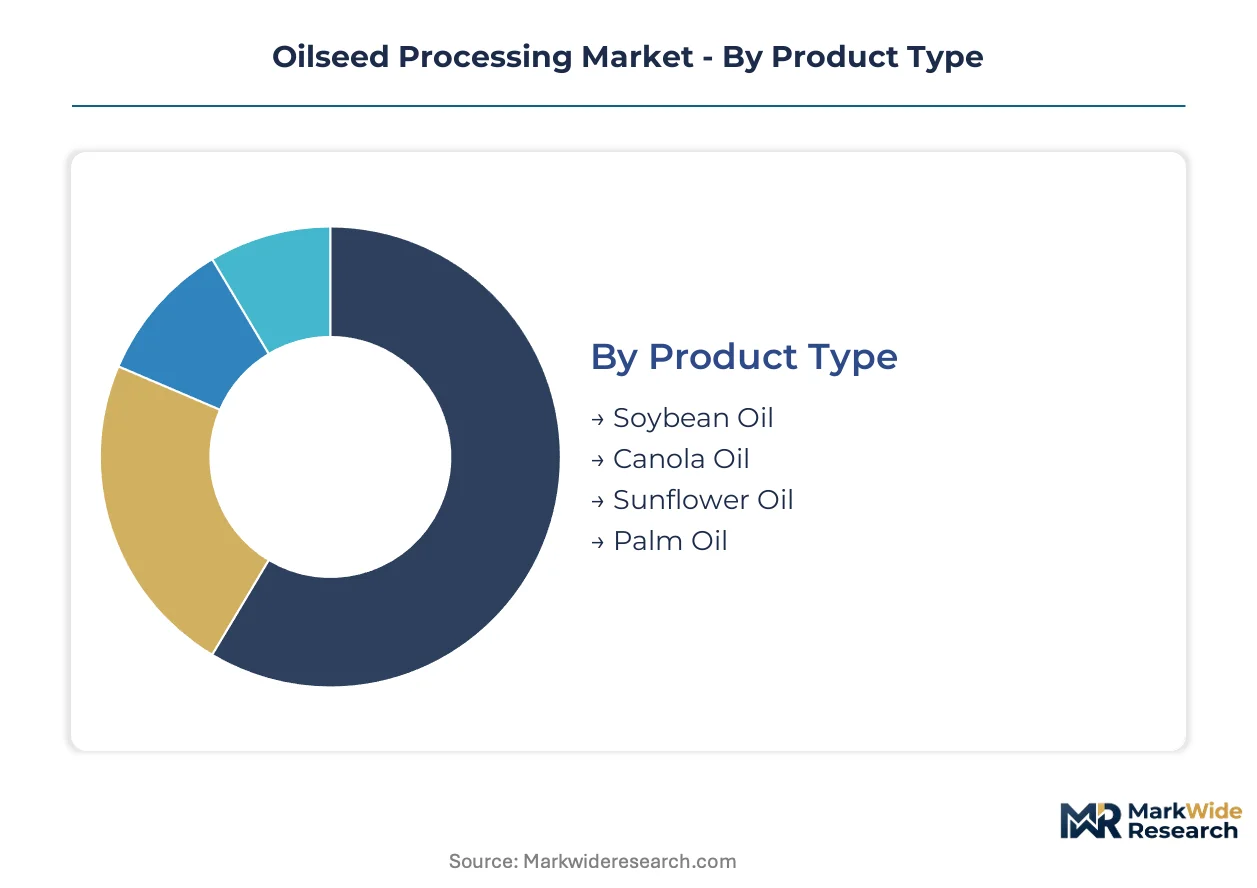
Oilseed processing segmentation reveals how crush capacity allocates across diverging quality tiers. Supply chain configuration determines which segments capture premium margins versus commodity economics.
Product Type:
Crush capacity concentrates where oil recovery rates and end-use premiums align most favorably.
- Soybean Oil:Dominates throughput volume with 18-20% oil content in beans and established hydrogenation infrastructure for shortening applications. North American renewable diesel facilities absorb distiller-grade streams under EPA RFS compliance pathways, anchoring crush expansion.
- Palm Oil:Delivers the highest oil yield per hectare at 4-5 tonnes annually, but EUDR traceability requirements are fragmenting supply chains into certified and uncertified tiers. Indonesian and Malaysian mills face diverging market access based on deforestation documentation.
- Canola Oil:Low erucic acid specification suits food-grade frying and renewable diesel feedstock with favorable carbon intensity scores.
- Sunflower Oil:High oleic variants command identity-preserved premiums in European clean-label formulations.
Today's leader: Soybean Oil. Tomorrow's challenger: Palm Oil.
Technology:
Capital deployment splits between fuel-market throughput and food-grade precision extraction.
- Solvent Extraction:Hexane-based systems achieve 98%+ oil recovery, dominating biofuel feedstock supply where volume economics override purity premiums. Margins compress when petrochemical feedstock costs spike.
- Mechanical Pressing:Cold-press methods cap at 90-92% recovery but preserve phospholipids for lecithin and nutraceutical markets. European and North American specialty producers bypass wholesale channels through direct e-commerce distribution.
- Degumming:Enzymatic variants enable standalone lecithin profit centers through membrane filtration advances.
- Refining:Neutralization and bleaching stages determine FFA specifications for food versus fuel qualification.
Solvent Extraction commands current capacity investment. Mechanical Pressing captures expanding premium positioning.
End User:
Demand fragmentation intensifies as fuel mandates absorb volumes once reserved for food applications.
- Food Industry:Frying, shortening, and salad oil applications specify 0.5-3% moisture and sub-2% FFA before refining. Clean-label procurement is compressing supplier consolidation cycles.
- Biofuel Production:Renewable diesel and biodiesel blending mandates in Brazil and the EU redirect crush capacity toward fuel-grade streams. This segment climbs fastest as RFS and LCFS mechanisms mature.
- Animal Feed:Soybean meal from solvent extraction supplies protein concentrate for livestock operations.
- Personal Care:Cosmetic-grade oils require supercritical CO2 extraction or cold-press certification.
Food Industry retains volume dominance. Biofuel Production gains share fastest through policy-driven offtake.
Application:
End-use specifications determine whether crude oil qualifies for food, fuel, or pharmaceutical pathways.
- Cooking:Refined, bleached, deodorized oils for retail and foodservice channels. High-oleic variants reduce polymerization in extended frying operations.
- Industrial Use:Biodiesel, renewable diesel, and oleochemical feedstocks absorb lower-grade streams with simplified refining requirements.
- Nutraceuticals:Cold-pressed and organic-certified oils for omega-3 and vitamin E extraction command 3-5x commodity premiums.
- Food Ingredients:Lecithin, monoglycerides, and emulsifier derivatives from degumming byproducts.
Cooking applications anchor baseline demand. Nutraceuticals deliver steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized agricultural engineers and chemical process operators concentrate in Brazil, the United States, and Germany, anchoring regional crush capacity expansion. These talent pools support diverging technology investments across solvent extraction corridors and cold-press specialty clusters.
Brazil
Biodiesel blending mandates advancing toward B15 absorb expanding soybean crush capacity in Mato Grosso and Paraná. ANVISA food safety protocols and MAPA agricultural inspection requirements govern export certification for European and Asian buyers. The Port of Santos corridor anchors South American export logistics, with integrated crush-to-ship terminals reducing inland freight exposure.
United States
Renewable diesel facility construction across Iowa, Illinois, and Indiana redirects distiller-grade soybean oil offtake under EPA RFS compliance pathways. FDA Food Safety Modernization Act traceability rules compress supplier consolidation cycles for identity-preserved streams. The Mississippi River crush corridor from Memphis to St. Louis concentrates solvent extraction capacity serving both domestic food manufacturers and Gulf Coast biofuel terminals.
Germany
Rapeseed oil demand from food manufacturers and biodiesel blenders splits crush capacity between food-grade and fuel-grade specifications. EUDR deforestation-free supply chain requirements redirect palm and soybean sourcing toward certified streams with batch-level traceability. The Hamburg-Rotterdam- Antwerp refining cluster processes imported crude oils for Central European distribution, with enzymatic interesterification investments eliminating trans-fat liabilities for bakery buyers.
China
Soybean import dependence drives crush capacity concentration in coastal provinces facing Yangtze River Delta food manufacturers. SAMR food safety labeling requirements and GB standards for edible oil quality constrain ingredient approval pathways. Shandong Province hosts the densest solvent extraction complex, with integrated refining serving both domestic retail brands and Southeast Asian export markets.
India
Palm oil import substitution targets expand domestic crush capacity in Gujarat and Maharashtra under PLI scheme incentives for integrated refining investments. FSSAI food safety standards and DGFT import tariff structures shape competitive positioning between domestic soybean processing and imported palm refining. The Kandla-Mundra port corridor anchors edible oil import logistics, with backward integration into oil palm cultivation emerging in Andhra Pradesh and Telangana.
Oilseed Processing Market Vendor Landscape
Capital-heavy producers compete with asset-light traders across diverging margin structures in the oilseed processing sector. Integrated crush-to-refine operators capture fuel-market premiums through long-term renewable diesel offtake agreements, while merchant processors rely on spot market exposure. Three archetypes dominate: global origination networks with identity-preserved certification capabilities, regional crush specialists with port-adjacent logistics, and integrated palm oil refiners with Southeast Asian plantation access. Competitive intensity centers on M&A consolidation of South American crush assets and strategic partnerships securing deforestation-free supply chain documentation.
Within the global origination tier, Cargill, Incorporated and Bunge Limited exemplify integrated networks spanning farm-gate procurement through export terminal control. Among Asia-Pacific-based operators, Wilmar International Limited occupies a position anchoring palm oil refining complexes with plantation backward integration. These three entities represent divergent geographic specializations—North American soybean dominance, South American crush logistics, and Southeast Asian palm processing—each capturing policy-driven demand shifts through compliance infrastructure investments rather than commodity scale alone.
| Leading Market Players |
|---|
| Louis Dreyfus Company |
| COFCO International Limited |
| Cargill, Incorporated |
| Viterra Inc. |
| Olam International Limited |
| Archer Daniels Midland Company |
| Wilmar International Limited |
| Richardson International Limited |
| Bunge Limited |
| Others |
Supply Flow & Price Mechanics
Hexane feedstock costs cascade from petrochemical indices through solvent extraction margins, compressing commodity processor economics while cold-press operators capture widening premiums through direct-to-restaurant channels bypassing wholesale markups.
Pricing Analysis
Contract-based long-term offtake dominates biofuel-grade streams, with renewable diesel facilities locking in distiller-grade soybean and canola oil through EPA RFS-compliant supply agreements. Price differentiation hinges on certification tier—EUDR deforestation-free documentation commands substantial premiums over uncertified commodity grades—and volume scale, with identity-preserved batches carrying higher per-unit costs. Cost compression in commodity solvent extraction is intensifying because hexane price volatility tracks naphtha markets. Food manufacturers with clean-label mandates show least price sensitivity, while biodiesel blenders exposed to RIN price swings exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian and Malaysian palm oil concentration, where EUDR compliance deadlines fragment market access based on deforestation documentation capabilities. Geographic supply concentration centers on Brazil, the United States, and Indonesia, with crush capacity expanding in Mato Grosso and Iowa to serve diverging food and fuel demand. Raw material dependencies rest on soybean, palm fruit, and rapeseed feedstocks. Tariff exposure from EU-Indonesia trade disputes and US-China agricultural levies threatens margin stability. Distribution runs through port-adjacent crush-to-ship terminals at Santos, the Mississippi River corridor, and the Kandla-Mundra complex.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oilseed processing has entered a late-cycle quality phase where premium identity-preserved and cold-pressed specifications displace commodity volumes as food brands consolidate supplier bases to reduce audit burden.
For Market Incumbents: Deepen backward integration into certified deforestation-free plantation sourcing to secure EUDR-compliant streams before compliance deadlines harden market access. Expand crush capacity in Paraná and Mato Grosso to anchor Brazilian biodiesel mandate growth while capturing Asian export demand. Invest in enzymatic interesterification retrofits to eliminate trans-fat labeling liabilities for North American and European bakery buyers. For New Entrants and Emerging Players: Launch via direct e-commerce distribution targeting specialty culinary buyers in European and North American urban markets, bypassing legacy wholesale channels dominated by integrated origination networks. Target Indian domestic crush expansion under PLI scheme incentives, where palm oil import substitution creates white-space for integrated refining investments. Penetrate through phospholipid isolation technology partnerships with nutraceutical formulators seeking food-grade lecithin supply security. For Investors and Strategic Acquirers: Consolidation pressure builds where South American crush assets lack EUDR traceability infrastructure and face stranded capacity risk. Long-term viability favors operators with dual food-fuel qualification capabilities and carbon capture integration securing preferential renewable diesel offtake terms. Target acquisition archetype: mid-scale Brazilian or US crush facilities with port logistics and retrofit-ready solvent extraction infrastructure. Signal to monitor: EPA RFS pathway expansion announcements and EU Green Deal enforcement timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Plantations | EUDR compliance documentation secures preferential European food and biofuel buyer access. |
| Enzymatic Interesterification Retrofit | Eliminates trans-fat liabilities for bakery and confectionery manufacturers in FDA-regulated markets. |
| Carbon Capture Integration at Crush Facilities | Lifecycle GHG reduction documentation captures EPA RFS renewable diesel offtake premiums. |
| Phospholipid Isolation Technology Deployment | Membrane filtration advances enable standalone lecithin profit centers for nutraceutical supply. |
| Direct-to-Restaurant E-Commerce Launch | Cold-pressed oil producers bypass wholesale channels to capture specialty culinary premiums. |
Methodological Framework
Direct dialogue with crush facility operations managers, renewable diesel procurement leads at fuel producers, EUDR compliance officers at European refiners, and specialty oil brand managers grounded qualitative findings in operational realities. Secondary validation drew from EPA RFS regulatory filings, ANVISA and MAPA export certification records, EU Green Deal implementation guidance, and SEC disclosures from listed agribusiness operators. Bottom-up capacity modeling triangulated against top-down demand segmentation across food, fuel, and nutraceutical end uses.
Top-down demand projections anchored analytical frameworks across the analysis window, with bottom-up crush capacity investments and technology deployment timelines cross-checked for consistency. Segmentation dimensions spanned product type, extraction technology, end-user qualification, and application specification. CAGRs derived from volume-throughput modeling against policy-mandated demand shifts, incorporating biodiesel blending mandate trajectories, renewable diesel facility construction pipelines, and clean-label procurement intensity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA RFS pathway modifications, EU-Indonesia trade dispute escalations, or hexane feedstock price spikes. Projections reflect documented assumptions regarding policy continuity and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seed Processing Innovations
North America Seed Treatment Market
Seed Processing Innovations
Soybean Seed Treatment Market
Seed Processing Innovations
India Seed and Grain Cleaning and Grading Machine Market
Seed Processing Innovations
Alfalfa Seed Extract Market
Seed Processing Innovations
Italy Seed Treatment Market
Seed Processing Innovations
Asia-Pacific Seed Treatment Market
Seed Processing Innovations
Rice Seed Treatment Market
Seed Processing Innovations
Maize Seed Treatment Market
Seed Processing Innovations
South America Seed Treatment Market
Seed Processing Innovations
United States Seed Treatment Market
Seed Processing Innovations
Sprouted Durum Wheat for Pasta Applications Market
Seed Processing Innovations
Kiwi Seed Extract Market
Seed Processing Innovations
Seed Sorting Machine Market
Seed Processing Innovations
Brazil Seed Treatment Market
Seed Processing Innovations
North America Soybean Seed Treatment Market
Seed Processing Innovations
Fenugreek Seed Extract Market