
 Fishing Net Market | 2026-2036
Fishing Net Market Size, Share, and Industry Trends Forecast 2026-2036
Fishing Net Market Analysis
Aquaculture operators is reorganizing procurement priorities toward longer-service-life netting systems. Nitto Seimo Co. Ltd. anchors Japanese domestic supply through advanced knotless braiding capabilities. Garware Technical Fibres Ltd. dominates Indian subcontinent exports with integrated rope-and-net manufacturing. Badinotti Group SPA specializes in Mediterranean purse seine systems for pelagic species.
Fishing nets are woven or knotted textile structures engineered from synthetic or natural fibers, with mesh apertures calibrated to target species dimensions and tensile strength rated to operational drag loads; they function as selective capture barriers in marine and freshwater harvesting. Gill nets and seine nets occupy the largest volume positions, though trammel nets command premium pricing in artisanal Mediterranean fleets. Monofilament polyethylene leads material substitution away from conventional nylon where UV degradation resistance governs total cost of ownership calculations.
The EU's F-Gas Regulation and REACH chemical restrictions constrain fluoropolymer coating formulations, while the US EPA and Japan's METI set divergent standards for microplastic shedding from synthetic net abrasion. Fisheries management agencies in Norway, Chile, and Thailand mandate gear traceability tagging that elevates compliance costs for smaller netters. Stakeholders must weigh capital allocation between bio-based polymer research and circular net recycling infrastructure before regulatory timelines harden.
Market Dynamics
Material substitution toward UV-stabilized polyethylene is compressing replacement cycles for commercial fleets while REACH chemical restrictions force reformulation of protective coatings across European supply chains.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled content thresholds for fishing gear sold in member states are accelerating rPET fiber adoption in net manufacturing.
- Commercial aquaculture expansion:Intensive shrimp and salmon farming operations in Vietnam and Indonesia are scaling procurement of knotless braiding systems engineered for multi-year deployment.
- Biodegradable polymer R&D:Aliphatic polyester blends developed for gill net applications are advancing toward commercial viability under Japan's METI sustainability grants.
Market Restraints
- Petrochemical feedstock volatility:Crude-linked polyethylene and nylon-6 pricing swings compress margin stability for mid-tier net weavers dependent on spot resin purchases.
- Fluoropolymer coating constraints:The EU's F-Gas Regulation and ECHA restrictions on perfluorinated compounds limit hydrophobic treatment options for high-performance seine systems.
- Artisanal fleet fragmentation:Small-scale operators across the Mediterranean and Southeast Asia lack capital for certified gear traceability systems mandated by Norwegian and Chilean fisheries agencies.
Strategic Opportunities
- Circular net recycling infrastructure:Depolymerization facilities for end-of-life nylon nets present white-space investment in port-adjacent industrial zones of Spain and Portugal.
- Smart tagging convergence:Integration of RFID traceability with blockchain verification creates premium positioning for EU-regulated pelagic fleets requiring full supply chain documentation.
- Indonesia's tuna fleet modernization:Government-backed harbor infrastructure upgrades in Bitung and Benoa are opening procurement channels for purse seine systems with integrated sonar-compatible mesh geometries.
Industry Challenges
- Master braider skill scarcity:Traditional knotless net construction expertise concentrates among aging workforces in Japan and Italy with limited vocational training pipeline replacement.
- Multi-jurisdiction certification timelines:Simultaneous compliance with US EPA microplastic shedding protocols and Japan's METI synthetic fiber standards extends product launch cycles by 8-14 months.
- Legacy fleet compatibility:New high-density polyethylene nets require winch and drum modifications on older vessels, creating retrofit cost barriers for owner-operator fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fishing Net Market |
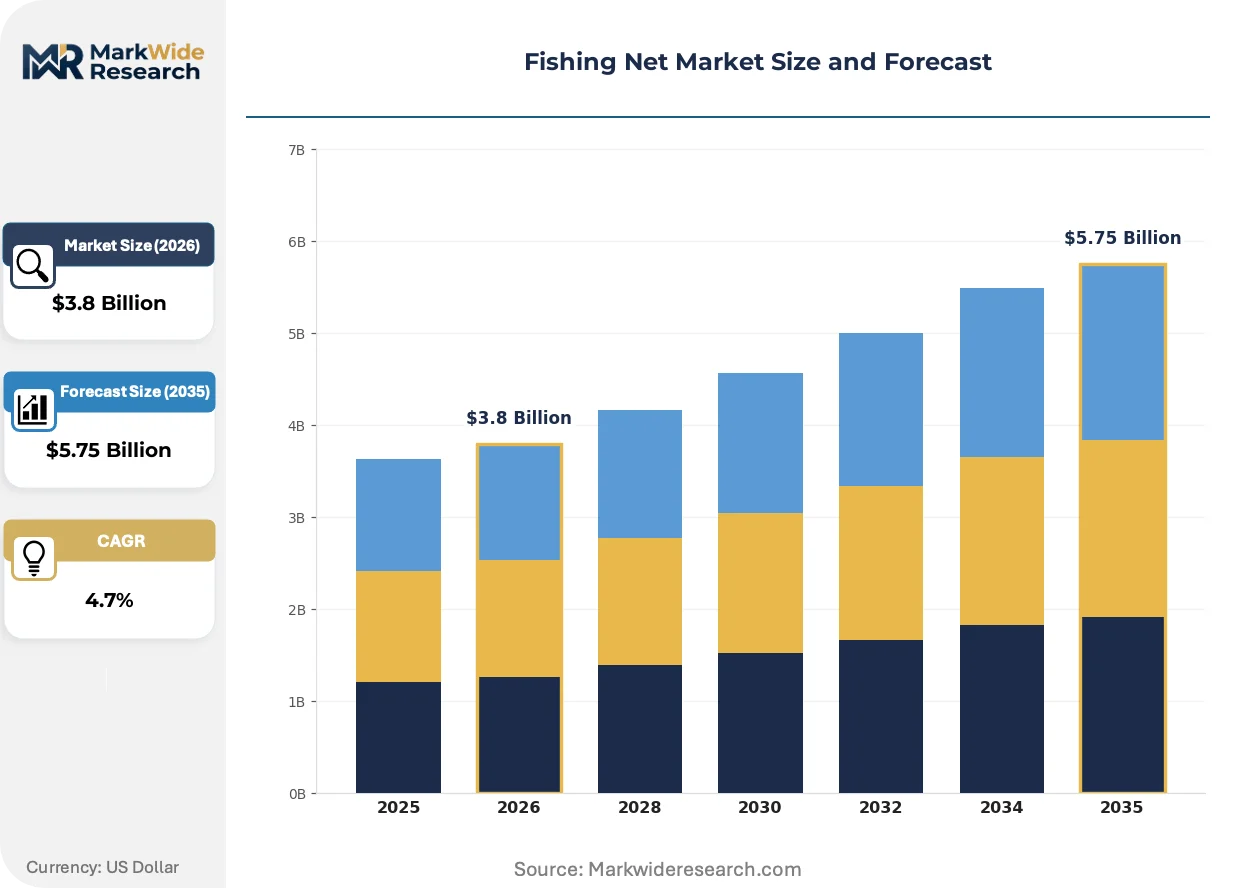
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Gill Nets, Trammel Nets, Seine Nets, Cast Nets Material: Monofilament, Multifilament, Nylon, Cotton Application: Commercial Fishing, Sport Fishing, Aquaculture, Research Mesh Size: Fine Mesh, Medium Mesh, Coarse Mesh, Extra Coarse Mesh |
| Companies Covered | Nitto Seimo Co. Ltd., Siang May Pte Ltd., Kohinoor Ropes Pvt. Ltd., Badinotti Group SPA, Memphis Net and Twine Co. Inc., Jaya Nets Sdn Bhd, Magnum Polymer, Officine Maccaferri Spa, Garware Technical Fibres Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fishing Net Market Emerging Trajectories
Active materials science breakthroughs and regulatory chemistry constraints are converging to redefine performance specifications and procurement criteria across commercial and artisanal segments simultaneously.
Monofilament high-density polyethylene engineered with hindered amine light stabilizers is displacing conventional nylon-6 in tropical gill net deployments. Vietnamese and Indonesian squid fleets are adopting these systems at replacement rates exceeding historical nylon cycles. The shift is compressing addressable market volume for legacy multifilament suppliers while elevating UV-resistance testing to primary specification status in tender evaluations.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating long-chain fluoropolymer coatings from European-sourced purse seine systems. Net finishers serving Mediterranean tuna fleets are pivoting toward silicone-based alternatives with shorter hydrophobic lifespans. This regulatory compression is fragmenting coating supply chains and forcing fleet operators into accelerated re-treatment schedules previously unnecessary under fluoropolymer regimes.
Consolidated procurement by vertically integrated aquaculture conglomerates is displacing fragmented spot purchasing through harbor-side net merchants. Charoen Pokphand and Cargill Aquaculture operations in Thailand and Vietnam now contract directly with fiber producers for specification-controlled master rolls. This channel concentration is marginalizing traditional net distributors and relocating technical specification authority from vessel captains to corporate engineering departments.
Fishing Net Market Segmentation
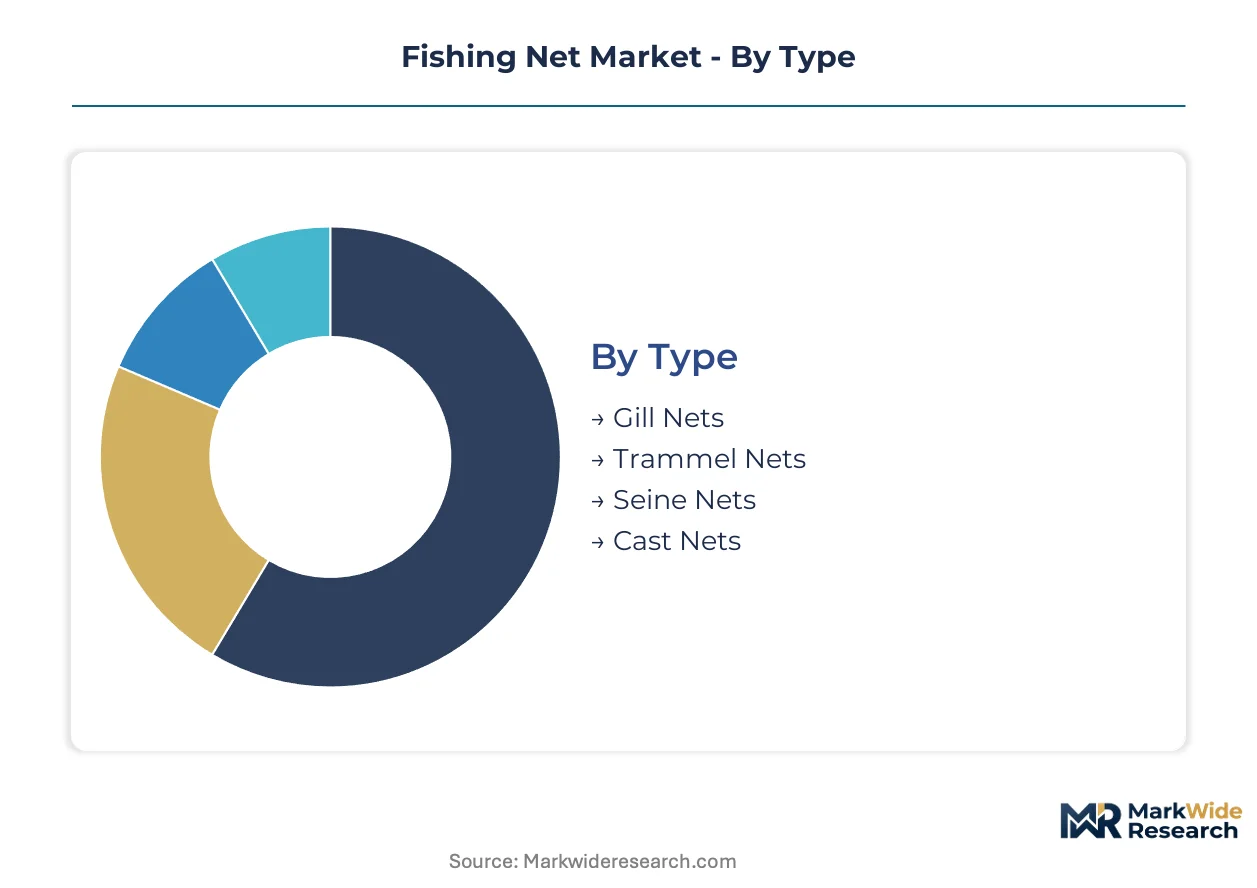
Fishing net procurement decisions hinge on mesh geometry, fiber chemistry, and deployment duration. Fleet operators balance initial capital outlay against replacement cycles and regulatory compliance costs. Material substitution pressures and aquaculture consolidation are compressing traditional category boundaries.
Type:
Gill nets and seine nets face the strongest displacement threat from knotless braiding systems in Vietnam's Mekong Delta processing clusters and Indonesia's tuna harbors.
- Gill Nets:Vertical panel structures with calibrated mesh apertures function as selective capture barriers for pelagic species. Vietnamese squid fleets are accelerating replacement with UV-stabilized polyethylene monofilament variants that outlast conventional nylon cycles in tropical deployments.
- Seine Nets:Encircling systems with weighted lead lines and float-corked head ropes surround schooling fish before purse-line closure. Indonesian government harbor upgrades in Bitung and Benoa are opening procurement channels for sonar-compatible mesh geometries in purse seine configurations.
- Trammel Nets:Triple-wall construction with slack inner panel traps species unable to pass through outer mesh walls. Mediterranean artisanal fleets command premium pricing for these systems despite REACH coating constraints.
- Cast Nets:Circular throwing nets with radial drawstrings target shallow-water schooling species. Southeast Asian small-scale operators favor these for low capital entry despite fluoropolymer treatment limitations under EU F-Gas Regulation.
Gill nets retain volume leadership; seine nets hold the steepest expansion curve.
Material:
Cost tier stratification separates specification-controlled master rolls from spot resin purchases in net manufacturing.
- Monofilament:Single-strand extrusions of high-density polyethylene engineered with hindered amine light stabilizers. Thai and Vietnamese aquaculture conglomerates now contract directly with fiber producers for multi-year deployment specifications, marginalizing traditional distributors.
- Nylon:Polyamide-6 fibers with established knot strength and abrasion resistance. Depolymerization facilities for end-of-life nylon nets present recycling infrastructure investment opportunities in Spanish and Portuguese port zones.
- Multifilament:Twisted yarn bundles offering suppleness and knot security. Addressable market volume is compressing as tropical fleets shift toward UV-resistant monofilament alternatives.
- Cotton:Natural cellulose fibers with biodegradability advantages. Limited commercial deployment persists in artisanal Mediterranean applications where synthetic shedding restrictions apply.
Monofilament captures specification authority from corporate engineering departments; nylon maintains installed base replacement demand.
Application:
Customer type concentration distinguishes vertically integrated aquaculture procurement from fragmented artisanal spot purchasing.
- Commercial Fishing:Industrial-scale harvesting operations deploying trawl, seine, and gill systems. EU Single-Use Plastics Directive recycled content thresholds are accelerating rPET fiber adoption in gear sold to member state fleets.
- Aquaculture:Intensive shrimp and salmon farming requiring knotless braiding for cage containment and predator exclusion. Charoen Pokphand and Cargill operations in Thailand and Vietnam are consolidating procurement through direct fiber producer contracts.
- Sport Fishing:Recreational angling equipment with lower durability requirements. Price sensitivity constrains material specification upgrades relative to commercial segments.
- Research:Scientific sampling gear requiring standardized mesh apertures and minimal environmental DNA contamination. Traceability tagging mandates from Norwegian and Chilean fisheries agencies elevate compliance costs.
Commercial fishing commands absolute revenue share; aquaculture is climbing the fastest.
Mesh Size:
Maturity gradients separate established coarse mesh standards from emerging fine mesh regulatory constraints.
- Coarse Mesh:Apertures exceeding 50mm targeting large pelagic species. Mediterranean purse seine systems for tuna fleets utilize these geometries with silicone-based hydrophobic coatings replacing banned fluoropolymers.
- Medium Mesh:Standardized 20-50mm openings for general commercial harvesting. Volume concentration in Indonesian and Vietnamese fleet procurement maintains category stability.
- Fine Mesh:10-20mm apertures for shrimp and small finfish capture. Bycatch reduction regulations in multiple jurisdictions are constraining deployment authorization.
- Extra Coarse Mesh:Specialized geometries for industrial tuna and shark targeting. Limited fleet penetration outside Pacific and Indian Ocean longline operations.
Coarse mesh retains volume leadership; fine mesh faces the steepest regulatory compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese net manufacturers export knotless braiding systems to Thai aquaculture conglomerates and Indonesian tuna fleets, establishing a dominant trade-flow corridor across Southeast Asian waters.
Vietnam
Mekong Delta processing clusters drive procurement of UV-stabilized polyethylene monofilament for squid fleet replacement cycles. The country's fisheries regulator mandates biodegradable trial deployments in select coastal provinces. Ho Chi Minh City anchors technical specification authority for Charoen Pokphand contract negotiations.
Indonesia
Government harbor infrastructure upgrades in Bitung and Benoa are opening procurement channels for purse seine systems with sonar-compatible mesh geometries. The national maritime affairs ministry coordinates fleet modernization grants with recycled content quotas. Surabaya-based net distributors are consolidating toward direct fiber producer relationships.
Japan
METI sustainability grants are accelerating aliphatic polyester blend development for gill net commercialization. The country's synthetic fiber standards diverge from US EPA microplastic shedding protocols, extending certification timelines. Osaka-Kobe industrial corridors retain master braider expertise concentrated among aging workforces.
Norway
Fisheries management agencies mandate gear traceability tagging that elevates compliance costs for smaller netters importing from Mediterranean suppliers. The country's aquaculture regulator enforces multi-year durability specifications for salmon farming containment systems. Bergen and Trondheim harbor zones concentrate technical service capacity for Nordic fleet operators.
Spain
Depolymerization facilities for end-of-life nylon nets present recycling infrastructure investment opportunities in Barcelona and Valencia port-adjacent industrial zones. ECHA restrictions on perfluorinated compounds are eliminating fluoropolymer coating options for purse seine finishers serving EU-registered tuna fleets. Galician net merchants face margin compression from consolidated aquaculture procurement.
Fishing Net Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technical specification authority. The vendor base stratifies between integrated fiber-to-net manufacturers and regional weaving specialists dependent on spot resin purchases. Three archetypes dominate: Japanese knotless braiding specialists, Indian subcontinent export consolidators, and Mediterranean purse seine finishers. M&A activity concentrates on recycling infrastructure assets, while strategic partnerships target aquaculture conglomerate direct contracting channels.
Among Japanese specialists, Nitto Seimo Co. Ltd. exemplifies the master braider archetype with domestic supply anchoring. Garware Technical Fibres Ltd. represents Indian integrated manufacturing across rope-and-net systems. Badinotti Group SPA occupies a position within Mediterranean pelagic specialization.
| Leading Market Players |
|---|
| Nitto Seimo Co. Ltd. |
| Siang May Pte Ltd. |
| Kohinoor Ropes Pvt. Ltd. |
| Badinotti Group SPA |
| Memphis Net and Twine Co. Inc. |
| Jaya Nets Sdn Bhd |
| Magnum Polymer |
| Officine Maccaferri Spa |
| Garware Technical Fibres Ltd. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day master roll lead times from Vietnamese fiber producers compress pricing power for European net finishers while expanding margin capture for integrated Asian manufacturers. This inventory-to-delivery lag concentrates specification authority with aquaculture conglomerates who contract directly with upstream suppliers, bypassing traditional harbor-side distributors.
Pricing Analysis
UV-stabilized polyethylene monofilament commands a 15-20% premium over conventional nylon-6 multifilament in tender evaluations, while next-generation aliphatic polyester blends remain pre-commercial with undefined pricing. Three-tier pricing structure across premium, standard, and economy levels separates specification-controlled master rolls from spot resin purchases and artisanal-grade cotton netting. Pricing pressure stems from petrochemical feedstock volatility compressing margin stability for mid-tier weavers dependent on spot polyethylene purchases. Commercial aquaculture operators exhibit lowest price sensitivity due to multi-year durability calculations, while Mediterranean artisanal fleets face acute cost constraints under traceability compliance mandates.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Spanish and Italian net finishers sourcing Vietnamese and Indonesian fiber. Manufacturing concentration centers on Vietnam, Indonesia, and Japan for knotless braiding systems, with India anchoring rope-and-net integrated production. Raw material dependencies include high-density polyethylene resin, hindered amine light stabilizers, and silicone-based hydrophobic coatings replacing banned fluoropolymers. Single-source vulnerability concentrates in Japanese master braider expertise with limited vocational pipeline replacement. Distribution runs through direct fiber producer contracts with aquaculture conglomerates, marginalizing traditional harbor-side merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fishing net market is recovering from a cyclical trough driven by aquaculture fleet replacement cycles deferred during prior resin price spikes. Procurement normalization among Vietnamese and Indonesian operators signals durable demand restoration.
For Market Incumbents: Shield installed base relationships by accelerating backward integration into recycled PET fiber production ahead of EU Single-Use Plastics Directive enforcement. Secure master braider talent through apprenticeship partnerships with Osaka-Kobe technical institutes before workforce attrition accelerates. Prioritize certification investment for dual US EPA and Japan METI compliance to compress product launch timelines.
For New Entrants and Emerging Players: Circular net recycling infrastructure gaps in Spanish and Portuguese port zones present service-layer entry points where incumbents under-serve. Target depolymerization facility partnerships with EU-funded harbor industrial zones as the most penetrable geography. Pursue go-to-market angles through aquaculture conglomerate sustainability procurement officers rather than traditional vessel captain channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core net manufacturing divisions facing REACH compliance cost escalation. Long-term viability favors recycling infrastructure assets with port-adjacent real estate and established offtake relationships with aquaculture operators. Watch biodegradable polymer commercialization timelines under Japan METI grants as inflection signal for material substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Infrastructure Acquisition | Depolymerization facilities in Barcelona and Valencia port zones capture EU regulatory tailwinds. |
| Backward Integration into rPET Fiber | In-house recycled polyethylene terephthalate production secures compliance with EU Single-Use Plastics Directive thresholds. |
| Master Braider Apprenticeship Programs | Osaka-Kobe technical institute partnerships address aging workforce scarcity in knotless construction expertise. |
| Dual-Jurisdiction Certification Investment | Simultaneous US EPA and Japan METI approval compresses product launch cycles by 8-14 months. |
| Direct Aquaculture Contracting | Charoen Pokphand and Cargill procurement channels displace fragmented harbor-side distribution. |
Methodological Framework
The analysis maps gill net, seine net, trammel net, and cast net sub-sectors, each validated through fleet procurement managers, aquaculture engineering directors, fiber producer technical sales leads, and harbor-side net merchants. Primary interviews combined with secondary validation from customs trade databases, EU ECHA regulatory filings, and Japan METI sustainability grant disclosures. Bottom-up fiber consumption estimates and top-down fleet replacement cycle analysis triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation across net type, material chemistry, application, and mesh geometry dimensions. CAGRs derive from weighted fleet replacement schedules and aquaculture expansion trajectories. Industry-specific forecast inputs include biodegradable polymer commercialization timelines and EU recycled content mandate enforcement phasing.
Forecasts assume regulatory continuity in EU REACH and F-Gas regimes alongside Japan METI synthetic fiber standards; material policy shifts would require re-modeling. Petrochemical price volatility, master braider workforce attrition, and aquaculture disease outbreaks constitute specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Global Infrared Heater for Agriculture Market
Agricultural Equipment
Wheelbarrow Market
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Aquarium Pumps and Filters Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Irrigation Syringe Market
Agricultural Equipment
Agriculture Seeder Market