
 Vegetable Sorting Machines Market | 2026-2036
Vegetable Sorting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Sorting Machines Market Insights
Food-grade optical resolution is bifurcating the competitive landscape into premium precision tiers and cost-optimized utility tiers. TOMRA Systems ASA leverages deep learning algorithms to sustain technology leadership in hyperspectral detection for defect removal. Bühler Group anchors its position through backward integration into camera module manufacturing, controlling critical sensor supply chains. Key Technology competes on throughput velocity, specializing in high-capacity lane configurations for industrial potato processors.
Vegetable sorting machines are automated systems that employ camera arrays, spectral sensors, and pneumatic ejection mechanisms to classify produce by size, color, defect profile, and internal composition at processing speeds exceeding ten tons per hour. Their primary commercial purpose is to reduce manual labor dependency while ensuring batch uniformity for retail specification compliance and export certification. Optical sorter deployments now lead capital expenditure among food processing companies, as vision system technology captures margin pools previously lost to downstream quality claims. Infrared technology is gaining fastest traction among exporters handling stone fruit and avocados, where internal bruise detection determines premium market access.
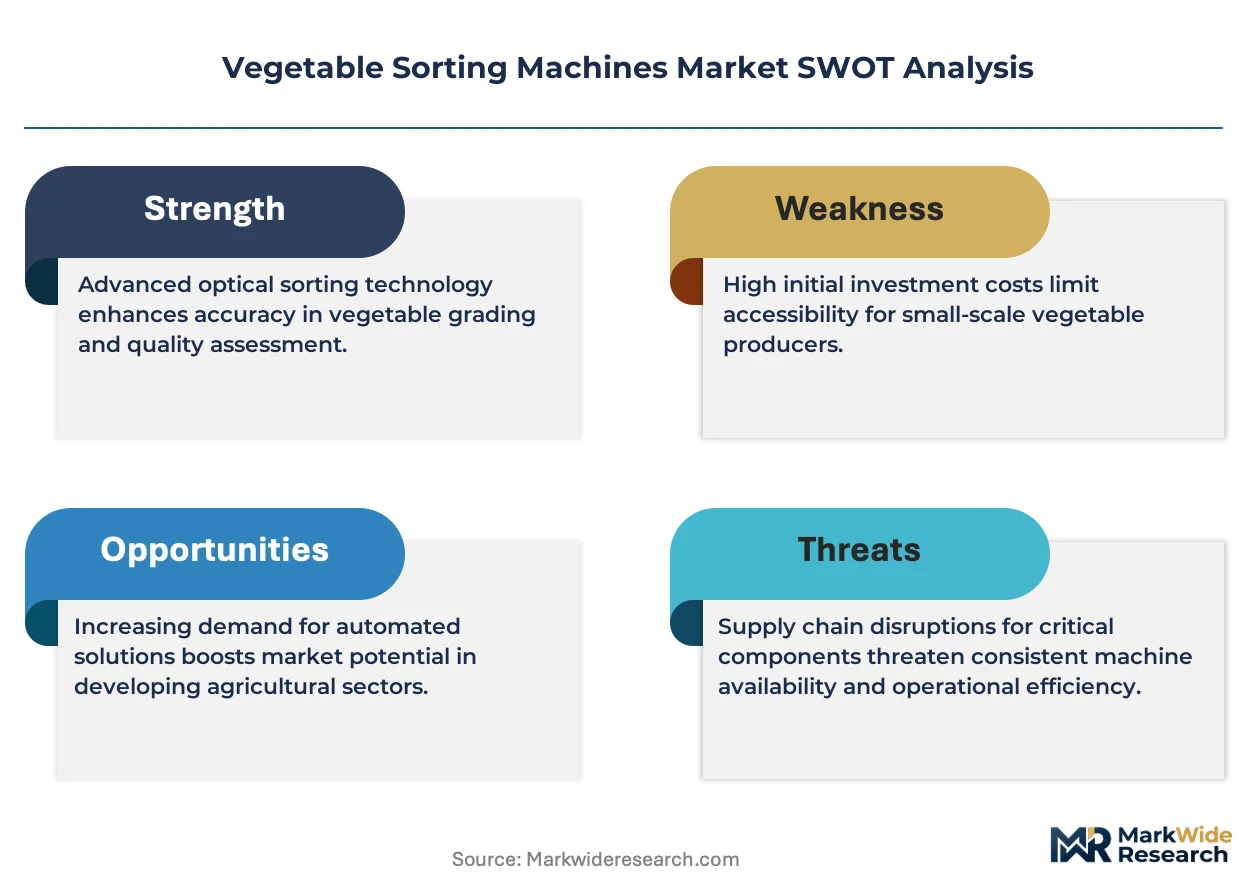
FDA enforcement of the Food Safety Modernization Act intensifies traceability requirements, compelling processors to adopt machine-graded lot documentation. EFSA guidelines on acrylamide mitigation in potato products indirectly elevate demand for defect-sensitive optical sorting that removes high-sugar tubers before frying. EU machinery safety directives under CE marking mandate operator-guarding specifications that inflate engineering costs for smaller manufacturers. Stakeholders must weigh regulatory compliance burdens against the operational savings from reduced manual inspection headcount when evaluating automation timelines.
Market Dynamics
Hyperspectral imaging hardware is compressing detection thresholds for internal defects, forcing processors to retool lines before depreciation cycles complete. Dutch potato cooperatives now specify sub-millimeter bruise detection as a contract condition for premium export slots.
Growth Catalysts
- FDA Food Safety Modernization Act:Traceability mandates compel processors to deploy machine-graded lot documentation systems. Automated sorting generates immutable quality records that satisfy enforcement protocols.
- Stone fruit exporters:Infrared bruise detection technology unlocks premium retail access for avocado and mango shipments. Internal quality grading commands price premiums in Japanese and South Korean import channels.
- CE marking machinery directives:Operator-guarding specifications under EU safety frameworks accelerate replacement of unguarded legacy equipment. Compliance deadlines concentrate purchasing among certified European manufacturers.
Market Restraints
- Camera sensor supply concentration:Sony and ON Semiconductor control CMOS supply for high-speed optical arrays. Shortage events cascade into six-month delivery delays for sorter OEMs.
- Technical limitation in wet produce:Water film interference degrades spectral accuracy for washed root vegetables. Tuber processors must pre-dry batches, adding energy and time costs.
- Substitution threat from manual labor:Temporary harvest labor pools in Eastern Europe and Central Asia retain cost advantage for low-value commodity grades. Seasonal wage arbitrage delays automation adoption for bulk processing.
Strategic Opportunities
- Underpenetrated onion segment:India's FSSAI food safety code expansion creates first-mover advantage for defect-sorting deployment. Domestic processors currently rely on hand-grading for export certification.
- Technology convergence:Integration of robotic handling arms with optical sorting lines enables end-to-end automated packing. Combined systems reduce floor space requirements by eliminating transfer conveyors.
- EU Green Deal agricultural funding:Sustainability-linked capital subsidies cover sorting equipment that reduces food waste. Member states allocate recovery funds toward precision grading infrastructure.
Industry Challenges
- Machine vision engineering talent scarcity:Spectral algorithm development requires hybrid expertise in optics and agricultural produce pathology. Universities produce fewer cross-trained graduates than OEM hiring demand.
- Legacy MES integration complexity:Proprietary communication protocols in older plant management systems obstruct real-time quality data flow. Middleware development adds unbudgeted implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Sorting Machines Market |
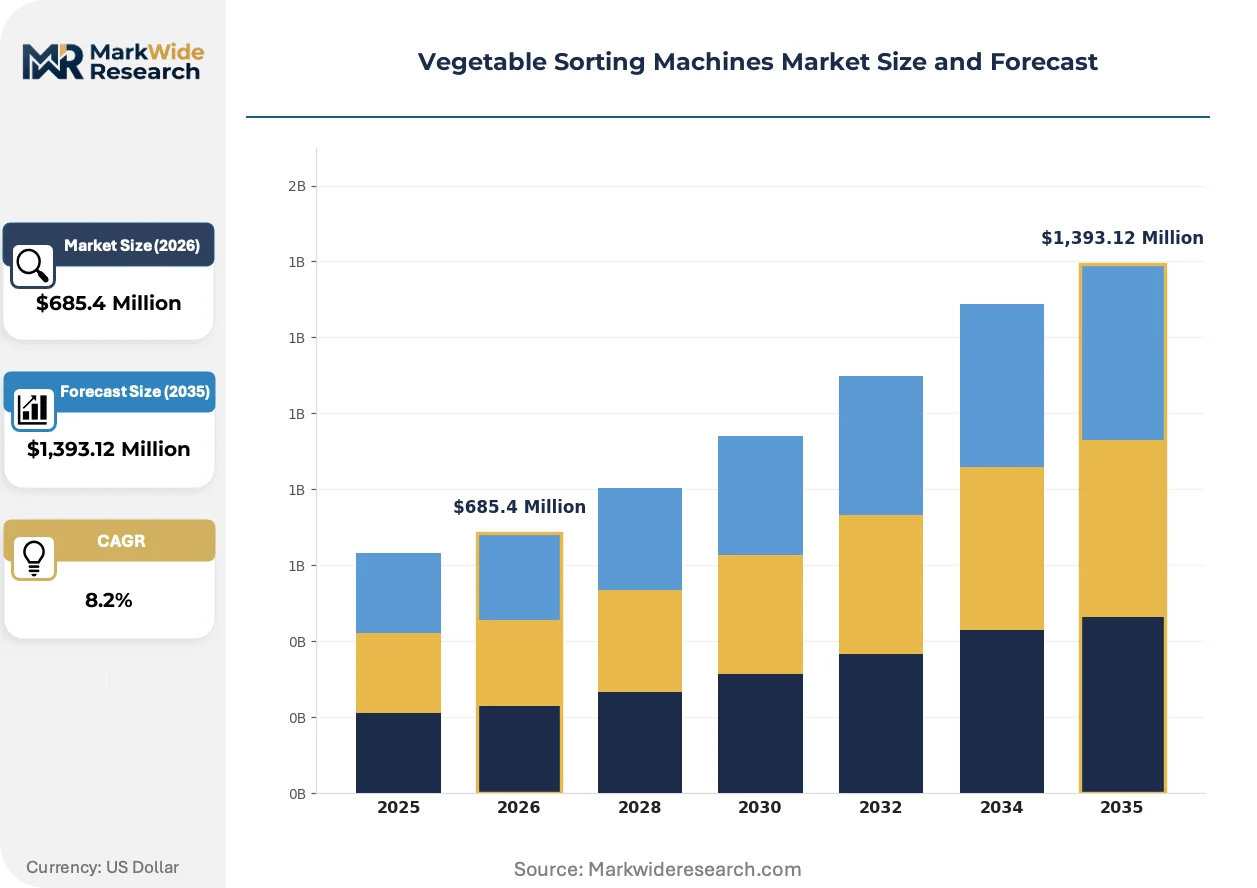
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Sorter, Optical Sorter, Grading Machine, Weight Sorter End User: Food Processing Companies, Agricultural Cooperatives, Retail Chains, Exporters Technology: Vision System, Infrared Technology, Mechanical Sorting, Pneumatic Handling Functionality: Sorting, Grading, Packing, Quality Inspection |
| Companies Covered | TOMRA Systems ASA, Bühler Group, Key Technology, Ellips, Greefa, Satma Corporation, Aweta, Sorma Group, Raytec Vision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Sorting Machines Market Trends and Innovations
Sensor fusion architectures are collapsing the cost-performance frontier for mid-capacity processors. Multi-wavelength detection modules now penetrate market tiers previously served by monochrome camera systems.
Short-wave infrared (SWIR) detector arrays is miniaturizing defect detection for internal bruising and foreign material. Mid-scale potato starch processors in Germany and Belgium are retrofitting existing lines with compact SWIR modules rather than purchasing complete new systems. The technology is compressing the minimum viable scale for premium optical sorting below five tons per hour.
EFSA acrylamide mitigation guidelines for fried potato products mandate removal of high-sugar tubers before processing. Optical sorters with sugar-content detection capability now qualify as preventive control equipment under EU food safety frameworks. Belgian and Dutch processors face the most acute compliance timelines due to frozen fry export concentration.
Certification-driven procurement preferences are displacing price-first vendor selection among retail-aligned processors. BRC and IFS audit requirements specify documented foreign-body control measures that only automated sorting satisfies. German discount retail chains now require supplier proof of optical detection systems as a condition for contract renewal.
Vegetable Sorting Machines Market Segmentation
Equipment configurations in vegetable sorting diverge sharply by capital intensity and technical sophistication. Procurement channels vary by segment, with OEM direct sales dominating high-specification optical systems while regional distributors capture utility-grade mechanical sorters.
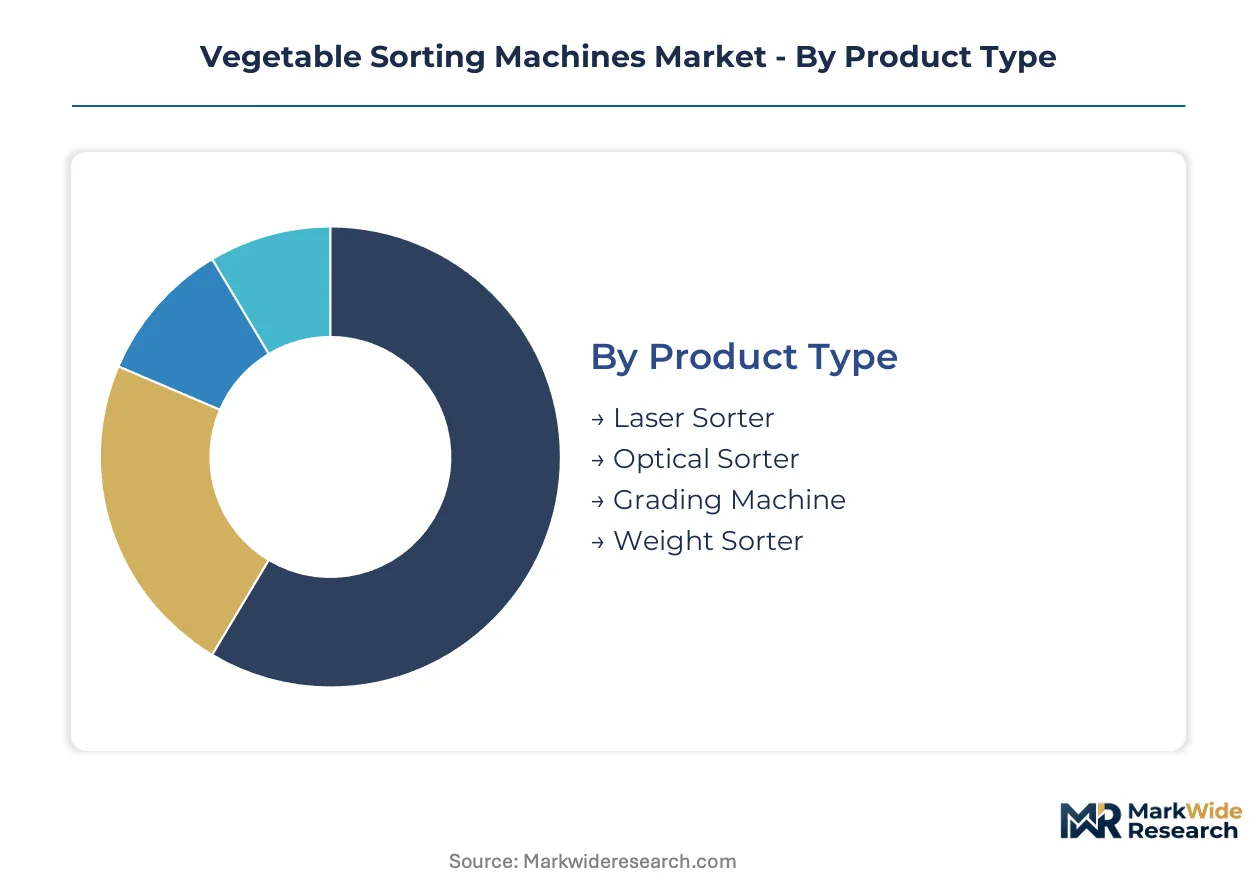
Product Type:
Channel mix splits between turnkey system integrators for premium configurations and component suppliers for retrofittable modules.
- Optical Sorter:Multi-spectral camera arrays detect surface defects and internal bruising through near-infrared penetration. Dutch potato cooperatives and Belgian frozen fry processors concentrate procurement here, driven by EFSA acrylamide mitigation mandates requiring sugar-content screening.
- Laser Sorter:Structured light projection maps three-dimensional produce geometry for volume-consistent grading. German discount retail chains specify laser-graded uniformity as a supplier contract condition, displacing manual sizing lines.
- Grading Machine:Rotary drum and weight-bridge configurations handle high-throughput commodity sorting with lower spectral resolution.
- Weight Sorter:Load-cell arrays classify by mass for pre-packaged retail portions, common in onion and carrot processing.
By volume, Weight Sorter leads. By growth pace, Optical Sorter is expanding most quickly.
End User:
Cost tier stratification separates capital-rich exporters from price-sensitive domestic processors.
- Food Processing Companies:Industrial-scale operators deploy complete sorting lines exceeding ten tons per hour capacity. FDA Food Safety Modernization Act traceability requirements compel machine-graded lot documentation, concentrating investment among US frozen vegetable packers.
- Exporters:Premium market access depends on defect-free certification for Japanese and South Korean import channels. Infrared bruise detection unlocks price premiums for avocado and mango shipments.
- Agricultural Cooperatives:Member-owned operations in the Netherlands and Belgium pool capital for shared precision grading infrastructure.
- Retail Chains:Private-label specifications drive backward integration into controlled sorting operations.
Food Processing Companies capture the largest installed base. Exporters show the steepest expansion trajectory.
Technology:
Application requirements dictate sensor selection, with wet versus dry processing environments forcing distinct technical approaches.
- Vision System:High-speed CMOS camera arrays capture color and shape data at conveyor speeds exceeding three meters per second. Sony and ON Semiconductor sensor supply concentration creates six-month delivery vulnerability for OEMs.
- Infrared Technology:Short-wave infrared detector arrays penetrate peel surfaces to detect internal bruising and foreign material. SWIR modules now retrofit existing lines below five tons per hour, compressing minimum viable scale for premium sorting.
- Pneumatic Handling:Compressed-air ejection mechanisms remove rejected produce without mechanical contact, preserving soft fruit integrity.
- Mechanical Sorting:Physical size separation through mesh screens and roller gaps serves low-value commodity grades.
Vision System holds dominant share. Infrared Technology is gaining share fastest.
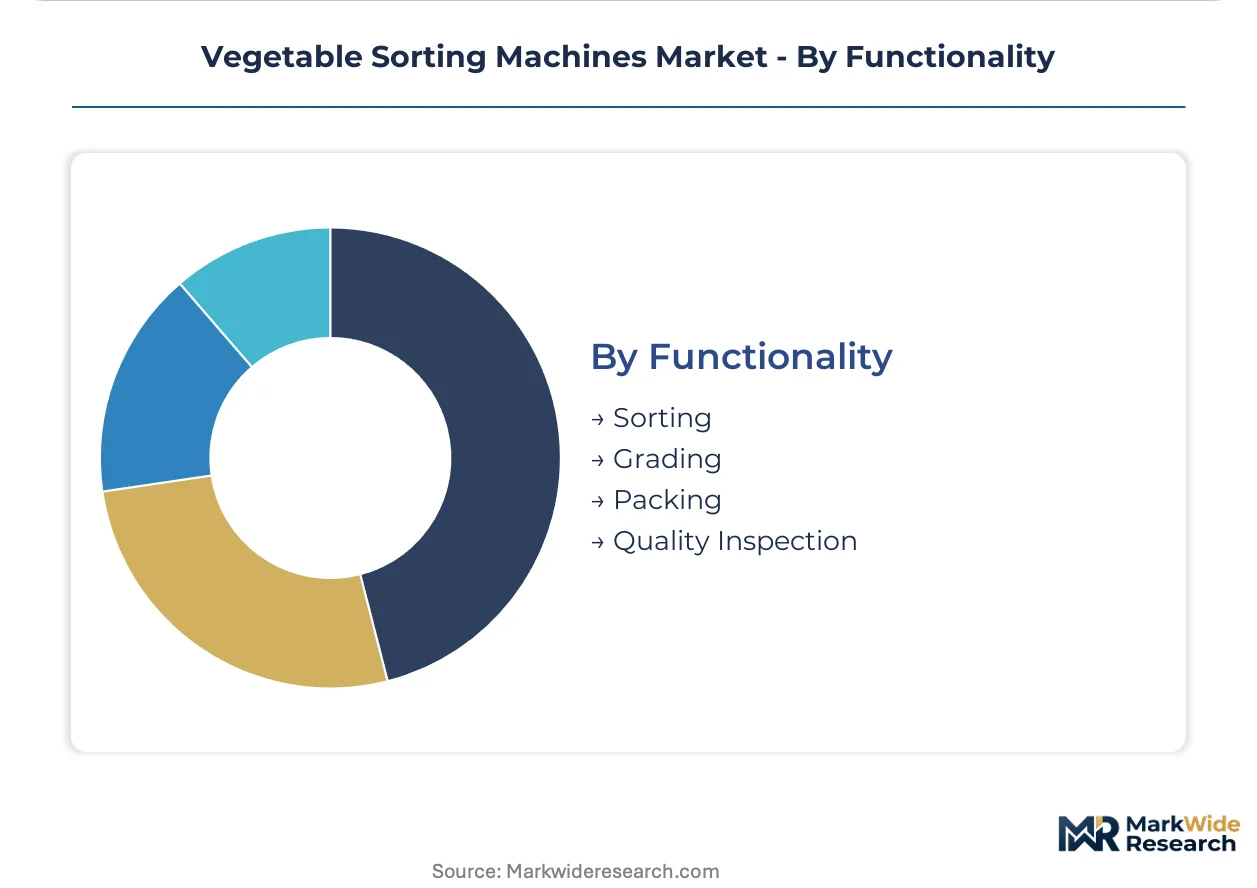
Functionality:
Customer type determines module integration depth, from standalone quality gates to end-to-end automated packing lines.
- Quality Inspection:Final-stage defect detection prevents downstream quality claims and retail rejection. BRC and IFS audit requirements mandate documented foreign-body control, displacing manual inspection.
- Sorting:Primary separation by defect profile, size, or color grade routes produce to appropriate downstream processing.
- Grading:Multi-criteria classification assigns batch uniformity ratings for export certification and retail specification compliance.
- Packing:Robotic handling integration with optical lines eliminates transfer conveyors, reducing floor space requirements.
Sorting commands the highest unit volume. Quality Inspection shows the strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters in Germany, the Netherlands, and Belgium supply precision optical systems to processors worldwide. Dutch agricultural cooperatives drive specification standards for premium export grading. Regulatory enforcement in the United States and Japan accelerates capital deployment toward automated documentation systems.
United States
Frozen vegetable packers in the Pacific Northwest and Midwest retrofit lines to meet FDA Food Safety Modernization Act traceability mandates. Machine-graded lot documentation satisfies enforcement protocols for domestic distribution and export certification. Washington State potato processors lead capital expenditure on hyperspectral detection systems.
Germany
Discount retail chains in Bavaria and North Rhine-Westphalia mandate supplier proof of optical detection for contract renewal. CE marking machinery directives accelerate replacement of unguarded legacy equipment. Stuttgart-area engineering firms integrate robotic handling with sorting lines to eliminate transfer conveyors.
Netherlands
Dutch potato cooperatives specify sub-millimeter bruise detection as a contract condition for premium European retail slots. EFSA acrylamide mitigation guidelines compel sugar-content screening before frying operations. Flevoland and North Brabant processing clusters concentrate shared precision grading infrastructure.
Belgium
Frozen fry exporters face acute compliance timelines for EFSA preventive control equipment classification. Antwerp and Limburg processors retrofit existing lines with compact SWIR modules rather than purchasing complete new systems. Walloon agricultural machinery distributors capture mid-capacity utility-grade demand.
Japan
Avocado and mango importers deploy infrared bruise detection to unlock premium retail access in Tokyo and Osaka markets. METI food safety guidelines elevate documentation requirements for imported produce. Chubu region machinery integrators specialize in compact footprint systems for limited processing floor space.
Vegetable Sorting Machines Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the equipment spectrum. The market structures around three tiers: hyperspectral precision specialists, integrated system engineering houses, and regional mechanical fabricators. Consolidation concentrates at the premium optical tier while utility-grade segments fragment across national suppliers. Dominant competitive moves include backward integration into sensor supply chains and strategic partnerships with agricultural cooperatives for specification influence.
Within the precision optical tier, TOMRA Systems ASA and Bühler Group exemplify technology-forward positioning through captive algorithm development and in-house camera module production. Key Technology occupies a position at the high-throughput industrial end. Among European specialists, Ellips and Greefa represent mid-capacity retrofit expertise, while Raytec Vision and Aweta anchor Italian and Dutch engineering traditions respectively. Sorma Group and Satma Corporation exemplify regional system integration capabilities serving cooperative and exporter procurement channels.
| Leading Market Players |
|---|
| TOMRA Systems ASA |
| Bühler Group |
| Key Technology |
| Ellips |
| Greefa |
| Satma Corporation |
| Aweta |
| Sorma Group |
| Raytec Vision |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with Dutch and Belgian potato processors lock in sensor module allocation and freeze price visibility across hyperspectral system tiers. These arrangements tether OEM margins to CMOS wafer output cycles while shielding premium buyers from spot-market volatility in camera component supply.
Pricing Analysis
CE marking machinery directives dictate the pricing tier structure for vegetable sorting equipment across European procurement channels. Three-tier pricing structure across premium hyperspectral, standard vision-system, and economy mechanical levels separates compliance-certified optical arrays from unguarded legacy retrofits. Cost compression in mid-capacity utility tiers is intensifying because regional distributors source monochrome camera modules from secondary sensor markets. Agricultural cooperatives in the Netherlands show least price sensitivity due to shared capital pooling, while Eastern European bulk processors remain most exposed to seasonal wage arbitrage delays.
Supply Chain Analysis
Germany, the Netherlands, and Belgium anchor precision optical system manufacturing for global vegetable processing deployment. Sony and ON Semiconductor CMOS sensors, SWIR detector arrays, and pneumatic ejection valves feed from concentrated East Asian and North American component sources. Single-source vulnerability in high-speed camera module supply creates six-month delivery cascade risk for sorter OEMs during shortage events. Distribution runs through OEM direct sales for premium configurations and regional agricultural machinery distributors for utility-grade mechanical sorters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperspectral imaging disruption is compressing detection thresholds faster than depreciation cycles, creating replacement demand windows for precision grading infrastructure. FDA and EFSA traceability mandates accelerate capital deployment timelines beyond normal equipment refresh patterns.
For Market Incumbents: Fortify sensor supply chain positioning through backward integration into camera module manufacturing or captive long-term offtake agreements with Sony and ON Semiconductor. Deepen algorithm development talent pools to defend against SWIR retrofit specialists encroaching on mid-capacity tiers. CE marking compliance engineering capabilities represent the critical lever for maintaining premium pricing power against unguarded legacy equipment replacement demand. For New Entrants and Emerging Players: FSSAI certification fast-track for Indian onion grading equipment opens first-mover positioning in hand-grading dependent export channels. Target underpenetrated domestic processors in India seeking defect-sorting deployment for European retail certification. Bundle compact SWIR retrofit modules with local service partnerships to bypass complete system OEM incumbency. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hyperspectral precision specialists with algorithm-update subscription models and long-term service contracts. Five-to-ten year viability favors OEMs with captive sensor supply chain control and cooperative specification influence in Dutch and Belgian processing clusters. Watch EFSA acrylamide enforcement intensity as inflection indicator for sugar-content detection equipment reclassification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | In-house CMOS module production insulates TOMRA and Bühler from Sony supply concentration risk. |
| SWIR Retrofit Module Development | Compact short-wave infrared arrays compress minimum viable scale below five tons per hour for Belgian processors. |
| Cooperative Specification Partnerships | Dutch agricultural pooling arrangements lock in premium grading standards for export slot allocation. |
| Algorithm Subscription Migration | Deep learning update contracts convert capital equipment sales into recurring hyperspectral detection revenue streams. |
| FSSAI Certification Pre-Positioning | Early compliance engineering captures Indian onion export infrastructure before domestic processor automation waves. |
Research Methodology
A standing panel of optical system engineering directors, food processing plant managers, agricultural cooperative procurement leads, and aftermarket service heads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA Food Safety Modernization Act enforcement documentation, EFSA acrylamide mitigation guidelines, CE marking machinery directive filings, and customs trade data for optical sorting equipment imports. Bottom-up equipment shipment analysis triangulated against top-down capital expenditure surveys from frozen vegetable packers and potato processing cooperatives.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling spanned product type tiers, end-user scale categories, technology sensor architectures, and functionality integration depth, with regional regulatory cluster overlays for FDA, EFSA, and FSSAI jurisdictions. CAGR derivation incorporated equipment replacement cycle compression from hyperspectral threshold advancement and compliance-driven procurement acceleration. Industry-specific forecast inputs included Dutch cooperative grading specification evolution and Japanese import channel bruise detection requirements.
Underlying assumptions cover EFSA enforcement timeline adherence, CMOS sensor supply normalization, and FSSAI code expansion implementation, with deviation risk concentrated in tariff exposure for East Asian camera components and seasonal labor pool availability in Eastern European processing regions. Recalibration cycles align with material shifts in food safety regulator enforcement intensity and hyperspectral imaging hardware cost-performance frontier movement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Billhook Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Aquarium Pumps and Filters Market
Agricultural Equipment
Asia-Pacific Agricultural Tires Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Plucker Machine Market
Agricultural Equipment
Floating Covers Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Crop Spraying Drone Market