
 Fish Breeding Tank Market | 2026-2036
Fish Breeding Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Breeding Tank Market Analysis
REACH compliance is recalibrating the cost-of-entry calculus for European tank manufacturers, requiring non-toxic sealant certifications and material traceability that smaller fabricators struggle to fund. Pentair Aquatic Eco-Systems leverages its integrated filtration engineering to absorb these compliance costs without margin erosion. Acrylic Tank Manufacturing anchors its position through captive acrylic supply and custom fabrication for research-grade installations. Hagen Marina competes across mass-market channels with standardized glass tank lines that limit regulatory exposure.
A fish breeding tank is a purpose-built vessel, typically constructed from glass, acrylic, or reinforced polymer, designed to maintain controlled water chemistry, temperature, and aeration for reproductive cycling and fry development. Wall thickness, joint sealing methodology, and UV-stabilization ratings determine structural longevity under continuous submersion and chemical exposure. Glass tanks dominate the amateur breeder segment where optical clarity and scratch resistance command premium positioning, while acrylic tanks capture the fastest growth in research institutions requiring larger custom volumes with superior thermal insulation. The accessory category concentrates margin pools in filtration and aeration systems, where replacement cycles outpace tank hardware by a factor of three to one.
EPA effluent guidelines and FDA seafood safety protocols shape product specifications for tanks entering commercial food-fish hatcheries, particularly in controlled-environment recirculating systems. ISO 9001 quality management and IEC electrical safety standards govern heater and lighting subsystem integration, creating compliance layering that favors vertically integrated suppliers. Stakeholders must monitor how emerging state-level water-use restrictions in drought-prone regions redefine tank sizing economics and drive modular system architectures.
Market Dynamics
REACH compliance and the EU Green Deal are forcing European manufacturers toward closed-loop filtration architectures, while commercial aquarists in Germany and Southeast Asia scale capacity to capture ornamental fish export premiums.
Growth Catalysts
- EU Green Deal water-efficiency mandates:Germany's large-scale koi and discus breeding operations around Bavaria and Baden-Württemberg are retrofitting facilities to meet tightening effluent standards, creating replacement demand for closed-loop systems.
- Ornamental fish export expansion:Commercial aquarists in Thailand and Indonesia are building dedicated breeding infrastructure to supply European and North American retail channels with certified disease-free stock.
- Acrylic thermal insulation performance:Research institutions requiring precise temperature control for sensitive fry development are specifying custom acrylic volumes over glass alternatives.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and reinforced polymer tank production faces margin compression from fluctuating methyl methacrylate monomer costs tied to crude oil derivatives.
- REACH certification cost barriers:Small-scale European fabricators lack capital to fund non-toxic sealant certifications and material traceability systems required for market access.
- Glass scratch-resistance threshold:Amateur breeders continue specifying glass despite weight and thermal limitations, slowing acrylic penetration in the volume segment.
Strategic Opportunities
- Modular system architectures:Drought-prone regions in Australia and the western United States are redefining tank sizing economics through state-level water-use restrictions that favor scalable, reconfigurable installations.
- Research-grade custom fabrication:Universities and marine biology institutes require larger experimental volumes with integrated sensor arrays, opening premium specification channels.
- Replacement accessory cycles:Filtration and aeration subsystems require replacement at triple the frequency of tank hardware, creating recurring revenue pools for integrated suppliers.
Industry Challenges
- ISO 9001 and IEC electrical safety layering:Heater and lighting subsystem integration requires simultaneous quality management and electrical safety certifications that extend product development timelines.
- EPA effluent guideline alignment:Commercial food-fish hatcheries must reconcile FDA seafood safety protocols with state-level discharge permits, complicating specification standardization.
- Filtration engineering talent scarcity:Closed-loop system design requires cross-disciplinary expertise in hydrodynamics and biological filtration that outpaces vocational training pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Breeding Tank Market |
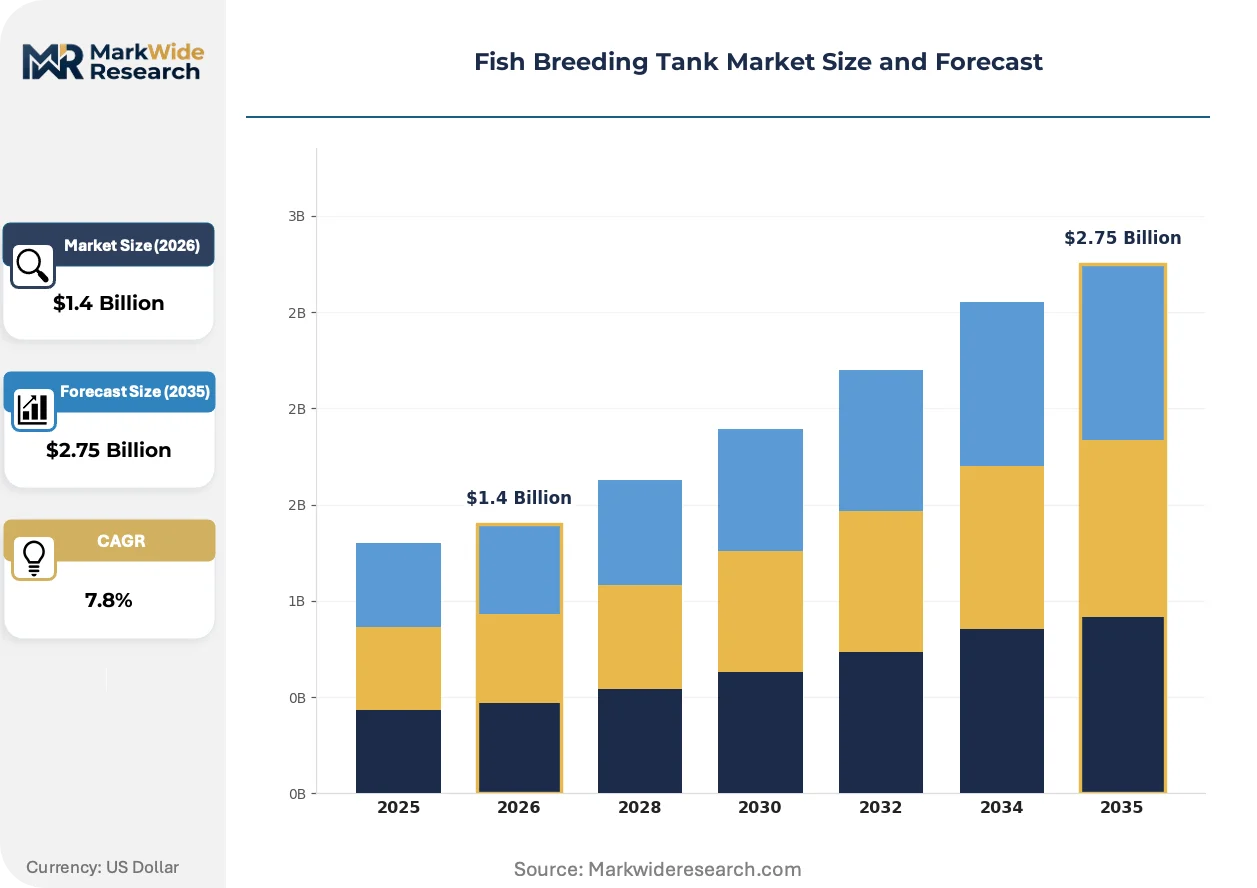
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Tanks, Acrylic Tanks, Plastic Tanks, Hybrid Tanks End User: Amateur Breeders, Commercial Aquarists, Research Institutions, Educational Institutions Size: Small Tanks, Medium Tanks, Large Tanks, Custom Tanks Accessory Type: Filters, Heaters, Aerators, Lighting Systems |
| Companies Covered | Hagen Marina, Penn-Plax, Purewell Fish Farming Equipment, Acrylic Tank Manufacturing, Sea Atlanta, Titan Aquatic Exhibits, Pentair Aquatic Eco-Systems, Aquatic Ecosystems, Aquaneering Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Breeding Tank Market Emerging Trajectories
Sensor-integrated monitoring systems and predictive maintenance algorithms are transforming how breeding facilities manage water chemistry stability, while regulatory pressure accelerates material substitution and energy recovery integration.
Recirculating aquaculture system (RAS) engineering is overtaking traditional flow-through designs in commercial hatchery specifications. Large-scale food-fish producers in Norway and Chile are adopting fully closed-loop architectures that recover thermal energy and minimize water exchange. This technology is overtaking conventional tank-farm layouts by compressing land-use requirements and enabling inland production of marine species previously restricted to coastal zones.
REACH substance restrictions are compelling sealant and adhesive reformulation across European supply chains. Manufacturers must eliminate specific phthalates and heavy-metal catalysts from bonding compounds used in tank assembly, extending material qualification periods. German fabricators serving research institutions are responding fastest, leveraging existing quality management infrastructure to pre-certify replacement chemistries before mandatory phase-in dates.
Research institutions are consolidating procurement around single-source integrated system contracts rather than discrete tank and component purchases. University marine science departments in California and Queensland are specifying turnkey installations with embedded telemetry and remote monitoring subscriptions. This pattern concentrates vendor selection authority with engineering teams rather than facilities management, rewarding suppliers with captive filtration and control system capabilities.
Fish Breeding Tank Market Segmentation
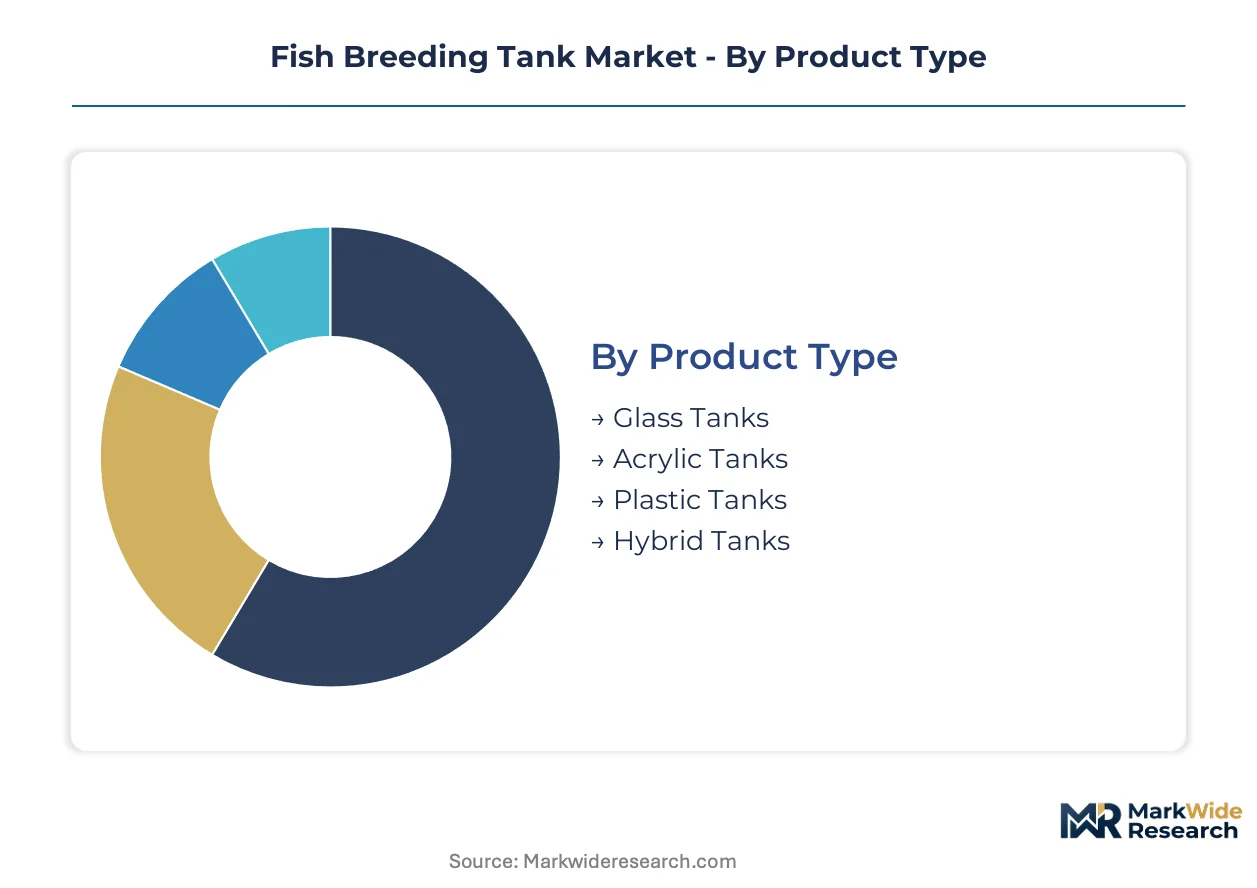
Material selection and end-use specialization drive divergent margin structures across the fish breeding tank market. Each segment category carries distinct regulatory exposure, replacement cycle dynamics, and customer procurement authority that reshape competitive positioning.
Product Type:
Glass commands volume share through amateur channel penetration while acrylic captures premium specification in research and commercial retrofit projects.
- Glass Tanks:Silicate-based construction with scratch-resistant surfaces and optical clarity serves hobbyist breeders prioritizing durability over thermal performance. Bavarian koi operations specify glass for breeding display units where visual inspection frequency matters.
- Acrylic Tanks:Polymethyl methacrylate composition delivers superior thermal insulation and seamless custom fabrication for large-volume research installations. California marine biology institutes specify acrylic for temperature-sensitive fry development protocols.
- Plastic Tanks:Reinforced polymer formulations serve budget-conscious educational institutions and entry-level commercial operations with standardized sizing.
- Hybrid Tanks:Composite assemblies combining glass viewing panels with polymer structural frames address mid-market buyers seeking weight reduction without full acrylic cost.
Today's leader: Glass Tanks. Tomorrow's challenger: Acrylic Tanks.
End User:
Procurement authority concentrates with facilities engineering teams in institutional settings while commercial aquarists optimize for export certification compliance.
- Amateur Breeders:Hobbyist segment drives standardized glass tank demand through retail and direct-to-consumer channels with limited accessory integration.
- Commercial Aquarists:Professional breeding operations in Thailand and Indonesia scale dedicated infrastructure for disease-free ornamental fish export to European and North American retail channels.
- Research Institutions:University marine science departments in Queensland and California consolidate procurement around single-source integrated system contracts with embedded telemetry and remote monitoring subscriptions.
- Educational Institutions:Schools and public aquariums prioritize durability and safety certification over performance specifications, favoring plastic and hybrid constructions.
Commercial Aquarists currently anchor volume demand. Research Institutions represent the steepest expansion trajectory through integrated system contracting.
Size:
Water-use restrictions in drought-prone regions are redefining tank sizing economics toward modular, scalable architectures.
- Small Tanks:Compact volumes under 100 liters dominate amateur breeder entry points and classroom educational deployments with limited filtration integration.
- Medium Tanks:Intermediate capacities serve commercial aquarist starter facilities and institutional research pilot programs requiring reconfigurable layouts.
- Large Tanks:Industrial-scale volumes exceeding 1000 liters concentrate in German koi and discus breeding clusters around Baden-Württemberg where land availability supports centralized operations.
- Custom Tanks:Non-standard dimensions specified by research institutions and specialized commercial breeders require captive fabrication capabilities and extended lead times.
Medium Tanks currently bridge volume and value. Custom Tanks are gaining share fastest as research procurement consolidates.
Accessory Type:
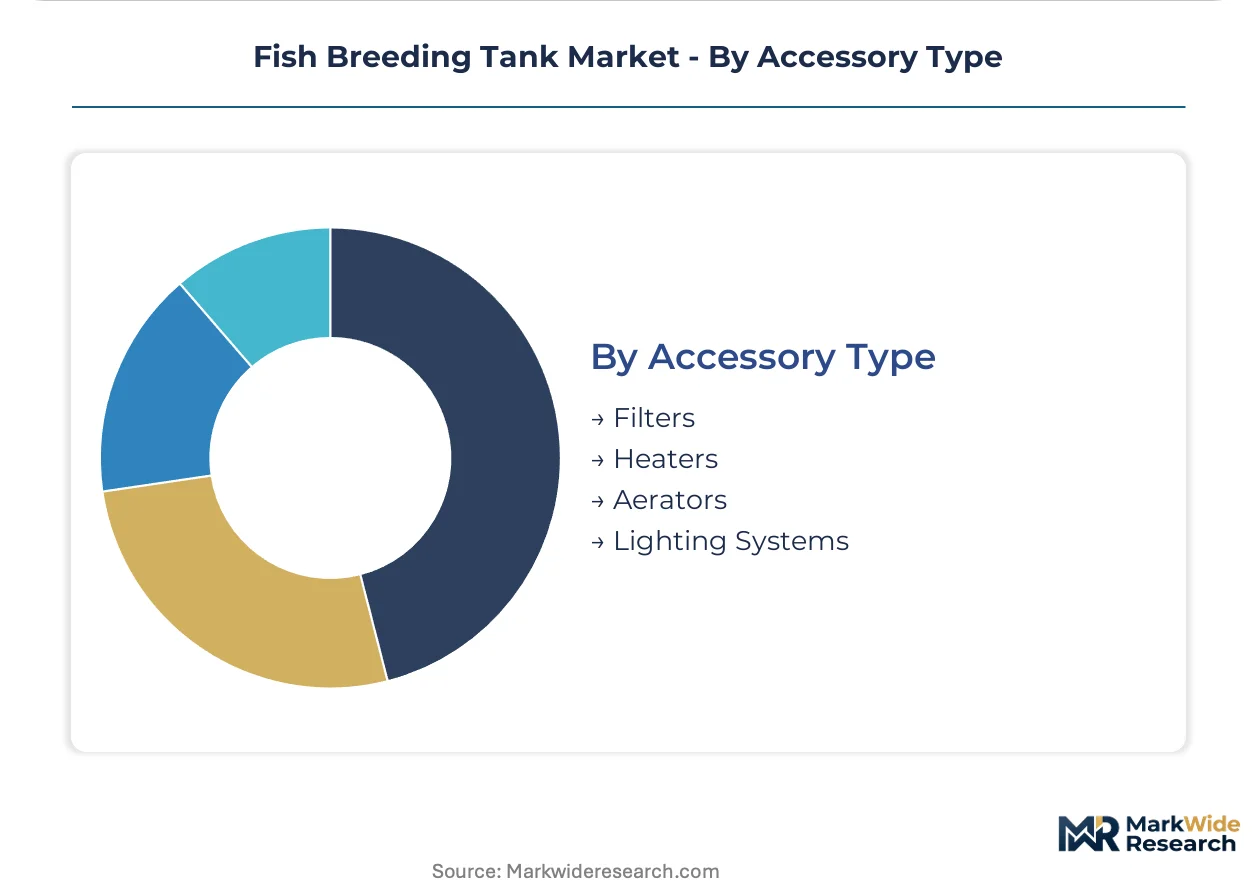
Replacement cycles for subsystems outpace tank hardware by three to one, concentrating recurring revenue with integrated suppliers.
- Filters:Mechanical and biological filtration units face mandatory replacement under EU Green Deal effluent standards, driving retrofit demand in German breeding facilities.
- Heaters:Temperature control systems require IEC electrical safety certification layering that extends product development timelines for subsystem integrators.
- Aerators:Dissolved oxygen management equipment serves high-density commercial operations where stocking rates exceed passive gas exchange capacity.
- Lighting Systems:Spectral control units for reproductive cycling and fry development support research-grade installations requiring programmable photoperiod management.
Filters dominate current replacement spend. Lighting Systems are climbing the fastest as research institutions specify precision photobiology controls.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale ornamental fish breeding in post-war Europe, establishing technical standards for recirculating systems that now propagate across commercial aquaculture worldwide. Export certification regimes in Southeast Asia trace their regulatory DNA to protocols developed in Bavarian breeding clusters during the 1980s.
Germany
Baden-Württemberg and Bavaria host Europe's densest concentration of koi and discus breeding operations, with facilities retrofitting under EU Green Deal water-efficiency mandates. ECHA's REACH substance restrictions are eliminating phthalate-based sealants from tank assembly lines, forcing reformulation cycles. Stuttgart-area fabricators are pre-certifying replacement chemistries ahead of mandatory phase-in dates.
United States
California and Florida marine biology institutes are consolidating procurement around single-source integrated system contracts with embedded telemetry. EPA effluent guidelines for commercial hatcheries intersect with FDA seafood safety protocols, complicating specification standardization. University marine science departments in San Diego and Miami are driving demand for custom acrylic volumes with precision photobiology controls.
Thailand
Bangkok metropolitan breeding operations are scaling dedicated infrastructure for disease-free ornamental fish export to European and North American retail channels. The country's national fisheries regulator enforces strict health certification for export stock. Pathum Thani province clusters commercial aquarists supplying certified discus and betta to German importers.
China
Pearl River Delta manufacturers dominate acrylic tank fabrication for research-grade installations, leveraging captive methyl methacrylate supply chains. MEE water discharge standards are tightening for aquaculture equipment producers in Guangdong province. Shenzhen-area fabricators are integrating sensor arrays for university contracts in California and Queensland.
Australia
Queensland research institutions are specifying turnkey installations with remote monitoring subscriptions for Great Barrier Reef restoration programs. State-level water-use restrictions in drought-prone regions are redefining tank sizing economics toward modular architectures. Brisbane marine science departments are consolidating vendor selection authority with engineering teams rather than facilities management.
Fish Breeding Tank Market Vendor Landscape
The competitive structure tilts toward vertically integrated filtration specialists with captive engineering capabilities. Market concentration is moderate, with three to five dominant players commanding research and commercial retrofit segments while fragmented local fabricators serve amateur channels. Two strategic archetypes predominate: integrated system suppliers bundling tanks with telemetry and control platforms, and material-specialist fabricators leveraging captive acrylic or glass supply. Competitive moves center on compliance pre-certification ahead of regulatory deadlines and strategic partnerships with university procurement departments.
Among North American integrated system suppliers, Pentair Aquatic Eco-Systems and Acrylic Tank Manufacturing occupy distinct positioning archetypes. Pentair represents the engineering-integrated tier, leveraging filtration subsystem expertise to absorb REACH compliance costs. Acrylic Tank Manufacturing exemplifies the captive-material specialist model. Hagen Marina sits within the mass-market standardization tier, competing through glass tank lines that limit regulatory exposure. These three anchors illustrate how compliance layering and material strategy are separating sustainable positioning from margin compression.
| Leading Market Players |
|---|
| Hagen Marina |
| Penn-Plax |
| Purewell Fish Farming Equipment |
| Acrylic Tank Manufacturing |
| Sea Atlanta |
| Titan Aquatic Exhibits |
| Pentair Aquatic Eco-Systems |
| Aquatic Ecosystems |
| Aquaneering Inc. |
| Others |
Supply Flow & Price Mechanics
Methyl methacrylate monomer spot prices cascade through acrylic tank fabrication into three distinct buyer tiers: research institutions absorbing premium custom volumes, commercial aquarists negotiating mid-market standardized lines, and amateur breeders gravitating toward entry-level glass alternatives. This raw-material cost transmission concentrates pricing power with German and Chinese fabricators commanding captive polymer supply.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates research-grade custom fabrication from commercial retrofit specifications and mass-market glass lines. Price differentiation hinges on REACH certification tier and volume scale, with certified German fabricators commanding substantial premiums over Southeast Asian competitors. Cost compression in the standard tier is intensifying because ECHA sealant reformulation mandates extend qualification timelines. Amateur breeders exhibit highest price sensitivity, while Queensland marine science departments demonstrate lowest sensitivity due to integrated system bundling.
Supply Chain Analysis
Container freight rates from Guangdong to California and Rotterdam determine landed cost competitiveness for acrylic research tanks. Manufacturing concentrates in China, Germany, and Thailand, drawing from petrochemical feedstocks, optical-grade glass, and marine-certified sealant inputs. Single-source vulnerability persists in methyl methacrylate monomer supply, where Pearl River Delta producers anchor global acrylic resin production. Distribution runs through university procurement consortia in California and Queensland, direct commercial aquarist relationships in Bavaria, and retail channel partnerships for amateur segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fish breeding tank market functions as a stable compounder anchored by recurring filtration accessory replacement cycles that outpace tank hardware turnover threefold. Regulatory compliance layering creates durable competitive moats for pre-certified suppliers.
For Market Incumbents: Cement market position by accelerating REACH-compliant sealant pre-certification ahead of ECHA phase-in deadlines and securing captive acrylic supply through backward integration into methyl methacrylate sourcing. Threat substitution from sensor-integrated monitoring platforms demands embedded telemetry bundling in research contracts. Certification investment represents the critical defensive lever.
For New Entrants and Emerging Players: Sensor-integrated predictive maintenance algorithms offer a technology-first wedge into the research institution segment currently dominated by legacy filtration engineering. White-space targets include modular tank architectures for drought-prone Australian state markets and disease-free ornamental fish export infrastructure in Indonesian commercial aquarist clusters. Go-to-market execution should prioritize university marine science department pilot programs with telemetry subscription bundling.
For Investors and Strategic Acquirers: Consolidation pressure builds where small-scale European fabricators face REACH certification cost barriers without capital reserves to fund material traceability systems. Long-term viability favors vertically integrated suppliers combining captive polymer supply with filtration engineering capabilities over pure-play tank fabricators. Acquisition targets should demonstrate pre-certified sealant chemistries and established university procurement relationships. The signal to watch is German state-level water-efficiency mandate acceleration triggering replacement demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Certification Investment | ECHA sealant reformulation deadlines favor early movers with qualified replacement chemistries in Stuttgart-area fabrication. |
| Captive Acrylic Supply Integration | Pearl River Delta methyl methacrylate sourcing secures margin stability against petrochemical feedstock volatility. |
| Sensor-Integrated System Bundling | Embedded telemetry contracts with Queensland marine science departments concentrate vendor selection authority with engineering teams. |
| Modular Architecture Development | Scalable tank designs address Australian state-level water-use restrictions redefining sizing economics in drought-prone regions. |
| University Procurement Partnership | Single-source integrated system contracts with California marine biology institutes lock in recurring filtration replacement revenue. |
Methodological Framework
Multiple input streams — primary interviews with commercial aquarist operators, research institution facilities managers, and filtration subsystem engineers; secondary validation through ECHA regulatory filings, customs trade data, and university procurement databases; plus patent landscape analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed breeding facility site assessments in Bavaria and Baden-Württemberg, technical consultations with German sealant formulators, and channel interviews with California marine science procurement committees. Secondary sources included EU Green Deal implementation directives, EPA effluent guideline documentation, and ornamental fish export certification records from Thai national fisheries regulators.
Data-stream reconciliation applied across the analysis window modeled volume and value outputs through segmentation by material type, end-user archetype, tank capacity tier, and accessory subsystem category. CAGRs were derived from trend extrapolation of replacement cycle dynamics, regulatory compliance cost absorption rates, and research institution procurement consolidation patterns. Industry-specific forecast inputs incorporated EU water-efficiency mandate implementation timelines and acrylic thermal insulation performance specifications driving institutional specification shifts.
The model holds under steady regulatory enforcement intensity and stable petrochemical feedstock availability; deviation in ECHA substance restriction acceleration or methyl methacrylate supply disruption would shift replacement demand timing and material substitution trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Crab Market
Aquaculture Innovations
South America Aqua Feed Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
Mariculture Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
Ornamental Fish Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Ecuador Shrimp Feed Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
Norway Aquaculture Market