
 Aquaculture Additives Market | 2026-2036
Aquaculture Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Aquaculture Additives Market Intelligence
Direct-to-farm distribution is rewriting how aquaculture additive producers reach end users in coastal production zones. Cargill, Incorporated leverages its integrated aquaculture nutrition platform to sustain volume leadership across Latin American shrimp operations. Alltech competes through yeast-derived additive specialization, while Evonik Industries AG anchors its position with precision amino acid formulations for high-density fish systems.
Aquaculture additives comprise functional feed ingredients including immunostimulants, probiotics, enzymes, and vitamins designed to enhance growth rates, disease resistance, and feed conversion ratios in farmed aquatic species. These compounds typically integrate at inclusion rates between 0.01% and 2% of total feed mass during extrusion or top-dressing processes. Probiotics and immunostimulants now command the fastest expansion as producers phase out antibiotic-dependent regimes, while vitamin premixes occupy mature margin pools sustained by bulk procurement contracts. Fish feed and shrimp feed applications together structure the dominant demand architecture, with crustacean breeding segments showing accelerated uptake of specialized enzyme blends.
EU EFSA residue monitoring frameworks and REACH chemical registration requirements shape product formulation standards for exporters targeting European retail channels. The EU Green Deal's Farm to Fork strategy tightens environmental performance benchmarks, while FDA import alert protocols in the United States enforce veterinary drug residue screening at border entry points. Stakeholders must monitor evolving certification thresholds across multiple jurisdictions to maintain market access and avoid supply chain disruption.
Market Dynamics
Antibiotic phase-out mandates across major importing blocs are forcing feed mills to rebuild formulation protocols around functional alternatives, compressing development timelines and reshaping supplier qualification criteria.
Growth Catalysts
- EU F-Gas Regulation:Residue limit tightening on imported aquaculture products drives Vietnamese and Indonesian farms toward certified additive programs to maintain European retail access.
- Shrimp feed applications:Intensive pond systems in Vietnam's Mekong Delta generate concentrated demand for immunostimulant and probiotic formulations as stocking densities rise.
- Enzyme engineering:Next-generation carbohydrase and protease blends improve feed conversion ratios in high-density tilapia and barramundi operations.
Market Restraints
- Fishmeal price volatility:Peruvian anchovy catch fluctuations transmit directly to marine protein costs, squeezing premix margin structures.
- REACH registration burdens:Novel additive molecules face extended ECHA evaluation timelines that delay European market entry by 18-36 months.
- Probiotic stability limits:Viability loss during extrusion above 85°C restricts inclusion rates in pelleted shrimp feeds.
Strategic Opportunities
- Recirculating aquaculture systems:Closed-loop salmon and trout facilities in Norway and Chile create demand for water-quality-modulating microbial consortia.
- Brazilian tilapia expansion:Underpenetrated feed additive penetration in Latin American freshwater operations offers volume growth potential.
- EU Green Deal incentives:Farm to Fork environmental performance benchmarks reward low-carbon feed formulation innovations with preferential procurement status.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in aquatic species digestive physiology remains concentrated among a limited pool of European and Asian research institutions.
- Multi-jurisdiction certification lag:Simultaneous FDA import alert compliance, EFSA residue monitoring, and national feed safety registrations create documentation bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquaculture Additives Market |
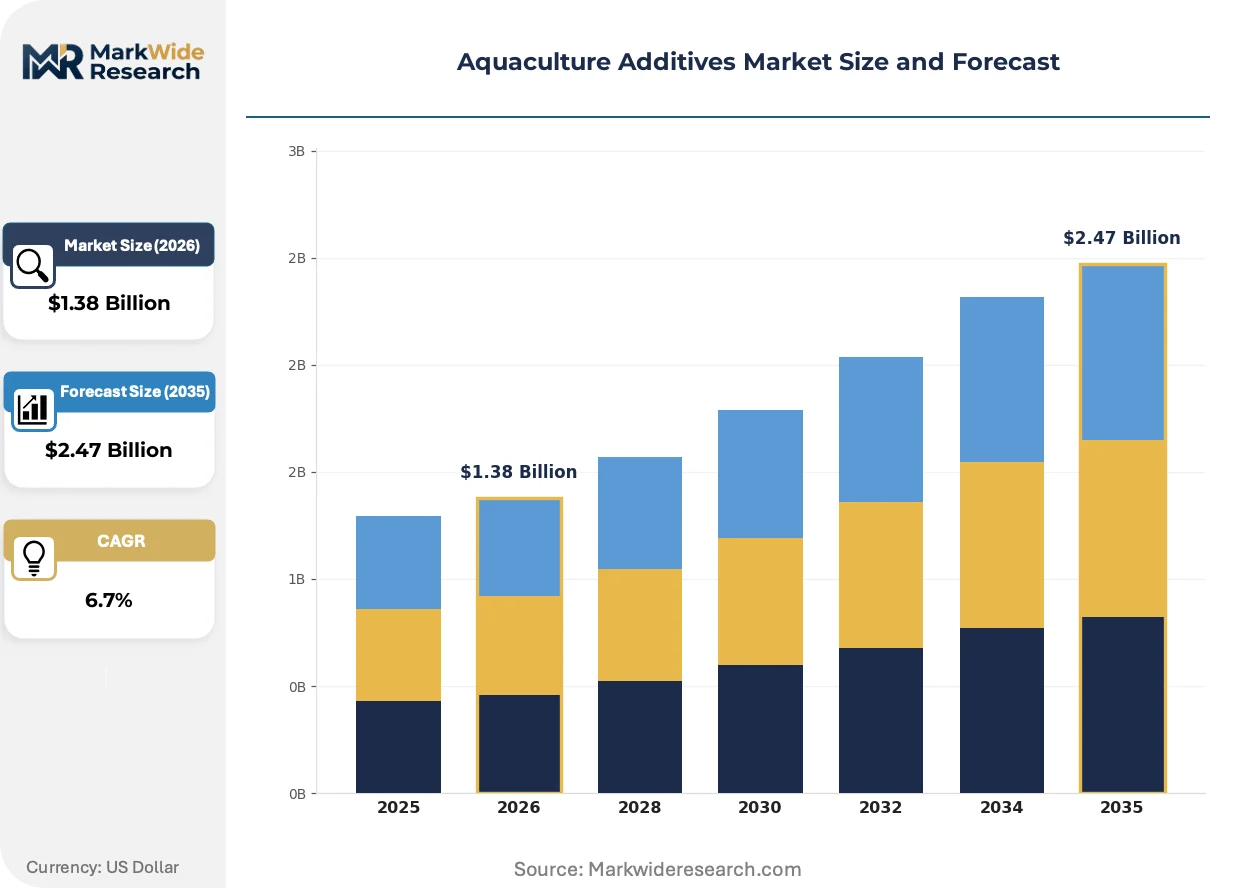
| Market Size in 2026 | $1.38 Billion |
| Market Size in 2035 | $2.47 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunostimulants, Growth Enhancers, Probiotics, Antioxidants, Enzymes, Vitamins Application: Fish Feed, Shrimp Feed, Mollusk Cultivation, Crustacean Breeding, Algae Growth, Water Quality Improvement End User: Aquaculture Farms, Hatcheries, Research Institutes, Feed Manufacturers, Government Agencies, Private Hatcheries Form: Liquid, Powder, Granules, Pellets, Suspension, Concentrate |
| Companies Covered | Cargill, Incorporated, Alltech, Evonik Industries AG, Kemin Industries, Nutreco N.V., Archer Daniels Midland Company, DuPont de Nemours Inc., BASF SE, BioMar Group A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquaculture Additives Market Strategic Shifts & Innovations
Digital feed formulation platforms and precision delivery systems are compressing the traditional additive development cycle while regulatory fragmentation forces parallel certification tracks.
Microencapsulation technology for heat-sensitive probiotics is virtualizing the conventional top-dressing application method. Thai and Vietnamese shrimp feed mills are adopting fluid-bed coating systems at pilot scale. This shift is virtualizing the historical trade-off between pellet durability and live culture viability.
EU EFSA residue monitoring frameworks now mandate expanded veterinary drug screening for imported crustacean products. European retailers are pushing supplier audits deeper into Southeast Asian contract farming operations. Vietnamese exporters are responding by segregating supply chains into EU-certified and general-market channels.
Direct-to-farm distribution networks are displacing traditional distributor intermediaries in coastal production zones. Additive producers now deploy technical service teams to pond-side locations in Indonesia's Java Sea clusters. This channel compression is most advanced in Vietnam, where Cargill's integrated nutrition platform has established localized blending facilities.
Aquaculture Additives Market Segmentation
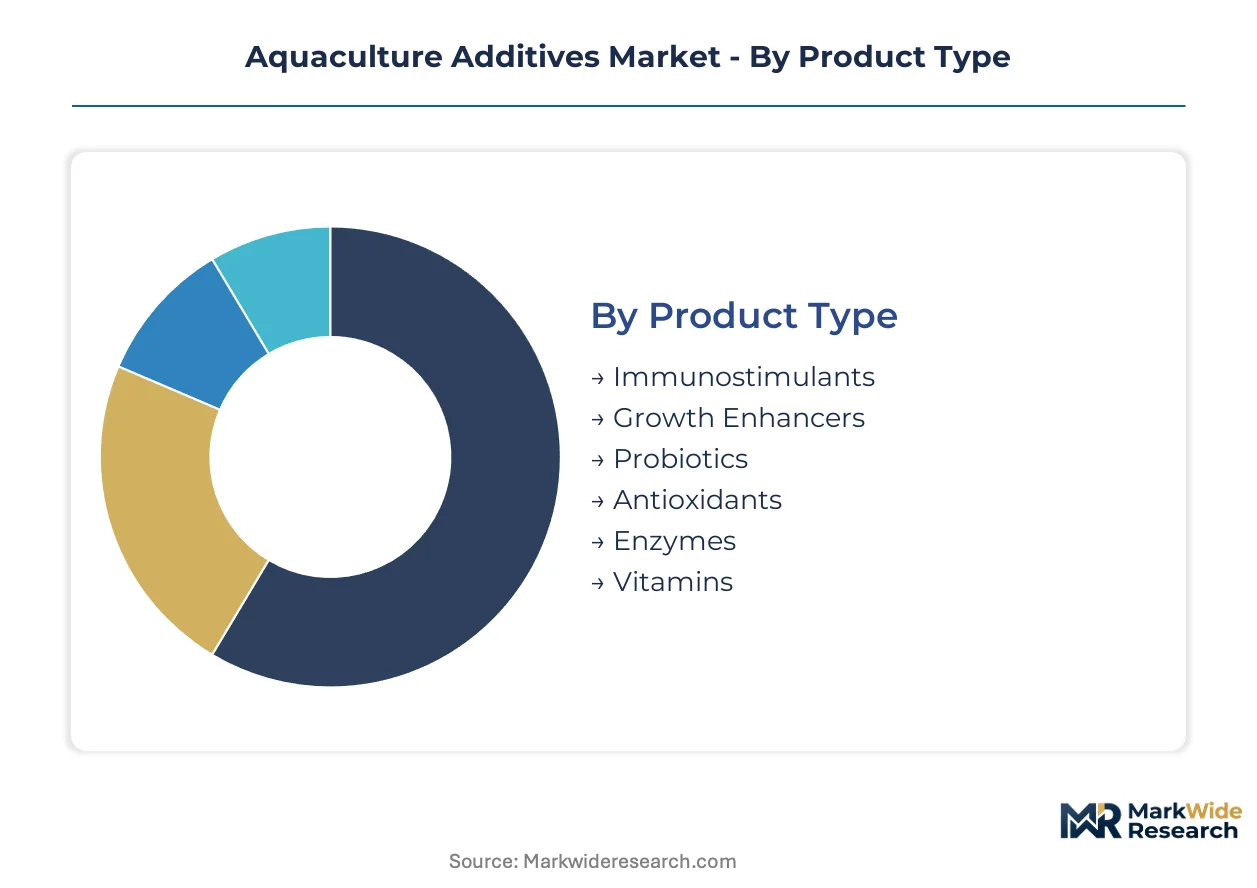
Segmentation in aquaculture additives reveals how formulation chemistry, delivery mechanisms, and species-specific physiology intersect to create distinct value pools. Each dimension carries different margin structures, regulatory exposure, and technical barriers to entry.
Product Type:
Functional ingredient chemistry spans immune modulation through metabolic optimization, with each class carrying distinct stability requirements and inclusion rate economics.
- Immunostimulants:Beta-glucan and nucleotide formulations activate non-specific immune responses in shrimp and finfish. Vietnamese Mekong Delta intensive pond systems now specify immunostimulant inclusion as a condition for EU export certification under tightening EFSA residue frameworks.
- Probiotics:Live microbial cultures including Bacillus and Lactobacillus strains colonize gut microbiota to outcompete pathogenic bacteria. Heat stability during extrusion above 85°C remains the primary constraint, driving demand for microencapsulated variants in pelleted shrimp feeds.
- Growth Enhancers:Hormone-free metabolic activators and nucleotide premixes accelerate biomass accumulation rates.
- Antioxidants:Ethoxyquin and natural tocopherol blends preserve lipid integrity in high-oil marine feeds.
- Enzymes:Next-generation carbohydrase and protease blends unlock nutrient bioavailability in plant-based protein formulations.
- Vitamins:Fat-soluble and water-soluble premixes maintain baseline nutritional adequacy across species.
Established volume favors vitamins; emerging adoption favors probiotics.
Application:
Species-specific digestive physiology and production system intensity dictate formulation requirements across aquatic taxa.
- Shrimp Feed:High-density Penaeus vannamei and Penaeus monodon operations require specialized immunostimulant and probiotic protocols. Indonesian and Vietnamese commercial farms are rebuilding formulation standards around antibiotic-free regimes to satisfy EU F-Gas Regulation residue limits.
- Fish Feed:Salmon, tilapia, and barramundi formulations emphasize amino acid precision and feed conversion optimization. Norwegian and Chilean recirculating aquaculture systems are creating demand for water-quality-modulating microbial consortia.
- Crustacean Breeding:Broodstock nutrition programs target reproductive performance and larval quality.
- Mollusk Cultivation:Bivalve hatcheries utilize microalgae enrichment and settlement cues.
- Algae Growth:Photobioreactor operations require micronutrient dosing for biomass productivity.
- Water Quality Improvement:Pond-bottom probiotic treatments and nitrifying bacterial inoculants support intensive stocking densities.
Shrimp feed commands premium pricing; fish feed sustains volume scale.
End User:
Customer type determines technical service intensity, procurement scale, and regulatory documentation requirements.
- Feed Manufacturers:Industrial compounders purchase bulk premixes and integrate additives during extrusion processes. Cargill's integrated nutrition platform in Vietnam supplies localized blending services to mid-scale regional mills.
- Aquaculture Farms:Direct-to-farm distribution channels now deliver pond-side technical support in Indonesia's Java Sea clusters and Vietnam's coastal production zones.
- Hatcheries:Larval-stage nutrition demands specialized live feed enrichment protocols.
- Private Hatcheries:Independent operators seek flexible minimum-order quantities and technical consultation.
- Research Institutes:Experimental validation programs require analytical-grade materials and batch documentation.
- Government Agencies:Extension programs and regulatory reference standards procurement.
Feed manufacturers consolidate procurement; farm-direct channels are expanding fastest.
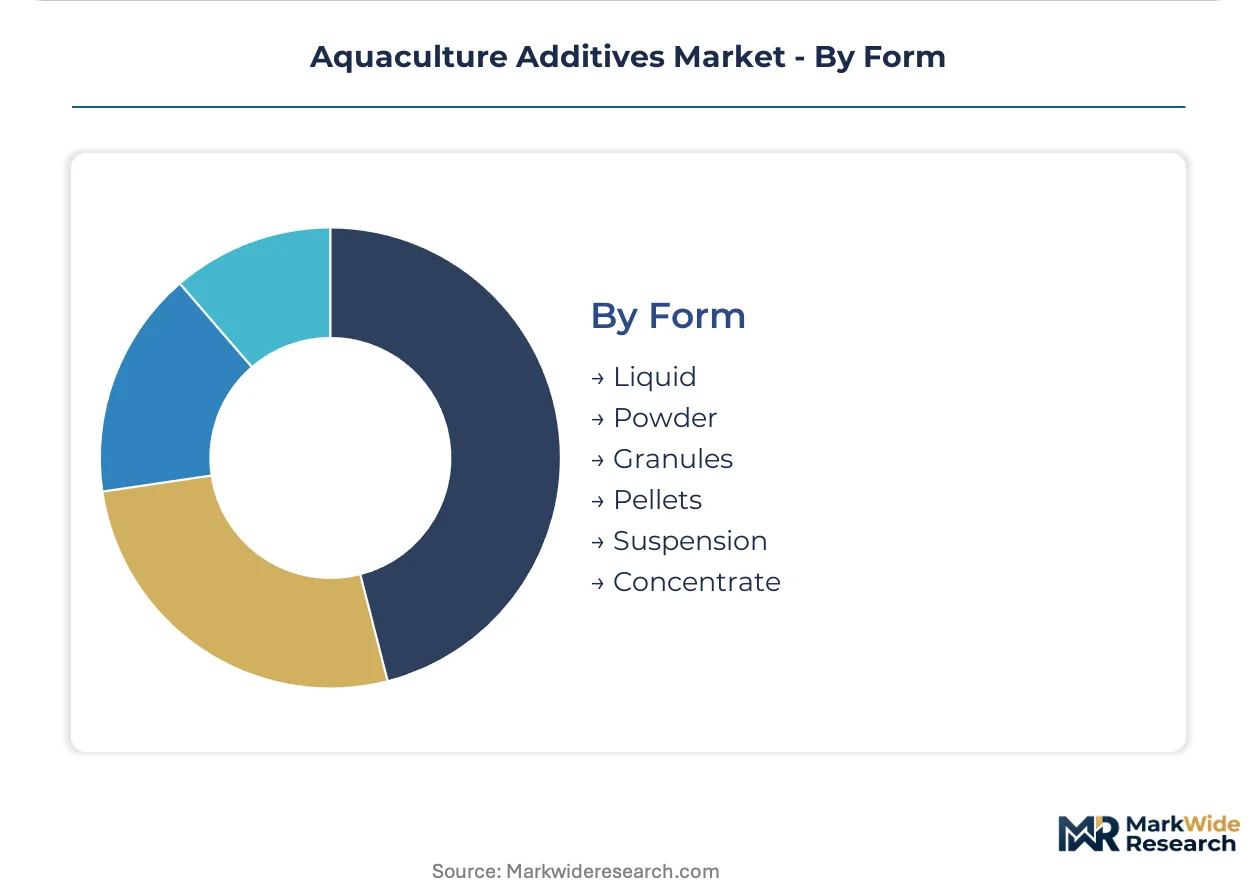
Form:
Physical delivery format determines processing compatibility, shelf stability, and application labor requirements.
- Powder:Dry premixes enable flexible dosing into mash feeds and top-dressing applications. Vietnamese shrimp feed mills specify powder probiotics for post-extrusion coating to preserve culture viability.
- Liquid:Aqueous suspensions and emulsions facilitate spray application and drinking water delivery. Thai hatcheries favor liquid vitamin concentrates for live feed enrichment in Artemia and rotifer cultures.
- Granules:Intermediate particle size for slow-release pond-bottom treatments.
- Pellets:Pre-formulated complete feeds with embedded additives.
- Suspension:Colloidal delivery systems for water-column distribution.
- Concentrate:High-potency formulations requiring dilution prior to application.
Powder dominates manufacturing throughput; liquid formats are gaining share in hatchery applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's Farm to Fork strategy and tightening residue limits under the F-Gas Regulation are redirecting investment flows toward certified additive programs in major exporting nations. Vietnam's Mekong Delta intensive pond systems now dominate Southeast Asian output volumes. Norwegian recirculating aquaculture facilities are pioneering water-quality-modulating microbial consortia adoption.
Vietnam
Intensive Penaeus vannamei operations in the Mekong Delta generate concentrated demand for immunostimulant and probiotic formulations as stocking densities rise. EFSA residue monitoring frameworks now mandate expanded veterinary drug screening for crustacean products bound for European retail channels. Vietnamese exporters are responding by segregating supply chains into EU-certified and general-market channels, with localized blending facilities expanding across coastal production zones.
Norway
Closed-loop salmon and trout recirculating aquaculture systems create specialized demand for nitrifying bacterial inoculants and pond-bottom probiotic treatments. The country's national feed safety regulator enforces strict environmental performance benchmarks aligned with EU Green Deal incentives. Bergen and Trondheim harbor clusters anchor technical service team deployments from major additive producers targeting high-density marine operations.
Indonesia
Commercial shrimp farms across Java Sea clusters are rebuilding formulation standards around antibiotic-free regimes to satisfy tightening import market requirements. The national food and drug regulator maintains registration protocols for novel feed additives entering domestic compound feed mills. Surabaya and Makassar production zones now receive direct-to-farm distribution with pond-side technical support replacing traditional distributor intermediaries.
United States
FDA import alert protocols enforce veterinary drug residue screening at border entry points for crustacean and finfish products. Domestic catfish operations in the Mississippi Delta and Gulf Coast shrimp farms drive steady demand for vitamin premixes and amino acid formulations. Seattle and Boston metropolitan areas concentrate research institute validation programs requiring analytical-grade materials and batch documentation.
Brazil
Underpenetrated feed additive penetration in Latin American freshwater tilapia operations offers volume growth potential for enzyme and probiotic suppliers. The national health surveillance agency oversees feed safety registration timelines that parallel FDA and EFSA documentation requirements. São Paulo state and Paraná river basin production clusters are attracting technical service investments from multinational nutrition platforms seeking to replicate Vietnamese direct-to-farm distribution models.
Aquaculture Additives Market Key Industry Players
On the supply side, the industry is consolidating around integrated nutrition platforms with captive feed manufacturing capabilities and specialized biotechnology firms with proprietary strain libraries. Three archetypes dominate competitive positioning: multinational agribusiness conglomerates with aquaculture divisions, dedicated animal nutrition specialists with yeast or enzyme platforms, and regional compounders with localized blending services. Capacity expansion in Southeast Asian coastal zones and strategic partnerships for microencapsulation technology licensing represent the dominant competitive moves reshaping supplier qualification criteria.
Within the integrated nutrition tier, Cargill, Incorporated anchors volume leadership through localized blending facilities and direct-to-farm distribution networks. Among dedicated biotechnology specialists, Alltech exemplifies yeast-derived additive specialization while Evonik Industries AG occupies a precision formulation position in amino acid chemistry for high-density systems. These three entities represent distinct strategic postures: backward integration into raw material sourcing, microbial culture banking, and precision chemical engineering respectively.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Alltech |
| Evonik Industries AG |
| Kemin Industries |
| Nutreco N.V. |
| Archer Daniels Midland Company |
| DuPont de Nemours Inc. |
| BASF SE |
| BioMar Group A/S |
| Others |
Cost & Logistics Intelligence
Ho Chi Minh City's coastal blending facilities concentrate probiotic and immunostimulant production capacity, translating upstream fermentation scale into downstream pricing leverage for Vietnamese exporters serving EU-certified channels. This geographic clustering tightens margin structures for non-integrated compounders while rewarding captive supply networks with volume-tier procurement advantages.
Pricing Analysis
Certification level (EFSA-compliant vs. general-market) creates the primary spread between premium and standard additive tiers. Three-tier pricing structure across EU-certified, export-grade, and domestic-economy levels segments buyer archetypes, with feed manufacturers consolidating procurement at scale and aquaculture farms absorbing technical service premiums. Pricing pressure stems from fishmeal cost volatility transmitting through marine protein-dependent formulations, compressing premix margins. Small-scale Indonesian farms exhibit highest price sensitivity; Norwegian recirculating system operators demonstrate lowest sensitivity due to performance-linked ROI metrics.
Supply Chain Analysis
EU REACH registration requirements and FDA import alert protocols restrict novel additive molecule flows into European and North American retail channels. Production gravity centers on Vietnam, Indonesia, and Thailand for Southeast Asian export supply, with Norway and Chile anchoring Atlantic salmon additive demand. Raw material dependencies include yeast culture banks, amino acid precursors, and microencapsulation polymers. Single-source vulnerability concentrates in specialized Bacillus strain suppliers. Distribution runs through direct-to-farm technical service teams displacing traditional distributor intermediaries in Java Sea and Mekong Delta clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aquaculture additive platforms are consolidating around integrated nutrition ecosystems where formulation databases interoperate with pond-side diagnostic hardware, shifting value capture from product sales to performance-linked subscription models.
For Market Incumbents: Harden formulation IP positions through captive microbial strain banking and localized blending facility expansion in Vietnam's Mekong Delta. Consolidate technical service teams into pond-side diagnostic platforms to defend against biotechnology specialists with precision enzyme platforms. Prioritize EFSA pre-certification investment to lock EU channel access before REACH evaluation timelines extend.
For New Entrants and Emerging Players: Brazil's Paraná river basin tilapia operations offer underpenetrated feed additive penetration with limited incumbent technical service presence. Target hatchery liquid vitamin concentrates as the most penetrable application, where minimum-order flexibility and live feed enrichment expertise create differentiation. Pursue joint development agreements with regional compounders lacking in-house R&D capacity.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because residue limit tightening across EU and US import channels will consolidate procurement toward pre-certified additive platforms. Acquisition targets include regional compounders with localized blending infrastructure and existing EFSA/FDA documentation. Monitor EU F-Gas Regulation enforcement intensity as the signal for accelerated supply chain segregation into certified and general-market channels.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Fluid-bed coating systems preserve probiotic viability above 85°C extrusion thresholds for pelleted shrimp feeds. |
| Direct-to-Farm Distribution Expansion | Pond-side technical service teams in Indonesia's Java Sea clusters displace traditional distributor intermediaries. |
| EU Pre-Certification Investment | EFSA residue framework compliance secures preferential procurement status under Farm to Fork environmental benchmarks. |
| Recirculating System Microbial Consortia Development | Nitrifying bacterial inoculants address water quality modulation in Norwegian and Chilean closed-loop salmon facilities. |
| Regional Blending Facility Acquisition | Localized compounding capacity in Vietnam's coastal zones captures Mekong Delta intensive pond system demand. |
Research Approach
The analysis maps immunostimulant, probiotic, enzyme, and vitamin additive sub-sectors, each validated through feed mill procurement managers, aquaculture farm operations directors, and regulatory affairs specialists at export-oriented compounders. Primary interview findings triangulate against EFSA residue monitoring databases, FDA import alert records, Vietnamese customs export statistics, and EU Green Deal policy documentation. Bottom-up volume estimates from individual facility consumption patterns reconcile with top-down trade flow analysis.
Assumptions held fixed include current EU F-Gas Regulation residue limits and REACH registration timelines; varied parameters encompass antibiotic phase-out acceleration rates and recirculating aquaculture system adoption curves. The forecast framework segments by product chemistry, application species, end-user type, and physical delivery form, with CAGRs derived from facility expansion pipelines and stocking density trends. Modeled inputs include Peruvian anchovy catch forecasts and enzyme engineering patent filings.
Practitioners should monitor EU EFSA enforcement intensity and Indonesian national feed safety registration protocol changes for early signals of supply chain restructuring. Forecasts reflect assumptions about regulatory stability and commodity input costs that commodity price volatility or accelerated antibiotic restrictions could revise. Cross-checking against Vietnamese export certification database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
Thailand Aquafeed Market
Aquaculture Innovations
Kuwait Fisheries and Aquaculture Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Qatar Fisheries and Aquaculture Market
Aquaculture Innovations
Marine Life Raft Market
Aquaculture Innovations
Global Aquaculture Vaccine Market
Aquaculture Innovations
United States Ornamental Fish Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
Saudi Arabia Aquaculture Market