
 APAC Aquafeed Market | 2026-2036
APAC Aquafeed Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Aquafeed Market Insights
Precision fermentation and single-cell protein production is reconfiguring ingredient sourcing across the aquafeed value chain. Charoen Pokphand Foods PCL leverages its integrated poultry-aquafeed platform to control raw material costs across Thailand and Vietnam. Tongwei Group Co., Ltd. anchors the China market through massive compound feed capacity co-located with its aquaculture operations. Guangdong HAID Group Co., Ltd. differentiates via R&D intensity in functional additives targeting gut health in marine species.
Aquafeed denotes formulated nutritional products designed for aquatic organisms, typically comprising 25-45% crude protein, lipid profiles adjusted for species-specific metabolism, and binders ensuring pellet stability in water for 2-6 hours. Its primary commercial purpose is to convert feed inputs into harvestable biomass at optimized feed conversion ratios in intensive and semi-intensive production systems. Fish feed occupies the dominant volume position across the region, though shrimp feed commands premium pricing due to higher protein specifications and specialized additive requirements. Plant-based ingredients are displacing fish meal in grower diets as price volatility and sustainability certification pressures intensify, while additives represent the fastest-expanding margin pool as producers seek disease resistance and growth enhancement.
China's SAMR enforces GB standards on feed hygiene and additive approvals, while Indonesia's national food and drug regulator mandates registration for imported premixes entering PT Japfa Comfeed Indonesia Tbk's supply chain. Vietnam's Ministry of Agriculture and Rural Development imposes antibiotic residue testing that shapes export-oriented farm feed choices. Stakeholders must monitor how evolving mycotoxin regulations and carbon accounting frameworks for deforestation-linked soy and palm ingredients will reshape sourcing strategies and supplier qualification criteria.
Market Dynamics
Precision fermentation and single-cell protein production are reconfiguring ingredient sourcing economics across the aquafeed value chain, compressing reliance on marine-derived inputs while tightening supplier qualification criteria around carbon accounting and deforestation traceability.
Growth Catalysts
- GB Standards Revision:SAMR's tightened mycotoxin limits and traceability mandates under China's feed safety framework are accelerating formalization of feed procurement channels, pushing smaller mills toward certified supply partnerships.
- Shrimp Farming Intensification:Specialized high-protein feed demand from Southeast Asian intensive pond operations is expanding the premium additive segment, with Vietnam's Mekong Delta clusters driving bulk volume procurement.
- Plant Protein Processing:Extruded soybean and pea protein concentrate technologies are achieving amino acid profiles competitive with fish meal in grower diets, enabling cost stabilization for pangasius and tilapia producers.
Market Restraints
- Fish Meal Price Volatility:Peruvian anchovy quota fluctuations and El Niño disruption patterns transmit directly into shrimp feed cost structures, compressing margins for producers locked into fixed-price grower contracts.
- Soy Sourcing Concentration:Deforestation-linked supply scrutiny from EU import regulations and emerging carbon border mechanisms is forcing costly supplier requalification across Brazilian and Argentinian soy import channels.
- Antibiotic Residue Testing:Vietnam's Ministry of Agriculture and Rural Development export-oriented testing protocols create compliance friction for unregistered premix suppliers, delaying feed formulation adjustments.
Strategic Opportunities
- Indonesia's Archipelago Expansion:Underdeveloped marine cage culture zones across Eastern Indonesia present white-space demand for floating feed formulations adapted to high-salinity, high-current conditions.
- Functional Additive Premiumization:Gut health and disease resistance formulations targeting marine finfish represent margin expansion potential as RAS and offshore cage systems proliferate in South Korea and Japan.
- Integrated Poultry-Aquafeed Platforms:Shared raw material procurement and extrusion infrastructure across species is capturing logistics efficiencies in Thailand and Vietnam, lowering per-ton overhead for multi-species feed groups.
Industry Challenges
- Formulation Talent Scarcity:Shortage of aquatic nutrition specialists capable of balancing species-specific amino acid requirements with volatile ingredient cost curves is constraining R&D throughput at mid-scale mills.
- Certification Timeline Compression:ASC and BAP feed mill certification cycles averaging 14-18 months are misaligned with shrimp farm expansion timelines in Vietnam and Indonesia, creating supply qualification bottlenecks.
- Legacy System Integration:ERP and traceability software deployment across family-owned mill operations faces resistance from established procurement workflows, delaying real-time inventory optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Aquafeed Market |
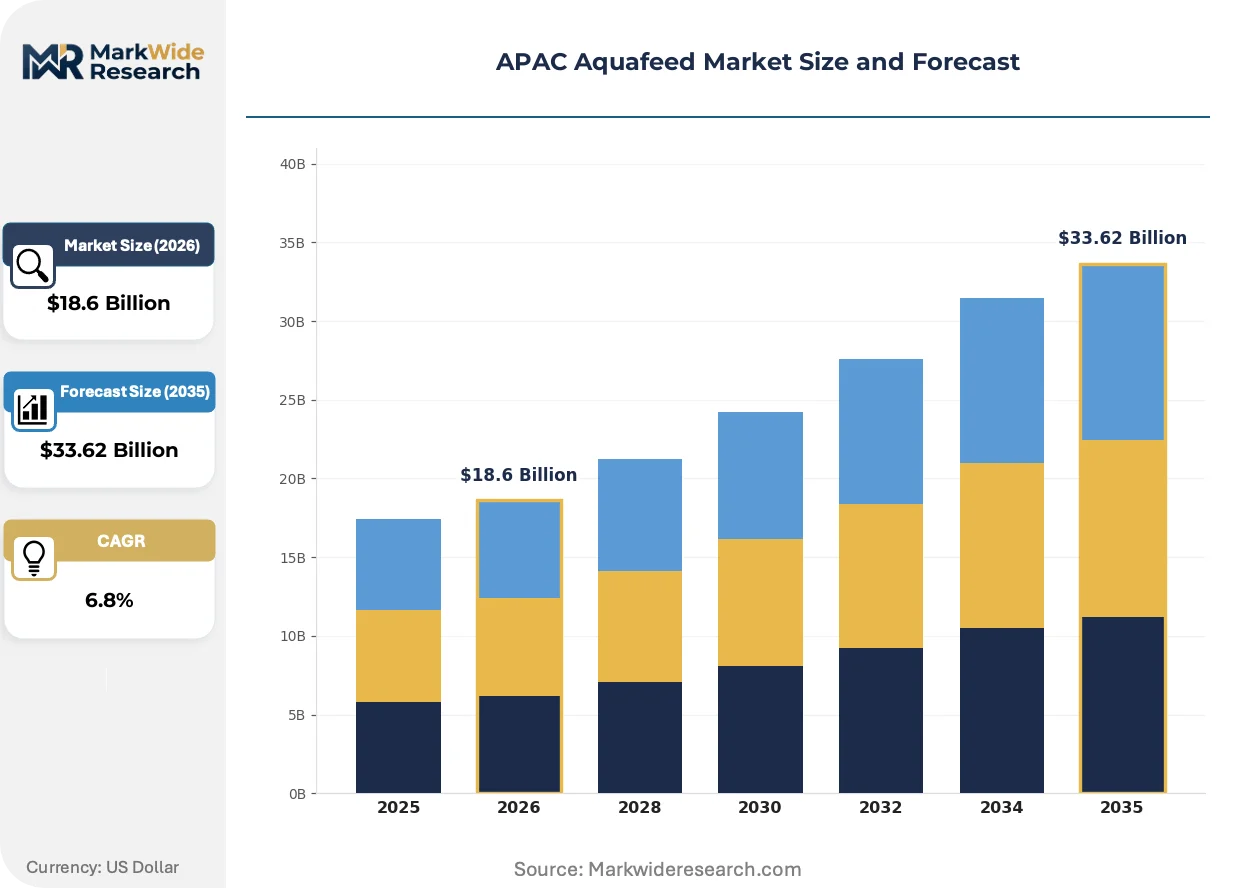
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Feed, Shrimp Feed, Mollusk Feed, Crustacean Feed Ingredient: Plant-Based, Fish Meal, Animal By-Products, Additives Distribution Channel: Online Retail, Direct Sales, Distributors, Mixers End User: Fish Farms, Aquaculture, Research Institutes, Hatcheries |
| Companies Covered | Charoen Pokphand Foods PCL, Tongwei Group Co., Ltd., Guangdong HAID Group Co., Ltd., Cargill, Inc., PT Japfa Comfeed Indonesia Tbk, Nutreco N.V., Biomar A/S, AllerAqua A/S, Avanti Feeds Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Aquafeed Market Trends and Innovations
Digital feed management systems and alternative protein platforms are converging to reshape production economics, with regulatory pressure on ingredient traceability accelerating technology adoption timelines across the value chain.
Sensor-equipped automated feeding systems are digitizing daily ration allocation across intensive shrimp pond operations. Thai and Vietnamese producers deploying acoustic and optical biomass monitoring are reducing feed conversion ratios by enabling real-time adjustment protocols. This precision hardware layer is digitizing the grower-feed supplier interface, generating demand for data-integrated formulation services that link pond-side metrics to mill production scheduling.
China's SAMR enforcement of revised GB standards on feed hygiene and additive approvals is tightening registration requirements for imported premix categories. Industrial consequence includes accelerated domestic substitution of foreign-sourced vitamin and mineral premixes as registration timelines extend. Shrimp feed producers targeting EU and US export markets are responding by dual-sourcing critical additives to maintain formulation flexibility under evolving compliance windows.
Integrated mill-farm procurement contracts are displacing spot-market ingredient purchasing across Vietnam's Mekong Delta clusters. Large pangasius and shrimp operations are consolidating feed supply relationships around volume-commitment structures that transfer price risk to mill operators. This contract densification is most visible in An Giang and Dong Thap provinces, where processor-backed farming groups are securing multi-year feed supply agreements to stabilize export cost structures.
APAC Aquafeed Market Segmentation
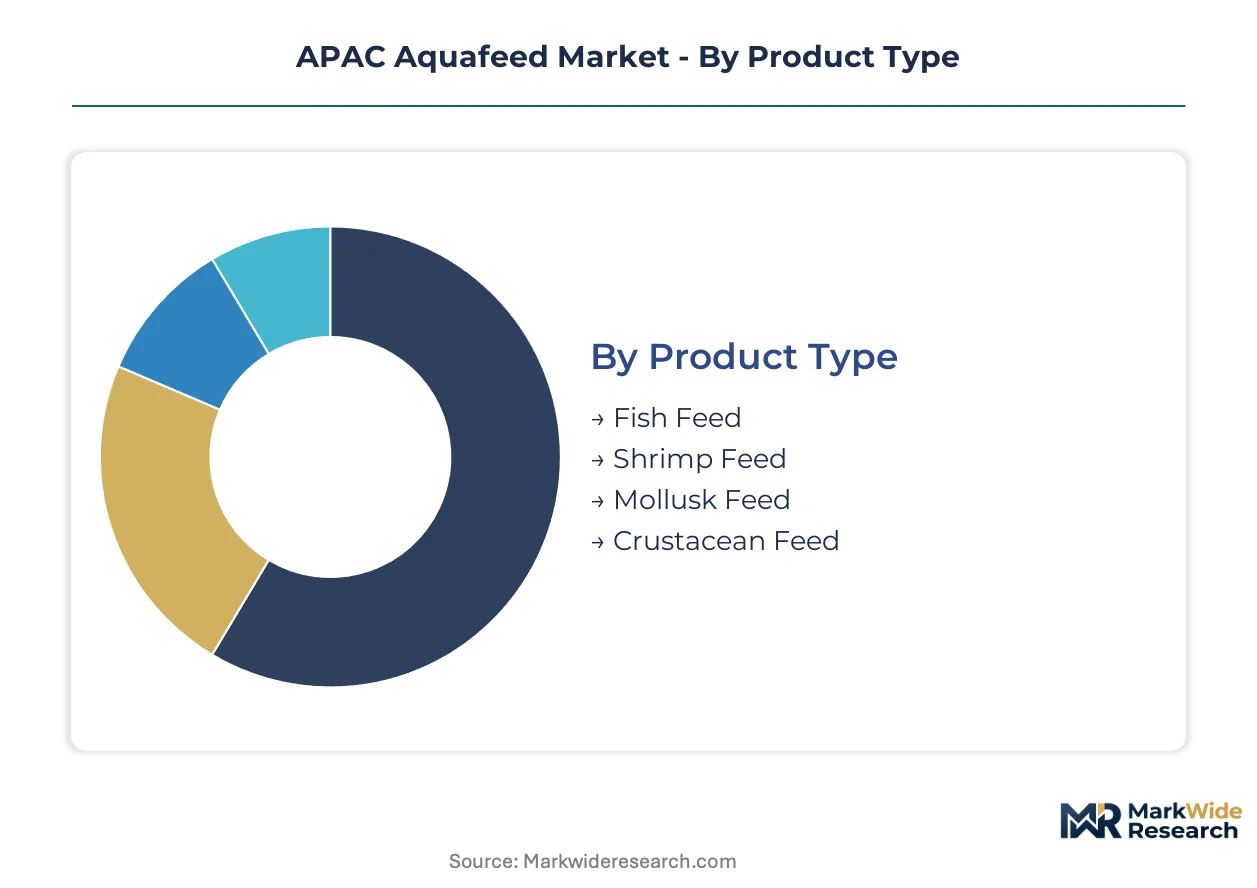
Aquafeed segmentation in APAC reflects divergent production cycles across species and procurement patterns shaped by farm scale. Understanding these divides clarifies where formulation investments concentrate versus where commoditization pressures dominate.
Product Type:
Cycle times stretch from rapid-turnover grower feeds to multi-phase broodstock formulations, with shrimp operations demanding the most frequent ration adjustments.
- Fish Feed:Formulations for tilapia, pangasius, and marine finfish comprise 25-35% crude protein with lipid profiles calibrated for water temperature regimes. Vietnam's Mekong Delta clusters absorb bulk volumes for intensive pangasius cages, though margin compression from soybean price volatility constrains producer flexibility.
- Shrimp Feed:High-protein specifications (35-45%) with specialized amino acid balancing and gut health additives command premium positioning. Intensive pond operations across Thailand's eastern seaboard and Vietnam's Ca Mau province drive procurement of phase-specific starter, grower, and finisher diets.
- Mollusk Feed:Microalgae and diatom-based formulations for oyster and mussel suspension culture in China's Fujian and Shandong provinces.
- Crustacean Feed:Specialized diets for crab and crayfish farming in South Korea's western coastal zones and Japan's Kyushu region.
Fish Feed dominates installed base. Shrimp Feed is where expansion concentrates.
Ingredient:
Cost tier stratification separates commodity proteins from functional inputs that protect margins through performance claims.
- Plant-Based:Extruded soybean meal, pea protein concentrate, and fermented grain by-products now constitute 40-60% of grower diet formulations. Thailand's Charoen Pokphand Foods PCL and Vietnam's feed groups are securing long-term offtake agreements with Brazilian crushers to deflect deforestation-linked supply scrutiny.
- Fish Meal:Peruvian anchovy-derived inputs retain irreplaceable amino acid profiles for larval and broodstock diets despite price volatility. El Niño disruption patterns transmit directly into shrimp hatchery cost structures.
- Animal By-Products:Poultry meal and blood meal from integrated poultry-aquafeed platforms in Thailand and Indonesia.
- Additives:Probiotics, enzymes, and pigmenting carotenoids represent the steepest expansion trajectory as producers seek disease resistance and flesh color premiums for export certification.
Plant-Based inputs anchor volume consumption. Additives is where margin expansion concentrates.
Distribution Channel:
Customer scale determines channel selection, with large integrated operations bypassing intermediaries while fragmented smallholders depend on local distribution density.
- Direct Sales:Mill-to-farm contracts with volume-commitment structures predominate across Vietnam's processor-backed farming groups in An Giang and Dong Thap provinces.
- Distributors:Provincial feed dealers with credit extension capabilities serve smallholder tilapia and catfish producers in Indonesia's Java and Sumatra.
- Mixers:On-farm or cooperative blending of base mixes with local ingredients persists in Bangladesh and Myanmar where formal feed penetration remains incomplete.
- Online Retail:E-commerce platforms for specialty additives and small-batch starter feeds in South Korea and Japan's precision aquaculture segments.
Direct Sales commands the largest contract value. Distributors retain the deepest smallholder penetration.
End User:
Application maturity separates intensive commercial operations from experimental and breeding facilities with specialized formulation requirements.
- Fish Farms:Intensive cage and pond operations across China's Guangdong and Hainan provinces consume formulated feeds at scale, with Tongwei Group's integrated mill-farm complexes setting procurement benchmarks.
- Aquaculture:Diverse production systems including marine net pens, RAS facilities, and integrated multi-trophic aquaculture in Japan and South Korea.
- Hatcheries:Larval nutrition with live feed substitution protocols and microencapsulated diets for shrimp and marine finfish seed production.
- Research Institutes:Experimental formulations for selective breeding programs and novel species domestication trials.
Fish Farms represent the largest volume absorption. Aquaculture is where system diversification and premium feed adoption concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed procurement concentrates around three buyer archetypes: integrated aquaculture conglomerates securing multi-year supply contracts, processor-backed farming groups in Vietnam's Mekong Delta, and fragmented smallholders dependent on provincial distributors with credit extension capabilities.
China
Tongwei Group's integrated mill-farm complexes in Sichuan and Guangdong provinces absorb massive compound feed volumes. SAMR's tightened GB standards on feed hygiene and additive approvals accelerate domestic substitution of foreign-sourced premixes. Yangtze River Delta clusters around Shanghai and Jiangsu drive premium additive demand for marine finfish cage culture.
Vietnam
Processor-backed farming groups in An Giang and Dong Thap provinces consolidate feed supply through volume-commitment contracts. The Ministry of Agriculture and Rural Development's antibiotic residue testing protocols shape export-oriented formulation choices. Ca Mau province's intensive shrimp pond operations drive phase-specific starter, grower, and finisher diet procurement at premium specifications.
Thailand
Charoen Pokphand Foods leverages its integrated poultry-aquafeed platform to control raw material costs across shared extrusion infrastructure. Eastern seaboard shrimp farming zones demand specialized high-protein feeds with gut health additives. Bangkok-based feed groups are securing long-term Brazilian soybean offtake agreements to deflect deforestation-linked supply scrutiny.
Indonesia
PT Japfa Comfeed Indonesia's supply chain faces registration mandates from the national food and drug regulator for imported premix categories. Java and Sumatra's smallholder tilapia producers depend on provincial distributors with credit extension capabilities. Eastern Indonesia's underdeveloped marine cage culture zones present white-space demand for floating feed formulations adapted to high-salinity conditions.
Japan
Precision aquaculture segments in Kyushu and western coastal zones adopt sensor-equipped automated feeding systems for real-time ration adjustment. METI-backed initiatives support RAS and offshore cage system proliferation driving functional additive premiumization. E-commerce platforms for specialty additives and small-batch starter feeds serve precision aquaculture operations in Kanto and Kansai regions.
APAC Aquafeed Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven integrated conglomerates anchor volume procurement while mid-scale mills serving fragmented smallholders face margin compression. The market fragments across three strategic archetypes: integrated aquaculture-feed conglomerates with captive demand, diversified agribusiness groups leveraging cross-species procurement platforms, and specialized shrimp feed producers commanding premium positioning through additive intensity. Dominant competitive moves include backward integration into raw material sourcing and capacity co-location with intensive farming clusters.
Within the integrated conglomerate tier, Charoen Pokphand Foods PCL and Tongwei Group Co., Ltd. exemplify channel-controlling archetypes that anchor regional procurement benchmarks. Guangdong HAID Group Co., Ltd. occupies a specialist position representing R&D-intensive formulation capabilities targeting functional additive segments. These three entities collectively illustrate the competitive spectrum from diversified agribusiness integration through aquaculture-specific technology differentiation.
| Leading Market Players |
|---|
| Charoen Pokphand Foods PCL |
| Tongwei Group Co., Ltd. |
| Guangdong HAID Group Co., Ltd. |
| Cargill, Inc. |
| PT Japfa Comfeed Indonesia Tbk |
| Nutreco N.V. |
| Biomar A/S |
| AllerAqua A/S |
| Avanti Feeds Ltd |
| Others |
Pricing and Supply Chain Analysis
El Niño-driven Peruvian anchovy quota volatility compresses margin spreads across shrimp feed tiers while simultaneously forcing supplier requalification toward Brazilian soy crushers with deforestation-free certification. This dual pressure mechanism widens the premium-to-economy feed price gap and accelerates contract densification around volume-commitment structures in Vietnam's Mekong Delta clusters.
Pricing Analysis
Cost-plus contracts indexed to Chicago soybean futures and Peruvian fish meal spot markets dominate procurement between Vietnamese processor-backed farming groups and Thai mill operators. Three-tier pricing structure across premium, standard, and economy levels separates ASC-certified additive-intensive formulations from commodity grower diets and unregistered base mixes. Pricing pressure stems from EU deforestation regulation compliance costs transmitting through Brazilian soy import channels. Smallholder tilapia producers in Indonesia's Java heartland exhibit highest price sensitivity, while Japan's precision aquaculture operations absorb premium functional additive pricing with minimal volume elasticity.
Supply Chain Analysis
Upstream feedstock procurement draws from Brazilian soybean crushing, Peruvian anchovy reduction, and Thai poultry rendering streams as primary protein anchors. Soybean meal, fish meal, and poultry by-product meal constitute the irreplaceable input trinity for high-performance shrimp and marine finfish formulations. Single-source vulnerability concentrates in Peruvian anchovy quotas where El Niño disruption patterns transmit direct cost shocks. Distribution runs through mill-to-farm direct contracts for integrated conglomerates, provincial dealer networks with credit extension for smallholders, and e-commerce platforms for precision aquaculture additives in developed East Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across species-specific formulation requirements and divergent certification standards creates multiple niche entry points as intensive aquaculture proliferates beyond traditional production belts. Demand-side shift toward export-oriented antibiotic-free production in Vietnam and Indonesia generates premium formulation whitespace absent from commoditized grower feed segments.
For Market Incumbents: Harden formulation talent retention through captive aquatic nutrition specialist pipelines as R&D throughput constraints emerge at mid-scale competitors. Deepen backward integration into Brazilian soy crushing assets with verified deforestation-free supply chains to deflect EU regulatory compliance cost transmission. Prioritize ASC and BAP feed mill certification pre-positioning ahead of Vietnamese and Indonesian farm expansion timelines to capture supply qualification bottlenecks. For New Entrants and Emerging Players: Establish a beachhead in Eastern Indonesia's underdeveloped marine cage culture zones where floating feed demand for high-salinity, high-current conditions remains unserved by incumbent Java-centric distribution networks. Target functional additive premiumization for Japan and South Korea's RAS and offshore cage proliferation as the most penetrable margin expansion segment. Deploy sensor-integrated formulation services linking pond-side biomass monitoring data to mill production scheduling as differentiated go-to-market architecture. For Investors and Strategic Acquirers: Mid-scale mills with established provincial distributor relationships and latent extrusion capacity represent the optimal acquisition target archetype for consolidation plays. Long-term viability hinges on feed producers' capacity to substitute marine-derived inputs with precision fermentation and single-cell protein platforms over the coming decade. Watch for inflection in domestic premix substitution rates under China's SAMR registration timeline extensions as signal of additive supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Verified Soy Supply | Captures deforestation-free certification premiums ahead of EU carbon border mechanism activation. |
| Sensor-Integrated Formulation Services | Links Charoen Pokphand Foods' pond-side biomass data to real-time mill production scheduling optimization. |
| Functional Additive R&D Partnerships | Secures gut health and disease resistance IP for premium marine finfish diets in Japan's RAS expansion zones. |
| Multi-Year Volume Commitment Contracts | Transfers price risk from Vietnam's processor-backed farming groups to mill operators in Mekong Delta clusters. |
| Certification Pre-Positioning Investment | Accelerates ASC and BAP feed mill qualification timelines ahead of Indonesian archipelago cage culture rollout. |
Research Methodology
The analysis maps fish feed, shrimp feed, mollusk feed, and crustacean feed sub-sectors, each validated through mill operations directors, aquatic nutrition formulators, procurement leads at integrated aquaculture conglomerates, and provincial distributor network managers. Primary interview intelligence triangulates against customs trade data for soybean and fish meal imports, SAMR and Vietnam Ministry of Agriculture regulatory filings, and compound feed production statistics from national agricultural bureaus. Bottom-up volume modeling across species-specific feed conversion ratios and top-down value estimation from input cost structures converge to establish market sizing envelopes.
Assumption-sets held Brazilian soy price volatility and Peruvian anchovy quota stability as fixed boundary conditions while varying intensive aquaculture expansion rates and additive penetration trajectories across the projection horizon. Segmentation dimensions modeled include product type, ingredient category, distribution channel, and end-user application maturity. CAGRs derive from historical feed production growth rates adjusted for species mix shifts and regulatory compliance cost absorption patterns. Industry-specific forecast inputs incorporate shrimp farming intensification indices and RAS facility commissioning timelines in South Korea and Japan.
Stress conditions across El Niño disruption frequency, EU deforestation regulation enforcement stringency, and SAMR premix registration timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on protein substitution elasticities and certification adoption curves. Quarterly review of Peruvian anchovy quota announcements, Brazilian soy export price movements, and Vietnamese antibiotic residue testing protocol amendments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
Clams, Cockles, Ark Shells Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Norway Aquaculture Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Brazil Fisheries and Aquaculture Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Marine Life Raft Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
Crab Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Aquaculture Market