
 Aquaculture Water Quality and Biomass Monitoring Test Equipment Market | 2026-2036
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market Insights
The capability gap between integrated sensor platform developers and component assemblers is unwinding as capital requirements for optical and ultrasonic R&D escalate. Xylem leverages its vertical integration across electrochemical and optical sensing modules to sustain pricing power in multiparameter probe deployments. Hach competes through dense channel control in North American environmental compliance testing, while Endress+Hauser anchors its position with process-automation expertise borrowed from chemical and pharmaceutical verticals.
Aquaculture water quality and biomass monitoring test equipment encompasses electrochemical, optical, ultrasonic, fluorescence, and infrared sensor systems engineered to measure dissolved oxygen, turbidity, chlorophyll-a, and biomass density in aqueous culture environments, typically operating at depths from surface to thirty meters with real-time telemetry to shore-based control systems. The primary commercial purpose is to prevent anoxic events, optimize feed conversion ratios, and ensure regulatory compliance in intensive fish and shellfish production. Multiparameter probes and dissolved oxygen sensors occupy the mature volume tier where price competition compresses margins, while biomass scanners and fluorescence-based optical systems represent the fastest-expanding margin pool as operators shift from reactive water testing to predictive biomass management. Spectrophotometer demand concentrates in research institutes and quality inspector workflows where laboratory-grade precision justifies premium positioning.
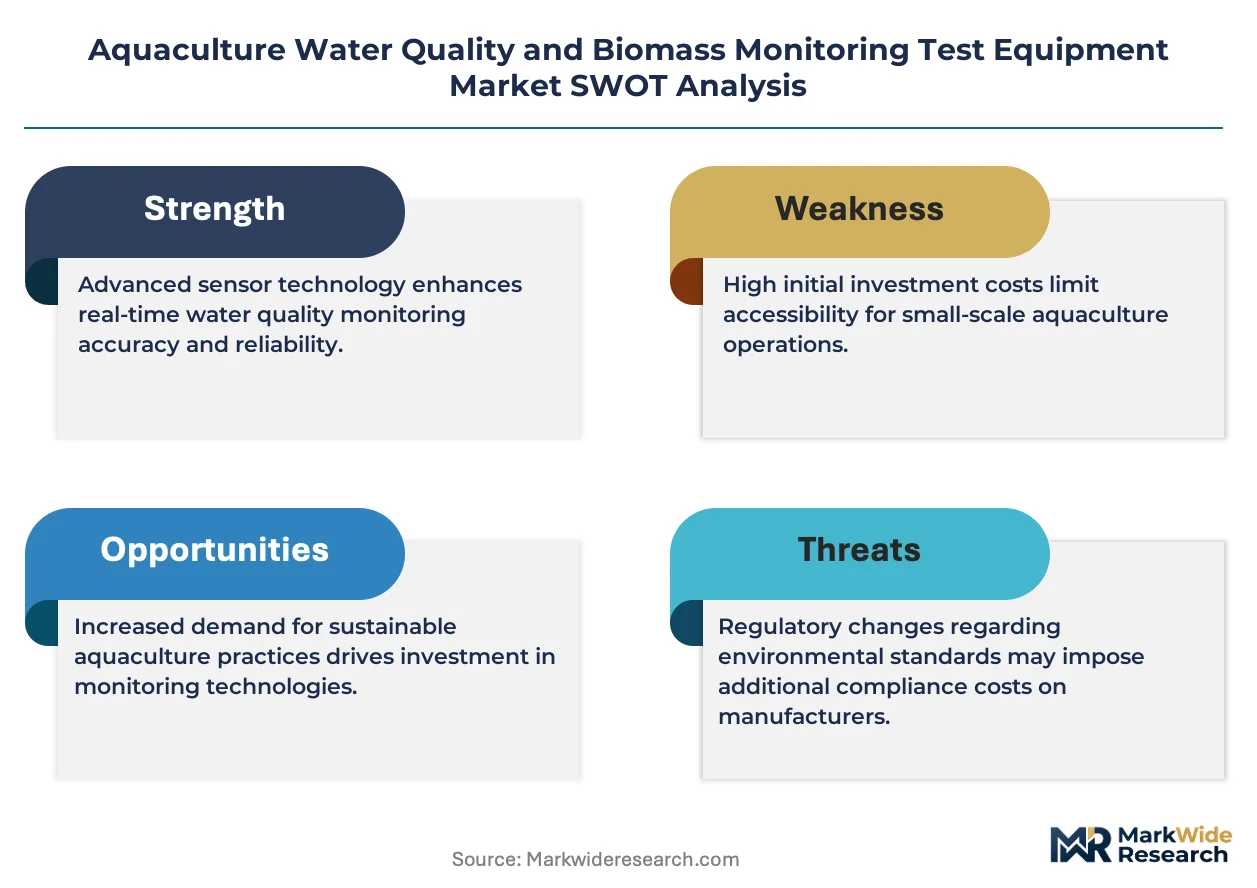
EPA effluent guidelines and EU Water Framework Directive standards shape product specifications by mandating continuous monitoring of nitrogen, phosphorus, and dissolved oxygen discharge from intensive aquaculture facilities, effectively filtering market access to equipment certified for regulatory-grade accuracy. ISO 17025 calibration protocols and NMPA registration requirements in China add compliance layers that favor established metrology vendors with in-house certification infrastructure. Stakeholders must weigh the trade-off between proprietary sensor ecosystems and open-platform interoperability as feed producers and environmental agencies press for unified data standards across multi-site operations.
Market Dynamics
Intensive salmon and shrimp producers are consolidating operations into fewer, larger sites, concentrating demand for integrated monitoring platforms that unify water quality and biomass data into single dashboards. This operational consolidation is compressing vendor margins on standalone sensors while expanding contract values for full-stack system integrators.
Growth Catalysts
- EPA effluent guidelines:Mandates for continuous nitrogen and phosphorus discharge monitoring from intensive aquaculture facilities are compelling farm operators to upgrade from manual sampling to automated sensor networks.
- Fluorescence-based optical systems:Real-time chlorophyll-a and algae bloom detection capabilities are displacing laboratory-based water testing workflows in Vietnamese and Indonesian coastal pond clusters.
- Norwegian salmon operators:Accelerating adoption of ultrasonic biomass scanners is creating pull-through demand for complementary dissolved oxygen and turbidity probes from the same vendor ecosystems.
Market Restraints
- Optical component supply concentration:Precision photodiodes and interference filters for fluorescence sensors concentrate among German and Japanese specialty optics suppliers, exposing assemblers to lead-time volatility.
- Capital intensity of calibration infrastructure:ISO 17025-certified reference laboratories require seven-figure investments in traceable standard solutions and environmental chambers, filtering market access.
- Technical limitation of biofouling:Electrochemical dissolved oxygen sensors suffer drift rates of 2-5% weekly in high-organic-load shrimp ponds, forcing frequent manual cleaning or expensive antifouling coatings.
Strategic Opportunities
- Ecuadorian shrimp corridor:Underpenetrated automated monitoring in extensive pond systems presents white-space demand for solar-powered telemetry platforms with simplified installation protocols.
- EU Water Framework Directive alignment:Cross-border data standardization mandates are creating openings for cloud-native platforms that aggregate multi-site compliance reporting across Norwegian, Scottish, and Irish salmon operations.
- AI-driven predictive feeding:Convergence of biomass scanner data with machine learning models for feed conversion optimization is opening subscription revenue streams beyond hardware sales.
Industry Challenges
- Multidisciplinary field engineering:Deployment of integrated sensor platforms requires technicians fluent in electrochemistry, marine biology, and industrial networking protocols, creating acute talent scarcity in Vietnam and Indonesia.
- Legacy SCADA integration:Proprietary communication protocols from incumbent pond aeration controllers complicate data aggregation into modern IoT architectures, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquaculture Water Quality and Biomass Monitoring Test Equipment Market |
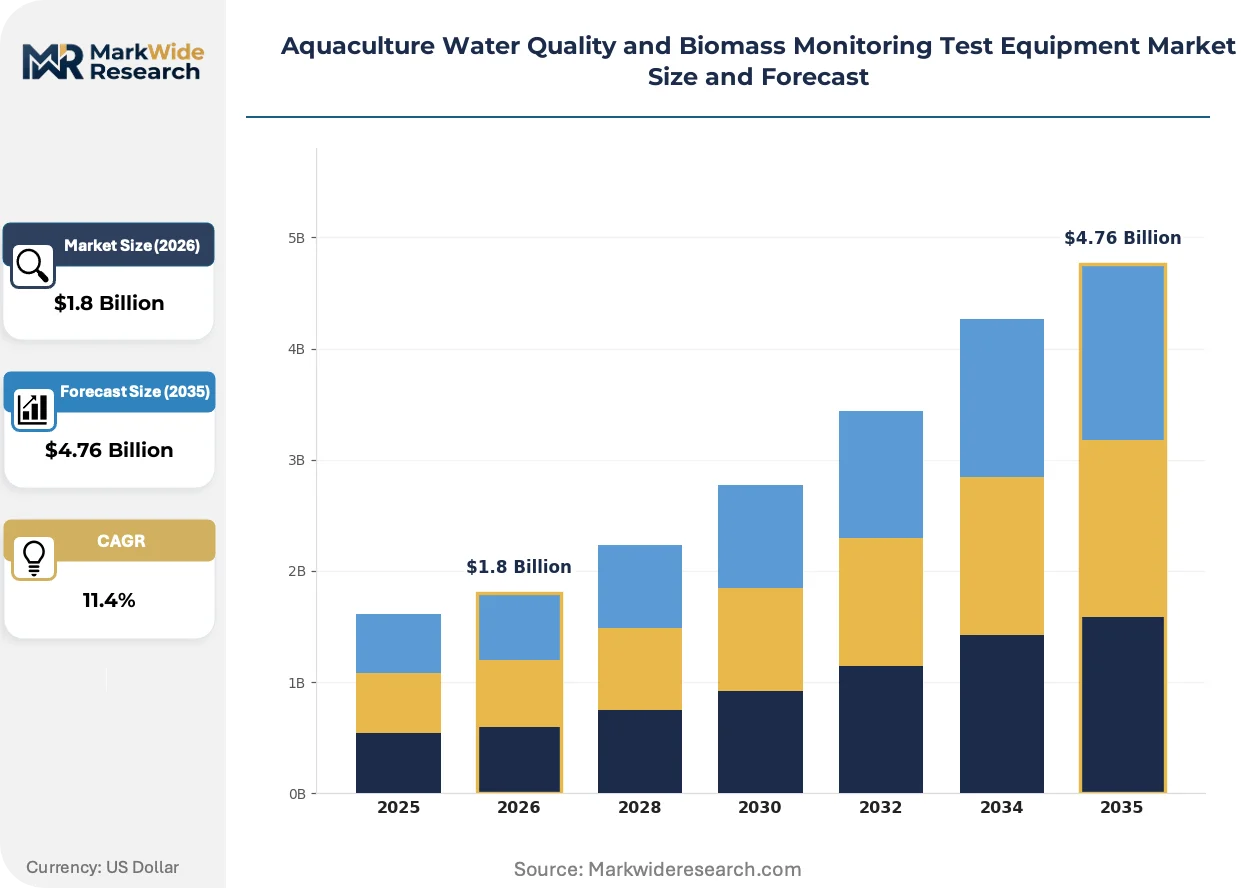
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multiparameter Probes, Spectrophotometers, Biomass Scanners, Turbidity Meters, Dissolved Oxygen Sensors Technology: Electrochemical, Optical, Ultrasonic, Fluorescence, Infrared Application: Fish Farms, Shrimp Ponds, Hatcheries, Recirculating Systems, Sea Cages End User: Aquaculture Operators, Research Institutes, Environmental Agencies, Feed Producers, Quality Inspectors |
| Companies Covered | Xylem, Hach, Hanna Instruments, Thermo Fisher Scientific, Horiba, Endress+Hauser, Yokogawa Electric, AKVA group, Innovasea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market Trends and Innovations
Sensor architecture is splitting between high-precision laboratory-grade systems and ruggedized field-deployable platforms, with the gap widening as optical miniaturization accelerates. This technological divergence is reshaping vendor specialization and buyer procurement patterns simultaneously.
Multiparameter probe technology is bifurcating into two distinct performance tiers. Research institutes and quality inspectors in Norway and Scotland demand laboratory-grade spectrophotometers with 0.1% accuracy for regulatory dispute resolution. Coastal shrimp operators in Vietnam and Ecuador are adopting simplified electrochemical arrays that trade precision for durability and solar autonomy. This split is compressing mid-tier positioning and forcing vendors to choose between metrology certification investments or cost-engineered volume manufacturing.
REACH substance restrictions and RoHS amendments are tightening constraints on heavy-metal electrodes in electrochemical dissolved oxygen sensors. Manufacturers are accelerating migration to gold-nickel alloy and optical alternatives that eliminate mercury and lead components. European salmon equipment suppliers face compressed redesign timelines to maintain CE marking validity, while Asian assemblers serving domestic markets encounter delayed compliance pressure through export certification requirements.
Service contracting is displacing transactional equipment sales among large Norwegian and Chilean salmon integrators. Operators now demand uptime guarantees and predictive maintenance subscriptions bundled with hardware, transferring sensor calibration and replacement risk to vendors. This shift concentrates procurement authority with platform vendors possessing regional service infrastructure, marginalizing component assemblers lacking field engineering depth.
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market Segmentation
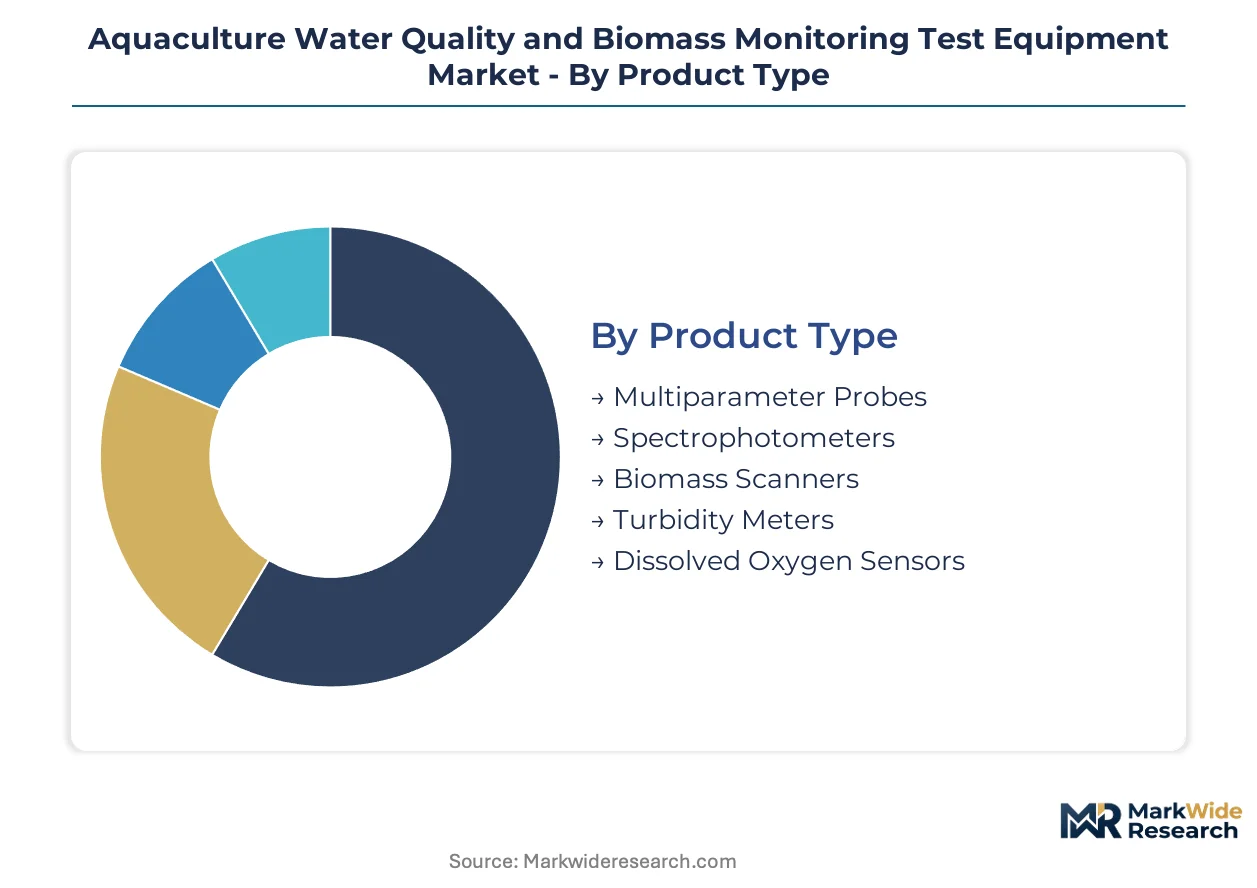
Equipment procurement patterns in aquaculture monitoring diverge sharply between integrated platform vendors and standalone component suppliers. Channel strategy—direct sales for large salmon integrators versus distributor networks for shrimp pond clusters—shapes which segments capture margin and which face commoditization pressure.
Product Type:
Channel concentration varies dramatically: multiparameter probes and dissolved oxygen sensors flow through agricultural equipment distributors serving Vietnamese and Indonesian pond clusters, while biomass scanners and spectrophotometers move through direct vendor relationships with Norwegian and Scottish salmon operators.
- Multiparameter Probes:Electrochemical and optical sensing modules integrated into single housings measuring dissolved oxygen, pH, temperature, and conductivity simultaneously. Norwegian salmon farmers deploy these as anchor nodes in site-wide sensor networks, driven by EPA and EU Water Framework Directive compliance mandates for continuous discharge monitoring.
- Biomass Scanners:Ultrasonic and stereo-vision systems quantifying fish size distribution and total biomass density in sea cages and ponds. Chilean and Norwegian operators are consolidating procurement of these systems with complementary water quality probes from identical vendor ecosystems, creating bundled contract expansion.
- Spectrophotometers:Laboratory-grade optical instruments for precise chlorophyll-a and nutrient analysis in regulatory dispute resolution workflows.
- Turbidity Meters:Nephelometric sensors tracking suspended solids in high-exchange recirculating systems and coastal shrimp ponds.
- Dissolved Oxygen Sensors:Galvanic and optical variants dominating unit volume but facing margin compression from Asian component assemblers.
Multiparameter probes dominate installed base across intensive operations. Biomass scanners are where expansion concentrates as operators shift from reactive water testing to predictive biomass management.
Technology:
Cost tier stratification separates precision instrumentation from field-ruggedized alternatives: electrochemical and infrared technologies occupy economy positioning, while fluorescence and advanced optical systems command premium pricing in regulatory-grade deployments.
- Electrochemical:Mature sensing paradigm using membrane-covered electrodes for dissolved oxygen and ion-selective probes for pH/ammonia. Vietnamese and Ecuadorian shrimp producers accept higher maintenance burdens and drift rates in exchange for lower capital outlay and simplified field replacement protocols.
- Fluorescence:Optical detection of chlorophyll-a, phycocyanin, and dissolved organic matter through excitation-emission matrices. Indonesian and Vietnamese coastal clusters are displacing laboratory workflows with real-time algae bloom detection, driven by intensifying disease pressure from harmful algal events.
- Optical:Absorbance and scattering-based measurements for turbidity and suspended solids in process control applications.
- Ultrasonic:Acoustic biomass estimation and bubble-free oxygen transfer monitoring in deep sea cages.
- Infrared:Non-dispersive absorption for CO2 and hydrocarbon detection in recirculating aquaculture system gas exchange monitoring.
Electrochemical technologies anchor volume shipments across price-sensitive pond operations. Fluorescence methods are gaining share fastest as coastal producers prioritize early-warning capabilities over capital cost minimization.
Application:
Customer type determines procurement authority concentration: fish farms and sea cages centralize capital equipment decisions with operations directors, while shrimp ponds and hatcheries fragment purchasing across numerous smallholder operators.
- Fish Farms:Land-based tank and pond systems for salmonids, tilapia, and catfish requiring continuous water quality surveillance. Norwegian operators are consolidating fewer, larger sites and demanding unified dashboards integrating biomass and environmental data, compressing standalone sensor margins while expanding system integrator contract values.
- Sea Cages:Open-water net pen installations for Atlantic salmon and rainbow trout in fjord and coastal environments. Scottish and Irish operators face EU Water Framework Directive cross-border data standardization mandates, creating openings for cloud-native platforms aggregating multi-site compliance reporting.
- Shrimp Ponds:Extensive and semi-intensive coastal production systems across Vietnam, Indonesia, and Ecuador.
- Hatcheries:Controlled-environment larval rearing facilities with ultra-precise temperature and oxygen requirements.
- Recirculating Systems:Closed-loop RAS installations with intensive biofiltration and oxygen injection subsystems.
Fish farms anchor current revenue concentration in mature markets. Sea cages are where technology substitution accelerates as open-water monitoring complexity outpaces legacy sensor capabilities.
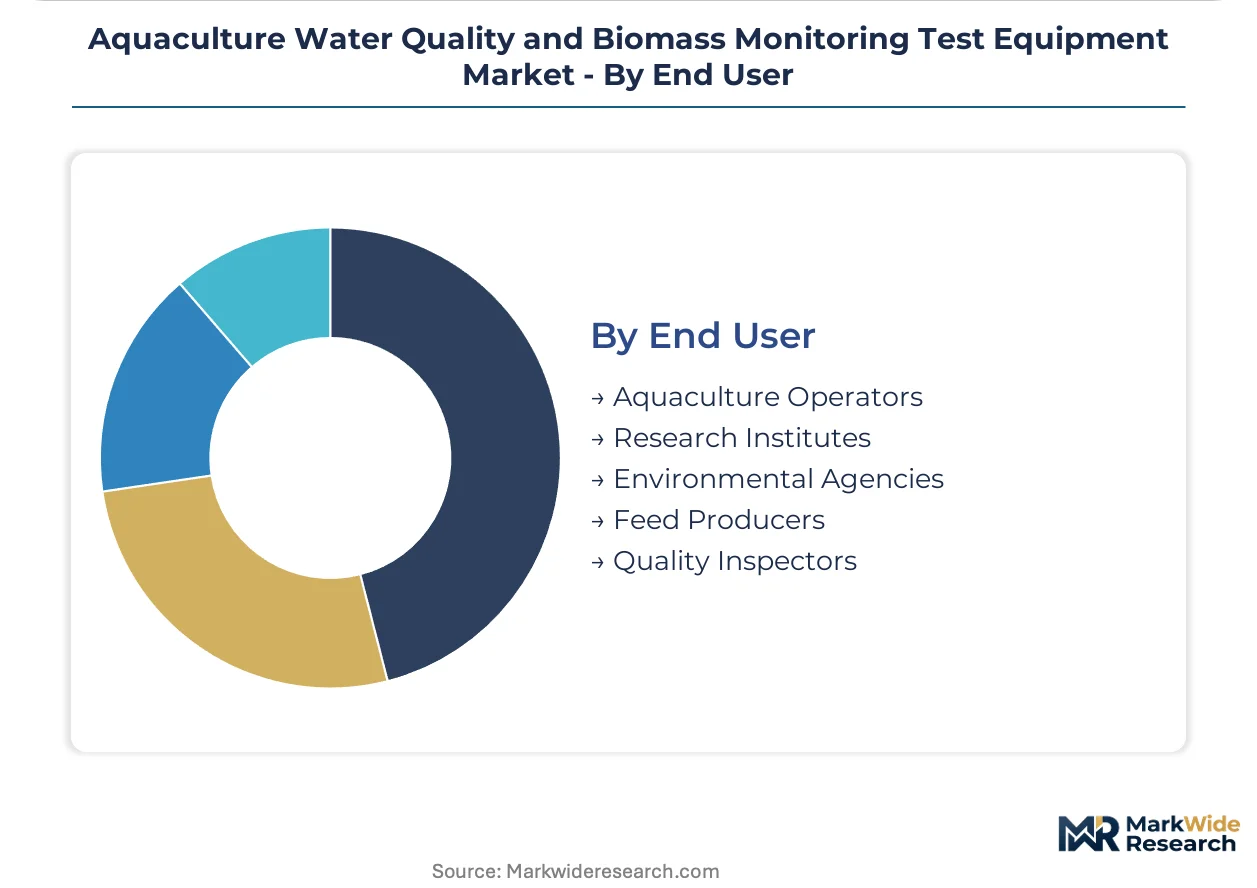
End User:
Volume scale separates procurement patterns: aquaculture operators and feed producers drive large-platform deployments, while research institutes and quality inspectors sustain low-volume, high-margin spectrophotometer demand.
- Aquaculture Operators:Farm owners and managers directly deploying monitoring infrastructure for production optimization and regulatory compliance. Large Norwegian and Chilean salmon integrators are shifting from transactional equipment purchases to service contracts bundling uptime guarantees and predictive maintenance, transferring calibration and replacement risk to vendors.
- Environmental Agencies:Governmental and quasi-governmental bodies conducting watershed-scale discharge monitoring and enforcement. EPA effluent guidelines for intensive aquaculture facilities are compelling upgrades from manual sampling to automated networks, filtering market access to regulatory-grade accuracy certification.
- Research Institutes:University and government laboratories requiring traceable metrology for method development and dispute resolution.
- Feed Producers:Aquafeed manufacturers optimizing formulation through growth trial monitoring and customer technical support.
- Quality Inspectors:Third-party certification and export compliance testing laboratories.
Aquaculture operators dominate hardware shipment volumes. Environmental agencies are where specification authority concentrates as regulatory stringency tightens certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnamese and Ecuadorian shrimp ponds demand sub-$500 electrochemical sensors with solar autonomy, while Norwegian and Scottish salmon operators pay 15-20x premiums for integrated biomass-water quality platforms with predictive analytics dashboards.
Norway
Salmon integrators are consolidating into fewer, larger sea-cage sites that demand unified monitoring dashboards. EU Water Framework Directive cross-border data standardization mandates are compelling upgrades to cloud-native compliance platforms. Bergen and Trondheim clusters anchor ultrasonic biomass scanner deployment alongside dissolved oxygen probe networks.
Vietnam
Coastal pond clusters in the Mekong Delta are displacing laboratory water testing with real-time fluorescence sensors for algae bloom detection. Domestic environmental regulations on effluent discharge are tightening enforcement timelines for intensive shrimp operations. Can Tho and Bac Lieu provinces concentrate solar-powered telemetry platform adoption among smallholder cooperatives.
Chile
Salmon producers are bundling biomass scanner procurement with complementary water quality probes from identical vendor ecosystems. EPA-aligned export certification requirements are filtering market access to regulatory-grade accuracy equipment. Puerto Montt and Chiloé Island anchor the fastest-expanding automated sensor network installations in South American aquaculture.
Indonesia
Shrimp pond operators in Java and Sulawesi are accelerating fluorescence-based optical system adoption driven by intensifying disease pressure from harmful algal events. National standards for coastal aquaculture effluent monitoring are pending finalization by the country's environmental ministry. Sidoarjo and Pinrang regencies concentrate demand for simplified electrochemical arrays trading precision for field durability.
United States
Recirculating aquaculture system operators are deploying multiparameter probe networks for intensive biofiltration control. EPA effluent guidelines for concentrated aquatic animal production facilities mandate continuous nitrogen and phosphorus discharge monitoring. Maine and Washington State anchor regulatory-grade sensor deployment among land-based salmonid producers.
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium integrated platforms coexist with commoditized component supply. The market splits between full-stack system integrators commanding service-contract pricing power and standalone sensor assemblers facing margin compression. Three archetypes dominate: vertically integrated metrology conglomerates with in-house certification infrastructure, regional channel specialists controlling distributor relationships, and optical component assemblers dependent on German and Japanese specialty suppliers. Consolidation pressure is intensifying through bundled procurement contracts and predictive maintenance subscription models that transfer operational risk to vendors.
Within the integrated platform tier, Xylem and Endress+Hauser represent archetypes of vertical control over electrochemical and optical sensing modules. Hach occupies a distinct position anchored in North American environmental compliance testing density. These three entities exemplify how regional service infrastructure depth and in-house metrology certification capabilities are becoming the decisive barriers to procurement authority among large salmon integrators shifting from transactional equipment purchases to outcome-based contracting.
| Leading Market Players |
|---|
| Xylem |
| Hach |
| Hanna Instruments |
| Thermo Fisher Scientific |
| Horiba |
| Endress+Hauser |
| Yokogawa Electric |
| AKVA group |
| Innovasea |
| Others |
Pricing and Supply Chain Analysis
ISO 17025 calibration certification gates both supplier qualification and price stratification simultaneously, filtering market access to vendors with seven-figure metrology laboratory investments while creating three distinct performance tiers that command 15-20x price multiples between economy electrochemical probes and integrated biomass-water quality platforms.
Pricing Analysis
Service contract bundling drives lifetime value capture as Norwegian and Chilean salmon integrators shift from transactional equipment purchases to uptime-guaranteed subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates regulatory-grade spectrophotometers from field-ruggedized electrochemical arrays and solar-powered telemetry nodes. Cost compression in standalone dissolved oxygen sensors intensifies because Asian component assemblers flood Vietnamese and Indonesian distributor channels. Shrimp pond cooperatives exhibit acute price sensitivity, while Scottish and Norwegian sea-cage operators prioritize predictive analytics capabilities over capital cost minimization.
Supply Chain Analysis
Strategic stockpiling of precision photodiodes and interference filters dominates inventory strategy as German and Japanese specialty optics suppliers concentrate fluorescence sensor component supply. Manufacturing draws from China for electrochemical electrode assemblies, Norway for ultrasonic transducer fabrication, and Germany for optical interference filter production. Raw material dependencies center on rare-earth-doped glass substrates, gold-nickel alloy electrodes, and marine-grade titanium housings. Single-source vulnerability in photodiode supply exposes assemblers to lead-time volatility. Distribution runs through agricultural equipment distributors for Southeast Asian pond clusters and direct vendor relationships for North Atlantic salmon integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Field engineering talent scarcity in electrochemistry, marine biology, and industrial networking protocols constrains deployment velocity for integrated sensor platforms, particularly across Vietnamese and Indonesian coastal clusters where multidisciplinary technician availability lags hardware shipment growth.
For Market Incumbents: Fortify regional service infrastructure depth in Norway and Chile to capture subscription revenue migration from large salmon integrators. Deepen backward integration into optical sensing module production to reduce dependency on German and Japanese photodiode suppliers. Certification investment in NMPA registration pathways secures positioning ahead of China's tightening aquaculture discharge enforcement. For New Entrants and Emerging Players: Differentiate on solar-powered telemetry platforms with simplified installation protocols targeting Ecuador's underpenetrated extensive shrimp pond systems. Penetrate the Indonesian fluorescence sensor segment where harmful algal event pressure displaces laboratory workflows. Pursue cooperative distribution partnerships with Vietnamese agricultural equipment distributors rather than direct sales investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biomass scanner and fluorescence optical system sub-segments as predictive analytics capabilities become table stakes. Long-term viability favors platform vendors with captive metrology certification infrastructure over component assemblers lacking field engineering depth. Acquisition target archetype: regional specialists with established ISO 17025 laboratories and existing distributor relationships in Vietnam or Indonesia. Watch for inflection in EU Water Framework Directive cross-border data standardization enforcement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Compliance Platform Development | Aggregates multi-site EPA and EU Water Framework Directive reporting across Norwegian, Scottish, and Irish salmon operations. |
| AI-Driven Predictive Feeding Subscription Launch | Converges biomass scanner data with machine learning models to optimize feed conversion ratios beyond hardware margins. |
| Optical Component Backward Integration | Reduces lead-time volatility from German and Japanese photodiode suppliers for fluorescence sensor manufacturing. |
| Regional Service Infrastructure Expansion | Captures outcome-based contracting migration among Chilean and Norwegian salmon integrators transferring calibration risk. |
| Solar Telemetry Platform Cost Engineering | Addresses price sensitivity in Vietnamese and Ecuadorian shrimp pond clusters through simplified installation protocols. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with sea-cage operations directors, shrimp pond cooperative managers, environmental compliance officers, distributor channel heads, and optical sensor R&D leads. Secondary validation drew from EPA effluent guideline filings, EU Water Framework Directive implementation reports, NMPA registration databases, and customs trade records for electrochemical and optical sensing equipment. Bottom-up equipment shipment modeling and top-down aquaculture production value allocation were triangulated to constrain estimate variance.
Across the analysis window, forecasts segment by product type, technology paradigm, application environment, and end-user procurement authority concentration. CAGRs were derived from installed base growth rates, replacement cycle compression, and technology substitution curves. Industry-specific inputs include salmon sea-cage consolidation timelines, shrimp pond intensification trajectories, and regulatory enforcement acceleration schedules.
The analysis sits within stated boundaries; outcomes outside sustained regulatory stringency or accelerated optical miniaturization would require recalibration. Forecasts reflect documented assumptions regarding certification timeline adherence and distributor channel stability. Disease pressure from harmful algal events and REACH substance restriction amendments represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Vietnam Aquafeed Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
Sandfish Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Qatar Fisheries and Aquaculture Market
Aquaculture Innovations
Europe Organic Aquaculture Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
Global Precision Aquaculture Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
Perch Market