
 Kuwait Fisheries and Aquaculture Market | 2026-2036
Kuwait Fisheries and Aquaculture Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Fisheries and Aquaculture Market Foresight
Kuwait's domestic fish production sector is repositioning toward land-based recirculating systems to offset declining Gulf wild-catch yields. Al-Bahar Fisheries Company leverages integrated hatchery-to-harvest operations across coastal sites. Kuwait Fish Farming Company anchors national tilapia and sea bream supply through controlled-environment tanks. Al Kout Industrial Projects Company differentiates via multi-species output serving institutional buyers.
Fisheries and aquaculture encompasses the breeding, rearing, and harvesting of fish, shellfish, crustaceans, and aquatic plants in marine, brackish, and freshwater environments, typically operating at salinity levels of 15–35 ppt for marine species and temperature-controlled recirculation for intensive land-based systems. Its primary commercial purpose is to deliver protein for human consumption, ornamental trade, and industrial derivatives. Fish dominates Kuwaiti production volume given established consumer preference for local hamour and zubaidi varieties. Recirculating Aquaculture Systems command capital investment focus as water-scarce geographies prioritize closed-loop resource efficiency. Food Services channels absorb the largest share of fresh output, particularly from hotel and catering contracts.
Kuwait's Public Authority for Agriculture Affairs and Fish Resources (PAAAFR) sets catch quotas and aquaculture licensing terms, while the Environment Public Authority monitors effluent discharge from coastal farms. These frameworks constrain wild-stock exploitation while channeling investment toward licensed inland facilities. Stakeholders must track PAAAFR licensing backlog resolution and coastal water quality enforcement to assess expansion feasibility.
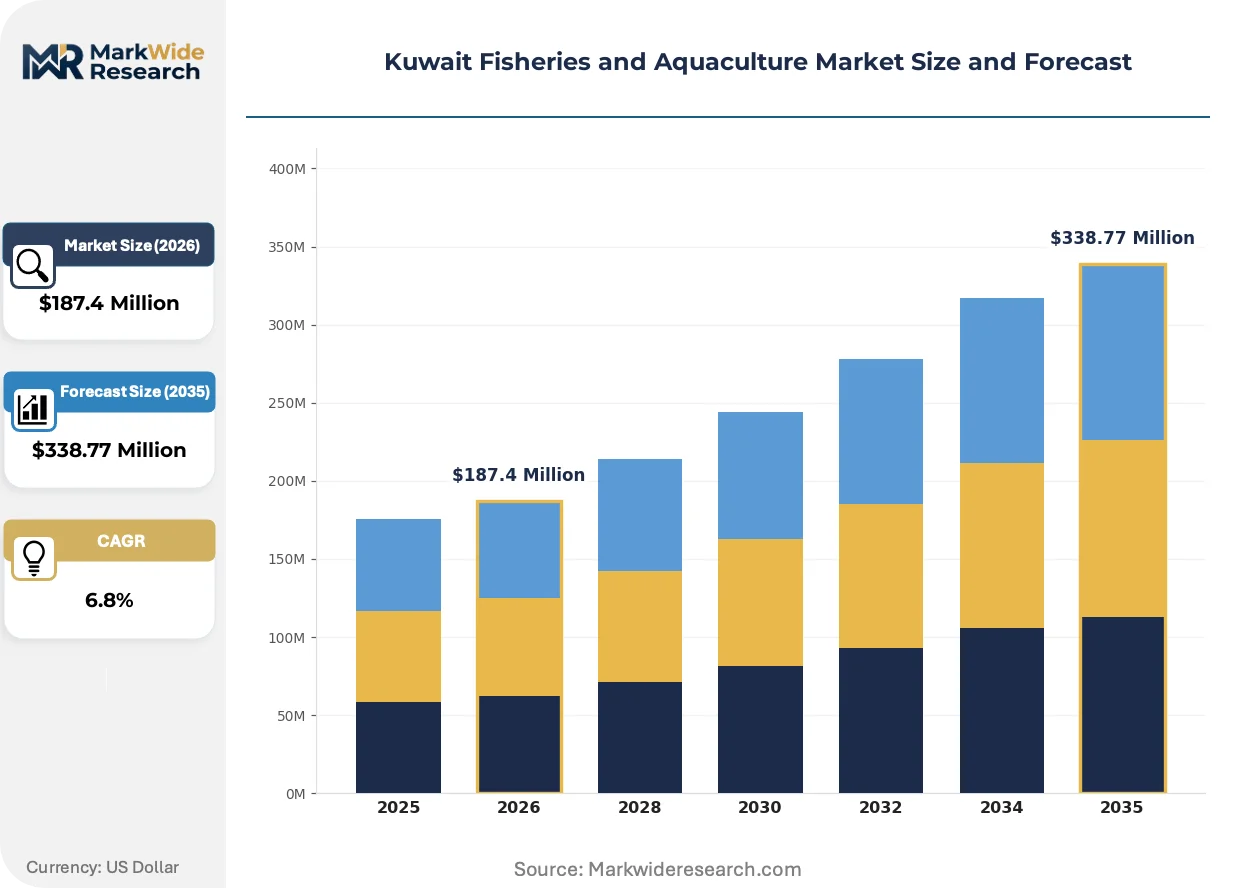
Market Dynamics
Kuwait's fisheries sector faces a structural pivot as Gulf wild-catch yields contract and PAAAFR licensing redirects investment toward land-based recirculating aquaculture systems. Water scarcity and coastal degradation are accelerating capital reallocation from marine extraction to controlled-environment production.
Growth Catalysts
- Recirculating Aquaculture Systems (RAS):Closed-loop water recycling technology enables year-round production in Kuwait's arid climate, reducing dependence on deteriorating Gulf marine stocks. Hotel and restaurant chains source live product through dedicated cold-chain distribution.
- PAAAFR Licensing Framework:The Public Authority for Agriculture Affairs and Fish Resources channels investment toward licensed inland facilities through aquaculture permitting, constraining wild exploitation while formalizing controlled production capacity.
- Hospitality Procurement Contracts:Kuwaiti hotel and catering groups are consolidating fresh seafood sourcing through direct farm partnerships, bypassing traditional auction markets for traceable supply.
Market Restraints
- Capital Intensity of RAS Infrastructure:Land-based recirculating systems require substantial upfront investment in tanks, filtration, and temperature control equipment, limiting participant pool to well-capitalized operators.
- Coastal Water Quality Degradation:Effluent discharge and rising salinity in Gulf waters constrain traditional marine farm expansion, compressing viable production geography.
- Input Cost Volatility:Feed formulations dependent on imported fishmeal and soy protein expose domestic producers to global commodity price swings.
Strategic Opportunities
- Jahra Governorate Expansion:Underdeveloped inland aquaculture zones west of Kuwait City offer greenfield RAS development potential with lower land costs than coastal governorates.
- Integrated Hatchery-to-Harvest Operations:Vertical control over broodstock, larval rearing, and grow-out phases reduces mortality losses and secures genetic quality for hamour and zubaidi varieties.
- Live-Product Premium Channels:Direct-to-restaurant delivery of live fish commands price premiums over iced product, rewarding farms with dedicated logistics infrastructure.
Industry Challenges
- Specialized Technician Shortage:RAS operation requires expertise in water chemistry, biofiltration management, and disease diagnostics that exceeds traditional fishery skill sets available domestically.
- PAAAFR Permit Backlog Resolution:Licensing delays for new facility approvals stall capacity expansion timelines and complicate investor planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Fisheries and Aquaculture Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish, Shellfish, Crustaceans, Aquatic Plants Technology: Recirculating Aquaculture Systems, Integrated Multi-Trophic Aquaculture, Offshore Aquaculture, Aquaponics End User: Food Services, Retailers, Exporters, Households Distribution Channel: Online, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Al-Bahar Fisheries Company, Al Kout Industrial Projects Company (Aquaculture Unit), Kuwait Fish Farming Company (KFFC), Al Jazeera Fish Farm, Al Asimah Fish Farm, Kuwait Danish Dairy Company (KDD) – Aquaculture Division, Kuwait United Fisheries Company (KUFC), Kuwait Fisheries Company, Al Watania Fisheries Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Fisheries and Aquaculture Market Shifts & Advancements
Technology diffusion and regulatory redirection are compressing Kuwait's traditional supply chains while elevating controlled-environment production. Three forces are restructuring competitive positioning around traceability, resource efficiency, and direct channel access.
Recirculating Aquaculture Systems (RAS) technology is decentralizing production geography away from coastal dependence toward inland industrial zones. Hotel procurement teams now specify live-product delivery windows that only RAS facilities can guarantee consistently. This shift is compressing the role of traditional auction markets and enabling farm-to-table traceability claims.
PAAAFR catch quota enforcement and aquaculture licensing terms are redirecting investment flows from marine extraction to licensed inland facilities. Coastal farm operators face intensified effluent monitoring by the Environment Public Authority, raising compliance costs. Domestic producers are responding by relocating or expanding into controlled-environment tank systems with closed water loops.
Direct contracting between farms and hospitality groups is displacing traditional wholesale auction intermediaries in fresh seafood distribution. Large hotel chains now negotiate annual volume agreements with named producers for hamour and zubaidi supply. This pattern concentrates most visibly in Kuwait City and surrounding Hawalli Governorate where cold-chain infrastructure supports live-product logistics.
Kuwait Fisheries and Aquaculture Market Segmentation
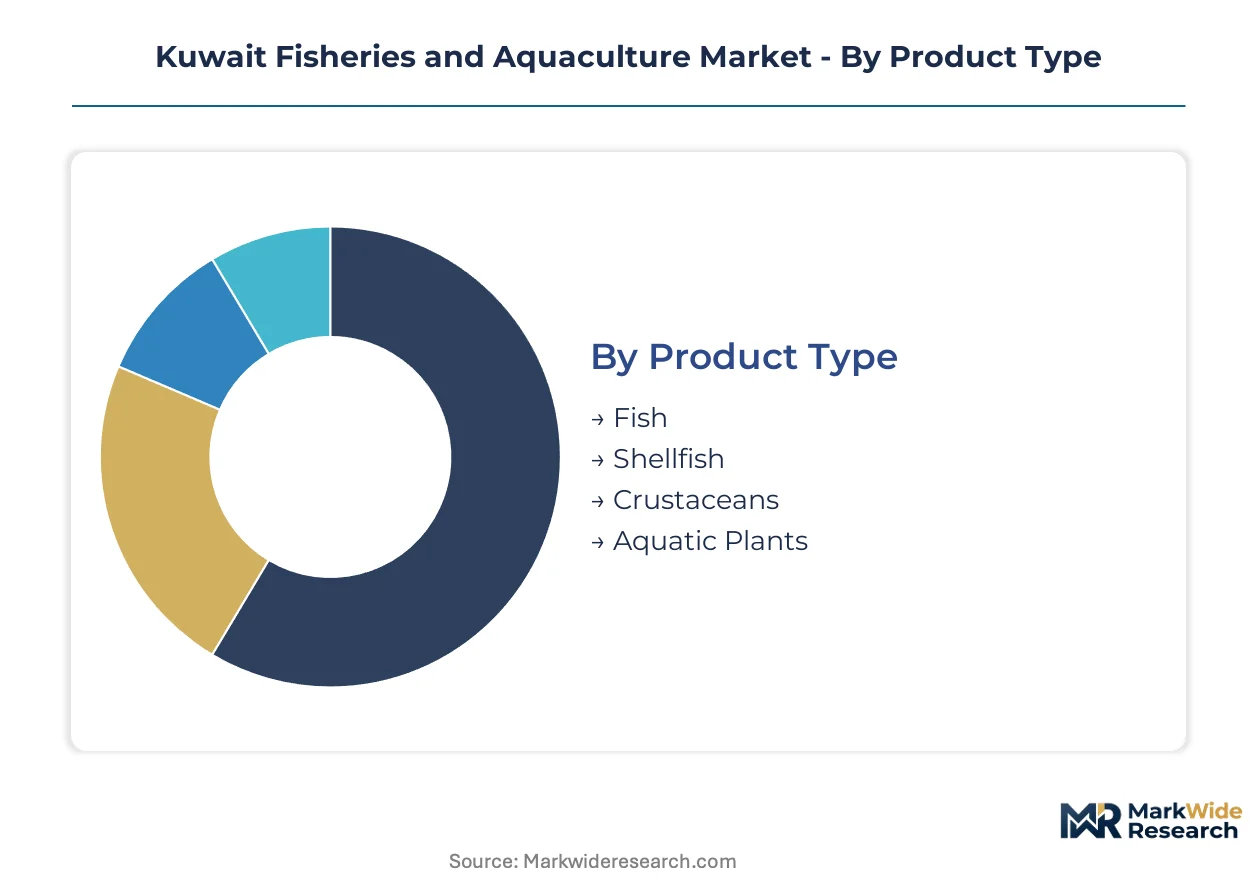
Segmentation reveals how capital deployment and regulatory pressure concentrate across Kuwait's fisheries value chain. Product mix and technology choices determine which operators capture hospitality procurement contracts and PAAAFR licensing priority.
Product Type:
Capital requirements vary sharply across biological categories, with finfish demanding the most intensive hatchery and grow-out infrastructure.
- Fish:Hamour and zubaidi varieties dominate Kuwaiti consumer preference and command premium pricing in hotel and restaurant channels. Live-product delivery requirements from Kuwait City hospitality groups drive investment in land-based recirculating systems for these species.
- Shellfish:Oysters and mussels filter-feed on suspended organic matter, reducing feed input costs versus carnivorous finfish. Coastal lease constraints from Environment Public Authority effluent monitoring limit expansion to licensed inland facilities with controlled water chemistry.
- Crustaceans:Shrimp production requires brackish water salinity management between 15-25 ppt and temperature-stable environments.
- Aquatic Plants:Seaweed and microalgae cultivation functions primarily as biofiltration components within integrated multi-trophic systems rather than standalone revenue centers.
Fish absorbs the bulk of installed capacity; shellfish is expanding most quickly as coastal water quality degradation favors filter-feeding species.
Technology:
Technology selection determines operational geography and regulatory exposure, with closed-loop systems enabling inland production away from deteriorating Gulf marine conditions.
- Recirculating Aquaculture Systems:Closed-loop water recycling with mechanical and biological filtration enables year-round production in Jahra Governorate industrial zones. RAS facilities secure direct contracts with Kuwait City hotel chains by guaranteeing live-product delivery windows that marine-dependent operations cannot match.
- Integrated Multi-Trophic Aquaculture:Species combination of fed finfish, filter-feeding shellfish, and extractive seaweed creates nutrient cycling efficiency. PAAAFR licensing frameworks increasingly favor these systems for waste reduction compliance.
- Offshore Aquaculture:Floating cage systems in Gulf waters face rising salinity and effluent discharge constraints from Environment Public Authority monitoring.
- Aquaponics:Combined fish and hydroponic vegetable production targets small-scale operators and educational institutions with limited commercial scale.
Recirculating Aquaculture Systems command the majority of new capital inflows; integrated multi-trophic configurations are gaining regulatory preference for licensing approval.
End User:
Customer type dictates pricing power and volume stability, with institutional buyers consolidating supply relationships away from auction intermediaries.
- Food Services:Hotel and catering groups in Kuwait City and Hawalli Governorate negotiate annual volume agreements for traceable hamour and zubaidi supply. Cold-chain infrastructure requirements for live-product delivery create barriers to entry that favor established RAS operators.
- Retailers:Supermarket chains source iced fresh and frozen product through wholesale channels with less stringent traceability requirements than hospitality procurement.
- Exporters:Regional Gulf markets absorb surplus production subject to sanitary certification from Kuwait's national food safety authority.
- Households:Direct consumer purchases concentrate in coastal governorates with traditional fish market access.
Food Services captures the dominant revenue share; exporters are scaling fastest as regional Gulf demand for certified Kuwaiti product expands.
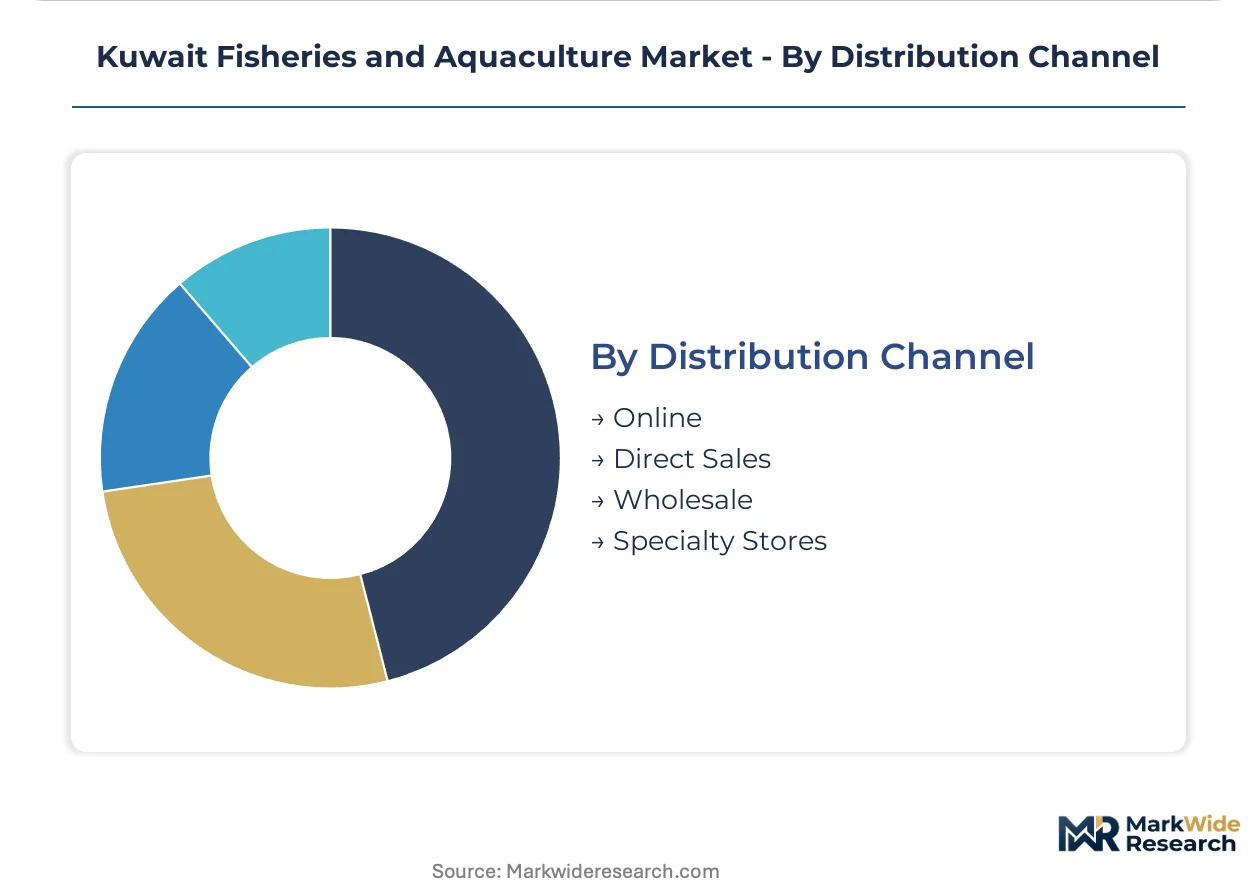
Distribution Channel:
Channel structure reflects the tension between traditional auction markets and direct farm-to-table relationships enabled by cold-chain investment.
- Direct Sales:Farm-to-restaurant contracts eliminate auction intermediary margins and enable live-product premium pricing. Large hospitality groups in Kuwait City consolidate procurement through named producer agreements with guaranteed delivery windows.
- Wholesale:Traditional fish auction markets in coastal governorates handle volume clearance for iced product with limited traceability documentation.
- Online:Digital platforms for home delivery of fresh and frozen seafood remain underdeveloped relative to other food categories.
- Specialty Stores:Premium retail outlets in urban governorates stock live tanks for consumer selection of specific specimens.
Direct Sales channels are displacing wholesale volume fastest; specialty stores maintain niche positioning for high-value live product.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf marine ecosystems anchor Kuwait's fisheries geography, with production concentrating in coastal governorates where cold-chain infrastructure supports live-product distribution to hospitality clusters.
Kuwait City
Hotel and restaurant chains in Kuwait City drive demand for traceable hamour and zubaidi through direct farm contracts. PAAAFR licensing requirements constrain wild-catch supply while channeling investment toward licensed RAS facilities. Cold-chain distribution hubs in Hawalli Governorate enable guaranteed live-product delivery windows that auction markets cannot match.
Jahra Governorate
Underdeveloped inland zones west of Kuwait City offer lower land costs for greenfield RAS development. The Environment Public Authority's coastal effluent monitoring redirects capital toward closed-loop systems in industrial areas. Several controlled-environment tank operations are establishing hatchery-to-harvest facilities to serve institutional buyers.
Al Ahmadi Governorate
Coastal industrial infrastructure supports integrated multi-trophic aquaculture configurations combining finfish and filter-feeding species. Rising Gulf salinity levels compress traditional marine farm viability. Operators are relocating grow-out capacity to land-based recirculating systems with dedicated logistics for food services channels.
Farwaniya Governorate
Urban density creates specialty retail demand for live-tank seafood selection in premium outlets. Distribution networks connect coastal production sites with consumer-facing facilities. Cold-storage investments support same-day delivery protocols for hospitality procurement teams.
Mubarak Al-Kabeer Governorate
Emerging aquaculture zones balance coastal access with industrial utility availability. PAAAFR permit backlogs stall some expansion timelines. Farms securing licensing priority are consolidating backward integration into broodstock and larval rearing phases.
Kuwait Fisheries and Aquaculture Market Competitive Landscape
Global aquaculture technology providers compete with Kuwaiti coastal incumbents across recirculating system deployment and hatchery genetics. The market structure concentrates around well-capitalized operators capable of RAS infrastructure investment, with smaller traditional fishers occupying wholesale auction segments. Three archetypes dominate: integrated hatchery-to-harvest specialists, hospitality-focused live-product suppliers, and diversified industrial project developers. Competitive dynamics center on PAAAFR licensing acquisition and direct procurement contract capture.
Among Kuwait-based integrated operators, Al-Bahar Fisheries Company and Kuwait Fish Farming Company exemplify the hatchery-to-harvest archetype through coastal site networks. Al Kout Industrial Projects Company occupies a position within the diversified industrial developer tier. These three entities anchor the competitive structure as PAAAFR licensing and hospitality direct-contracting patterns reshape participant viability.
| Leading Market Players |
|---|
| Al-Bahar Fisheries Company |
| Al Kout Industrial Projects Company (Aquaculture Unit) |
| Kuwait Fish Farming Company (KFFC) |
| Al Jazeera Fish Farm |
| Al Asimah Fish Farm |
| Kuwait Danish Dairy Company (KDD) – Aquaculture Division |
| Kuwait United Fisheries Company (KUFC) |
| Kuwait Fisheries Company |
| Al Watania Fisheries Company |
| Others |
Supply & Pricing Matrix
Fishmeal import costs from Peru and Chile cascade through feed formulation tiers to separate premium RAS-grown hamour from auction-sourced zubaidi in Kuwaiti hospitality procurement. Energy-intensive temperature control and biological filtration equipment anchor capital recovery schedules that concentrate pricing power among licensed operators with PAAAFR-approved capacity.
Pricing Analysis
Live-product delivery guarantees bundle cold-chain logistics and mortality replacement warranties into annual hospitality contracts that command premiums over iced wholesale channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by genetic certification, volume commitment scale, and traceability documentation depth. Cost compression in standard-tier iced product is intensifying because traditional auction intermediaries face margin erosion from direct farm contracting. Food services procurement teams in Kuwait City show lowest price sensitivity given menu positioning requirements, while retail supermarket buyers negotiate aggressively on volume clearance terms.
Supply Chain Analysis
Dual-sourcing qualification requirements from major hotel chains mandate that hospitality procurement teams validate at least two licensed RAS facilities for hamour and zubaidi supply before contract execution. Domestic production draws from Norwegian salmon genetics, Thai shrimp broodstock, and Danish recirculation equipment as critical upstream dependencies. Single-source vulnerability concentrates in specialized biofilter media and temperature control components subject to extended lead times from European manufacturers. Distribution runs through dedicated cold-chain logistics providers operating between Jahra Governorate production zones and Hawalli Governorate hospitality clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's fisheries sector sits at a technology-transition inflection where recirculating aquaculture systems displace marine cage operations degraded by Gulf salinity rise and effluent enforcement. This replacement dynamic restructures competitive viability around capital access and licensing speed rather than traditional fishing heritage.
For Market Incumbents: Cement PAAAFR licensing priority by accelerating backward integration into hatchery genetics and broodstock programs before permit backlogs clear. Secure multi-year hospitality procurement contracts with live-product delivery guarantees that RAS-dependent new entrants cannot match immediately. Threat substitution from vertically integrated Gulf aquaculture investors with sovereign capital access demands preemptive channel lock-in through exclusive supply agreements. For New Entrants and Emerging Players: Direct-to-restaurant digital ordering platforms offer the lowest-friction entry path around established wholesale auction intermediaries. Target Jahra Governorate greenfield RAS development where land cost advantages and industrial utility access offset coastal incumbents' logistics proximity. White-space concentration appears in specialty retail live-tank outlets serving Farwaniya Governorate's urban density with traceable product unavailable through traditional markets. For Investors and Strategic Acquirers: PAAAFR licensing resolution velocity is the leading indicator that capacity expansion timelines will compress and first-mover returns will concentrate among early permit holders. Long-term viability over the coming decade rests on genetic improvement programs and disease-resistant broodstock development rather than commodity volume scale. Acquisition target archetype: mid-cap RAS operators with secured coastal water rights and existing hospitality channel relationships but underdeveloped hatchery infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Hatchery-to-Harvest Integration | Captive broodstock supply reduces mortality losses and secures genetic quality for hamour varieties. |
| PAAAFR Licensing Acceleration | Permit priority resolution compresses competitor entry timelines and concentrates production geography. |
| Live-Product Cold-Chain Investment | Guaranteed delivery windows unlock direct hospitality contracts bypassing auction intermediaries. |
| Multi-Species IMTA Configuration | Filter-feeding shellfish integration satisfies Environment Public Authority waste reduction compliance. |
| Direct Farm Sourcing Agreements | Annual volume commitments with Kuwait City hotel chains stabilize revenue and reduce price volatility. |
Research Methodology
PAAAFR licensing databases, Environment Public Authority effluent monitoring records, and Kuwait Central Statistical Bureau trade data formed the secondary backbone for production volume and import dependency assessment. Primary interviews with RAS facility operations managers, hospitality procurement directors, cold-chain logistics providers, and PAAAFR licensing officials combined with secondary validation through bottom-up facility capacity aggregation and top-down consumption demand estimation.
Historical trendline analysis of installed RAS capacity, wild-catch quota allocations, and hospitality sector expansion patterns anchored the projection framework across the analysis window. Segmentation modeling incorporated product type, technology configuration, end-user channel, and governorate-level geography dimensions. CAGRs derived from slope analysis of capacity addition schedules and demand elasticity estimates for premium live-product versus iced commodity segments.
The model holds under sustained PAAAFR licensing enforcement and stable fishmeal import availability; deviation in Gulf salinity acceleration or sovereign capital subsidy programs for competing producers would shift capacity deployment timelines. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory backlog resolution rates. A model refresh is warranted upon material change in PAAAFR permit approval velocity or Environment Public Authority coastal water quality enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market
Aquaculture Innovations
Global Aquaculture Vaccine Market
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Qatar Fisheries and Aquaculture Market
Aquaculture Innovations
Ornamental Fish Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
Shrimp Feed Market
Aquaculture Innovations
Europe Organic Aquaculture Market
Aquaculture Innovations
Marine Life Raft Market