
 Fish Farming Equipment Market | 2026-2036
Fish Farming Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Farming Equipment Market Insights
Multi-source procurement for precision feeding hardware is hardening as farm operators diversify supplier relationships beyond single-vendor dependencies. BAADER Group leverages its Nordic manufacturing footprint to sustain long-term contracts with North Atlantic salmon producers. Marel competes through integrated software-to-hardware platforms that dominate automated processing lines. GroAqua specializes in recirculating system engineering, positioning its technology portfolio for land-based facility expansion.
Fish farming equipment encompasses mechanical, electronic, and biological systems engineered to control water chemistry, feed delivery, and stock containment in controlled aquatic production environments, typically operating within dissolved oxygen parameters of 6-9 mg/L for finfish species. Feeding Systems command substantial capital allocation due to their direct impact on feed conversion ratios and labor reduction across large-scale commercial operations. Recirculating Aquaculture Systems attract accelerated investment as water-scarce regions mandate closed-loop discharge compliance. Net Systems remain mature in offshore saltwater applications where polyethylene cage technology anchors established supply chains with limited margin expansion.
Norway's Directorate of Fisheries enforces strict escape-prevention standards that shape net system design and mooring specifications for Atlantic salmon licenses. The EU Green Deal and F-Gas Regulation constrain refrigerant choices in live-haul transport and processing equipment, redirecting R&D toward natural refrigerant architectures. The US FDA Seafood Hazard Analysis Critical Control Point framework governs equipment sanitation protocols for imported farmed seafood. Stakeholders must monitor how evolving antimicrobial resistance policies in major producing nations reshape water treatment equipment specifications and certification requirements.
Market Dynamics
EU Green Deal sustainability mandates are forcing commercial salmon producers in Norway to replace legacy feeding infrastructure with precision systems that cut waste and emissions. This regulatory pressure cascades through equipment procurement cycles, reshaping supplier relationships and capital allocation priorities across the North Atlantic basin.
Growth Catalysts
- EU F-Gas Regulation:Norway's salmon farms accelerate equipment replacement to eliminate synthetic refrigerants from live-haul transport, creating pull for natural refrigerant architectures.
- Water-scarce protein production:Vietnam, Indonesia, and India mandate closed-loop discharge compliance, driving recirculating aquaculture system installations at commercial scale.
- Feed conversion optimization:Automated feeding hardware cuts labor dependency and improves biological performance metrics, justifying capital expenditure even in margin-compressed cycles.
Market Restraints
- Polyethylene supply concentration:Net system manufacturers face input cost volatility from petrochemical feedstock exposure, squeezing margins on mature cage technology.
- Antimicrobial resistance policy uncertainty:Evolving water treatment certification requirements in major producing nations freeze procurement decisions pending regulatory clarity.
- Steel and electronics import dependency:Precision feeding hardware relies on concentrated Asian component supply, exposing European and North American integrators to tariff and logistics risk.
Strategic Opportunities
- Land-based facility expansion:Recirculating aquaculture system engineering positions equipment vendors for brownfield industrial conversions in water-stressed regions.
- Outcome-based service models:Hardware suppliers bundle software analytics and biological support, capturing recurring revenue from farm operators seeking performance guarantees.
- India's PLI scheme for food processing:Domestic protein production subsidies extend to aquaculture infrastructure, opening equipment procurement channels previously blocked by import cost structures.
Industry Challenges
- Biological systems integration:Mechanical and electronic equipment must interface with living stock cycles, requiring cross-functional expertise scarce in traditional engineering talent pools.
- Escape-prevention certification timelines:Norway's Directorate of Fisheries enforces strict net system validation protocols that extend approval cycles and freeze fleet modernization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Farming Equipment Market |
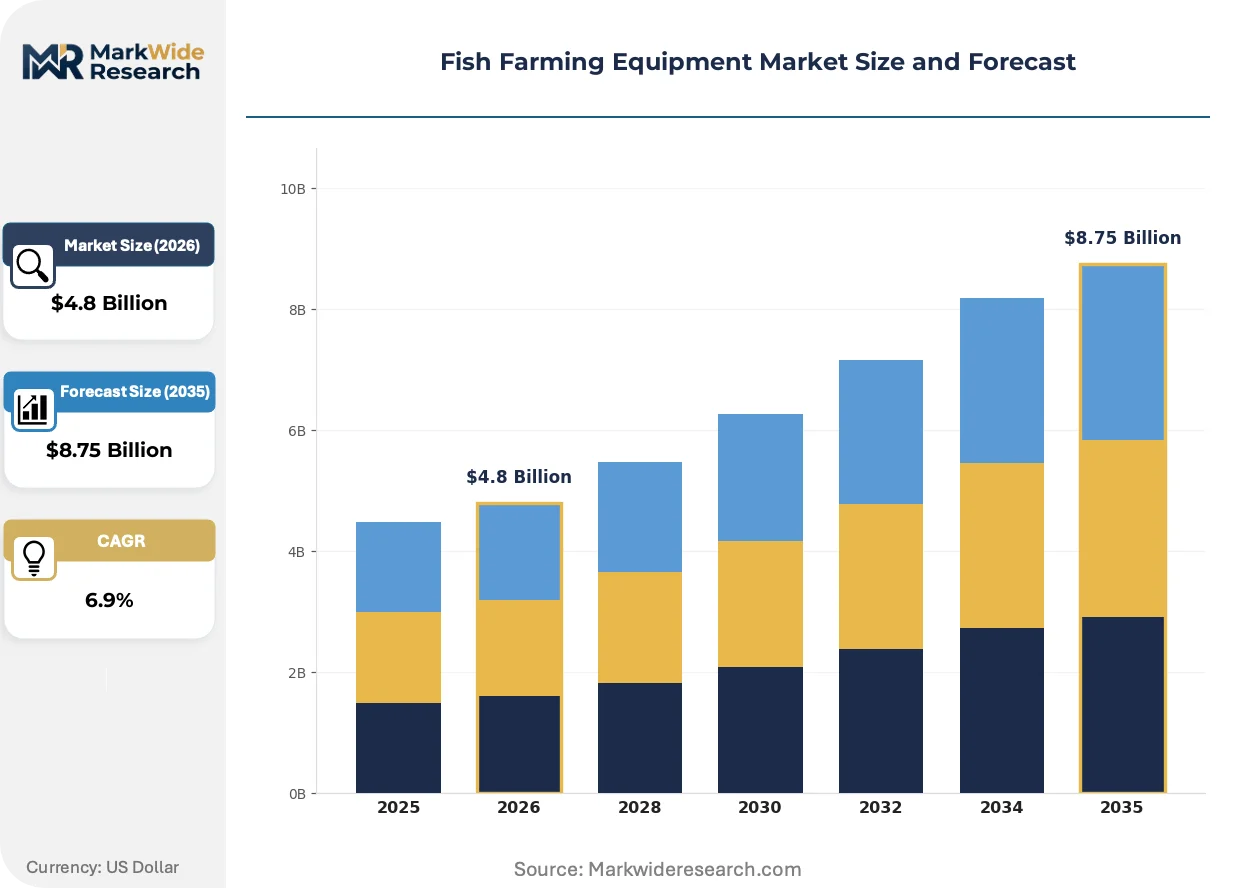
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.75 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Net Systems, Feeding Systems, Aeration Devices, Water Quality Monitoring Tools Technology: Recirculating Aquaculture Systems, Offshore Aquaculture, Integrated Multi-Trophic Aquaculture, Aquaponics End User: Commercial Farms, Research Institutions, Government Agencies, Aquatic Animal Health Organizations Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Carsoe Group A/S, JBT Corporation, BAADER Group, GroAqua, Coastline Equipment Inc, Marel, Optimar A/S, Aquatic Equipment and Design Inc, GEA Group Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Farming Equipment Market Trends and Innovations
Sensor-integrated feeding platforms and closed-loop water chemistry systems are compressing the gap between biological science and mechanical engineering. Equipment vendors now compete on data architecture and biological outcomes rather than hardware durability alone.
Computer vision-based biomass estimation is overtaking manual sampling and fixed-schedule feeding protocols in Atlantic salmon operations. Norwegian license holders deploy underwater cameras with machine-learning algorithms to adjust pellet delivery in real time. This precision hardware is compressing feed conversion ratios and forcing secondary equipment suppliers to integrate with proprietary software stacks.
The EU Green Deal and F-Gas Regulation constrain refrigerant choices in live-haul transport and processing equipment. Natural refrigerant architectures redirect R&D budgets away from conventional compressor technologies. Nordic equipment manufacturers face compressed product development timelines to maintain export eligibility into EU member state markets.
Consolidated procurement through integrated aquaculture platforms is displacing fragmented equipment purchasing across Southeast Asian markets. Vietnamese and Indonesian operators now source complete recirculating systems from single vendors rather than assembling components from specialized suppliers. This pattern concentrates contract volume with engineering-integrated firms and marginalizes standalone hardware manufacturers in the region's fastest-expanding production zones.
Fish Farming Equipment Market Segmentation
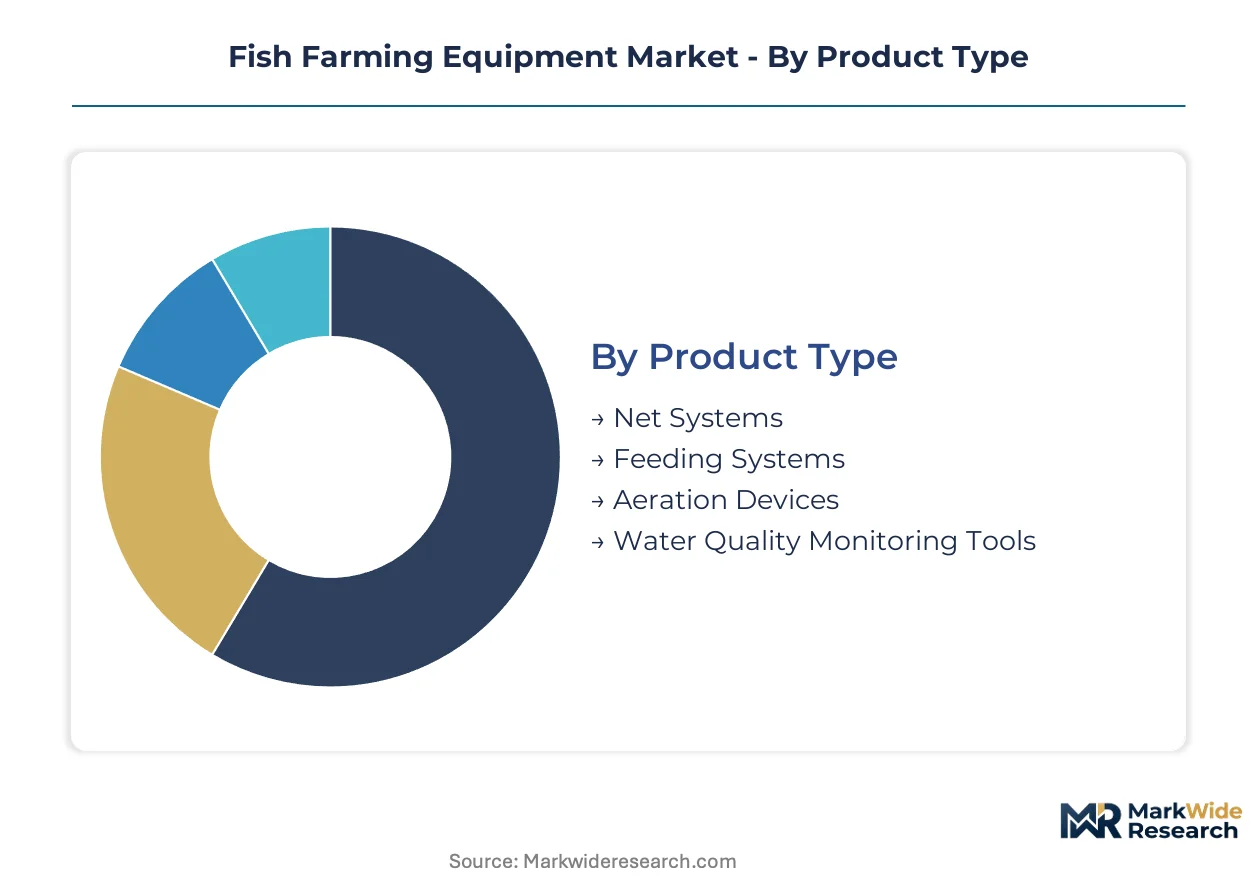
Equipment procurement patterns in aquaculture diverge sharply across production scales and regulatory environments. Buyers prioritize capital efficiency in net-intensive offshore operations while land-based facilities demand integrated biological-mechanical systems.
Product Type:
Capital allocation decisions hinge on feed conversion economics and labor substitution potential rather than hardware durability alone.
- Feeding Systems:Automated pellet delivery platforms integrate underwater sensors and machine-learning algorithms to adjust ration timing based on biomass estimates. Norwegian salmon license holders deploy these systems to meet EU Green Deal waste-reduction mandates while cutting labor dependency.
- Net Systems:Polyethylene cage structures with mooring assemblies dominate offshore saltwater production. Norway's Directorate of Fisheries enforces escape-prevention certification that extends validation timelines and concentrates procurement with validated suppliers.
- Aeration Devices:Mechanical and diffused aeration systems maintain dissolved oxygen parameters between 6-9 mg/L for finfish species.
- Water Quality Monitoring Tools:Sensor arrays track pH, ammonia, nitrite, and temperature parameters in real-time.
Volume sits with Net Systems; growth tilts toward Feeding Systems.
Technology:
Water scarcity and discharge compliance are reorienting investment toward closed-loop architectures.
- Recirculating Aquaculture Systems:Engineered closed-loop facilities treat and reuse water through mechanical filtration, biological conversion, and UV disinfection stages. Vietnam, Indonesia, and India mandate discharge compliance that accelerates commercial-scale installations.
- Offshore Aquaculture:Open-water cage operations in exposed marine environments rely on storm-resistant mooring engineering.
- Integrated Multi-Trophic Aquaculture:Co-cultivation systems combine fed species with extractive organisms in nutrient-recycling configurations.
- Aquaponics:Hydroponic crop integration with fish production creates dual-revenue stream operations.
Offshore Aquaculture carries installed base; Recirculating Aquaculture Systems gain share fastest.
End User:
Procurement sophistication varies dramatically across institutional mandates and production economics.
- Commercial Farms:Large-scale operators source integrated platforms through multi-year service contracts with performance guarantees. These buyers dominate capital deployment and drive vendor consolidation toward engineering-integrated suppliers.
- Research Institutions:Universities and aquaculture research centers acquire specialized systems for controlled experiments.
- Government Agencies:Public extension services and regulatory bodies fund demonstration projects and stock enhancement programs.
- Aquatic Animal Health Organizations:Disease surveillance and quarantine facilities require specialized containment and treatment equipment.
Commercial Farms absorb the majority of capital expenditure; Research Institutions expand most quickly.
Distribution Channel:
Channel selection reflects equipment complexity and buyer technical capability.
- Direct Sales:Engineering-integrated vendors deploy technical sales teams for large-scale recirculating system and automated feeding contracts. Vietnamese and Indonesian operators increasingly source complete systems through direct relationships rather than component assembly.
- Distributors:Regional equipment dealers stock net systems, aeration hardware, and replacement components.
- Wholesale:Volume procurement of standardized cage components and mooring hardware.
- Online Retail:Small-scale operators and hobbyist producers acquire monitoring tools and spare parts through digital channels.
Direct Sales command the largest transaction values; Distributors maintain broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for precision feeding hardware concentrates in North Atlantic salmon jurisdictions, while recirculating aquaculture system procurement accelerates across water-scarce Asian markets. Regulatory pressure from the EU Green Deal reshapes capital allocation priorities in Norway and neighboring producing zones.
Norway
Commercial salmon license holders deploy automated feeding platforms to meet EU Green Deal waste-reduction mandates and cut labor dependency. The Directorate of Fisheries enforces escape-prevention certification that extends net system validation timelines and concentrates procurement with validated suppliers. Bergen and Trondheim anchor the Nordic equipment engineering cluster where BAADER Group and Marel sustain long-term service contracts.
United States
Domestic aquaculture operators source recirculating systems for land-based Atlantic salmon production in water-stressed jurisdictions. The FDA Seafood Hazard Analysis Critical Control Point framework governs equipment sanitation protocols for imported farmed seafood, redirecting vendor compliance investments. The Pacific Northwest and Maine concentrate recirculating facility development where biological-mechanical system integration commands premium engineering support.
Vietnam
Commercial pangasius and shrimp producers mandate closed-loop discharge compliance, driving consolidated procurement of complete recirculating systems from single vendors rather than component assembly. The country's national environmental regulator tightens effluent standards for coastal aquaculture zones, accelerating capital expenditure timelines. The Mekong Delta concentrates system installations where Vietnamese operators source engineering-integrated platforms through direct technical sales relationships.
India
Domestic protein production subsidies under the PLI scheme for food processing extend to aquaculture infrastructure, opening equipment procurement channels previously blocked by import cost structures. The Central Pollution Control Board issues discharge compliance directives for intensive aquaculture clusters in water-stressed states. Gujarat and Andhra Pradesh anchor commercial-scale recirculating system deployment where capital efficiency demands override fragmented component sourcing.
Indonesia
Shrimp and finfish producers scale recirculating aquaculture system installations to meet provincial discharge mandates in Java and Sumatra. The Ministry of Marine Affairs and Fisheries encloses coastal aquaculture zones under stricter environmental licensing, redirecting investment toward closed-loop architectures. Surabaya and Medan concentrate engineering-integrated vendor relationships where consolidated procurement displaces fragmented equipment purchasing.
Fish Farming Equipment Market Competitive Landscape
Capacity expansion dominates the current landscape as engineering-integrated vendors build regional technical service teams to capture recurring revenue from performance-guarantee contracts. The vendor base stratifies across three tiers: Nordic-origin full-system integrators, Asian component fabricators, and specialized recirculating system engineering firms. Consolidation pressure concentrates contract volume with suppliers bundling software analytics and biological support. Geographic expansion and outcome-based service models represent the dominant competitive vectors reshaping supplier-farm operator relationships.
Within the Nordic engineering-integrated tier, BAADER Group and Marel occupy positions defined by manufacturing footprint proximity to North Atlantic salmon producers. GroAqua exemplifies the specialized recirculating system archetype, positioning its technology portfolio for land-based facility expansion in water-stressed Asian markets. These three anchors illustrate how competitive positioning separates full-platform vendors from component specialists across diverging procurement patterns.
| Leading Market Players |
|---|
| Carsoe Group A/S |
| JBT Corporation |
| BAADER Group |
| GroAqua |
| Coastline Equipment Inc |
| Marel |
| Optimar A/S |
| Aquatic Equipment and Design Inc |
| GEA Group Aktiengesellschaft |
| Others |
Pricing and Supply Chain Analysis
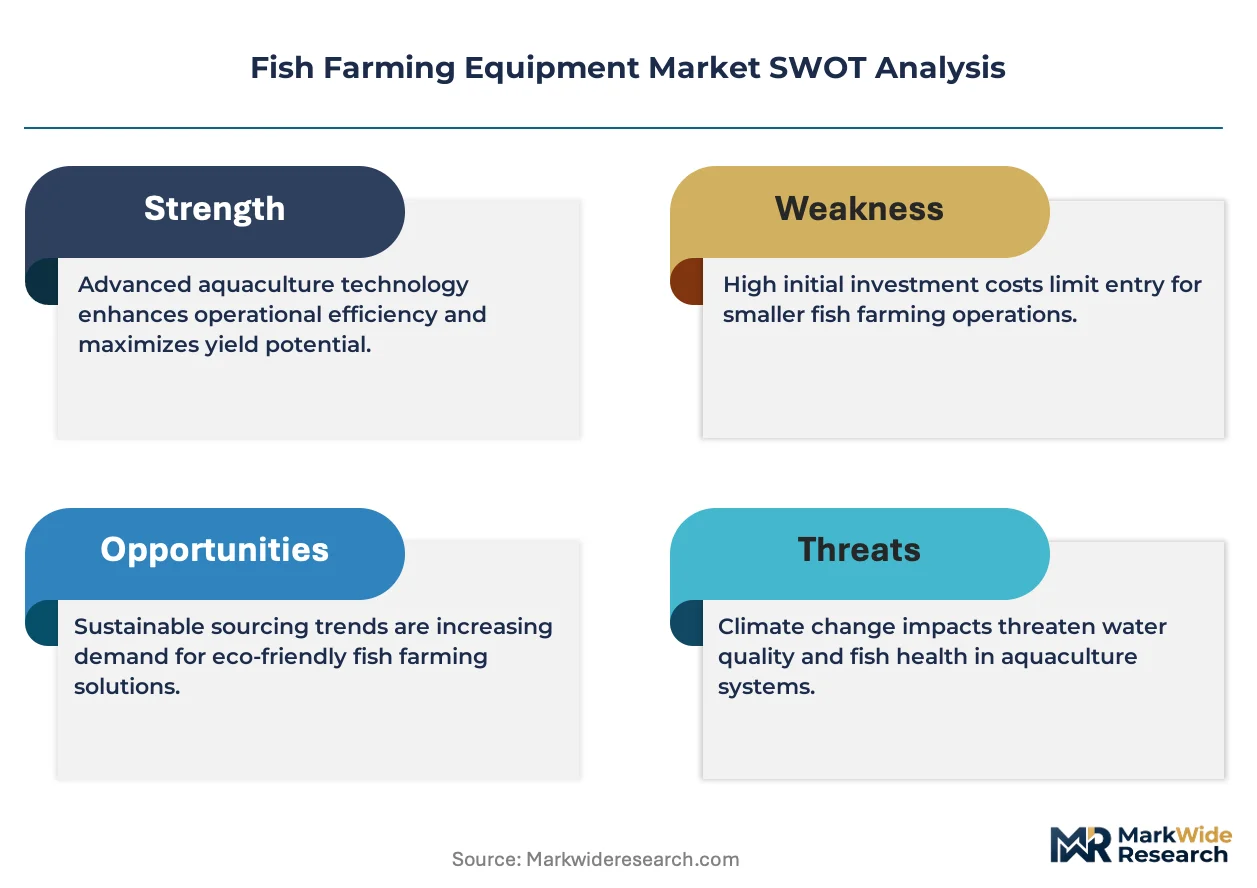
Certification-grade divergence between EU Green Deal-compliant precision feeding systems and legacy polyethylene cage hardware manifests in pricing power concentration and supply chain fragmentation. Premium automated feeding platforms command sustained margins through software-integrated service bundling, while commodity net manufacturers absorb petrochemical feedstock volatility with limited pricing leverage.
Pricing Analysis
Volume-massive net systems trade on razor-thin margins against project-scale recirculating aquaculture systems that capture value through biological performance guarantees. Pricing stratifies across premium sensor-integrated feeding platforms, standard automated hardware, and economy-grade cage components. Cost compression in polyethylene-based net manufacturing intensifies as Asian petrochemical feedstock exposure transmits volatility. Small-scale Vietnamese and Indonesian operators exhibit highest price sensitivity, while Norwegian salmon license holders prioritize outcome-based service contracts over unit economics.
Supply Chain Analysis
Direct-to-farm technical sales channels handle large-scale recirculating system procurement, while regional distributors manage replacement components and standardized hardware. Precision feeding equipment draws from concentrated electronics and steel component supply in China, South Korea, and Taiwan. Polyethylene resin and mooring hardware rest on petrochemical and maritime steel supply chains vulnerable to tariff exposure. Single-source vulnerability concentrates in machine-learning sensor arrays and proprietary software stacks. Distribution runs through engineering-integrated vendors for complex systems, with wholesale channels capturing volume cage assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained biological systems integration talent props pricing for vendors bundling software analytics with hardware deployment. Escape-prevention certification bottlenecks in Norway freeze fleet modernization schedules and concentrate procurement with validated engineering partners.
For Market Incumbents: Deepen captive supply of sensor-integrated feeding components to offset Asian electronics import dependency. Expand technical service teams in Vietnam and Indonesia before consolidated procurement patterns lock in competitor relationships. Defend against specialized recirculating system engineering firms by acquiring biological-mechanical integration capabilities. For New Entrants and Emerging Players: Capture India's PLI-subsidized equipment procurement channels by partnering with domestic fabricators for cost-competitive recirculating system assembly. Target water-stressed Indian states where discharge compliance mandates override import cost barriers. Lead with direct technical sales relationships that bundle biological support and performance guarantees. For Investors and Strategic Acquirers: Re-rating potential sits with specialized recirculating system engineering firms given land-based facility expansion across water-scarce Asian markets. Long-term viability favors vendors with software-to-hardware platform integration and recurring revenue from outcome-based service contracts. Monitor EU F-Gas Regulation enforcement timelines as inflection indicator for natural refrigerant equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Reduces electronics import dependency for Norwegian precision feeding vendors facing EU Green Deal compliance deadlines. |
| Biological-Mechanical System Integration | Captures performance-guarantee contracts from Vietnamese operators consolidating procurement with engineering-integrated suppliers. |
| Natural Refrigerant Architecture Development | Maintains EU market eligibility for Nordic live-haul transport equipment manufacturers under F-Gas Regulation constraints. |
| Direct Technical Sales Expansion | Locks in long-term service relationships with Indonesian shrimp producers facing provincial discharge mandates. |
| PLI Scheme Partnership Structuring | Opens equipment procurement channels in Gujarat and Andhra Pradesh previously blocked by import cost structures. |
Research Methodology
Multi-period observation of recirculating aquaculture system installation rates and automated feeding platform deployment anchored the trend analysis, supplemented by interviews with aquaculture farm operations directors, equipment procurement managers at Norwegian salmon license holders, biological systems engineers, regional distribution channel partners, and regulatory affairs specialists at Nordic manufacturers. Secondary validation drew from EU Directorate-General for Maritime Affairs and Fisheries reports, Norwegian Directorate of Fisheries licensing data, Vietnam Ministry of Natural Resources and Environment discharge compliance filings, India's PLI scheme administrative records, and SEC filings of publicly traded processing equipment manufacturers. Bottom-up project pipeline assessment triangulated against top-down protein production demand modeling.
Segment-weighting applied differential growth assumptions across recirculating aquaculture systems, offshore cage operations, and integrated multi-trophic configurations, with technology adoption curves calibrated to water scarcity indices and discharge regulation enforcement intensity. Product type segmentation modeled feeding systems, net systems, aeration devices, and water quality monitoring tools against capital allocation patterns by farm scale. CAGRs derived from installed base expansion rates, replacement cycle compression, and regulatory-driven equipment refresh mandates. Forecast inputs incorporated EU Green Deal implementation timelines and India's PLI scheme subsidy disbursement trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to antimicrobial resistance policy evolution, petrochemical feedstock price volatility, and biological systems integration talent scarcity. Projections reflect assumptions regarding regulatory enforcement consistency, subsidy program continuity, and supply chain logistics stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Brazil Fisheries and Aquaculture Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Ornamental Fish Market
Aquaculture Innovations
North America Shrimp Feed Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Aquaponics Market
Aquaculture Innovations
Kuwait Fisheries and Aquaculture Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Aquaculture UAE in Market