
 Sandfish Market | 2026-2036
Sandfish Market Size, Share, and Industry Trends Forecast 2026-2036
Sandfish Market Intelligence
Subscription-based traceability services is expanding as a recurring revenue layer atop traditional sandfish sales, with processors bundling blockchain-verified origin certificates into annual contracts. Aik Lee Dried Seafood leverages its Malaysian processing base to dominate dried-format exports across Greater China. Indian Ocean Trepang anchors its position through Seychelles-sourced raw material control and EU-compliant cold chain logistics. Seawijh Indonesia competes aggressively on volume, using Java-based aquaculture ponds to supply frozen formats into ASEAN wholesale channels.
Sandfish (Holothuria scabra) is a tropical sea cucumber species harvested from Indo-Pacific reef systems, typically processed through boiling, salting, and air-drying to achieve moisture content below 15% for long-haul trade. Its primary commercial purpose centers on East Asian gastronomy and traditional medicine, where dried specimens command premium placement in tonic soups and restorative preparations. The dried product type leads absolute revenue contribution due to shelf stability and concentrated export economics, while online distribution channels represent the fastest-expanding access route as direct-to-consumer platforms bypass layered wholesale markups. Value chain margins concentrate disproportionately in processing and marketing stages, where brand authentication and grading certification create defendable price premiums over commoditized catching operations.
FDA import alert protocols for seafood adulteration shape US market access conditions, forcing exporters to maintain HACCP-aligned documentation. China's SAMR enforces GB standards for dried aquatic product heavy metal limits, directly filtering which Southeast Asian suppliers qualify for mainland entry. Indonesia's national fisheries ministry operates catch certificate verification that governs wild-harvest legality for EU-bound shipments. Stakeholders must monitor evolving traceability mandates as regulatory divergence between destination markets fragments compliance architectures and reshapes supplier qualification thresholds.
Market Dynamics
China's NMPA food safety protocols for aquatic products are tightening traceability requirements, reshaping export compliance costs and forcing processors to absorb blockchain-verified documentation systems or exit mainland supply chains entirely.
Growth Catalysts
- East Asian gastronomy demand:Restaurant chains across Greater China and Southeast Asia are expanding dried sandfish procurement for tonic soup applications, creating stable volume anchors for Indonesian and Vietnamese processors.
- GB standards alignment:China's SAMR enforcement of heavy metal limits for dried aquatic products is filtering supplier pools, rewarding HACCP-certified processors with preferential mainland market access.
- Blockchain traceability:Subscription-based origin verification services are generating recurring revenue streams atop commodity sales, with annual contract bundling becoming standard for EU-bound shipments.
Market Restraints
- Wild-harvest input volatility:Seychelles and Indo-Pacific reef systems face cyclone and bleaching disruptions, concentrating raw material risk in geographically constrained sourcing zones.
- Cold chain capex intensity:EU-compliant logistics infrastructure requires sustained capital deployment, freezing out smaller Indonesian and Philippine processors from premium export tiers.
- FDA import alert friction:US seafood adulteration protocols create documentation burdens that extend clearance timelines and elevate working capital requirements for Southeast Asian exporters.
Strategic Opportunities
- Direct-to-consumer channel expansion:Online distribution platforms are bypassing layered wholesale markups, enabling Indonesian aquaculture operators to capture margin previously absorbed by ASEAN trading houses.
- Value-added format development:Frozen and partially prepared sandfish products targeting East Asian retail markets remain underdeveloped relative to dried formats, offering white space for Malaysian and Vietnamese processors.
- EU Green Deal alignment:Carbon footprint certification for aquaculture operations is emerging as a procurement differentiator for Nordic and German specialty seafood retailers sourcing through Rotterdam and Hamburg.
Industry Challenges
- Grading certification talent scarcity:Holothuria scabra quality assessment requires specialized expertise in moisture content and specimen classification that outpaces training pipeline output across Java and Mindanao processing clusters.
- Multi-jurisdiction compliance synchronization:Exporters must simultaneously maintain FDA HACCP documentation, NMPA traceability protocols, and EU catch certificate verification, fragmenting quality management system architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sandfish Market |
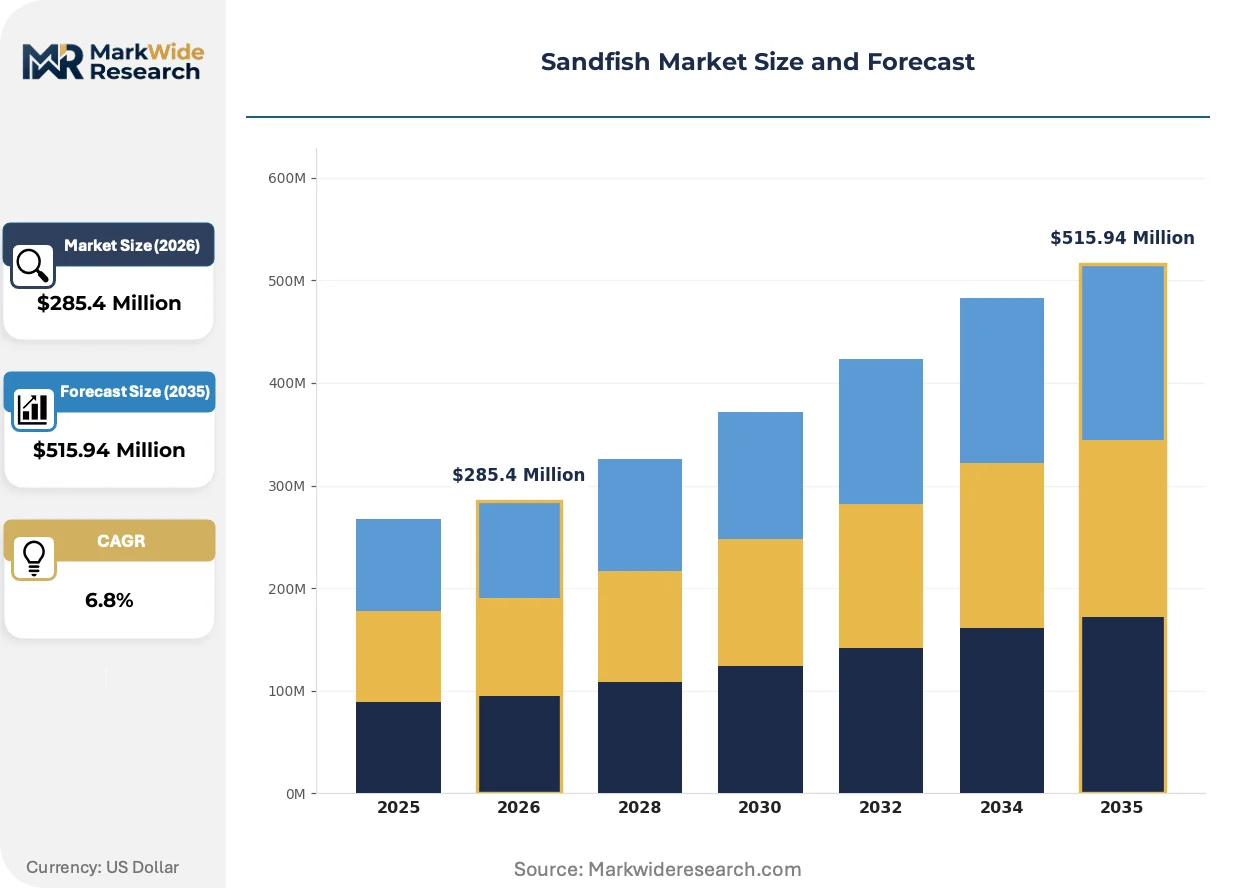
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Dried, Frozen, Canned Distribution Channel: Retail, Wholesale, Online, Direct Sales End User: Restaurants, Supermarkets, Exporters, Households Value Chain Stage: Catching, Processing, Distribution, Marketing |
| Companies Covered | Aik Lee Dried Seafood, Indian Ocean Trepang, Joo Hwa Food, National Aquaculture Group, Seawijh Indonesia, Seychelles Aquaculture, Tasmanian Seafoods, Vietnam Sea Ginseng, Feide Organisms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sandfish Market Strategic Shifts & Innovations
Processing technology and distribution architecture are converging to compress value chain layers, with automation and digital verification systems displacing manual grading and paper-based provenance tracking across Southeast Asian supply corridors.
Blockchain-enabled traceability platforms are modularizing provenance documentation for sandfish shipments, allowing Indonesian and Malaysian processors to unbundle certification services from physical product sales. Specialty seafood retailers in Shanghai and Shenzhen are adopting these systems fastest, demanding API-integrated origin verification that compresses due diligence cycles from weeks to hours. This modularization is enabling smaller aquaculture operators to compete on transparency metrics previously monopolized by vertically integrated incumbents.
China's SAMR is intensifying GB standard enforcement for dried aquatic product heavy metal limits, disqualifying wild-harvest suppliers with inadequate pre-export testing infrastructure. The industrial consequence is a supplier consolidation wave across Vietnam and the Philippines, where only processors with in-house laboratory capabilities maintain mainland market access. Dried-format exporters serving Guangzhou and Beijing distribution hubs are most affected, responding with accelerated ISO 17025 laboratory accreditation investments.
Certification-driven procurement preferences are rotating demand toward blockchain-verified origin documentation among East Asian restaurant chains and direct-to-consumer platforms. Layered wholesale channels with opaque provenance are losing share to vertically transparent suppliers, particularly in Singapore and Hong Kong retail markets. This behavioral shift is most visible in premium tonic soup ingredient sourcing, where specimen grading and catch coordinates now appear on consumer-facing packaging.
Sandfish Market Segmentation
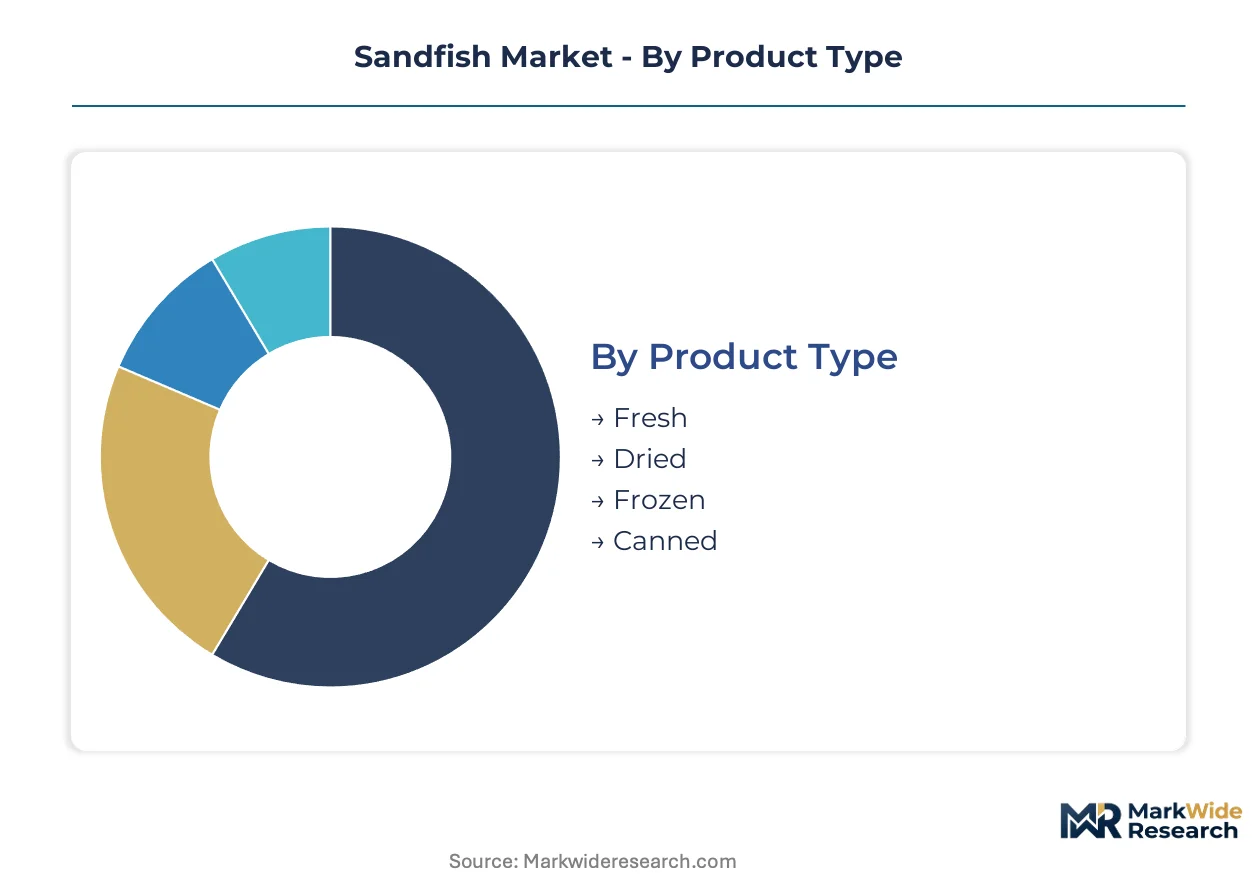
Sandfish market segmentation reveals how capital deployment and regulatory compliance concentrate across product formats and channel structures. Processors must align infrastructure investments with the specific traceability and cold-chain requirements governing each segment's access to premium East Asian markets.
Product Type:
Capital intensity varies sharply across formats, with drying infrastructure requiring lower upfront outlay than EU-compliant frozen processing lines while commanding comparable margin premiums in Greater China.
- Dried:Air-dried specimens achieve sub-15% moisture content through boiling, salting, and solar or mechanical drying cycles. Demand concentrates in Guangzhou and Beijing distribution hubs where restaurant chains and tonic soup manufacturers prize shelf stability and concentrated flavor profiles. China's SAMR enforcement of GB heavy metal limits is filtering supplier pools, rewarding processors with in-house ISO 17025 laboratory capabilities.
- Frozen:Blast-freezing to -18°C preserves Holothuria scabra texture for high-end restaurant applications requiring rehydration flexibility. Southeast Asian aquaculture operators in Java and Mindanao are expanding frozen capacity to supply ASEAN wholesale channels, though EU-bound shipments require cold-chain infrastructure that freezes out smaller processors.
- Fresh:Live or chilled specimens serve immediate-consumption restaurants within 48-hour catch radiuses, limiting geographic scope to coastal Indonesian and Philippine population centers.
- Canned:Thermally processed formats in brine target mass-market retail in secondary Southeast Asian cities with limited cold storage penetration.
Most installed capacity flows through dried processing. Expansion is steepest in frozen formats as Vietnamese and Malaysian processors target EU Green Deal procurement preferences.
Distribution Channel:
Channel selection determines margin capture, with direct platforms compressing wholesale markups while layered intermediaries retain quality assurance functions for risk-averse institutional buyers.
- Online:Direct-to-consumer platforms bypass ASEAN trading house markups, enabling Indonesian aquaculture operators to capture margin previously absorbed by layered wholesale channels. Singapore and Hong Kong retail markets show fastest adoption of API-integrated origin verification systems.
- Wholesale:Traditional trading houses in Jakarta, Ho Chi Minh City, and Manila aggregate supply from dispersed catching operations, maintaining quality grading and lot consolidation functions.
- Retail:Specialty seafood counters in Shanghai and Shenzhen supermarkets demand blockchain-verified origin certificates bundled into annual procurement contracts.
- Direct Sales:Processor-to-restaurant relationships dominate premium dried sandfish allocation, with Aik Lee Dried Seafood and comparable operators maintaining captive supply agreements with Greater China restaurant chains.
Wholesale channels retain volume dominance. Online distribution is gaining share fastest as traceability technology modularizes provenance verification for smaller operators.
End User:
End-user segmentation tracks how preparation format and certification requirements diverge across institutional versus household consumption patterns.
- Restaurants:East Asian gastronomy establishments across Greater China and Southeast Asia anchor dried sandfish procurement for tonic soup applications, creating stable volume anchors for Indonesian and Vietnamese processors with HACCP certification.
- Exporters:Re-export traders in Singapore and Hong Kong manage multi-jurisdiction compliance synchronization, maintaining simultaneous FDA HACCP documentation, NMPA traceability protocols, and EU catch certificate verification.
- Supermarkets:Specialty seafood retailers in Nordic and German markets are rotating procurement toward carbon footprint certified aquaculture operations aligned with EU Green Deal frameworks.
- Households:Direct purchasing through e-commerce platforms is concentrated in tier-one Chinese cities where consumer-facing packaging displays specimen grading and catch coordinates.
Restaurant procurement absorbs the majority of premium dried supply. Household direct purchasing is climbing the fastest as platform infrastructure penetrates Southeast Asian consumer markets.
Value Chain Stage:
Margin concentration and defendable positioning vary across value chain stages, with processing and marketing capturing disproportionate returns relative to commoditized catching operations.
- Processing:Boiling, salting, drying, and grading operations concentrate in Vietnam, Indonesia, and the Philippines where labor costs intersect with proximity to raw material sources. Blockchain-verified documentation systems and ISO 17025 laboratory accreditation create supplier differentiation under tightening NMPA protocols.
- Marketing:Brand authentication and grading certification generate price premiums in East Asian markets, with vertically integrated operators capturing margin through origin storytelling and quality guarantee functions.
- Catching:Wild-harvest operations in Seychelles and Indo-Pacific reef systems face cyclone and bleaching disruptions, concentrating raw material risk in geographically constrained sourcing zones with limited buffer capacity.
- Distribution:Cold-chain logistics and customs brokerage functions fragment across specialized providers, with EU-compliant infrastructure requiring sustained capital deployment that elevates working capital requirements.
Processing capacity holds the majority of fixed asset deployment. Marketing functions are expanding most quickly as subscription-based traceability services generate recurring revenue layers atop commodity sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the majority of dried sandfish imports while Vietnam and Indonesia compete aggressively on processing capacity expansion, creating divergent supply corridor dynamics across Southeast Asian export hubs.
China
Guangzhou and Beijing distribution hubs anchor dried sandfish procurement for restaurant chains and tonic soup manufacturers. SAMR enforcement of GB heavy metal limits filters supplier pools, disqualifying wild-harvest operators without ISO 17025 laboratory capabilities. Shanghai and Shenzhen specialty seafood retailers demand blockchain-verified origin certificates bundled into annual contracts.
Vietnam
Ho Chi Minh City processors expand frozen format capacity to supply ASEAN wholesale channels and EU Green Deal-aligned Nordic retailers. The national fisheries ministry operates catch certificate verification systems governing wild-harvest legality for export shipments. Processing clusters in the Mekong Delta concentrate boiling, salting, and grading operations for dried format exports.
Indonesia
Java-based aquaculture ponds supply frozen sandfish formats into ASEAN wholesale channels while competing on volume against Malaysian dried specialists. The country's national fisheries ministry maintains catch certificate verification for EU-bound shipments. Jakarta trading houses aggregate supply from dispersed catching operations across the archipelago.
Seychelles
Indian Ocean reef systems provide raw material control for EU-compliant cold chain logistics serving premium European specialty seafood markets. Cyclone and bleaching disruptions concentrate raw material risk in geographically constrained sourcing zones. Victoria-based operations maintain captive supply agreements with vertically integrated processors.
Philippines
Mindanao processing clusters face cold chain capex intensity that freezes smaller operators from premium export tiers to the EU and North America. Manila trading houses maintain quality grading and lot consolidation functions for layered wholesale channels. Grading certification talent scarcity in Holothuria scabra quality assessment outpaces training pipeline output.
Sandfish Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated dried processors commanding premium positioning in Greater China while volume-oriented aquaculture operators compete on frozen format throughput. The vendor base concentrates around three strategic archetypes: Malaysian and Vietnamese dried specialists with ISO 17025 laboratory accreditation, Indonesian aquaculture operators leveraging Java-based pond systems, and Seychelles-anchored raw material controllers with EU cold chain infrastructure. Competitive moves center on backward integration into captive supply agreements and subscription-based traceability service bundling.
Among Southeast Asian dried specialists, Aik Lee Dried Seafood and Vietnam Sea Ginseng occupy positions exemplifying the laboratory-accredited processor archetype serving SAMR-compliant mainland China entry. Seawijh Indonesia represents the volume-driven aquaculture operator model competing aggressively on frozen format throughput through Java-based production systems. These three companies anchor the competitive structure visible across the supplier landscape.
| Leading Market Players |
|---|
| Aik Lee Dried Seafood |
| Indian Ocean Trepang |
| Joo Hwa Food |
| National Aquaculture Group |
| Seawijh Indonesia |
| Seychelles Aquaculture |
| Tasmanian Seafoods |
| Vietnam Sea Ginseng |
| Feide Organisms |
| Others |
Cost & Logistics Intelligence
Wild-harvest Holothuria scabra input costs from Seychelles reef systems cascade through Indonesian and Vietnamese processing tiers into three distinct pricing bands: ISO 17025-accredited dried specimens command premium placement in Guangzhou distribution hubs, frozen formats compete on volume through ASEAN wholesale channels, and ungraded fresh product serves coastal population centers at compressed margins.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for frozen sandfish formats while dried segment premiums hold firm. Pricing stratifies across premium, standard, and economy tiers based on blockchain-verified origin documentation and SAMR GB standard compliance. Cost compression in frozen formats is intensifying because Java-based aquaculture operators are expanding pond capacity faster than demand absorption. Restaurant chains in Greater China show least price sensitivity for dried specimens with catch-coordinate verification, while ASEAN wholesale buyers of frozen product negotiate aggressively on volume.
Supply Chain Analysis
Single-source vulnerability sits with Seychelles wild-harvest operations that feed EU-compliant cold chain logistics serving premium European retailers. Geographic supply concentration centers on Indonesia, Vietnam, and the Philippines where boiling, salting, and grading operations cluster. Raw material dependencies rest on Indo-Pacific reef system health, blast-freezing infrastructure, and ISO 17025 laboratory accreditation. Tariff exposure from divergent NMPA, FDA, and EU catch certificate protocols fragments compliance architectures. Distribution runs through Jakarta and Ho Chi Minh City trading houses that aggregate dispersed catching operations into consolidated export lots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sandfish market margin expansion hinges on subscription-based traceability services layering recurring revenue atop commodity sales, with carbon footprint certification emerging as a premium-tier differentiator for EU Green Deal-aligned procurement.
For Market Incumbents: Anticipate regulatory divergence between NMPA blockchain protocols and FDA HACCP documentation requirements by building modular quality management systems that unbundle certification services. Deepen backward integration into captive supply agreements with Seychelles raw material controllers to buffer cyclone disruption risk. Prioritize ISO 17025 laboratory investments that maintain mainland China market access under tightening SAMR enforcement. For New Entrants and Emerging Players: Direct-to-consumer platforms in Singapore and Hong Kong retail markets offer the most penetrable white-space target, with API-integrated origin verification systems compressing due diligence cycles from weeks to hours. Frozen and partially prepared formats for East Asian retail remain underdeveloped relative to dried product, creating entry opportunity for Malaysian and Vietnamese processors. Launch through vertically transparent supply chains that display specimen grading and catch coordinates on consumer-facing packaging. For Investors and Strategic Acquirers: Asymmetric upside sits with aquaculture operators combining Java-based pond systems with blockchain-verified documentation capabilities. Long-term viability favors processors with in-house laboratory accreditation and multi-jurisdiction compliance synchronization across the projection horizon. Watch for NMPA protocol harmonization signals as inflection indicator for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Laboratory Accreditation | SAMR GB standard enforcement filters supplier pools, rewarding accredited processors with preferential mainland China entry. |
| Blockchain Traceability Platform Deployment | Shanghai and Shenzhen specialty seafood retailers demand API-integrated origin verification bundled into annual contracts. |
| Java-Based Aquaculture Pond Expansion | Seawijh Indonesia demonstrates volume competitiveness through pond-based frozen format supply into ASEAN wholesale channels. |
| EU Green Deal Carbon Certification | Nordic and German specialty seafood retailers rotate procurement toward footprint-certified aquaculture operations. |
| Direct-to-Consumer Channel Buildout | Online platforms bypass Jakarta trading house markups, enabling Indonesian operators to capture margin previously absorbed by intermediaries. |
Research Approach
Direct dialogue with Indonesian aquaculture operators, Vietnamese processing plant managers, Singapore re-export traders, EU specialty seafood retailers, and NMPA compliance consultants anchored qualitative grounding, cross-referenced with SAMR enforcement bulletins, EU catch certificate verification records, FDA import alert databases, and ASEAN customs trade data. Bottom-up and top-down triangulation validated volume estimates across product formats.
Bottom-up modeling built segment-level projections from processor capacity utilization, aquaculture pond yields, and wild-harvest quota allocations across the analysis window. Top-down constraints applied macroeconomic filters and regulatory trajectory assumptions. Segmentation dimensions spanned product type, distribution channel, end user, and value chain stage. CAGRs derived from fitted growth curves adjusted for compliance cost inflation and cold chain infrastructure deployment timelines.
Underlying measurement precision varies by segment; dried format revenue flows carry tighter precision than fresh product given consolidated distribution through Guangzhou and Beijing hubs. Forecasts reflect documented assumptions regarding NMPA protocol evolution, reef system health indices, and aquaculture pond expansion rates. Cyclone frequency, bleaching events, or sudden SAMR standard revisions could materially alter trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
Global Precision Aquaculture Market
Aquaculture Innovations
Marine Life Raft Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
North America Shrimp Market
Aquaculture Innovations
Qatar Fisheries and Aquaculture Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Crab Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
Thailand Aquafeed Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
APAC Aquafeed Market
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
United States Ornamental Fish Market