
 Middle East Animal Protein Market | 2026-2036
Middle East Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Animal Protein Market Foresight
Veterinary and halal-slaughter expertise is bifurcating the Middle East animal protein competitive landscape as Gulf states expand local production capacity. Almarai leverages its integrated dairy and poultry operations across Saudi Arabia to secure feed-to-retail control. Tanmiah sustains one of the region's largest broiler operations through backward integration into hatcheries and feed mills. ARASCO anchors the Saudi market with captive grain milling and protein processing infrastructure that reduces import dependency.
Middle East animal protein encompasses slaughtered and processed livestock products—primarily poultry, beef, lamb, and limited pork—typically graded by halal certification status, fat coverage, and chilled versus frozen preservation state, serving commercial foodservice and retail consumption. Poultry dominates volume flows due to lower feed conversion ratios and shorter production cycles that suit desert-climate farming constraints. Beef and lamb segments command margin pools tied to import reliance on Australian and South American sources, with premium positioning around grain-fed and organic claims. Distribution channels split structurally between wholesale bulk sales to institutional buyers and supermarket retail packs for household end users, with online retail gaining traction among urban consumers seeking subscription-based meat delivery.
Saudi Arabia's SFDA enforces halal slaughter and cold-chain standards that shape product specifications and cross-border market access for imported protein. The UAE's MOHAP and ESMA coordinate on import licensing and labeling rules that filter which suppliers enter Dubai and Abu Dhabi retail channels. Stakeholders must monitor how Gulf Cooperation Council harmonization of food safety protocols reshapes compliance costs for exporters and domestic processors alike.
Market Dynamics
Saudi Arabia's SFDA cold-chain traceability mandates are forcing Gulf distributors to consolidate supplier bases around HACCP-certified processors, reshaping procurement patterns across quick-service restaurant chains and institutional buyers.
Growth Catalysts
- Foodservice Expansion:Quick-service restaurant chains across Saudi Arabia and the UAE are scaling chilled protein volumes to support drive-through and delivery formats.
- Saudi Food Security Programs:Government-backed domestic poultry and red meat production incentives are accelerating local capacity buildout and import substitution.
- Halal Certification Harmonization:Gulf Cooperation Council alignment on slaughter and labeling standards is streamlining cross-border protein flows between member states.
Market Restraints
- Feed Grain Import Dependency:Saudi Arabia and UAE poultry operations remain exposed to international corn and soybean price volatility with limited domestic cultivation alternatives.
- Water Scarcity Constraints:Desert-climate farming limits expansion of cattle feedlots and dairy operations, capping local beef and milk protein output regardless of capital investment.
- Slaughter Capacity Concentration:Centralized halal-certified processing infrastructure in Riyadh and Jeddah creates supply bottlenecks during peak demand periods.
Strategic Opportunities
- E-Commerce Subscription Channels:Urban Saudi and Emirati consumers are adopting app-based meat delivery platforms that bypass traditional wholesale distribution layers.
- Precision Fermentation Feed:Novel protein sources for poultry and aquaculture diets offer pathways to reduce grain import exposure and improve feed conversion metrics.
- UAE Re-Export Hub Positioning:Dubai's logistics infrastructure enables regional processors to access African and South Asian markets with halal-certified products.
Industry Challenges
- Veterinary Specialist Shortage:Gulf states face acute scarcity of halal-slaughter certified veterinarians and animal health technicians, constraining facility licensing timelines.
- Cold-Chain Capex Burden:SFDA-mandated temperature monitoring and traceability systems require substantial hardware investment across aging distribution networks.
- Multi-Jurisdiction Compliance:Exporters must navigate divergent labeling, shelf-life, and packaging rules between Saudi SFDA, UAE MOHAP, and ESMA frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Animal Protein Market |
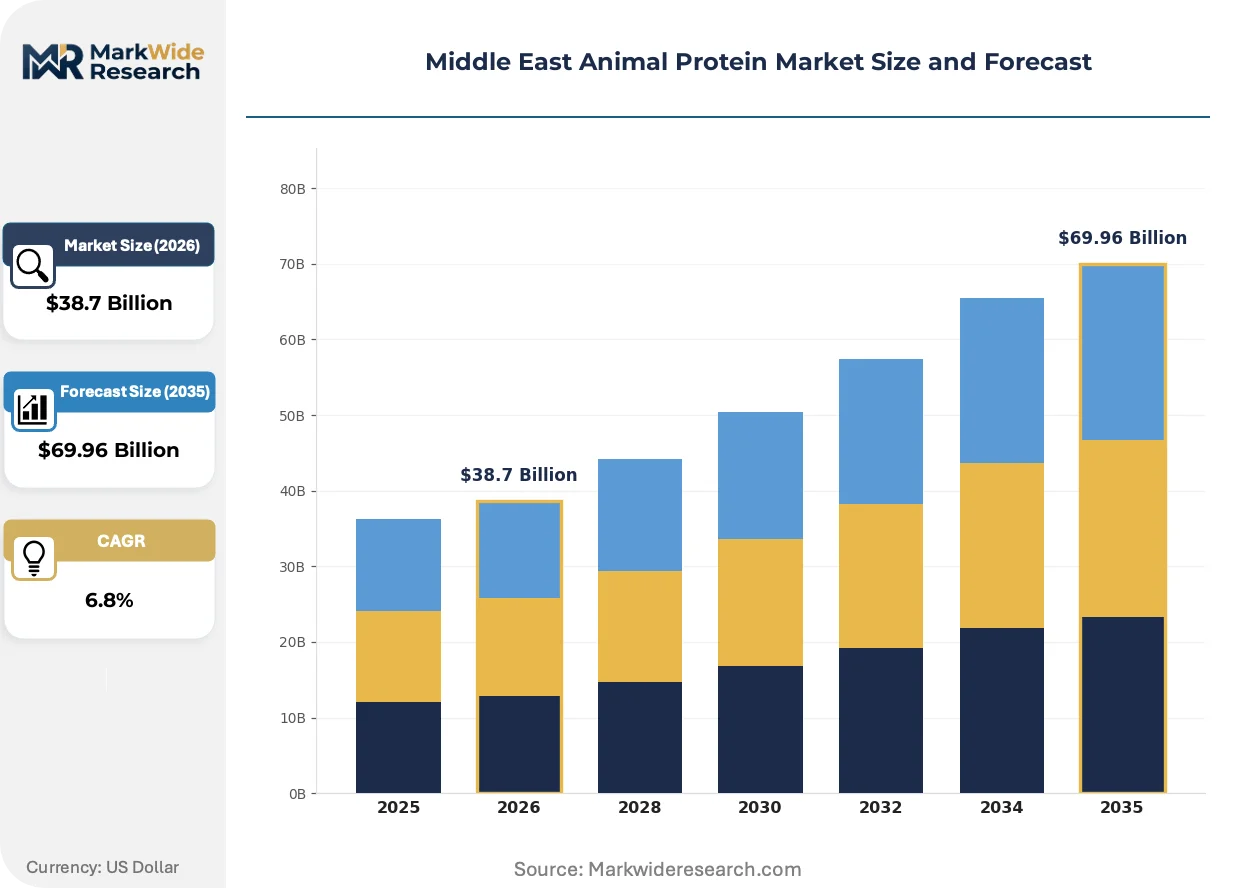
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry, Beef, Pork, Lamb Distribution Channel: Supermarkets, Online Retail, Wholesale, Direct Sales End User: Restaurants, Households, Food Processors, Caterers Pricing Model: Premium, Mid-range, Economy, Discount |
| Companies Covered | Almarai, Tanmiah, Americana Group, National Poultry Company, Al Islami Foods, Sunbulah Group, National Feed and Flour Production and Marketing, ARASCO, Baladna, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Animal Protein Market Shifts & Advancements
Climate-adaptive production systems and digital traceability platforms are converging to redefine how Gulf processors manage desert-environment constraints and regulatory compliance burdens simultaneously.
Controlled-environment poultry housing with evaporative cooling and automated ventilation is displacing open-sided barn designs that previously dominated Saudi and UAE broiler operations. Large integrated producers are retrofitting existing facilities at scale to reduce mortality rates during summer heat peaks. This capital-intensive shift is compressing margins for smaller operators unable to fund climate-control infrastructure upgrades.
Saudi SFDA's phased implementation of blockchain-enabled cold-chain tracking is mandating real-time temperature logging from slaughterhouse to retail shelf. Distributors must now integrate IoT sensor networks with existing warehouse management systems or face import license suspension. Quick-service restaurant chains with centralized procurement functions are demanding supplier compliance ahead of regulatory deadlines to secure volume commitments.
Subscription-based fresh meat delivery is capturing urban household segments previously served by supermarket retail counters. Dubai and Riyadh-based platforms offer scheduled portion-controlled deliveries that reduce consumer freezer inventory and waste. This channel shift is fragmenting traditional wholesale-to-retail relationships and forcing processors to develop direct-to-consumer packaging formats and last-mile logistics partnerships.
Middle East Animal Protein Market Segmentation
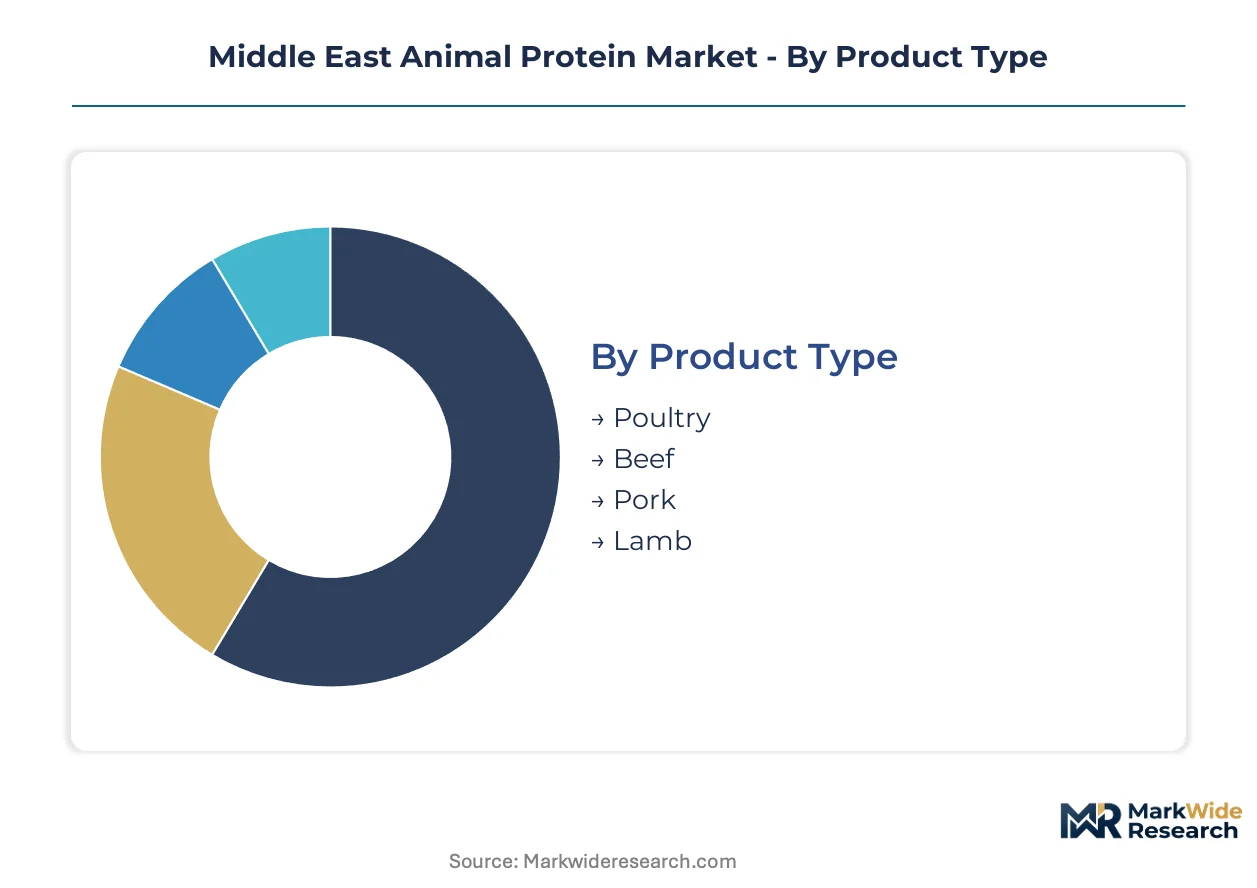
Segmentation in the Middle East animal protein market reveals how halal certification requirements, cold-chain infrastructure, and channel economics partition commercial opportunity. Understanding these divisions clarifies where procurement power concentrates and which customer segments reward premium positioning.
Product Type:
Poultry commands the dominant channel flow through quick-service restaurant chains and institutional wholesalers, while beef and lamb circulate through premium retail and foodservice tiers with distinct margin profiles.
- Poultry:Broiler meat with halal certification dominates volume flows due to favorable feed conversion ratios and shorter production cycles suited to Saudi and UAE desert-climate farming. Quick-service restaurant chains across Riyadh and Dubai drive chilled poultry procurement at scale.
- Beef:Grain-fed and grass-fed categories, predominantly imported from Australian and South American sources, carry premium positioning tied to marbling grades and organic claims. High-end steakhouses and hotel foodservice in Abu Dhabi and Jeddah concentrate demand for premium cuts.
- Pork:Limited to non-Muslim expatriate communities and specific hospitality channels in the UAE, with restricted distribution outside Dubai's designated free zones. Volume remains marginal across the broader regional market.
- Lamb:Local and imported sources serve traditional consumption patterns during religious observances, with Australian and New Zealand exports supplying consistent year-round availability for retail and catering segments.
Poultry dominates installed base. Beef is where expansion concentrates for premium positioning.
Distribution Channel:
Cost tier stratification separates capital-intensive cold-chain operators from traditional wholesale layers, with digital platforms capturing margin through disintermediation of legacy distribution networks.
- Supermarkets:Chilled and frozen retail packs with halal certification labeling serve household consumers through Carrefour, Lulu, and local chains across Saudi Arabia and the UAE. SFDA-mandated traceability requirements favor larger format stores with integrated cold-chain monitoring.
- Online Retail:Subscription-based meat delivery platforms bypass traditional wholesale layers, offering portion-controlled fresh deliveries to urban Saudi and Emirati households. These channels fragment conventional procurement relationships and demand direct-to-consumer packaging formats.
- Wholesale:Bulk frozen shipments to institutional buyers, quick-service restaurant chains, and hotel groups remain the volume backbone, with HACCP certification now mandatory under tightened SFDA cold-chain rules.
- Direct Sales:Processor-to-foodservice relationships for customized cuts and volume contracts serve large catering operations and government institutional buyers with specific halal slaughter certification requirements.
Wholesale channels anchor volume throughput. Online retail is climbing the fastest among emerging segments.
End User:
Application-driven segmentation splits between high-volume contract supply to foodservice chains and fragmented household consumption patterns shaped by religious calendar peaks and urbanization trends.
- Restaurants:Quick-service chains and fine-dining establishments across Saudi Arabia and the UAE drive standardized portion specifications and consistent halal certification documentation. Chilled protein volumes scale with drive-through and delivery format expansion.
- Households:Urban consumers in Riyadh, Jeddah, and Dubai shift toward subscription delivery and premium retail packs, reducing freezer inventory and waste through portion-controlled purchasing.
- Food Processors:Industrial buyers of frozen bulk protein for further processing into value-added products, nuggets, and prepared meals supply retail and foodservice downstream channels with specific fat content and grind specifications.
- Caterers:Large-scale hospitality and event catering operations demand volume reliability during religious observances and peak seasons, with halal certification and cold-chain documentation as non-negotiable procurement criteria.
Restaurant channels command procurement scale. Household segments show steepest expansion trajectory through digital adoption.
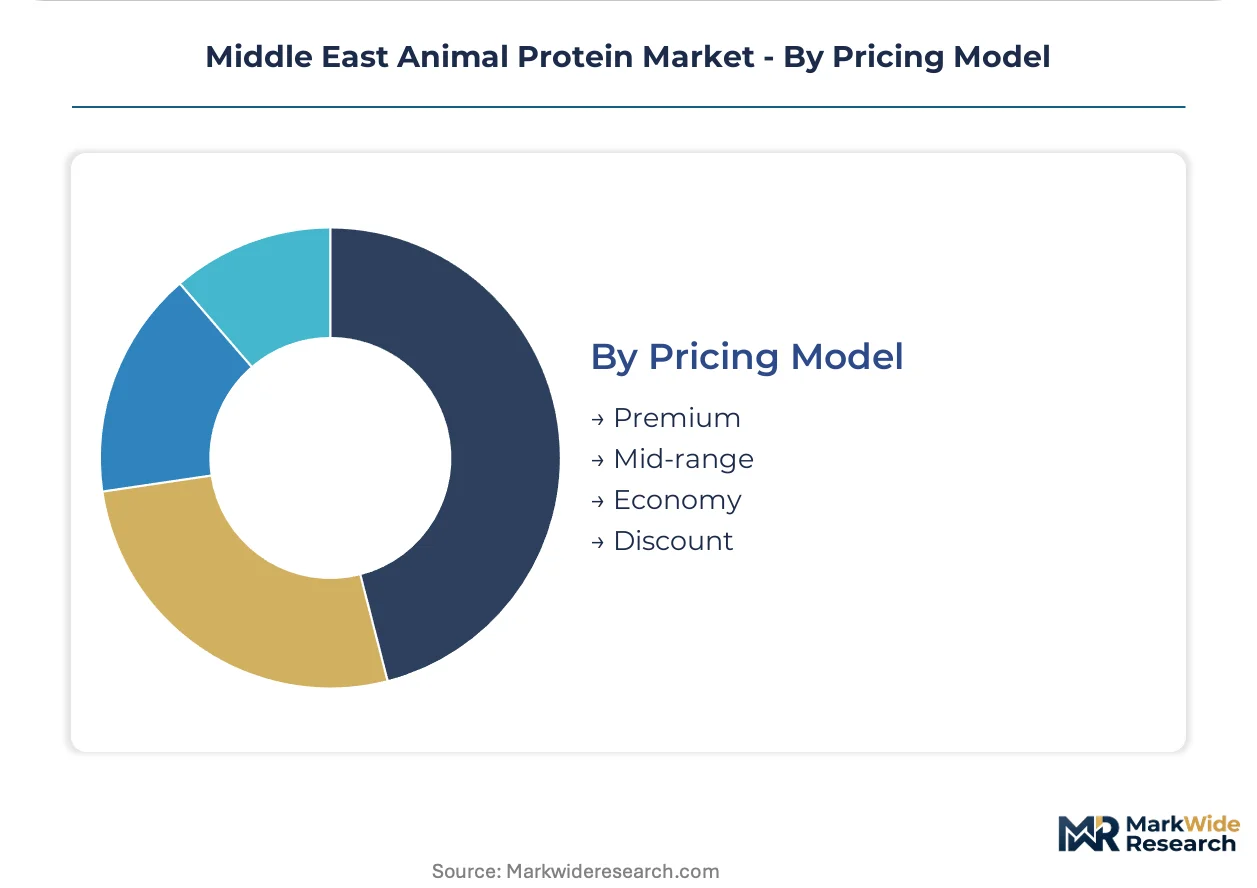
Pricing Model:
Margin structure reflects certification grade, import dependency, and channel service levels rather than simple commodity tiering, with halal premiumization creating pricing separation even within comparable product categories.
- Premium:Organic, grain-fed, and specialty-certified products with full traceability documentation serve high-end foodservice and discerning retail consumers in Dubai and Riyadh. Australian Wagyu and specific halal-certified imports anchor this tier.
- Mid-range:Standard chilled and frozen products with reliable halal certification and consistent supply for mainstream retail and casual dining segments across Saudi and UAE urban centers.
- Economy:Frozen bulk imports and domestic broiler production serving price-sensitive institutional buyers and value-oriented retail segments with basic halal compliance and functional cold-chain handling.
- Discount:Near-expiry or promotional inventory moving through secondary channels and specific wholesale clearances, with limited shelf-life remaining and reduced certification documentation.
Economy pricing anchors volume throughput. Premium tier is gaining share fastest through certification-driven differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA cold-chain mandates and food security programs anchor Saudi Arabia's regulatory framework, with procurement patterns rippling across Gulf Cooperation Council states. National production incentives and halal certification harmonization shape sub-regional competitive dynamics.
Saudi Arabia
Domestic poultry capacity expansion and red meat localization targets drive procurement volume growth under Vision 2030 food security mandates. SFDA traceability rules enforce HACCP certification across slaughterhouse and distribution networks. Riyadh and Jeddah processing clusters concentrate halal-certified infrastructure, with distributors consolidating supplier bases to meet compliance deadlines.
United Arab Emirates
Dubai's quick-service restaurant chains and hotel foodservice sectors scale chilled protein imports to serve tourism and expatriate consumption. MOHAP and ESMA coordinate import licensing and labeling standards that filter supplier market access. Jebel Ali logistics corridors enable re-export positioning toward African and South Asian markets with halal certification documentation.
Qatar
State-led food security investments accelerate domestic poultry farm development to reduce import dependency following trade disruption experiences. National food storage and strategic reserve programs mandate minimum local production quotas. Doha-based distribution networks prioritize cold-chain reliability for institutional catering and retail channels serving World Cup legacy hospitality infrastructure.
Kuwait
Public-private partnership frameworks incentivize private sector investment in slaughterhouse modernization and feed milling capacity. Ministry of Commerce and Industry oversight aligns import regulations with Gulf Cooperation Council harmonization efforts. Shuwaikh industrial zone processors upgrade temperature-controlled storage to meet evolving regional standards and secure cross-border supply contracts.
Egypt
Nile Delta poultry operations supply affordable protein to price-sensitive household segments across Greater Cairo and Alexandria metropolitan corridors. Government feed subsidy programs partially offset international grain price volatility for domestic producers. Alexandria port infrastructure handles frozen beef and lamb imports serving both local consumption and transit trade toward Gulf markets.
Middle East Animal Protein Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with feed-to-retail control separating scale players from margin-pressed distributors. National champions leverage captive grain milling and hatchery operations to secure supply continuity against import volatility. Strategic archetypes include backward-integrated poultry conglomerates, halal-certified red meat importers, and emerging precision-fermentation feed technology developers. Competitive moves concentrate on slaughter capacity expansion and cold-chain infrastructure partnerships to meet tightened SFDA compliance windows.
Within the integrated leader tier, Almarai and Tanmiah exemplify feed-to-retail control models spanning Saudi production geographies. Al Islami Foods occupies a position among specialized halal protein processors serving Gulf foodservice channels. These anchors illustrate how veterinary expertise and certification infrastructure function as competitive moats in a market where regulatory compliance timelines constrain facility licensing.
| Leading Market Players |
|---|
| Almarai |
| Tanmiah |
| Americana Group |
| National Poultry Company |
| Al Islami Foods |
| Sunbulah Group |
| National Feed and Flour Production and Marketing |
| ARASCO |
| Baladna |
| Others |
Supply & Pricing Matrix
Domestic broiler production replacing Australian and South American beef imports is compressing protein price spreads across Saudi Arabia and the UAE while redistributing sourcing geography toward Riyadh-based processing clusters and away from Jeddah port clearance dependencies.
Pricing Analysis
Price spreads between chilled premium cuts and frozen economy broiler portions widen by certification tier and cold-chain service level rather than raw commodity grade alone. Australian grain-fed beef commands premium positioning in Dubai hotel foodservice channels, while domestic Saudi poultry undercuts import parity through Vision 2030 production subsidies. Pricing pressure intensifies in wholesale frozen segments as SFDA traceability mandates raise compliance costs for smaller distributors. Quick-service restaurant chains exhibit lowest price sensitivity due to volume contract structures, whereas independent caterers face margin compression from certification documentation requirements.
Supply Chain Analysis
Strait of Hormuz transit vulnerability concentrates risk for Brazilian and Australian beef shipments serving UAE re-export hubs and Saudi retail channels. Feed grain sourcing draws from Black Sea corn corridors and Brazilian soybean export terminals, exposing poultry operations to commodity volatility and currency fluctuation. Single-source dependency on Jebel Ali and Jeddah port cold-chain infrastructure creates bottleneck exposure during peak religious demand periods. Distribution runs through HACCP-certified wholesale layers to quick-service chains, with emerging direct-to-consumer platforms disintermediating traditional retail counter relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against precision-fermentation protein substitutes gaining traction in poultry feed applications and alternative protein positioning, requiring strategic positioning before cost parity erodes conventional feed conversion advantages.
For Market Incumbents: Fortify backward integration into captive hatchery and feed milling capacity to secure margin control against imported grain price volatility. Lock in multi-year halal certification infrastructure partnerships before SFDA licensing timelines extend further. Defensive consolidation around veterinary-slaughter expertise creates moats as facility approval queues lengthen across Riyadh and Jeddah processing zones.
For New Entrants and Emerging Players: Lead with subscription-based fresh meat delivery platforms targeting Riyadh and Dubai urban households seeking portion-controlled convenience outside traditional wholesale layers. White-space concentration exists in precision-fermentation feed inputs for poultry and aquaculture diets, reducing grain import exposure. Direct-to-consumer channel partnerships with last-mile logistics operators offer fastest penetration path versus contested retail shelf access.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated poultry conglomerates with captive grain milling and established SFDA certification infrastructure spanning feed-to-retail operations. Long-term viability favors asset-heavy players controlling upstream inputs rather than pure-play distribution entities exposed to compliance cost escalation. Monitor blockchain-enabled cold-chain tracking adoption rates as inflection signal for regulatory compliance differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Milling | Captive grain processing insulates Almarai and Tanmiah from international corn price volatility. |
| SFDA Cold-Chain Certification Investment | Blockchain-enabled traceability systems secure import licenses for Jeddah and Riyadh distribution networks. |
| Subscription Delivery Platform Launch | Direct-to-consumer channels bypass traditional wholesale layers serving Dubai and Riyadh urban households. |
| Precision Fermentation Feed Partnership | Novel protein sources reduce grain import dependency for Saudi poultry and aquaculture operations. |
| UAE Re-Export Hub Positioning | Jebel Ali logistics infrastructure enables halal-certified access to African and South Asian markets. |
Research Methodology
Cross-validation between regulatory filing analysis and trade flow databases anchors the qualitative findings on halal certification infrastructure and cold-chain compliance patterns. Primary interviews with SFDA compliance officers, poultry operations directors, quick-service restaurant procurement heads, and cold-chain logistics operators combined with secondary validation against Saudi customs records, UAE MOHAP licensing databases, and Gulf Cooperation Council harmonization directives. Bottom-up capacity modeling and top-down consumption estimation triangulate volume figures across the analysis window.
Sensitivity analysis on feed grain price scenarios and regulatory timeline slippage frames the projection methodology. Segmentation dimensions span product type, distribution channel, end-user application, and certification tier across Saudi Arabia, UAE, Qatar, Kuwait, and Egypt production and consumption clusters. CAGRs derive from installed base expansion rates and per-capita protein consumption trajectory modeling. Forecast inputs incorporate Vision 2030 food security program targets and SFDA phased implementation schedules for traceability mandates.
The analysis sits within stated boundaries; outcomes outside sustained government subsidy levels and stable Gulf Cooperation Council trade frameworks would require recalibration. Forecasts reflect documented assumptions on domestic production capacity buildout and import substitution rates. Practitioners should keep alternative scenarios live as precision-fermentation feed cost curves and blockchain traceability adoption timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Dairy Cattle Feed Market
Agriculture and Agri Products
Thailand Compound Feed Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Seaweed Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Organic Hemp Market
Agriculture and Agri Products
Canada Animal Protein Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Global Vermicompost Market