
 Bahrain Fisheries and Aquaculture Market | 2026-2036
Bahrain Fisheries and Aquaculture Market Size, Share, and Industry Trends Forecast 2026-2036
Bahrain Fisheries and Aquaculture Market Outlook
Modular processing configurations are repositioning buyer choice across Bahrain's seafood supply chain. Alba Fish Farm leverages integrated hatchery-to-harvest operations to control broodstock quality. Gulf Seafood anchors its position through cold-chain distribution into Saudi Arabia and Kuwait. Banader Fish Processing and Distribution Co. specializes in value-added fillet packs for Bahrain's retail sector.
Fisheries and aquaculture encompasses the breeding, rearing, harvesting, and processing of finfish, shellfish, crustaceans, and aquatic plants in marine, brackish, and freshwater environments, typically operating salinity thresholds between 15–35 ppt for marine species and controlled temperature ranges of 22–28°C for optimal growth cycles. The sector serves commercial food production, protein security, and export revenue generation for island economies with limited terrestrial agriculture. Finfish dominates production volume due to established sea bream and sea bass hatchery protocols, while shellfish cultivation remains nascent with higher per-unit margins. Recirculating aquaculture systems attract capital inflows as land-based facilities reduce dependency on coastal water quality fluctuations.
Bahrain's Ministry of Municipalities Affairs and Agriculture administers aquaculture licensing and coastal zone permits, while the Bahrain Food Safety Authority enforces HACCP standards for seafood processing facilities. The General Directorate of Marine Resources monitors wild stock quotas and habitat protection in territorial waters. Stakeholders must track regulatory adjustments to offshore cage culture permits and evolving export certification requirements for Gulf Cooperation Council markets.
Market Dynamics
Recirculating aquaculture systems are compressing the traditional hatchery-to-harvest timeline across Bahrain's coastal operations, forcing established farms to reconfigure water treatment infrastructure or cede market position to land-based entrants with controlled-environment protocols.
Growth Catalysts
- Hospitality procurement concentration:Manama's restaurant clusters now contract directly with farms for live sea bream delivery, bypassing wholesale intermediaries and locking in volume commitments.
- Coastal licensing framework:The Ministry of Municipalities Affairs and Agriculture's streamlined environmental permits for Hawar Islands sites accelerates farm expansion into previously restricted zones.
- Export corridor activation:Cold-chain infrastructure investments enable same-day delivery to Saudi Arabia and Kuwait, opening premium pricing tiers for Bahraini producers.
Market Restraints
- Broodstock import dependency:Domestic hatcheries source 90% of sea bass and sea bream fry from Cyprus and Greece, exposing operations to Mediterranean supply shocks and currency volatility.
- Coastal water quality degradation:Algal bloom frequency in territorial waters forces cage operators to relocate stock or install costly oxygenation systems.
- Land scarcity for RAS expansion:Industrial zoned plots near Muharraq command premium lease rates that compress project IRRs below regional benchmarks.
Strategic Opportunities
- Shellfish cultivation white space:Oyster and mussel farming protocols adapted from Mediterranean operations await commercial deployment in Bahrain's northern waters.
- HACCP certification arbitrage:The Bahrain Food Safety Authority's accelerated inspection program for export-ready facilities creates first-mover advantage for GCC market access.
- Integrated algae-fish systems:Biofloc technology convergence with finfish production enables nutrient recycling and reduced feed input costs for pilot operators.
Industry Challenges
- RAS engineering talent scarcity:Water chemistry specialists and biofilter technicians command 40% wage premiums over conventional farm managers, constraining expansion timelines.
- Multi-agency compliance sequencing:Coastal permits from the Ministry, HACCP validation from the Food Safety Authority, and export certification from the General Directorate of Marine Resources create overlapping review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bahrain Fisheries and Aquaculture Market |
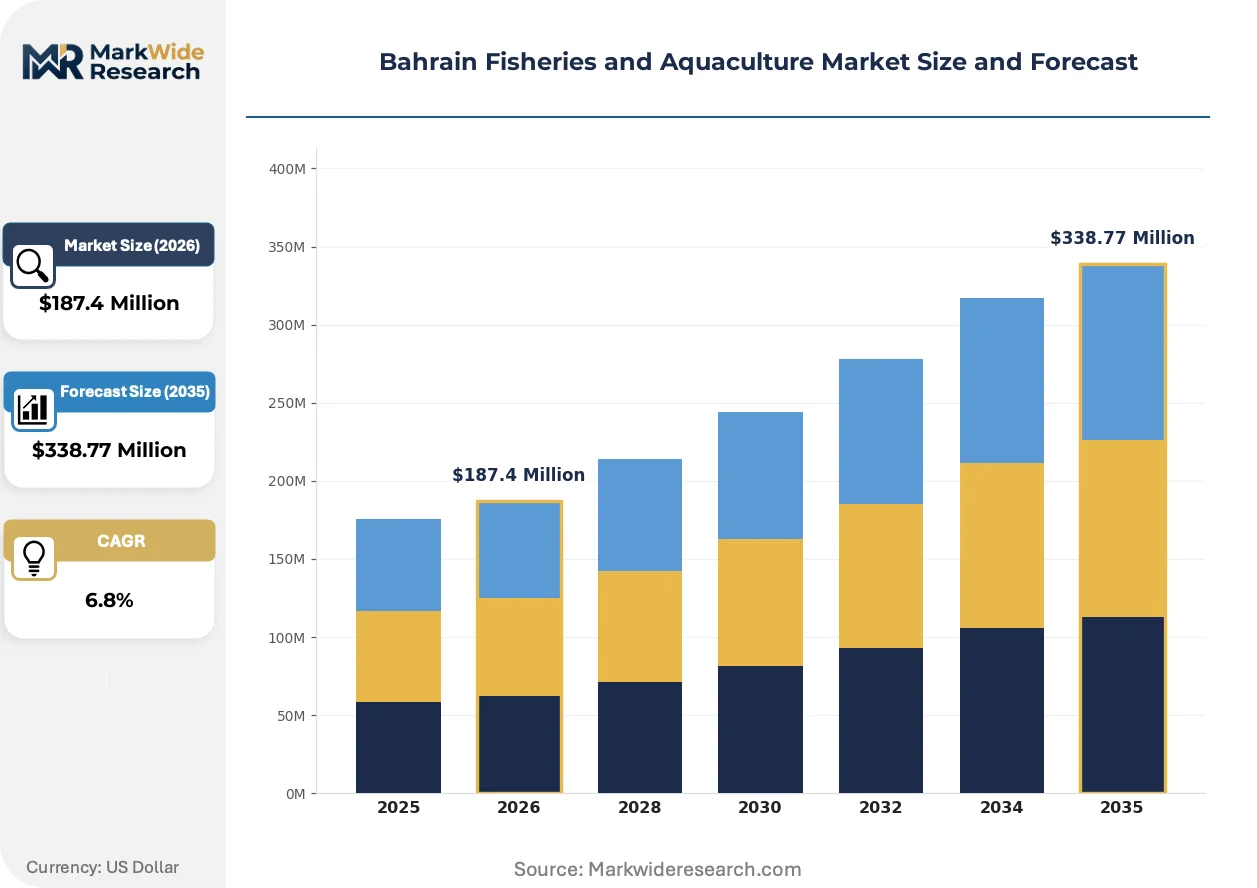
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Finfish, Shellfish, Crustaceans, Aquatic Plants End User: Food Service, Retail, Direct Sales, Export Distribution Channel: Wholesale, Online, Supermarket, Fishermen's Markets Technology: Recirculating Systems, Open Ocean, Cage Culture, Hatchery Systems |
| Companies Covered | Alba Fish Farm, Fish World, Shell Fisheries Company, Gulf Seafood, Al Rawdah Fish Company, Century Fisheries Company, Banader Fish Processing and Distribution Co., Alia Fish Processing Industries, Bahrain National Seafood Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bahrain Fisheries and Aquaculture Market Strategic Shifts
Sensor-driven water quality monitoring is displacing manual testing regimes across Bahrain's aquaculture operations, compressing response times to dissolved oxygen crashes and enabling predictive mortality prevention.
Automated feeding systems with computer vision are consolidating feed conversion efficiency gains across mid-scale sea bream operations. Farms deploying camera-based biomass estimation reduce feed waste by calibrating ration to actual growth rates rather than scheduled protocols. The technology is compressing cost differentials between established coastal cage farms and new RAS entrants.
The Ministry of Municipalities Affairs and Agriculture is tightening offshore cage culture permits through revised environmental impact assessments. Operators must now submit benthic monitoring data quarterly rather than annually, increasing compliance overhead. Farms near the Hawar Islands are responding by clustering into cooperative monitoring pools to share laboratory costs.
Direct sourcing contracts are displacing auction-based wholesale transactions across Bahrain's hospitality procurement channels. Restaurant groups in Manama's Seef and Adliya districts now negotiate annual volume agreements with named farms, securing traceability documentation for menu marketing. This pattern is most visible in premium hotel seafood programs competing on provenance claims.
Bahrain Fisheries and Aquaculture Market Segmentation
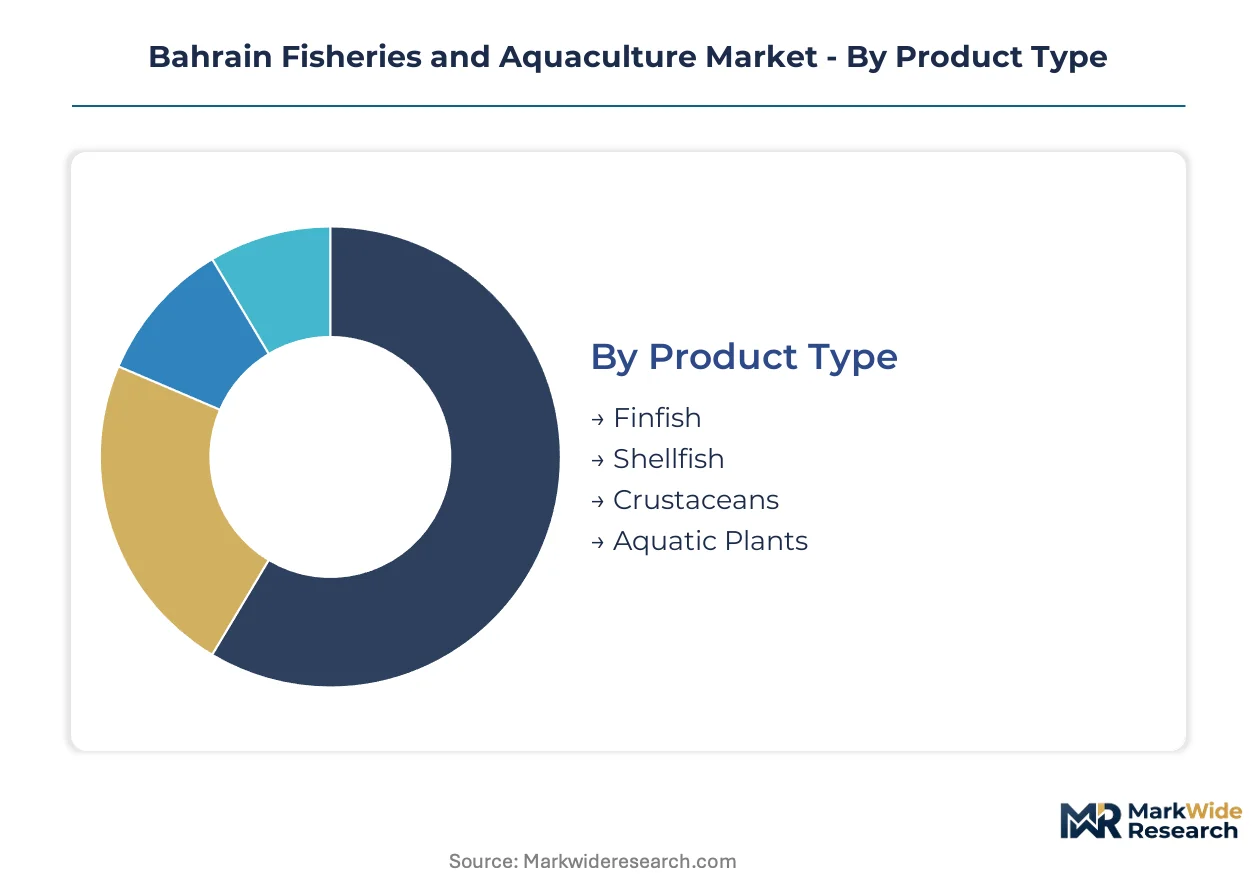
Procurement patterns across Bahrain's seafood supply chain diverge sharply by buyer type and operational scale. Segment boundaries determine pricing power, regulatory exposure, and technology adoption timelines for producers serving Manama's hospitality clusters and GCC export corridors.
Product Type:
Buyer specifications for protein format and preparation convenience dictate farm-level investment priorities and hatchery broodstock selection.
- Finfish:Sea bream and sea bass dominate production volumes through established Mediterranean hatchery protocols. Manama's restaurant clusters contract directly for live delivery, locking in traceability documentation for menu provenance claims.
- Shellfish:Oyster and mussel farming remains commercially underdeveloped despite favorable northern water conditions. Higher per-unit margins attract pilot operators adapting Mediterranean cultivation protocols to Bahrain's salinity profiles.
- Crustaceans:Shrimp and prawn operations face temperature management constraints in coastal cage systems.
- Aquatic Plants:Seaweed and algae cultivation serves niche nutraceutical and feed additive markets with limited domestic processing infrastructure.
Finfish leads on scale; shellfish leads on momentum.
End User:
Volume concentration and margin capture vary by channel access requirements and certification burdens.
- Food Service:Hotels and restaurants in Seef and Adliya districts negotiate annual volume agreements bypassing wholesale intermediaries. Live tank delivery and same-day freshness specifications command premium pricing tiers.
- Export:Cold-chain investments enable same-day delivery to Saudi Arabia and Kuwait. HACCP certification from the Bahrain Food Safety Authority creates first-mover advantage for GCC market access.
- Retail:Supermarket chains and independent fishmongers source value-added fillet packs for household consumption.
- Direct Sales:Fishermen's market stalls and farm-gate transactions serve price-sensitive local buyers with minimal processing overhead.
Food service captures margin; export captures growth trajectory.
Distribution Channel:
Logistics infrastructure and buyer proximity determine working capital intensity and spoilage risk allocation.
- Wholesale:Centralized auction houses and cold storage facilities aggregate catch from multiple operators for redistribution to retail and food service buyers.
- Supermarket:Chained retail formats demand consistent supply volumes and packaged presentation standards.
- Online:E-commerce platforms for fresh seafood delivery remain nascent with last-mile temperature control challenges.
- Fishermen's Markets:Traditional landing-site sales concentrate in Muharraq and Manama waterfront districts with minimal regulatory oversight.
Wholesale dominates volume throughput; supermarket formats gain share fastest.
Technology:
Capital deployment and environmental compliance exposure hinge on production system selection.
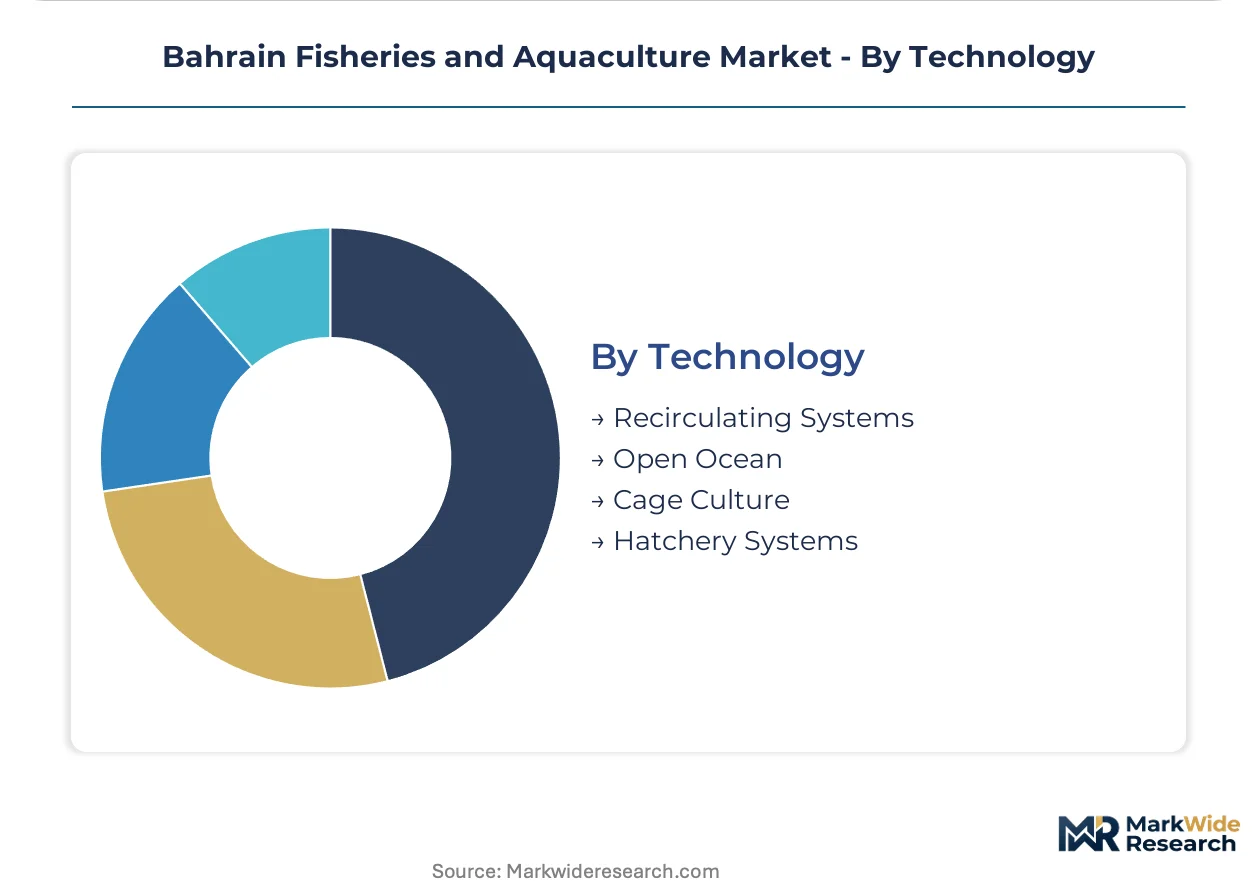
- Recirculating Systems:Land-based RAS facilities compress hatchery-to-harvest timelines through controlled water chemistry. Industrial zoned plots near Muharraq command premium lease rates that constrain project returns.
- Cage Culture:Offshore net pen operations near the Hawar Islands face tightened environmental permits with quarterly benthic monitoring requirements. Algal bloom frequency forces oxygenation system investments or stock relocation.
- Open Ocean:Extensive aquaculture in territorial waters operates under General Directorate of Marine Resources quotas with habitat protection constraints.
- Hatchery Systems:Broodstock quality control depends on fry imports from Cyprus and Greece, exposing operations to Mediterranean supply shocks.
Cage culture maintains installed base; recirculating systems climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Traditional pearl diving communities along Bahrain's coastline evolved into structured aquaculture operations during the late twentieth century, establishing the island's foundational expertise in marine resource management. This heritage now supports integrated finfish production systems serving hospitality and export channels across the Gulf Cooperation Council.
Manama Capital District
Seef and Adliya restaurant clusters contract directly with coastal farms for live sea bream delivery, bypassing wholesale intermediaries. The Bahrain Food Safety Authority enforces HACCP standards for seafood processing facilities operating within municipal boundaries. Cold-chain distribution hubs in the capital enable same-day delivery to Saudi Arabia and Kuwait.
Muharraq Industrial Zone
Recirculating aquaculture system operators concentrate land-based facilities near industrial zoned plots despite premium lease rates. The Ministry of Municipalities Affairs and Agriculture administers environmental permits for coastal zone development. RAS engineering talent scarcity forces wage premiums of forty percent above conventional farm management roles.
Hawar Islands
Sea bream and sea bass cage culture operations cluster in previously restricted marine zones following streamlined licensing frameworks. Quarterly benthic monitoring requirements replace annual submissions, increasing compliance overhead for offshore net pen operators. Cooperative monitoring pools share laboratory costs among clustered farms.
Northern Governorate Waters
Oyster and mussel farming pilot operators adapt Mediterranean cultivation protocols to local salinity profiles. The General Directorate of Marine Resources monitors habitat protection constraints in territorial waters. Shellfish cultivation remains commercially underdeveloped despite favorable conditions and higher per-unit margins.
Southern Governorate Coast
Fishermen's market stalls concentrate in waterfront districts with minimal regulatory oversight for direct sales. Traditional landing-site transactions serve price-sensitive local buyers. Limited processing infrastructure constrains value-added product development in this sub-region.
Bahrain Fisheries and Aquaculture Market Competitive Environment
Premium-margin players sit above commodity-margin players across traceability and live-delivery capabilities. The vendor base spans integrated hatchery-to-harvest operators, cold-chain distributors, and value-added processors with divergent capital intensity requirements. Three archetypes dominate: vertically integrated farm-to-table specialists, logistics-focused export enablers, and retail-packaging processors. Competitive moves center on direct sourcing contracts with hospitality groups and cooperative environmental monitoring arrangements.
Among Bahrain-based integrated operators, Alba Fish Farm exemplifies the hatchery-to-harvest archetype through captive broodstock quality control. Gulf Seafood anchors the cold-chain distribution tier with corridor access into neighboring GCC markets. Banader Fish Processing and Distribution Co. occupies a position within the value-added segment, specializing in retail-format fillet packs. These three entities represent distinct strategic postures without overlapping core capabilities.
| Leading Market Players |
|---|
| Alba Fish Farm |
| Fish World |
| Shell Fisheries Company |
| Gulf Seafood |
| Al Rawdah Fish Company |
| Century Fisheries Company |
| Banader Fish Processing and Distribution Co. |
| Alia Fish Processing Industries |
| Bahrain National Seafood Company |
| Others |
Value Chain & Pricing Dynamics
Family-owned coastal farms across Bahrain's Hawar Islands and Muharraq zones anchor supply-side pricing discipline through multi-generational holding patterns that resist margin compression. Their captive relationships with Seef and Adliya restaurant clusters lock in volume commitments, insulating premium live-delivery tiers from spot-market volatility.
Pricing Analysis
Three-tier pricing structure across premium live-delivery, standard chilled fillet, and economy frozen bulk channels segments buyer access by freshness specification and traceability documentation. Price differentiation hinges on HACCP certification tier from the Bahrain Food Safety Authority and live-tank delivery capability to Manama hospitality clusters. Pricing pressure stems from broodstock import costs tethered to euro-denominated Mediterranean fry contracts. Food service buyers in premium hotel seafood programs show least price sensitivity; retail supermarket chains exhibit highest elasticity.
Supply Chain Analysis
Broodstock supply rests on Cyprus and Greece hatchery specialists, with fry shipments constituting ninety percent of domestic sea bream and sea bass seed stock. Feed inputs draw from Norwegian and Chilean marine ingredient processors; cold-chain equipment sources from South Korean and German manufacturers. Single-source vulnerability concentrates in Mediterranean fry supply, exposing operations to currency volatility and shipping disruptions. Distribution runs through farm-direct contracts to hospitality clusters, with wholesale auction houses handling residual retail and export volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bahrain's fisheries sector reads as a late-cycle quality story as GCC hospitality procurement shifts toward traceable live-delivery specifications that command sustained premium capture.
For Market Incumbents: Acquire RAS engineering capabilities to compress hatchery-to-harvest timelines and defend against land-based entrants with controlled-environment protocols. Deepen backward integration into broodstock quality control to reduce Cyprus and Greece fry dependency. Prioritize cooperative benthic monitoring pools near Hawar Islands to distribute quarterly compliance overhead. For New Entrants and Emerging Players: The Ministry of Municipalities Affairs and Agriculture's streamlined environmental permits for Hawar Islands sites opens a window for cage culture expansion into previously restricted marine zones. Target shellfish cultivation white space in Northern Governorate waters where oyster and mussel protocols await commercial deployment. Lead with HACCP certification arbitrage to secure first-mover GCC export access. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale cage operators facing quarterly monitoring cost escalations without cooperative infrastructure. Long-term viability favors integrated hatchery-to-harvest specialists with captive broodstock and direct hospitality contracts. Watch algal bloom frequency in territorial waters as inflection indicator for oxygenation system capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Recirculating Aquaculture System Deployment | Land-based RAS facilities reduce coastal water quality dependency for Bahraini producers. |
| Cooperative Benthic Monitoring Pool | Shared laboratory costs distribute quarterly compliance burden among Hawar Islands operators. |
| HACCP Certification Fast-Track | Accelerated Bahrain Food Safety Authority inspection unlocks premium GCC export corridors. |
| Direct Sourcing Contract Negotiation | Annual volume agreements with Seef and Adliya restaurant clusters bypass wholesale intermediaries. |
| Shellfish Cultivation Protocol Adaptation | Mediterranean oyster and mussel techniques adapted to Northern Governorate salinity profiles. |
Study Parameters
Coverage spans Bahrain's five governorates with primary inputs from each, combining structured interviews with hatchery operations managers, seafood processing facility compliance officers, hospitality procurement directors at Seef and Adliya restaurant clusters, and cold-chain logistics coordinators. Secondary validation draws from Bahrain Food Safety Authority HACCP registration databases, General Directorate of Marine Resources wild stock quota filings, Ministry of Municipalities Affairs and Agriculture coastal permit records, and GCC customs trade flow data. Bottom-up farm production estimates and top-down hospitality demand sizing triangulate volume figures.
Granularity-level modeling spans product type dimensions including finfish, shellfish, crustaceans, and aquatic plants; end-user channels covering food service, export, retail, and direct sales; technology tiers across recirculating systems, cage culture, open ocean, and hatchery systems; plus geographic segmentation across Manama, Muharraq, Hawar Islands, Northern Governorate, and Southern Governorate. CAGRs derive from regression analysis of historical production volumes against regulatory event timelines and infrastructure investment cycles. Industry-specific inputs include broodstock import dependency ratios and algal bloom frequency indices.
Revisions become necessary when regulatory permit streamlining stalls, Mediterranean fry supply disruptions materialize, or cold-chain infrastructure investments lag projected GCC export corridor activation. Forecasts reflect documented assumptions around licensing timeline acceleration and hospitality procurement pattern stability. A small set of named triggers warrants ongoing watch: coastal water quality degradation indices, RAS engineering wage premium escalation, and multi-agency compliance sequencing bottlenecks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Saudi Arabia Aquaculture Market
Aquaculture Innovations
Thailand Aquafeed Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
Crab Market
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
Fish Farming Equipment Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
South America Aqua Feed Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Norway Aquaculture Market