
 Global Aquafeed Market | 2026-2036
Global Aquafeed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aquafeed Market Analysis
The capital-intensity divergence between integrated multinationals and regional compounders is rotating competitive dynamics across the aquafeed sector. Cargill leverages its oilseed crushing infrastructure to secure cost-advantaged soy protein supplies for salmon and shrimp diets. BioMar Group anchors its position through marine ingredient optimization and species-specific formulation leadership. Skretting competes via precision nutrition platforms that reduce feed conversion ratios in intensive aquaculture systems.
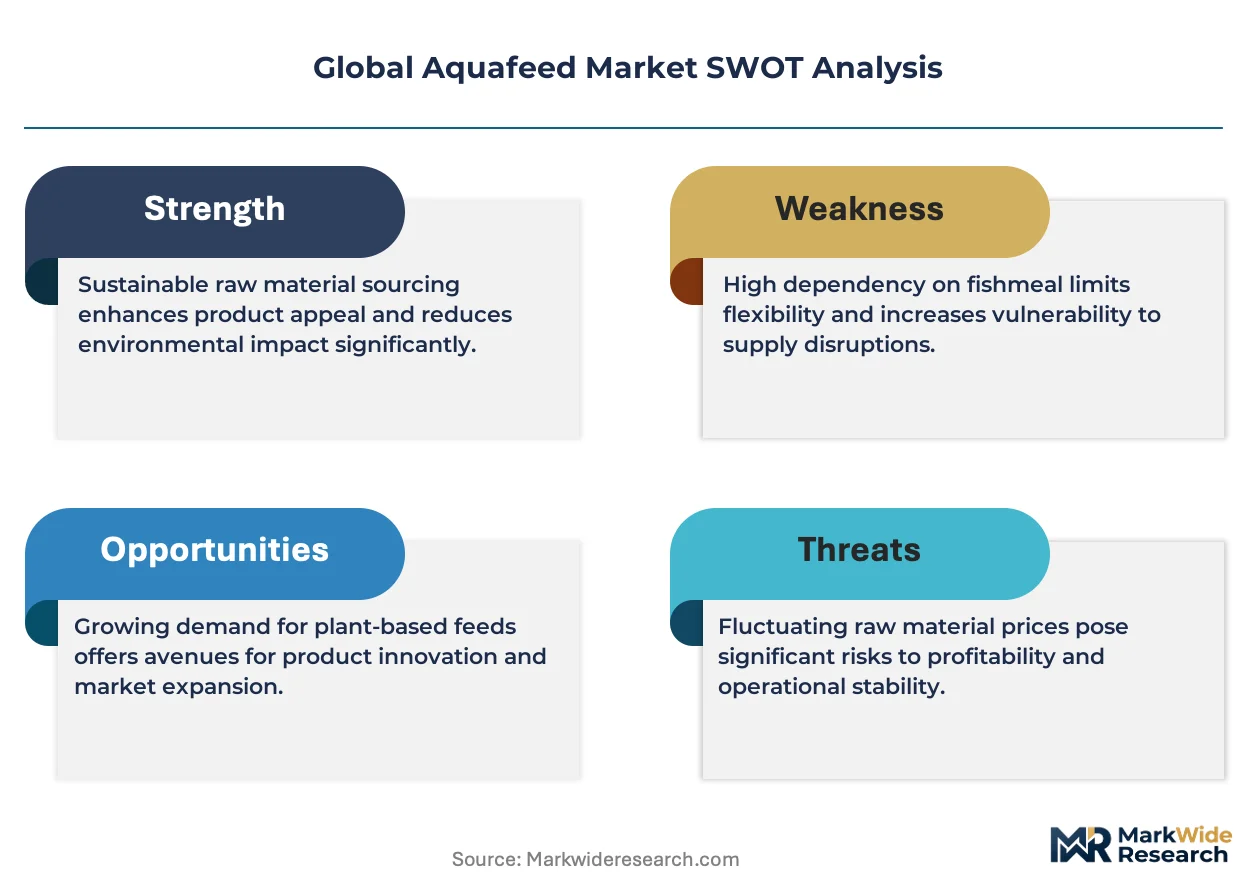
Aquafeed denotes nutritionally complete formulated diets manufactured through extrusion, pelleting, or expansion processes, typically containing 25-50% crude protein from fishmeal, soybean meal, or alternative ingredients, designed to deliver targeted growth rates and health outcomes in farmed aquatic species. Fish feed occupies the dominant volume position given salmonid and tilapia production scale, while shrimp feed commands premium pricing due to higher protein specifications and specialized amino acid profiles. Soybean meal is displacing marine ingredients across multiple formulations as sustainability pressures and price volatility reshape sourcing strategies.
Regulatory oversight from the EU's REACH framework, the FDA's aquaculture drug and feed additive protocols, and China's GB standards collectively determine ingredient approvals, residue limits, and market access conditions for compound feed manufacturers. The EU Green Deal's farm-to-fork targets are tightening environmental performance requirements across European supply chains. Stakeholders must monitor alternative protein certification pathways and evolving maximum residue limits to sustain formulation flexibility and geographic market presence.
Market Dynamics
The EU's F-Gas Regulation is compressing capital deployment timelines for aquafeed manufacturers, forcing accelerated transitions to low-carbon extrusion and drying infrastructure ahead of phasedown mandates.
Growth Catalysts
- Salmonid production expansion:Norwegian aquaculture operators are scaling formulated feed volumes to support offshore cage systems and post-smolt grow-out facilities.
- REACH-compliant ingredient pipelines:Novel protein approvals under ECHA frameworks are unlocking insect meal and single-cell protein inclusion rates above previous limits.
- Shrimp farming corridor densification:Vietnam's Mekong Delta producers are consolidating pond operations, concentrating demand for high-specification feeds with enhanced amino acid profiles.
Market Restraints
- Fishmeal price volatility:Peruvian anchovy quota fluctuations transmit directly into marine protein input costs, compressing margin buffers for compounders without long-term offtake contracts.
- Soy protein supply concentration:Crushing capacity clustering in Brazil and Argentina creates geographic vulnerability for Asian and European feed mills dependent on South American meal.
- Extrusion energy intensity:Thermal processing requirements for floating feeds lock manufacturers into natural gas or electricity exposure without mature alternative heat sources.
Strategic Opportunities
- Indonesian archipelago penetration:Underdeveloped marine cage networks across Sumatra and Sulawesi present volume expansion potential for species-specific formulations.
- EU Green Deal procurement alignment:Farm-to-fork carbon intensity scoring is creating preferential sourcing channels for certified-low-carbon feed suppliers.
- Precision nutrition platform convergence:Integration of real-time biomass monitoring with automated feeding systems is enabling outcome-based contract structures.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in marine ingredient substitution and amino acid balancing remains concentrated among veteran practitioners approaching retirement.
- Alternative protein certification timelines:Novel feed additive approvals under FDA aquaculture protocols and EFSA novel food frameworks extend commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aquafeed Market |
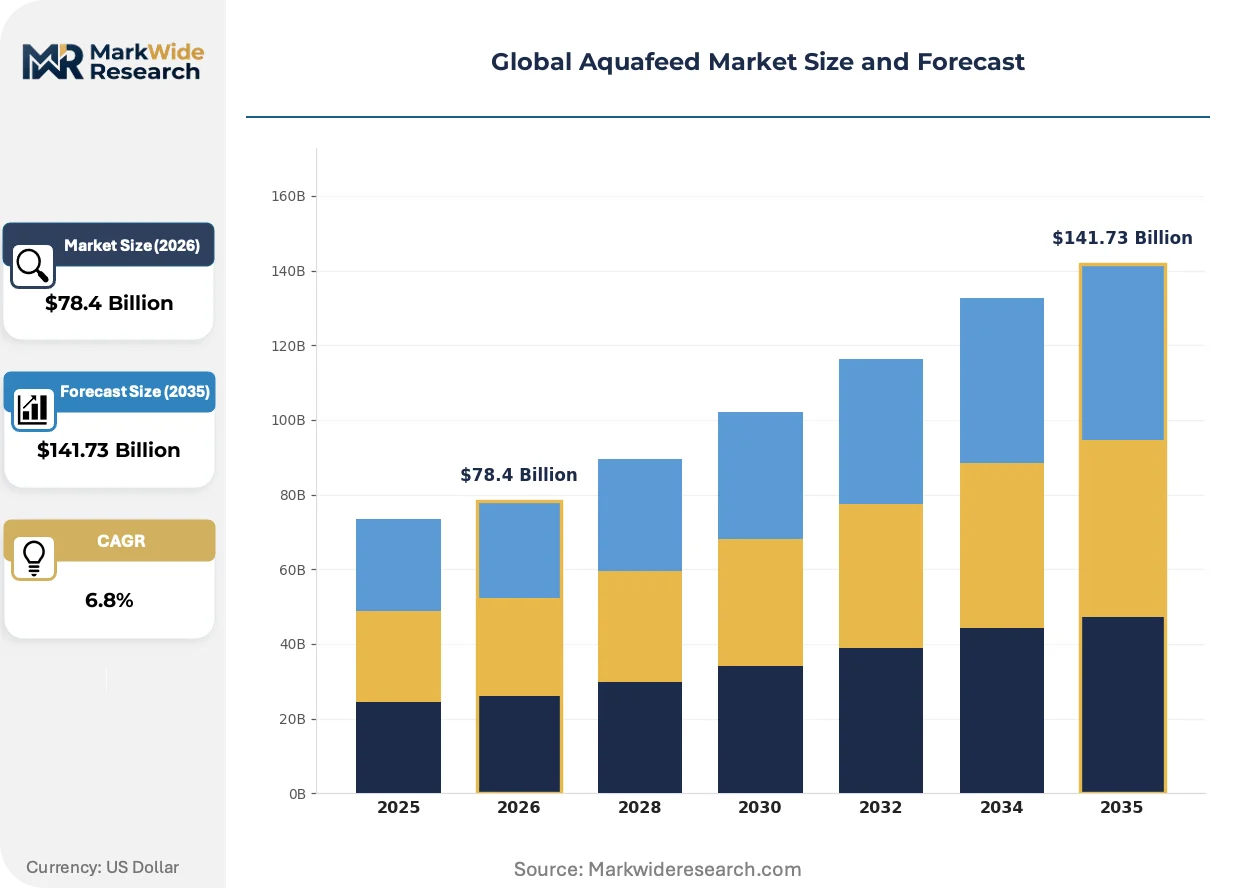
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Feed, Shrimp Feed, Crab Feed, Others Ingredient Type: Fishmeal, Soybean Meal, Corn Gluten Meal, Wheat Gluten End User: Commercial Aquaculture, Subsistence Aquaculture, Research Institutions, Feed Manufacturers Distribution Channel: Online Retail, Food Service, Direct Sales, Distributors |
| Companies Covered | Skretting, Aller Aqua Group, Cargill, dsm-firmenich, Charoen Pokphand Foods PCL, BioMar Group, Archer Daniels Midland Company, Alltech, Nutreco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aquafeed Market Emerging Trajectories
Active reformulation programs are compressing marine dependency ratios while digital feeding systems rewrite operational economics across intensive aquaculture zones.
Single-cell protein derived from methanotrophic bacteria is miniaturizing the functional role of fishmeal in salmonid grower diets. Norwegian and Chilean producers are accelerating inclusion trials beyond 15% substitution thresholds. This protein source is miniaturizing the marine ingredient footprint of premium feeds without compromising growth performance metrics.
The EU's F-Gas Regulation mandates progressive hydrofluorocarbon phase-downs through 2030, forcing extrusion dryer retrofits or replacement. Capital allocation is shifting toward heat pump and electric thermal oil systems. European compounders face the steepest compliance curves, with Nordic operators already deploying low-carbon infrastructure ahead of enforcement windows.
Buyer consolidation among integrated shrimp conglomerates is compressing supplier negotiation cycles and demanding volume-backed pricing guarantees. Traditional distributor networks in Southeast Asia are losing share to direct mill-to-farm contracts. This pattern is most pronounced in Vietnam's Mekong Delta, where top-ten producers now control majority off-take volumes.
Global Aquafeed Market Segmentation
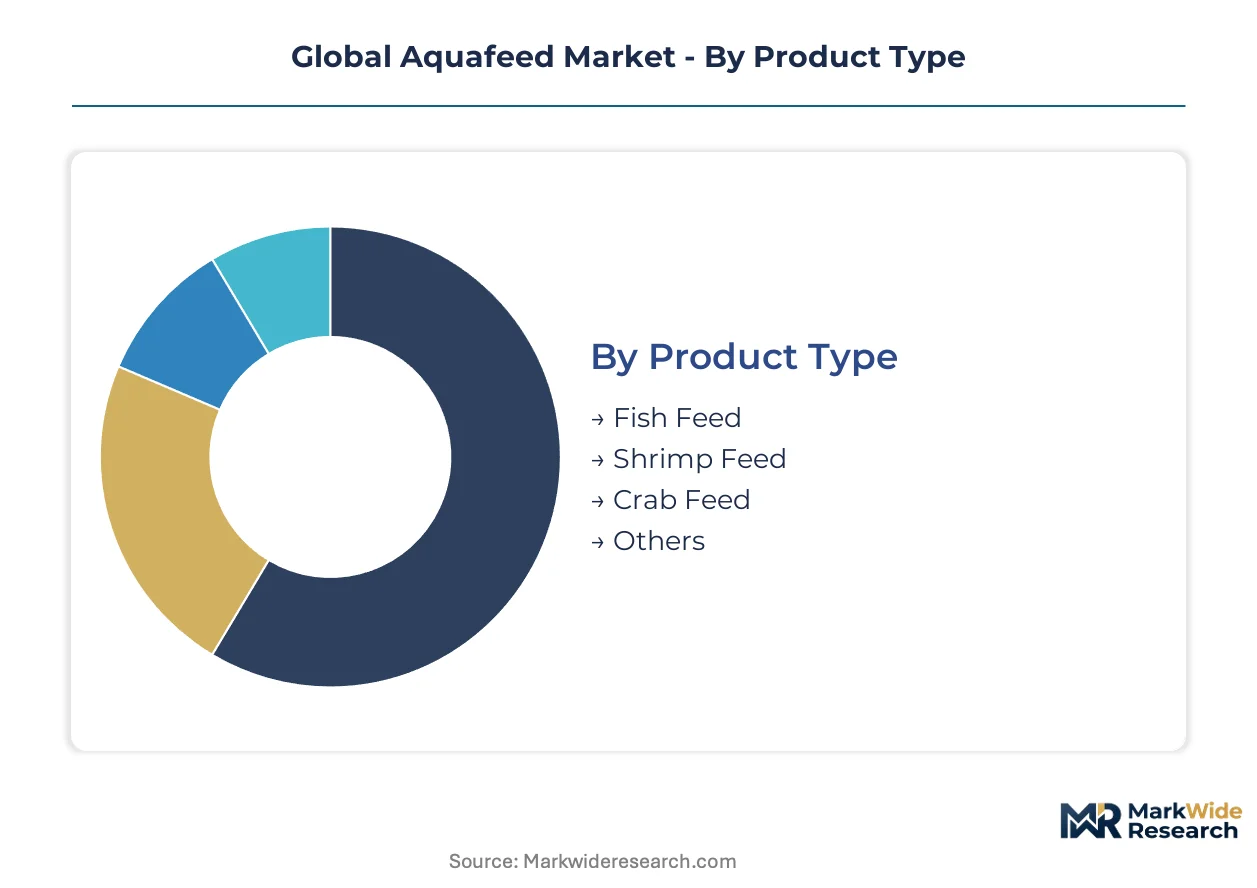
Aquafeed segmentation reveals how formulation chemistry, species physiology, and procurement channels intersect. Product type and ingredient sourcing decisions cascade through distribution architectures and end-user procurement patterns.
Product Type:
Fish feed flows through mill-direct channels to large-scale salmonid and tilapia operations, while shrimp feed concentrates in specialized distributor networks serving intensive pond systems.
- Fish Feed:Formulations contain 25-40% crude protein with extruded floating or sinking pellet structures calibrated to salmonid, tilapia, or carp digestive physiology. Norwegian offshore cage operators and Vietnamese pangasius pond systems drive volume concentration as producers scale post-smolt grow-out facilities.
- Shrimp Feed:Higher protein specifications at 35-50% with specialized amino acid profiles including taurine and phospholipid enrichment for crustacean molting cycles. Vietnam's Mekong Delta corridor concentrates demand as top-ten producers consolidate pond operations and shift from distributor networks to direct mill contracts.
- Crab Feed:Slow-sinking pellet formulations with enhanced chitin content for portunid and grapsid species in East Asian soft-shell production.
- Others:Specialized diets for mollusk, eel, and ornamental species occupying niche formulation tiers.
By volume, fish feed leads. By growth pace, shrimp feed is ahead.
Ingredient Type:
Raw material cost tiers stratify procurement strategies, with marine proteins commanding premium positions against plant-based alternatives reshaping formulation economics.
- Fishmeal:Peruvian anchovy landings and quota fluctuations transmit directly into marine protein pricing. Long-term offtake contracts with Chilean or Mauritanian reduction fisheries defend margin buffers against volatility.
- Soybean Meal:Crushing capacity clustering in Brazil and Argentina creates geographic vulnerability for Asian and European mills. Cargill leverages oilseed infrastructure to secure cost-advantaged supplies.
- Corn Gluten Meal:Yellow protein concentrate from wet milling operations, valued for xanthophyll pigmentation in salmonid flesh coloration.
- Wheat Gluten:European aquafeed compounders source from EU starch processing networks for binder functionality in sinking pellet formulations.
By formulation share, soybean meal dominates. By premium positioning, fishmeal retains the steepest price elevation.
End User:
Customer scale and technical sophistication determine service intensity, with integrated multinationals demanding precision nutrition platforms versus smallholder cooperatives prioritizing price accessibility.
- Commercial Aquaculture:Large-scale salmonid cage operators and shrimp conglomerates in Vietnam, Indonesia, and Ecuador. These buyers negotiate volume-backed pricing and demand real-time biomass monitoring integration.
- Subsistence Aquaculture:Smallholder pond systems across Southeast Asia and sub-Saharan Africa, typically served through cooperative aggregator networks with limited technical extension.
- Research Institutions:Norwegian and Chilean aquaculture research stations conducting inclusion trials for single-cell protein and insect meal substitution thresholds.
- Feed Manufacturers:Regional compounders purchasing premixes and base mixes from multinationals for local blending and distribution.
By revenue concentration, commercial aquaculture leads. By untapped volume potential, subsistence aquaculture shows the steepest expansion trajectory.
Distribution Channel:
Channel selection reflects buyer consolidation trends, with direct mill relationships displacing traditional distributor layers in mature production corridors.
- Direct Sales:Mill-to-farm contracts dominate Vietnam's Mekong Delta and Norwegian salmonid zones as integrated producers consolidate procurement. BioMar and Skretting deploy technical sales teams for precision nutrition platform implementation.
- Distributors:Traditional networks retain share in fragmented Indonesian archipelago markets and emerging African aquaculture zones with underdeveloped logistics infrastructure.
- Online Retail:E-commerce penetration remains limited to hobbyist ornamental feeds and small-scale probiotic supplements rather than bulk formulated diets.
- Food Service:Minimal relevance for aquafeed; this channel serves prepared feed products for aquarium retail rather than production aquaculture.
By volume flow, direct sales leads. By coverage extension, distributors maintain the widest geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Norwegian salmonid corridors while Vietnamese shrimp zones operate on compressed margin structures. This asymmetry shapes capital deployment patterns across formulation facilities and marine ingredient procurement networks.
Norway
Offshore cage expansion and post-smolt grow-out facilities are scaling formulated feed consumption along the Norwegian coastline. The EU F-Gas Regulation mandates hydrofluorocarbon phase-downs through 2030, accelerating heat pump adoption in extrusion infrastructure. Bergen and Trondheim harbor zones concentrate supplier technical service teams for precision nutrition platform deployment.
Vietnam
Mekong Delta shrimp conglomerates are consolidating pond operations and shifting from distributor networks to direct mill contracts. The country's national feed safety regulator enforces GB-aligned maximum residue limits for antibiotic traces in export-bound production. Can Tho and Soc Trang provinces host the densest concentration of high-specification feed demand for intensive crustacean systems.
China
GB standards and dual carbon goals are tightening environmental performance requirements for compound feed manufacturers across coastal provinces. NMPA protocols govern aquaculture drug and feed additive approvals, extending commercialization cycles for novel protein inclusions. Guangdong and Fujian provinces anchor the largest marine cage networks for species-specific formulation volumes.
United States
Catfish pond systems in the Mississippi Delta and emerging recirculating aquaculture operations are diversifying demand beyond traditional channel formulations. FDA aquaculture protocols determine feed additive approvals and residue limits for domestic and export market access. Seattle and Boston harbor zones concentrate supplier R&D coordination for single-cell protein inclusion trials.
Indonesia
Underdeveloped marine cage networks across Sumatra and Sulawesi present volume expansion potential for species-specific formulations serving barramundi and grouper operations. The country's national feed safety regulator monitors aflatoxin thresholds in imported soybean meal shipments. Lampung and South Sulawesi provinces are consolidating smallholder cooperatives into technical extension programs.
Global Aquafeed Market Vendor Landscape
Concentration sits with integrated multinationals possessing captive oilseed crushing infrastructure and marine ingredient offtake contracts. Regional compounders defend position through species-specific formulation expertise and localized technical service density. Three archetypes dominate: agribusiness conglomerates with backward integration into protein supply, marine-focused specialists optimizing fishmeal substitution thresholds, and precision nutrition platforms integrating real-time biomass monitoring. Competitive moves center on low-carbon extrusion infrastructure deployment and direct mill-to-farm contract structures displacing traditional distributor layers.
Within the agribusiness conglomerate tier, Cargill and Archer Daniels Midland Company exemplify scale-driven procurement leverage across soybean meal and corn gluten concentrate networks. BioMar Group and Skretting occupy positions as marine-focused specialists, anchoring formulation leadership through species-specific diet optimization and precision nutrition platform convergence. These five entities collectively represent the competitive core spanning protein supply security, technical service intensity, and sustainability certification alignment.
| Leading Market Players |
|---|
| Skretting |
| Aller Aqua Group |
| Cargill |
| dsm-firmenich |
| Charoen Pokphand Foods PCL |
| BioMar Group |
| Archer Daniels Midland Company |
| Alltech |
| Nutreco |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with Peruvian and Chilean reduction fisheries lock in marine protein supply access while anchoring price visibility against anchovy quota volatility. These structures compress spot market exposure for integrated compounders while transmitting commodity risk to regional mills without captive sourcing infrastructure.
Pricing Analysis
Customization-premium spreads separate species-specific formulations from commodity base mixes. Three-tier pricing structure across premium, standard, and economy levels tracks protein specification density, with salmonid grower diets commanding elevation over tilapia carp feeds. Price differentiation hinges on marine ingredient inclusion rates and sustainability certification alignment. Cost compression in standard tiers intensifies as soybean meal substitution accelerates under EU Green Deal procurement pressure. Smallholder cooperatives in Southeast Asian pond systems exhibit highest price sensitivity, while Norwegian offshore cage operators prioritize feed conversion performance over unit cost.
Supply Chain Analysis
Brazil and Argentina anchor global soybean meal supply, crushing capacity clustering that feeds Asian and European aquafeed production. Peru and Chile draw from anchovy biomass for fishmeal concentration, while Mauritanian and South African reduction fisheries provide alternative marine sourcing. Single-source vulnerability concentrates in South American oilseed infrastructure exposed to climate-driven harvest variability. Distribution runs through direct mill-to-farm channels in consolidated corridors like Vietnam's Mekong Delta, with traditional distributor networks retaining share in fragmented Indonesian archipelago markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against single-cell protein and insect meal displacement of marine ingredients. Incumbents must navigate reformulation economics while preserving growth performance metrics that justify premium positioning.
For Market Incumbents: Consolidate marine ingredient offtake contracts with Mauritanian and Chilean reduction fisheries to defend input cost position against Peruvian anchovy quota compression. Deepen precision nutrition platform integration with Norwegian offshore cage operators to lock in outcome-based contract structures that resist commodity substitution. Prioritize low-carbon extrusion infrastructure deployment ahead of EU F-Gas Regulation enforcement windows.
For New Entrants and Emerging Players: Differentiate on species-specific formulation expertise for underdeveloped Indonesian barramundi and grouper cage networks. Target the subsistence aquaculture segment across sub-Saharan Africa with price-accessible cooperative aggregator models. Penetrate through technical extension partnerships that transfer pond management knowledge alongside feed supply.
For Investors and Strategic Acquirers: Regional compounders with localized technical service density and established distributor relationships in fragmented Southeast Asian markets represent priority acquisition archetypes. Long-term viability hinges on formulation chemist succession planning and alternative protein certification pipeline positioning. Monitor EFSA novel food approval timelines for single-cell protein inclusion rate expansion as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Marine Ingredient Substitution Program | Single-cell protein trials beyond 15% thresholds reduce fishmeal dependency for Norwegian salmonid producers. |
| Low-Carbon Extrusion Retrofit | Heat pump and electric thermal oil systems align with EU F-Gas Regulation phasedown mandates. |
| Direct Mill-to-Farm Contract Expansion | Bypassing distributor layers in Vietnam's Mekong Delta captures volume concentration from shrimp conglomerates. |
| Precision Nutrition Platform Deployment | Real-time biomass monitoring integration enables outcome-based pricing with large-scale cage operators. |
| Alternative Protein Certification Pipeline | FDA aquaculture protocol and EFSA novel food approvals unlock insect meal and bacterial protein commercialization. |
Methodological Framework
A standing panel of aquafeed formulation chemists, marine ingredient procurement directors, and commercial aquaculture operations managers provided ongoing calibration across the study. Primary interviews with species-specific diet specialists, extrusion equipment engineers, and shrimp farm technical officers combined with secondary validation from FAO aquaculture production databases, EFSA novel food submission records, and EU F-Gas Regulation implementation reports. Bottom-up volume modeling across ingredient type and product category segments triangulated against top-down value estimates from compounder revenue disclosures and trade flow analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including species physiology requirements, protein source tier, end-user scale category, and distribution channel structure. CAGRs derived from fitted growth curves incorporating salmonid production expansion trajectories, shrimp farming corridor densification patterns, and regulatory compliance cost pass-through assumptions.
Material uncertainties — Peruvian anchovy quota volatility, novel protein approval timeline delays, and energy transition cost inflation — sit outside the modeled envelope. Forecasts reflect assumptions regarding substitution threshold acceptance and certification pathway progression. Recalibration cycles align with material shifts in marine ingredient availability and EU environmental performance enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
Brazil Fisheries and Aquaculture Market
Aquaculture Innovations
Saudi Arabia Aquaculture Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
North America Shrimp Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
South Korea Aquaculture Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
North America Shrimp Feed Market