
 Bacterial Diagnostics in Aquaculture Market | 2026-2036
Bacterial Diagnostics in Aquaculture Market Size, Share, and Industry Trends Forecast 2026-2036
Bacterial Diagnostics in Aquaculture Market Outlook
Multi-source procurement of molecular reagents is consolidating around a narrower set of qualified suppliers with cold-chain reliability. Thermo Fisher Scientific leverages its Taq polymerase supply scale to anchor regional distribution networks across major aquaculture belts. Qiagen NV competes through automated nucleic acid extraction platforms designed for field-deployable pathogen screening. Zoetis Inc differentiates by integrating veterinary diagnostics with antimicrobial stewardship programs for farm clients.
Bacterial diagnostics in aquaculture encompasses laboratory and point-of-need methods for identifying pathogenic bacteria affecting finfish and shellfish, typically employing nucleic acid amplification with detection thresholds below 10 colony-forming units per milliliter or chromogenic culture media with 18-24 hour incubation protocols. The primary commercial purpose is to enable early disease intervention, reduce antibiotic use, and satisfy export certification requirements for live animals and processed seafood. Molecular diagnostics commands the dominant share of revenue due to multiplex pathogen panels and quantitative sensitivity, while biosensors represent the fastest-expanding technology category as electrochemical and optical transducers achieve portability without sacrificing analytical performance. PCR kits generate the highest margin pools among product formats because proprietary master mixes and primer sets create recurring consumable demand tied to installed thermal cycler bases.
The EU F-Gas Regulation constrains refrigerant-dependent cold-chain logistics for perishable reagent shipments, while EFSA residue monitoring directives mandate documented pathogen testing for antibiotic-free certification. The US FDA enforces Hazard Analysis Critical Control Point protocols that require verified bacterial monitoring in imported aquaculture products. Stakeholders must weigh in-house molecular laboratory buildouts against third-party aquatic veterinary service contracts as pathogen panel complexity and regulatory documentation burdens intensify.
Market Dynamics
Intensifying farm biosecurity protocols across Southeast Asian shrimp and pangasius operations are compressing pathogen detection timelines from 48 hours toward 4-hour turnaround windows, forcing diagnostic workflows toward field-deployable molecular platforms.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain constraints on refrigerant-dependent reagent shipments are accelerating investment in ambient-stable lyophilized PCR master mixes, creating pull for reformulated diagnostic chemistry.
- Shrimp hatchery intensification:Vietnam's Mekong Delta farming clusters now stock densities exceeding 150 post-larvae per square meter, multiplying bacterial outbreak frequency and routine screening volumes.
- Zero-antibiotic residue mandates:EFSA monitoring directives for antibiotic-free seafood certification are embedding pathogen diagnostics into export documentation workflows for European-bound consignments.
Market Restraints
- Taq polymerase supply concentration:Three qualified suppliers control 80% of thermostable enzyme production, exposing regional distributors to allocation risk during influenza vaccine manufacturing surges.
- Reagent cold-chain dependency:Perishable nucleic acid extraction buffers require 2-8°C logistics through tropical last-mile networks, inflating distribution costs and spoilage rates.
- Fluorophore import licensing:Photoluminescent probe chemistries face dual-use biosecurity controls in several Southeast Asian jurisdictions, extending customs clearance timelines.
Strategic Opportunities
- Electrochemical biosensor convergence:Screen-printed electrode platforms paired with smartphone readouts are opening point-of-need deployment in Indonesian smallholder ponds lacking laboratory infrastructure.
- Antimicrobial stewardship integration:Diagnostic-veterinary service bundles that tie test results to treatment protocols represent unbundled revenue pools beyond commodity kit sales.
- Philippine aquaculture expansion:Mindanao tilapia cage farming growth is outpacing local diagnostic capacity, creating first-mover positioning for mobile laboratory services.
Industry Challenges
- Molecular technician scarcity:Nucleic acid amplification competency gaps in provincial veterinary laboratories delay result reporting and erode farm trust in laboratory channels.
- Multiplex panel validation timelines:Regulatory acceptance of 12-pathogen simultaneous detection requires 18-24 month equivalence studies against culture-based reference methods.
- Legacy serology infrastructure:Antibody-based detection systems in government hatcheries resist displacement despite inferior sensitivity for subclinical infections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bacterial Diagnostics in Aquaculture Market |
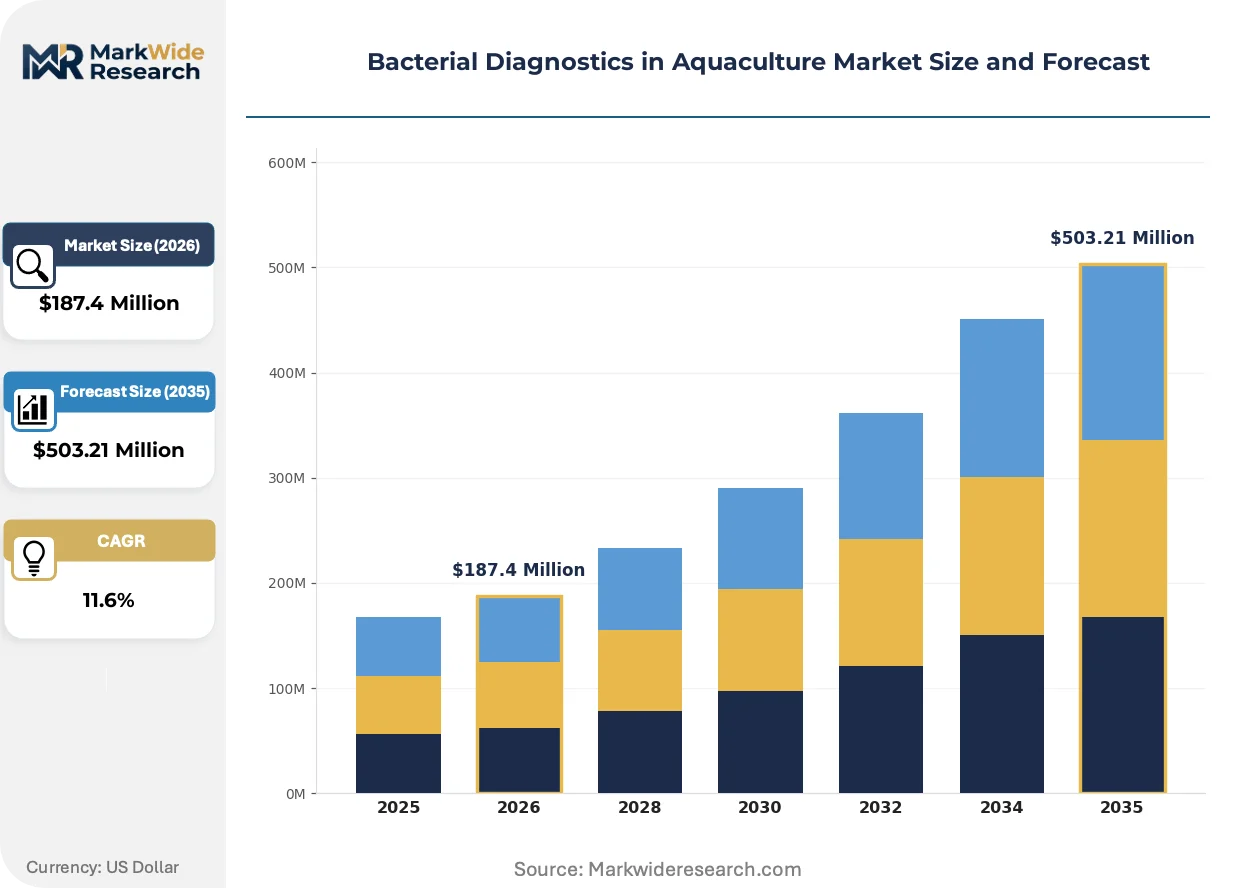
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Kits, Culture Media, Detection Systems, Test Strips End User: Fish Farms, Research Institutions, Aquatic Veterinary Services, Aquaculture Suppliers Technology: Molecular Diagnostics, Immunoassays, Enzymatic Methods, Biosensors Application: Pathogen Detection, Water Quality Testing, Disease Surveillance, Antibiotic Resistance Monitoring |
| Companies Covered | Agilent Technologies, LexaGene, Thermo Fisher Scientific, Zoetis Inc, Aquatic Diagnostics Ltd, IDEXX Laboratories, Qiagen NV, Neogen Corporation, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bacterial Diagnostics in Aquaculture Market Strategic Shifts
Diagnostic platforms are converging toward sample-to-answer automation, compressing technical skill requirements while embedding connectivity for remote veterinary oversight. This convergence is redrawing competitive boundaries between instrument manufacturers and service providers.
Loop-mediated isothermal amplification chemistry is integrating fluorescent probe detection into battery-operated devices for pond-side Vibrio and Aeromonas screening. Indonesian and Vietnamese farm cooperatives are piloting these systems at 200-site density. The technology is integrating veterinary decision support directly into harvest timing and antibiotic withholding protocols, bypassing centralized laboratory bottlenecks.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in reagent cold chains, compelling suppliers to reformulate transport stability or absorb carbon offset costs. Diagnostic distributors serving European export certification markets are consolidating freight consolidation hubs in Rotterdam and Singapore. Ambient-stable lyophilized formats are capturing preference share among logistics-constrained buyers in tropical production zones.
Shrimp hatcheries are consolidating procurement through aquatic veterinary service contracts that bundle diagnostics with biosecurity audits and antimicrobial stewardship compliance. Traditional kit resellers face margin compression as technical service components capture value previously realized through reagent markups. Vietnam's vertically integrated processing exporters are driving this shift fastest, internalizing diagnostic capability to secure EU and US FDA HACCP documentation.
Bacterial Diagnostics in Aquaculture Market Segmentation
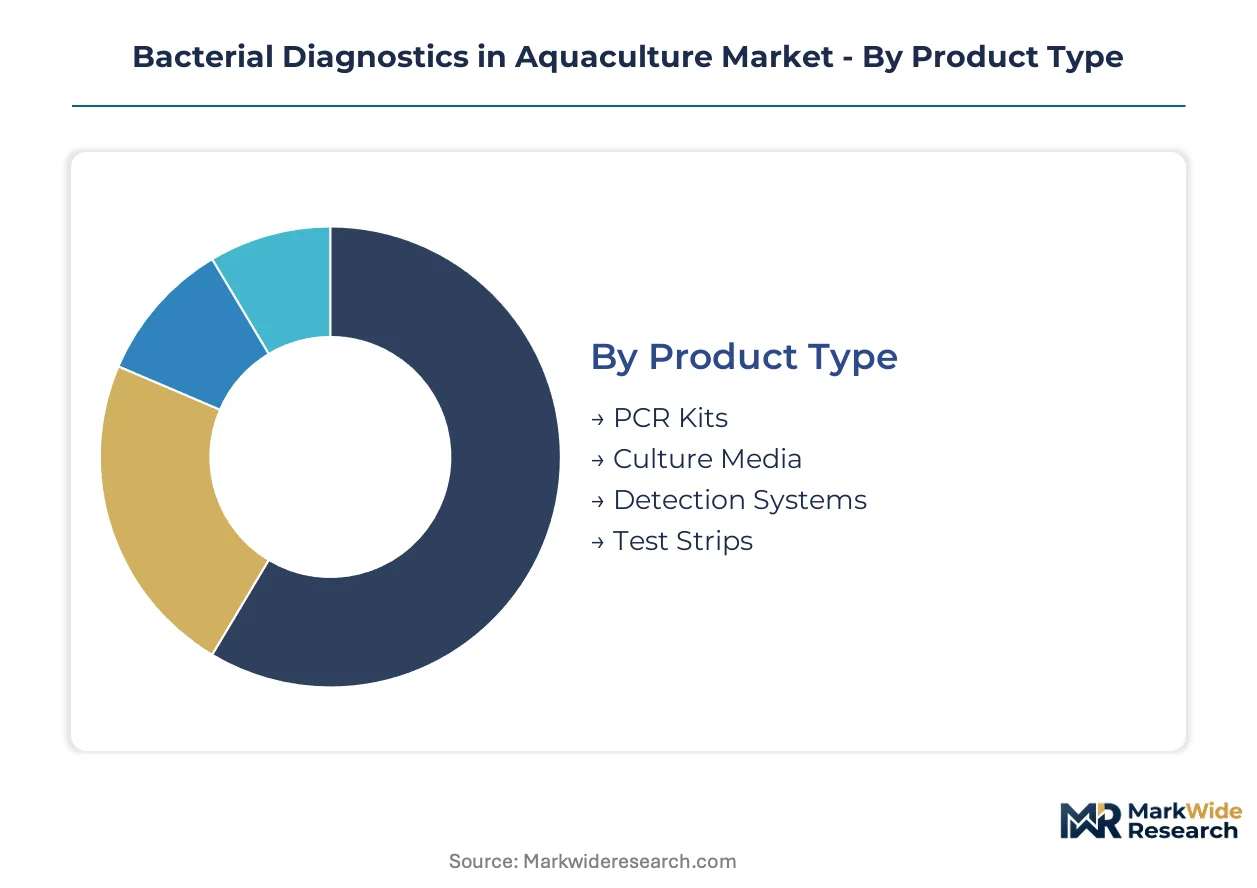
Diagnostic procurement patterns in aquaculture diverge sharply between export-certified operations and domestic-market farms, with technology choice, end-user sophistication, and regulatory documentation requirements driving distinct purchasing behaviors across each segment axis.
Product Type:
Reagent stability and thermal cycling dependency differentiate procurement economics across format categories.
- PCR Kits:Lyophilized master mixes with proprietary primer sets anchor laboratory workflows, with ambient-stable formulations gaining preference in Vietnam's Mekong Delta farming clusters where cold-chain infrastructure remains inconsistent. These kits generate recurring consumable demand tied to installed thermal cycler bases.
- Culture Media:Chromogenic agar formulations with 18-24 hour incubation protocols persist in government hatcheries and smaller operations, constrained by longer turnaround times that conflict with intensifying biosecurity timelines. Legacy infrastructure investment slows displacement despite inferior sensitivity for subclinical infections.
- Detection Systems:Integrated sample-to-answer platforms compress technical skill requirements while embedding connectivity for remote veterinary oversight.
- Test Strips:Lateral flow formats serve rapid screening needs in field conditions with limited laboratory access.
PCR Kits lead on scale; Detection Systems lead on momentum.
End User:
Customer capability and documentation burden shape service bundling opportunities and pricing power.
- Fish Farms:Vietnamese pangasius and shrimp operations drive volume procurement, with vertically integrated exporters internalizing diagnostic capability to secure EU F-Gas Regulation compliance and US FDA HACCP documentation. Intensifying stock densities multiply bacterial outbreak frequency and routine screening volumes.
- Aquatic Veterinary Services:Diagnostic-biosecurity bundles capture value previously realized through reagent markups, with antimicrobial stewardship integration representing unbundled revenue pools beyond commodity kit sales.
- Research Institutions:Multiplex panel validation studies and equivalence trials against culture-based reference methods concentrate demand here.
- Aquaculture Suppliers:Distribution consolidation around qualified suppliers with cold-chain reliability reshapes channel economics.
Fish Farms dominate procurement volume; Aquatic Veterinary Services expand most quickly through service integration.
Technology:
Analytical performance thresholds and portability requirements determine competitive positioning across detection methodologies.
- Molecular Diagnostics:Nucleic acid amplification with detection thresholds below 10 colony-forming units per milliliter commands dominant revenue share, with multiplex pathogen panels and quantitative sensitivity driving preference in export certification workflows.
- Biosensors:Electrochemical and optical transducers achieve portability without sacrificing analytical performance, with screen-printed electrode platforms paired with smartphone readouts opening point-of-need deployment in Indonesian smallholder ponds lacking laboratory infrastructure.
- Immunoassays:Antibody-based detection systems in government hatcheries resist displacement despite inferior sensitivity for subclinical infections.
- Enzymatic Methods:Cost-effective screening for specific metabolic markers supports routine monitoring applications.
Molecular Diagnostics anchors revenue concentration; Biosensors climb the fastest on portability advances.
Application:
Regulatory mandate intensity and intervention timing urgency segment demand by use case priority.
- Pathogen Detection:Early Vibrio and Aeromonas identification enables harvest timing and antibiotic withholding protocol adjustments, with loop-mediated isothermal amplification chemistry integrating into battery-operated devices for pond-side screening at 200-site density in Indonesian and Vietnamese farm cooperatives.
- Antibiotic Resistance Monitoring:EFSA residue monitoring directives for antibiotic-free seafood certification embed diagnostics into export documentation workflows for European-bound consignments.
- Disease Surveillance:Systematic monitoring programs support regional biosecurity coordination and outbreak containment.
- Water Quality Testing:Environmental parameter assessment complements pathogen screening in comprehensive farm management protocols.
Pathogen Detection leads on scale; Antibiotic Resistance Monitoring gains share fastest on regulatory tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Mekong Delta farming clusters anchor diagnostic procurement intensity as intensification raises pathogen screening volumes across Southeast Asian aquaculture belts. National regulations and export certification requirements reshape demand patterns in each production center.
Vietnam
Shrimp hatcheries in the Mekong Delta now exceed 150 post-larvae per square meter, multiplying bacterial outbreak frequency and routine screening demand. The Ministry of Agriculture and Rural Development enforces antibiotic residue monitoring for EU-bound seafood exports. Vertically integrated pangasius processors in An Giang and Dong Thap provinces internalize molecular diagnostic capability to secure HACCP documentation.
Indonesia
Smallholder tilapia and shrimp ponds in Java and Sulawesi drive point-of-need biosensor deployment where laboratory infrastructure remains sparse. The national fisheries regulator mandates disease reporting for commercial aquaculture operations. Farm cooperatives in South Sulawesi pilot 200-site loop-mediated isothermal amplification networks for pond-side Vibrio screening.
Thailand
Intensive shrimp farming in Samut Sakhon and Surat Thani provinces sustains high-throughput PCR laboratory demand. The Department of Fisheries operates residue monitoring programs aligned with EFSA import requirements. Processing exporters in the Eastern Seaboard cluster backward integrate diagnostic services to maintain EU market access.
India
Andhra Pradesh's brackishwater shrimp belt generates concentrated demand for antibiotic resistance monitoring kits. The Food Safety and Standards Authority of India enforces maximum residue limits for seafood destined for European markets. Hatchery operators in Nellore and Krishna districts contract aquatic veterinary services bundling diagnostics with biosecurity audits.
United States
Catfish operations in Mississippi and Alabama sustain steady diagnostic demand for Edwardsiella ictaluri and Flavobacterium columnare screening. The FDA enforces HACCP protocols requiring verified bacterial monitoring in imported aquaculture products. University extension services in the Delta region validate multiplex pathogen panels for regional farm cooperatives.
Bacterial Diagnostics in Aquaculture Market Competitive Environment
Global majors compete with regional champions across cold-chain reliability and field-deployable platform design. Thermo Fisher Scientific and Qiagen NV anchor laboratory-grade molecular workflows, while specialized aquatic diagnostics firms penetrate hatchery service contracts. Three strategic archetypes dominate: diversified life science conglomerates leveraging reagent scale, veterinary service integrators bundling diagnostics with antimicrobial stewardship, and point-of-need technology specialists advancing biosensor portability. Competitive moves concentrate on ambient-stable chemistry reformulation and third-party aquatic veterinary service acquisitions.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Qiagen NV exemplify scale-driven positioning anchored to thermal cycler installed bases and nucleic acid extraction automation. Zoetis Inc occupies a distinct integration archetype, representing veterinary service bundling that captures value beyond commodity reagent sales. Among specialized aquatic diagnostics providers, Aquatic Diagnostics Ltd exemplifies regional service penetration in European export certification markets. IDEXX Laboratories and Bio-Rad Laboratories sit within the broader veterinary and life science diagnostics tier, anchoring multiplex platform development for farm and laboratory end users.
| Leading Market Players |
|---|
| Agilent Technologies |
| LexaGene |
| Thermo Fisher Scientific |
| Zoetis Inc |
| Aquatic Diagnostics Ltd |
| IDEXX Laboratories |
| Qiagen NV |
| Neogen Corporation |
| Bio-Rad Laboratories |
| Others |
Value Chain & Pricing Dynamics
Taq polymerase spot pricing volatility cascades through reagent manufacturing tiers, compressing margins on standard PCR master mixes while amplifying premium capture for ambient-stable lyophilized formulations serving Vietnam's Mekong Delta cold-chain constrained buyers.
Pricing Analysis
Input-cost pass-through from thermostable enzyme supply concentration shapes a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade documentation for EU F-Gas Regulation compliance and US FDA HACCP workflows, while economy tiers serve domestic-market Indonesian smallholders with stripped-down reagent formats. Pricing pressure stems from fluorophore import licensing delays extending customs clearance timelines in Southeast Asian jurisdictions. Aquatic veterinary service bundles demonstrate lowest price sensitivity as technical service components capture value previously realized through reagent markups.
Supply Chain Analysis
Freight consolidation costs through Rotterdam and Singapore hubs inflate landed costs for perishable nucleic acid extraction buffers requiring 2-8°C logistics. Manufacturing concentration in the United States, Germany, and China anchors thermocycler and reagent production, with regional formulation facilities in Singapore serving Southeast Asian distribution networks. Raw material dependencies center on purified Taq polymerase, photoluminescent probe chemistries, and chromogenic culture substrates. Single-source vulnerability concentrates in qualified cold-chain logistics providers serving tropical last-mile networks. Distribution runs through aquatic veterinary service contracts bundling diagnostics with biosecurity audits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as shrimp hatchery intensification above 150 post-larvae per square meter shifts procurement toward multiplex pathogen panels with documented sensitivity thresholds.
For Market Incumbents: Hedge Taq polymerase supply concentration risk by securing dual-qualified enzyme suppliers before influenza vaccine manufacturing surges trigger allocation constraints. Deepen backward integration into ambient-stable lyophilized chemistry formulation to capture preference share among logistics-constrained tropical buyers. Defend against electrochemical biosensor displacement by embedding connectivity for remote veterinary oversight into installed thermal cycler bases. For New Entrants and Emerging Players: The EU F-Gas Regulation opens a window for point-of-need technology specialists advancing screen-printed electrode platforms with smartphone readouts. Indonesian smallholder tilapia and shrimp ponds in Java and Sulawesi represent the most penetrable geography lacking laboratory infrastructure. Partner with farm cooperatives piloting 200-site loop-mediated isothermal amplification networks for pond-side Vibrio screening. For Investors and Strategic Acquirers: Asymmetric upside sits with veterinary service integrators bundling diagnostics with antimicrobial stewardship programs. Long-term viability hinges on recurring revenue attachment to export certification workflows rather than commodity kit sales. Watch for consolidation signals when aquatic veterinary service contracts begin displacing traditional kit resellers in Vietnam's vertically integrated pangasius processing sector.| Strategic Initiative | Industry Significance |
|---|---|
| Ambient-Stable Chemistry Reformulation | EU F-Gas Regulation compliance secures cold-chain constrained Southeast Asian market access. |
| Third-Party Aquatic Veterinary Service Acquisition | Diagnostic-biosecurity bundles capture value beyond commodity reagent markups in Vietnam. |
| Multiplex Pathogen Panel Regulatory Validation | EFSA equivalence studies against culture-based methods unlock European export certification workflows. |
| Electrochemical Biosensor Platform Launch | Screen-printed electrode systems penetrate Indonesian smallholder ponds lacking laboratory infrastructure. |
| Regional Distribution Hub Consolidation | Rotterdam and Singapore freight consolidation reduces spoilage rates for perishable reagent shipments. |
Study Parameters
Multiple input streams — primary interviews with aquaculture farm managers, aquatic veterinary service directors, and diagnostic kit procurement leads; secondary validation through EFSA residue monitoring directives, US FDA HACCP guidance documents, and national fisheries regulator filings; plus customs and trade data on reagent import flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, end user, technology, and application segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from pathogen screening volume trajectories tied to shrimp hatchery intensification rates, antibiotic resistance monitoring mandate expansion, and biosensor adoption curves in laboratory-constrained geographies.
Revisions become necessary when regulatory enforcement intensity shifts, thermostable enzyme supply allocation disrupts, or electrochemical biosensor sensitivity thresholds achieve equivalence with PCR-based methods. Forecasts reflect documented assumptions about farm biosecurity protocol intensification and cold-chain infrastructure development. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Microalgae-Based Aquafeed Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
Europe Organic Aquaculture Market
Aquaculture Innovations
Global Ornamental Fish Feed Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
Ecuador Shrimp Feed Market
Aquaculture Innovations
Kuwait Fisheries and Aquaculture Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Ornamental Fish Market