
 North America Diesel Generator Market | 2026-2036
North America Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
North America Diesel Generator Market Analytics
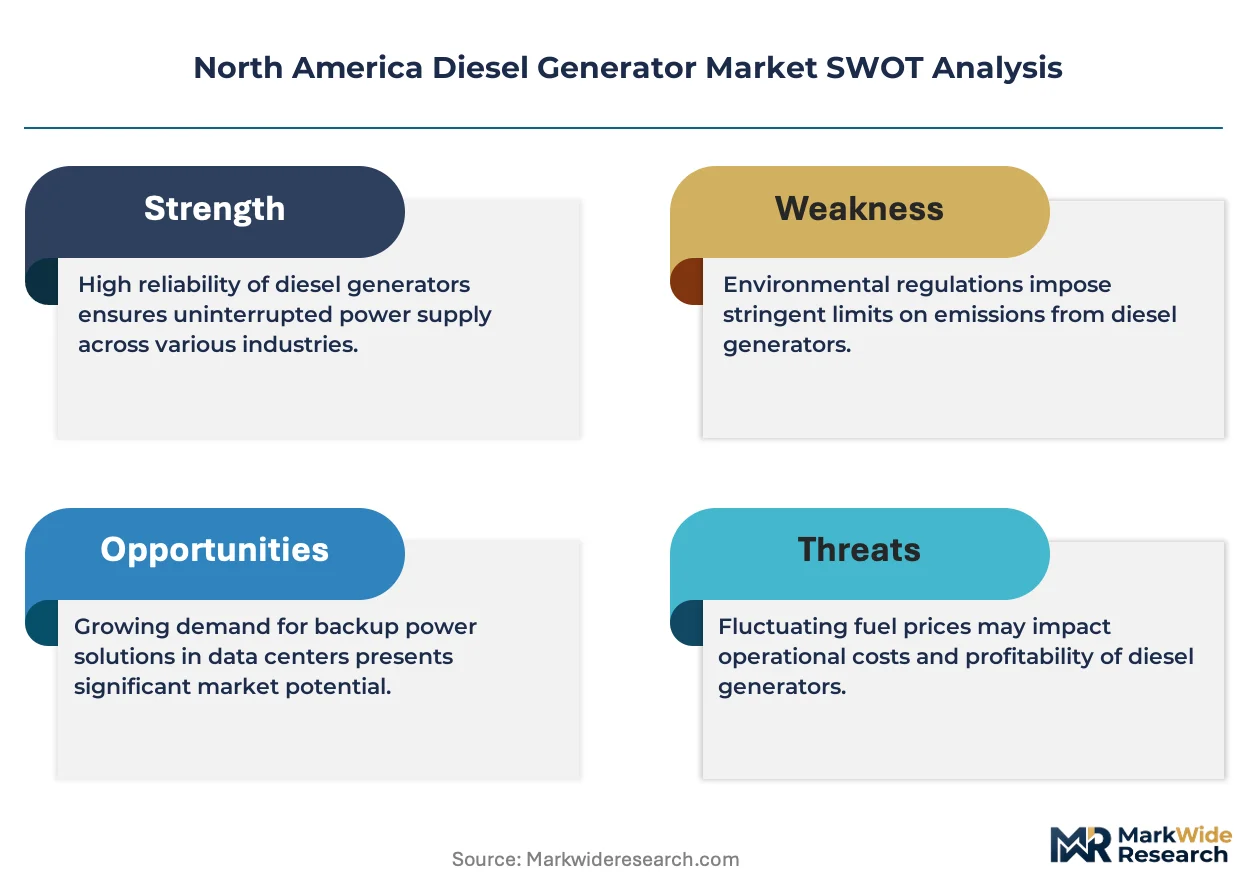
Steel enclosures and aluminum radiator housings are pivoting toward composite and hybrid material designs that reduce generator set weight and improve corrosion resistance in coastal installations. Cummins Inc. anchors the high-capacity industrial segment through captive engine manufacturing and integrated control systems. Caterpillar Inc. dominates the mining and oilfield rental channel with modular power module architectures. Generac Holdings Inc. specializes in residential and light commercial standby systems through controlled distribution networks.
A diesel generator is a reciprocating internal combustion engine coupled to an alternator that converts mechanical energy into electrical power, typically operating at 1,800 or 1,500 RPM with voltage regulation within plus or minus one percent for critical load compatibility. Standby generators serve as the largest product category by installed base, reflecting mandatory backup requirements for healthcare facilities and financial infrastructure under NFPA 110. The data center end-user segment commands premium pricing for units above 500 kVA, where N+1 redundancy specifications and sub-ten-second start mandates create specialized procurement criteria distinct from construction or telecom applications.
EPA Tier 4 Final emissions standards constrain engine certification pathways and limit aftermarket retrofit options for non-compliant legacy fleets in the United States. Canadian environmental regulations through Environment and Climate Change Canada align with U.S. thresholds but introduce provincial variability in permitting timelines for stationary installations. OSHA workplace noise exposure limits and NEC Article 700 emergency system requirements further shape product configuration and site engineering decisions. Stakeholders must evaluate dual-fuel retrofit compatibility and EPA re-certification pathways when assessing fleet replacement cycles against evolving state-level carbon intensity benchmarks.
Market Dynamics
Data center operators across the United States and Canada are accelerating backup power procurement as EPA Tier 4 Final emissions standards tighten engine certification pathways and compress replacement cycles for legacy diesel generator fleets.
Growth Catalysts
- EPA Tier 4 Final compliance mandates:Healthcare facilities and financial infrastructure face mandatory engine replacements under NFPA 110, creating sustained demand for certified standby systems.
- Texas grid instability:Enterprise investment in resilient onsite generation concentrates in hurricane-exposed coastal zones and ERCOT-constrained load centers.
- Composite material substitution:Steel enclosures and aluminum radiator housings pivot toward hybrid designs that reduce weight and improve corrosion resistance in salt-air installations.
Market Restraints
- Platinum group metal cost volatility:Diesel oxidation catalysts and selective catalytic reduction systems depend on palladium and rhodium pricing, compressing margins on Tier 4 Final-certified engines.
- Aftermarket retrofit limitations:EPA re-certification pathways for non-compliant legacy fleets remain constrained, forcing premature capital expenditure on new equipment.
- Natural gas dual-fuel substitution:CNG and LNG backup systems gain traction in jurisdictions with carbon intensity benchmarking, threatening diesel's dominance in sub-500 kVA applications.
Strategic Opportunities
- Canadian provincial permitting variability:Environment and Climate Change Canada alignment with U.S. thresholds creates arbitrage opportunities for manufacturers with cross-border certification expertise.
- Data center N+1 redundancy specifications:Sub-ten-second start mandates for units above 500 kVA create specialized procurement criteria with premium pricing structures distinct from construction or telecom verticals.
- Remote monitoring convergence:Integration of predictive maintenance algorithms with integrated control systems enables outcome-based service contracts for critical load applications.
Industry Challenges
- Tier 4 Final calibration technician scarcity:Specialized expertise in emissions control system troubleshooting and ECM programming remains concentrated among OEM-authorized service networks.
- Legacy NFPA 110 integration complexity:Retrofitting existing fuel storage, ventilation, and automatic transfer switch infrastructure to accommodate new engine footprints extends project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Diesel Generator Market |
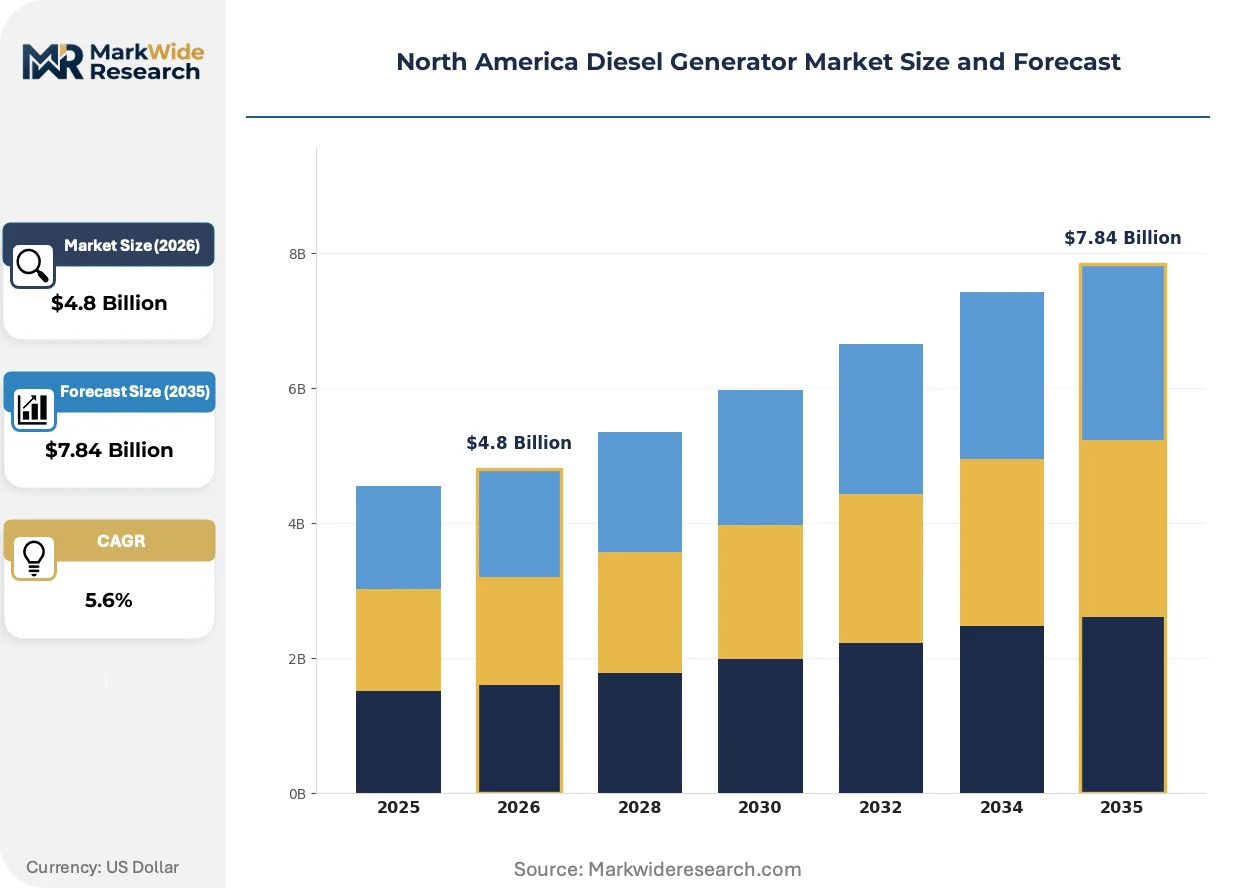
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Industrial Generators, Marine Generators End User: Healthcare, Construction, Telecommunications, Data Centers Application: Backup Power, Prime Power, Continuous Power, Off-Grid Power Capacity: Less than 100 kVA, 100-300 kVA, 301-500 kVA, More than 500 kVA |
| Companies Covered | Caterpillar Inc., Cummins Inc., Generac Holdings Inc., MTU Onsite Energy Corp., Kohler Co., Aggreko plc, Briggs & Stratton Corporation, Winco Inc., Multiquip Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Diesel Generator Market Evolving Landscape
Material science advances and emissions control integration are compressing traditional generator set architectures while reshaping how operators procure and maintain critical backup power infrastructure.
Hybrid composite enclosures are overtaking conventional steel housings in coastal and offshore applications. These fiberglass-reinforced polymer systems reduce installed weight by thirty to forty percent while eliminating galvanic corrosion in salt-air environments. Data center operators in Florida and Gulf Coast Texas are specifying these housings for hurricane-rated installations, compressing foundation and crane-lift requirements.
EPA Tier 4 Final certification pathways now require onboard diagnostics with permanent malfunction indicator systems for emissions control components. This mandate forces engine manufacturers to integrate proprietary telematics modules that transmit fault codes to service networks. The industrial rental channel faces the steepest compliance costs, as remote oilfield and mining sites lack the connectivity infrastructure for real-time monitoring.
Buyers in the data center vertical now unbundle after-sales service from equipment procurement, selecting third-party maintenance providers with ISO 9001 certification over OEM service contracts. This pattern concentrates in Northern Virginia and Phoenix, where hyperscale operators negotiate multi-site fleet management agreements independent of initial generator set vendors.
North America Diesel Generator Market Segmentation
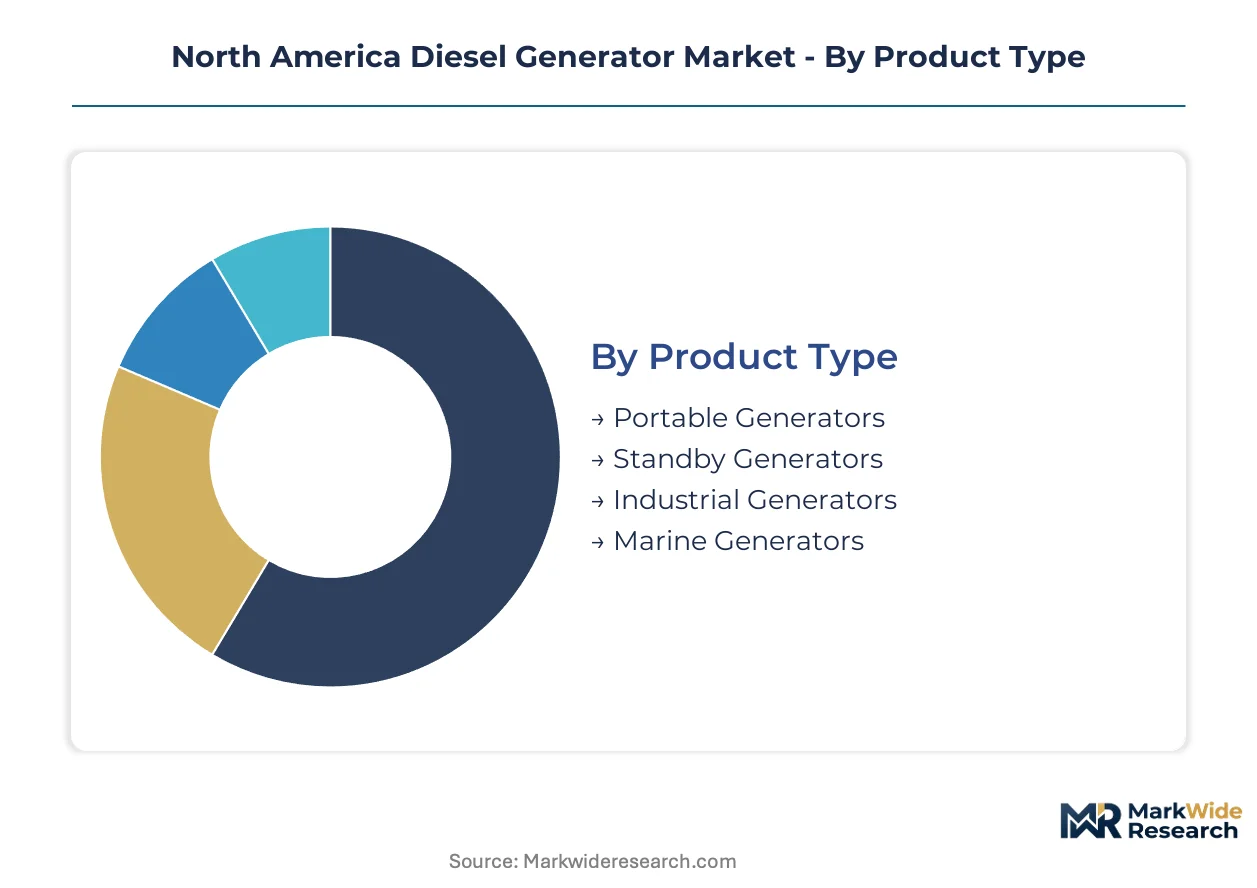
Segmentation in the North America diesel generator market reveals how procurement criteria diverge across regulatory environments, load criticality, and operational duty cycles. Buyers in Texas data centers prioritize sub-ten-second start capability and N+1 redundancy, while healthcare facilities in hurricane zones emphasize NFPA 110 compliance and extended fuel autonomy.
Product Type:
Cost tier differentiation separates emergency-only buyers from continuous-duty operators with multi-year runtime requirements.
- Standby Generators:Fixed-installation systems engineered for automatic startup upon utility failure, with EPA Tier 4 Final certification mandatory for healthcare and financial infrastructure under NFPA 110. Demand concentrates in Texas coastal counties and Northern Virginia data center clusters, where ERCOT instability and hyperscale expansion drive replacement cycles for aging pre-Tier 4 fleets.
- Industrial Generators:Heavy-duty units rated for prime and continuous power applications in mining, oilfield, and manufacturing settings. Procurement tilts toward Alberta oil sands and Permian Basin operations, where remote site logistics and extreme ambient temperature ranges dictate modular power module architectures with integrated fuel polishing systems.
- Portable Generators:Mobile units serving construction sites, emergency response, and temporary power rental markets. OSHA noise exposure limits and transport weight restrictions shape enclosure design.
- Marine Generators:Vessel-mounted systems engineered for salt-air corrosion resistance and dynamic load following. Gulf Coast shipyards and Great Lakes commercial fleets specify hybrid composite housings.
Volume sits with standby generators; growth tilts toward industrial generators as oilfield activity recovers and mining electrification accelerates.
End User:
Application maturity determines whether buyers accept lead times measured in weeks or months, with critical infrastructure operators demanding dedicated production slots.
- Data Centers:Hyperscale and colocation facilities requiring N+1 or 2N redundancy configurations with sub-ten-second start mandates. Procurement clusters in Northern Virginia's Loudoun County, Phoenix's Mesa-Queen Creek corridor, and Dallas-Fort Worth, where utility interconnection queues and carbon intensity benchmarking reshape fuel strategy discussions toward dual-fuel compatibility.
- Healthcare:Hospitals, outpatient surgery centers, and long-term care facilities under Joint Commission and CMS emergency power mandates. Florida and Gulf Coast Texas dominate installed base, with hurricane-rated fuel storage and seven-day autonomy requirements extending project timelines.
- Construction:General contractors and rental fleet operators serving commercial and residential development. Demand tracks housing starts and infrastructure appropriations.
- Telecommunications:Wireless carriers and wireline operators maintaining network continuity for 911 service and financial transaction processing. Cell tower backup requirements favor sub-100 kVA units with extended tank autonomy.
Revenue concentration favors data centers; margin expansion is climbing the fastest in healthcare as Tier 4 Final compliance costs compound with NFPA 110 integration complexity.
Application:
Customer type splits between regulated entities with mandatory testing protocols and discretionary buyers optimizing for capital efficiency.
- Backup Power:Emergency-only duty cycle with automatic transfer switch integration for life safety and critical business continuity loads. Dominates healthcare, data center, and financial infrastructure procurement, with EPA Tier 4 Final certification now mandatory for new installations across all U.S. jurisdictions.
- Prime Power:Primary electricity source for off-grid or unreliable grid locations, typical in remote mining camps and oilfield production facilities. Canadian oil sands and West Texas Permian operations specify high-capacity units with 24/7 runtime capability and integrated maintenance scheduling.
- Continuous Power:Base load generation with unlimited annual operating hours, common in islanded industrial facilities and combined heat and power configurations.
- Off-Grid Power:Standalone systems for rural residences, agricultural operations, and remote telecommunications infrastructure. Alaska and northern Canadian territories drive demand for cold-weather starting packages.
Installed base tilts toward backup power; steepest expansion trajectory appears in prime power as distributed generation economics improve for industrial off-takers.
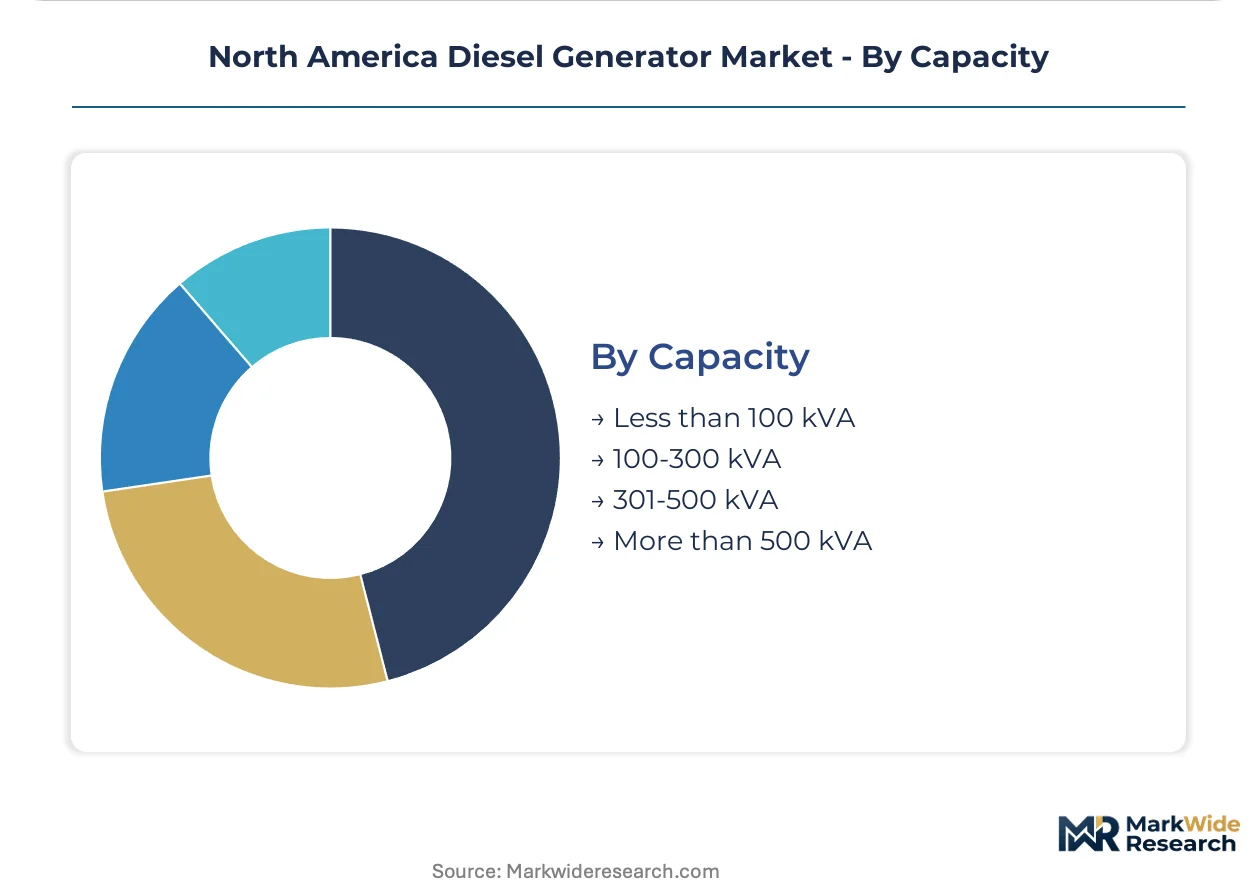
Capacity:
Supply concentration varies by tier, with domestic engine manufacturing anchoring high-capacity segments and import dependence rising below 100 kVA.
- More than 500 kVA:Large-format units serving data center campuses, hospital central plants, and industrial facilities with megawatt-scale load requirements. Manufacturing concentrates at Caterpillar and Cummins U.S. engine plants, with premium pricing justified by captive component sourcing and integrated control system engineering.
- 100-300 kVA:Mid-range segment serving commercial buildings, small data centers, and telecommunications switching facilities. Distribution runs through electrical contractors and specified by consulting engineers.
- Less than 100 kVA:Residential standby and light commercial applications with price-sensitive procurement through retail and online channels. Generac dominates through controlled distribution networks.
- 301-500 kVA:Transitional capacity range bridging commercial and industrial applications, common in manufacturing facilities and large retail distribution centers.
Unit volume concentrates below 100 kVA; value capture is expanding most quickly above 500 kVA where N+1 specifications and sub-ten-second start mandates create specialized procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement concentrates in hurricane-exposed coastal zones and ERCOT-constrained load centers, with data center operators and healthcare facilities driving replacement cycles for pre-Tier 4 diesel generator fleets.
United States
Texas grid instability and Northern Virginia hyperscale expansion anchor demand, with EPA Tier 4 Final emissions standards mandating certified standby systems for healthcare and financial infrastructure under NFPA 110. Dallas-Fort Worth and Loudoun County data center clusters command premium pricing for units above 500 kVA with N+1 redundancy specifications.
Canada
Alberta oil sands operations and remote mining camps sustain prime power demand for continuous-duty industrial generators, with Environment and Climate Change Canada regulations aligning with U.S. thresholds but introducing provincial variability in permitting timelines. Ontario and Quebec healthcare facilities face Joint Commission-mandated backup power upgrades.
Mexico
Manufacturing expansion in Nuevo León and the Bajío Region drives commercial standby generator procurement, with CFE grid reliability concerns pushing maquiladora facilities toward onsite generation. Mexico City metro area telecommunications infrastructure requires sub-100 kVA units for cell tower backup.
North America Diesel Generator Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers balance captive engine production against modular power module architectures. The vendor base stratifies across three tiers: integrated engine-alternator manufacturers with in-house component sourcing, assembly specialists relying on third-party powertrain supply, and rental fleet operators with distributed service networks. Two strategic archetypes have emerged: vertically integrated industrial specialists and controlled-distribution residential players. Competitive intensity centers on EPA certification speed and cross-border regulatory arbitrage.
Among U.S.-based integrated manufacturers, Caterpillar Inc. and Cummins Inc. occupy positions exemplifying the industrial-scale archetype, while Generac Holdings Inc. represents the controlled-distribution model for residential and light commercial segments. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning across divergent procurement channels.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Generac Holdings Inc. |
| MTU Onsite Energy Corp. |
| Kohler Co. |
| Aggreko plc |
| Briggs & Stratton Corporation |
| Winco Inc. |
| Multiquip Inc. |
| Others |
Value Network & Pricing Analysis
EPA Tier 4 Final certification ladders create a sharp bifurcation between premium-engine manufacturers with captive production and assembly specialists sourcing third-party powertrains, with this divergence manifesting in both pricing power and supply chain control. Tier 4 Final compliance costs compress margins on sub-500 kVA units while conferring pricing leverage on integrated manufacturers serving data center and healthcare verticals.
Pricing Analysis
Volume concentrates below 100 kVA where Generac's controlled distribution networks compete on price, while margins expand above 500 kVA where Caterpillar and Cummins command premium positioning through N+1 redundancy engineering and sub-ten-second start guarantees. Price differentiation hinges on EPA certification grade and after-sales service bundling, with unbundled maintenance contracts gaining traction among hyperscale data center operators in Northern Virginia and Phoenix. Cost compression in the mid-range 100-300 kVA segment is intensifying because platinum group metal volatility in diesel oxidation catalysts erodes profitability on Tier 4 Final-certified engines. Healthcare facilities exhibit least price sensitivity due to Joint Commission mandates, while construction rental fleets show highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Platinum group metal supply rests on South African and Russian mining operations, with palladium and rhodium pricing volatility feeding directly into diesel oxidation catalyst and selective catalytic reduction system costs. Engine block casting draws from U.S. and Mexican foundries, while alternator windings and electronic control modules source from China and South Korea. Single-source vulnerability concentrates in EPA-certified emissions control component supply, where OEM-authorized service networks maintain exclusive calibration tool access. Distribution runs through electrical contractors for commercial and industrial segments, retail channels for residential standby units, and rental fleet operators for temporary power applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around EPA Tier 4 Final certification capabilities, with technician scarcity and re-certification complexity forcing smaller assembly specialists toward acquisition or exit.
For Market Incumbents: Lock in captive engine manufacturing advantages by deepening backward integration into emissions control component production, insulating margin structures from platinum group metal volatility. Secure exclusive service network agreements in Texas and Northern Virginia data center clusters to defend against third-party maintenance providers with ISO 9001 certification. Prioritize cross-border certification expertise to exploit Canadian provincial permitting variability. For New Entrants and Emerging Players: The price-point gap between premium integrated manufacturers and economy assembly specialists opens white-space in the 301-500 kVA transitional range serving manufacturing facilities and large retail distribution centers. Target remote monitoring and predictive maintenance service contracts as the most penetrable angle, particularly for cell tower backup and construction rental fleets lacking OEM-authorized technician access. Lead with outcome-based service pricing rather than equipment margin capture. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated manufacturers seeking regional service network density or dual-fuel retrofit capabilities. Five-to-ten-year viability favors assembly specialists with established EPA certification pathways and cross-border Canadian expertise over pure-play rental operators. Watch for inflection in state-level carbon intensity benchmarking adoption, which would accelerate natural gas dual-fuel substitution and strand diesel-focused fleet assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emissions Control Components | Captive palladium and rhodium sourcing insulates Tier 4 Final margins from PGM volatility. |
| Cross-Border Certification Investment | Dual EPA and Environment and Climate Change Canada approval unlocks arbitrage in provincial permitting. |
| Remote Monitoring Platform Development | Predictive maintenance algorithms enable outcome-based contracts for hyperscale data center operators. |
| Dual-Fuel Retrofit Capability Buildout | Natural gas compatibility addresses carbon intensity benchmarking in ERCOT-constrained load centers. |
| Service Network Density Expansion | OEM-authorized technician concentration defends against ISO 9001-certified third-party maintenance entrants. |
Research Methodology
Independent corroboration across primary interviews with data center facility engineers, healthcare plant operations directors, EPA certification specialists, and rental fleet procurement managers underwrites the qualitative findings in this study. Secondary validation draws from EPA engine certification databases, FERC interconnection queue filings, EIA electricity reliability indicators, and SEC 10-K disclosures from publicly traded generator set manufacturers. Bottom-up unit shipment estimates triangulate against top-down addressable market calculations across standby, prime, and continuous power applications.
Comparable-period anchoring to historical EPA Tier implementation timelines and NFPA 110 adoption cycles shapes the forecast framework across the analysis window. Segmentation dimensions include product type, end-user vertical, application duty cycle, and capacity tier, with additional modeling of regional grid reliability indices and carbon intensity benchmarking adoption patterns. CAGRs derive from regression analysis of replacement cycle compression under Tier 4 Final mandates and data center power density growth trajectories.
Inputs from EPA certification databases and ERCOT outage incident reports were available through the study window; gaps in real-time platinum group metal contract pricing and proprietary telematics fault code data introduce uncertainty bands around emissions control cost forecasts. Assumptions regarding technician training pipeline expansion and provincial permitting timeline convergence in Canada may revise projections. A small set of triggers—state-level carbon intensity benchmarking adoption, hurricane frequency shifts in Gulf Coast counties, and natural gas infrastructure buildout pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Europe Gas Turbine Market
Generators
North America Gas Generator Market
Generators
Construction Generator Sets Market
Generators
Military Generator Market
Generators
Industrial Generator Market
Generators
Tri Fuel Generators Market
Generators
Emergency Power Generators Sales Market
Generators
Residential Generators Market
Generators
Generator (Up to 20 Kva) Market
Generators
Middle-East and Africa Diesel Generator Market
Generators
US Generator Sales Market
Generators
South America and Africa Diesel Generator Market
Generators
Portable Inverter Generators Market
Generators
Asia Pacific Electric Generators Market
Generators
Middle East Portable Generator Market
Generators
Construction Prime Power Generators Market