
 Wind Power Generators Market | 2026-2036
Wind Power Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Power Generators Market Outlook
Offshore wind developers are unwinding reliance on traditional onshore procurement patterns as floating platform viability improves. Vestas Wind Systems AS leverages its nacelle assembly scale across European port infrastructure. Siemens Gamesa Renewable Energy SA anchors its position through blade manufacturing specialization for harsh marine environments. GE Vernova competes aggressively on turbine rating class upgrades for the US East Coast lease rounds.
Wind power generators convert kinetic energy from airflow into electrical power through rotor-driven generators, typically achieving rated outputs from 2 MW to 15 MW depending on swept area and tip-speed ratio. Onshore turbines dominate installed base volumes while offshore turbines command premium pricing due to foundation complexity and grid connection costs; horizontal axis configurations retain overwhelming share against vertical axis alternatives limited to niche distributed applications. Control systems and power electronics segments attract disproportionate R&D investment as grid codes tighten fault-ride-through requirements.
The EU Green Deal and F-Gas Regulation are phasing down fluorinated gases in turbine switchgear, forcing generator redesigns toward vacuum-interrupter alternatives. China's MIIT enforces GB standards on grid synchronization that filter market access for imported units. The US IRA production tax credit structure directly shapes buyer capital commitment timing. Stakeholders must monitor evolving domestic content thresholds across jurisdictions to avoid supply chain disqualification.
Market Dynamics
The wind power generators market is compressing around nacelle platform standardization as offshore foundation costs force turbine OEMs to extract economies from fewer base architectures. Floating substructure maturation is redrawing procurement geography away from shallow-water ports toward deepwater assembly hubs.
Growth Catalysts
- EU Green Deal efficiency mandates:Brussels is tightening turbine performance thresholds for grid access, forcing generator upgrades across the North Sea corridor.
- China's dual carbon goals:Beijing's MIIT is filtering import access through GB synchronization standards, accelerating domestic procurement of high-capacity units.
- US East Coast lease rounds:Bureau of Ocean Energy Management auctions are concentrating developer capital commitments around 15 MW-class turbines.
Market Restraints
- Rare earth magnet concentration:Neodymium supply chains cluster in Chinese processing facilities, exposing generator manufacturers to input volatility.
- F-Gas phase-down timelines:The EU F-Gas Regulation is forcing vacuum-interrupter redesigns that extend certification cycles by 18-24 months.
- Foundation fabrication bottlenecks:Monopile steel rolling capacity concentrates in three European yards, constraining offshore deployment velocity.
Strategic Opportunities
- Floating platform commercialization:Portugal's WindFloat Atlantic and Scotland's Kincardine arrays demonstrate viability in 60+ meter water depths.
- Power electronics convergence:Silicon carbide inverters paired with direct-drive generators are cutting converter losses below 2%.
- US IRA domestic content bonuses:Treasury guidance on qualifying steel and nacelle assembly is redirecting supply chain investment toward Gulf Coast ports.
Industry Challenges
- Installation vessel scarcity:Heavy-lift jack-up availability constrains offshore commissioning schedules to narrow weather windows.
- Grid code synchronization complexity:Fault-ride-through testing for GB, IEEE 1547, and ENTSO-E variants multiplies certification costs for multi-jurisdiction suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Power Generators Market |
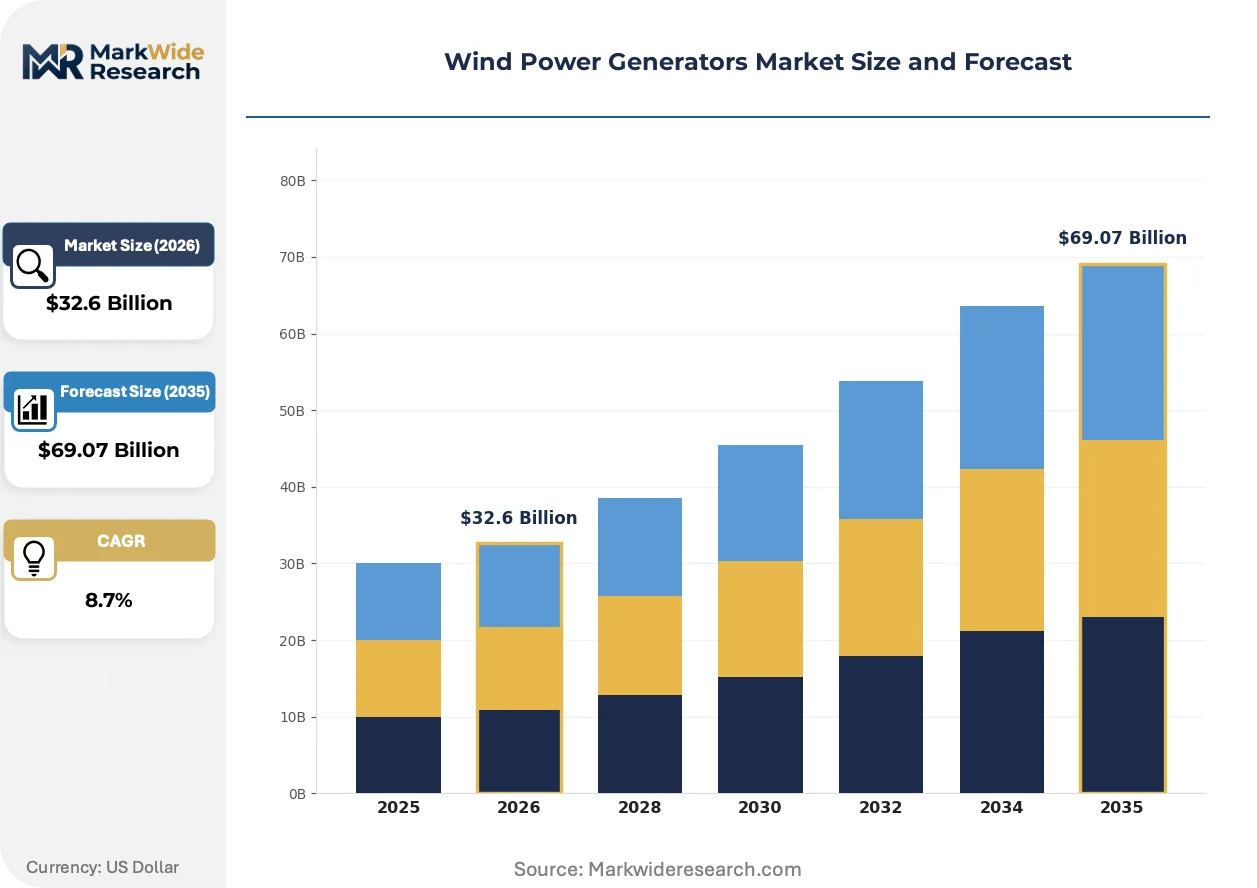
| Market Size in 2026 | $32.6 Billion |
| Market Size in 2035 | $69.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Axis, Vertical Axis, Offshore Turbines, Onshore Turbines Application: Utility Scale, Distributed Generation, Microgrid, Remote Locations Technology: Drivetrain, Blade Design, Control Systems, Power Electronics End User: Utilities, Independent Power Producers, Agricultural, Commercial Enterprises |
| Companies Covered | Vestas Wind Systems AS, Siemens Gamesa Renewable Energy SA, GE Vernova, Xinjiang Goldwind Science and Technology Co. Ltd., Nordex SE, ENERCON GmbH, Ming Yang Smart Energy Group Limited, Suzlon Energy Ltd., Envision Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Power Generators Market Strategic Shifts
Turbine architecture is compressing around modular drivetrain designs that separate generator, gearbox, and power electronics into field-replaceable units. Control systems and blade materials are attracting parallel R&D investment as rated capacities push past 12 MW.
Direct-drive permanent magnet generators are decomposing gearbox-dependent architectures in offshore installations above 10 MW. Danish and German developers are specifying these units for North Sea arrays to cut maintenance intervals. The technology is decomposing traditional nacelle supplier hierarchies by elevating magnet and power electronics vendors to tier-one status.
The EU F-Gas Regulation is phasing down sulfur hexafluoride in turbine switchgear, forcing generator manufacturers toward vacuum-interrupter and clean-air insulation designs. Siemens Gamesa and Vestas are redesigning medium-voltage systems to eliminate fluorinated gas dependencies entirely. Offshore units face the tightest compliance deadlines, with 2027 serving as the cutoff for new SF6-based installations in EU waters.
Utility-scale operators are consolidating procurement around full-scope service agreements that bundle availability guarantees with predictive maintenance. Danish Energy Agency contracts and German Bundesnetzagentur tenders now specify 25-30 year operational performance clauses. This contracting evolution is visible across the North Sea corridor, where Orsted and RWE are unbundling component warranties from turbine supply to capture lifecycle cost transparency.
Wind Power Generators Market Segmentation
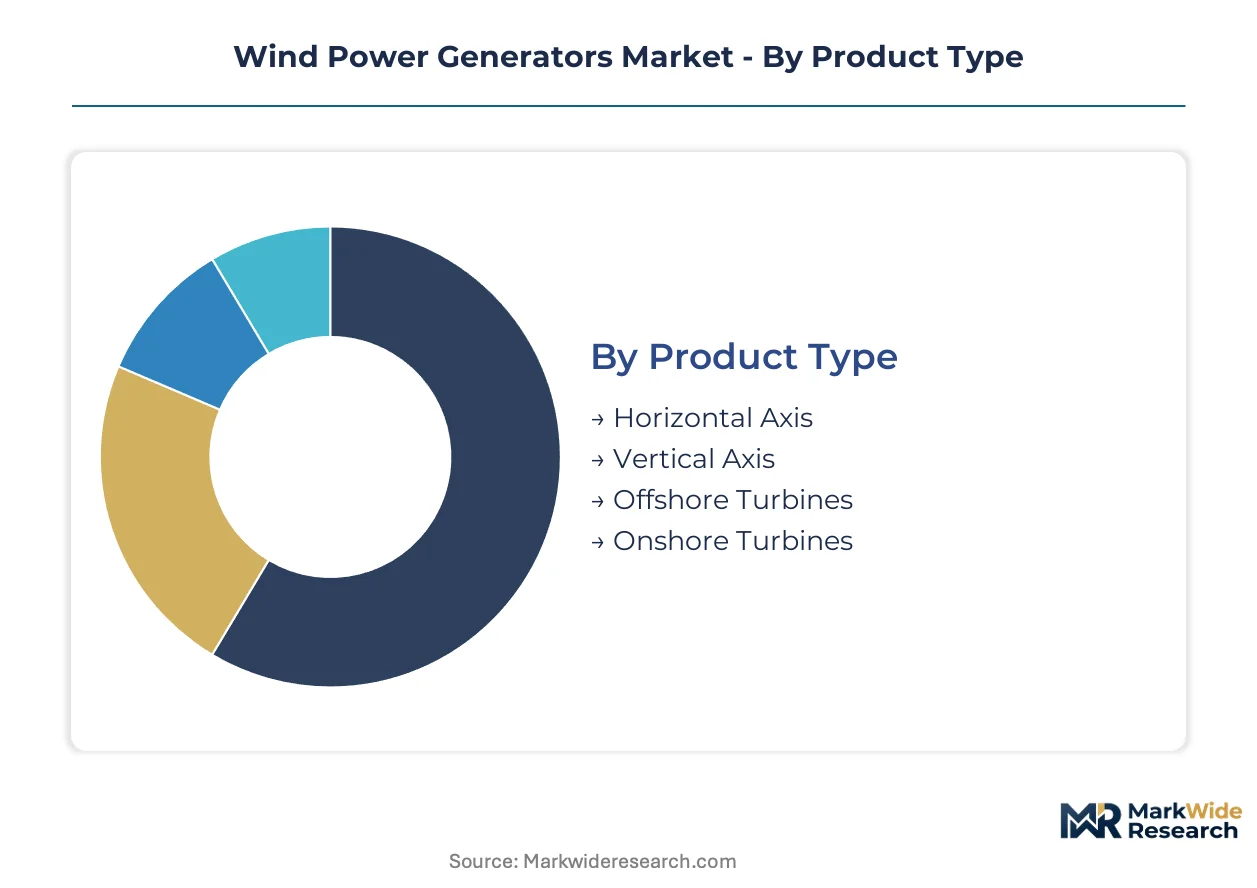
Wind power generator segmentation reflects divergent technical requirements across marine and terrestrial environments, with regulatory frameworks in Brussels, Beijing, and Washington each privileging different performance thresholds. Procurement patterns fragment sharply between utility-scale operators seeking 15 MW-class offshore units and distributed generators optimizing for grid-edge flexibility.
Product Type:
EU F-Gas Regulation deadlines and China's GB synchronization standards are segmenting certification pathways, with vacuum-interrupter redesigns mandatory for EU-bound units and grid-code compliance filtering import access to Chinese projects.
- Horizontal Axis:Dominant three-blade upwind configurations achieve tip-speed ratios exceeding 6:1 through variable-pitch control systems. North Sea developers in Denmark, Germany, and the Netherlands specify these units for utility-scale arrays where swept areas now exceed 20,000 square meters; fault-ride-through mandates under ENTSO-E codes are forcing nacelle redesigns.
- Offshore Turbines:Foundation-integrated units rated 10-15 MW command premium pricing due to monopile fabrication complexity and subsea cable termination costs. Bureau of Ocean Energy Management lease rounds along the US East Coast are concentrating capital commitments around this segment; installation vessel scarcity constrains commissioning velocity to narrow weather windows.
- Vertical Axis:Darrieus and Savonius variants serve niche distributed applications where omnidirectional wind capture offsets lower efficiency curves.
- Onshore Turbines:Geared drivetrain architectures dominate installed base volumes across land-constrained sites in India and Brazil.
Horizontal Axis handles the majority of throughput; Offshore Turbines is climbing the fastest on share.
Application:
Capital intensity tiers separate procurement patterns, with tax credit structures in the US IRA and contract-for-difference mechanisms in the UK Contracts for Difference scheme shaping buyer commitment timing.
- Utility Scale:Grid-connected arrays above 100 MW aggregate capacity dominate capacity additions, with Danish Energy Agency and German Bundesnetzagentur tenders now specifying 25-30 year operational performance clauses. Procurement is consolidating around full-scope service agreements that bundle availability guarantees with predictive maintenance across the North Sea corridor.
- Distributed Generation:Behind-the-meter installations below 5 MW serve commercial and industrial load centers where net metering policies determine project economics. Agricultural operations in Iowa and Texas are deploying mid-scale units to offset irrigation pumping loads; interconnection queue delays are the primary constraint.
- Microgrid:Islanded or weak-grid configurations pair turbines with battery storage and diesel backup for reliability-critical facilities.
- Remote Locations:Off-grid mining camps and telecommunication relay stations specify ruggedized units with extended maintenance intervals.
Utility Scale captures the dominant share of capital deployment; Distributed Generation is expanding most quickly as grid-edge flexibility premiums rise.
Technology:
Supply chain concentration in silicon carbide substrates and rare earth processing is elevating certain component vendors to tier-one status, with Chinese neodymium supply chains exposing generator manufacturers to input volatility.
- Power Electronics:Silicon carbide inverters paired with direct-drive generators are cutting converter losses below 2%, enabling higher switching frequencies that reduce filter component mass. Offshore developers in Scotland and Portugal are specifying these systems for floating platforms where nacelle weight directly impacts substructure costs; F-Gas phase-down timelines are forcing vacuum-interrupter redesigns that extend certification cycles.
- Control Systems:Advanced pitch and yaw algorithms optimize energy capture across variable wind shear profiles while managing fatigue loading. Grid code synchronization complexity for GB, IEEE 1547, and ENTSO-E variants multiplies certification costs for multi-jurisdiction suppliers.
- Drivetrain:Direct-drive permanent magnet architectures are displacing geared systems in offshore installations above 10 MW.
- Blade Design:Carbon fiber hybrid spar caps enable 100+ meter lengths with tip speeds approaching 90 meters per second.
Power Electronics commands disproportionate R&D investment; Control Systems is gaining share fastest as grid codes tighten fault-ride-through requirements.
End User:
Contracting sophistication varies sharply across buyer categories, with utilities leveraging offtake scale for performance guarantees while independent developers optimize for construction finance terms.
- Utilities:Vertically integrated grid operators in Spain, Italy, and Poland are consolidating procurement through framework agreements that standardize turbine specifications across multi-year deployment programs. State-owned enterprises in China are accelerating domestic procurement of high-capacity units under MIIT enforcement of GB synchronization standards.
- Independent Power Producers:Project finance-dependent developers structure turbine supply agreements around availability warranties that satisfy lender technical due diligence. US East Coast lease round winners are competing for heavy-lift jack-up vessel slots to meet IRA production tax credit safe harbor deadlines.
- Agricultural:Rural landowners in the US Midwest and Australian wheat belt deploy single-turbine installations to diversify revenue streams.
- Commercial Enterprises:Corporate offtake agreements drive direct procurement for data centers and manufacturing facilities with 24/7 clean energy commitments.
Utilities anchor the majority of order intake; Independent Power Producers is expanding most quickly as merchant risk appetite recovers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark exports nacelle assemblies to German and Dutch offshore lease rounds along the North Sea corridor. Chinese turbine OEMs ship direct-drive generators to Southeast Asian markets under MIIT export certification protocols. Brazil receives geared drivetrain units from European fabricators for wind-rich northeastern states.
China
MIIT enforces GB synchronization standards that filter import access and accelerate domestic procurement of 10-15 MW offshore units. The dual carbon goals mandate turbine efficiency upgrades across coastal provinces. Yangtze River Delta ports cluster nacelle assembly facilities serving Bohai Sea and Guangdong developments.
Germany
Offshore developers in the North Sea specify 15 MW-class turbines for Bundesnetzagentur tenders with 25-30 year performance clauses. The EU F-Gas Regulation forces vacuum-interrupter redesigns eliminating SF6 from switchgear by 2027. Port of Cuxhaven anchors monopile staging for Danish and Dutch cross-border arrays.
United States
Bureau of Ocean Energy Management lease rounds concentrate capital commitments around 15 MW turbines for Massachusetts and New Jersey projects. IRA production tax credit structures shape buyer timing with domestic content bonus thresholds. Gulf Coast ports attract nacelle assembly investment to qualify Treasury guidance on qualifying steel.
Denmark
Ørsted and Copenhagen Infrastructure Partners drive procurement of floating platform turbines for 60+ meter water depths. Danish Energy Agency contracts specify full-scope service agreements bundling availability guarantees. Port of Esbjerg handles blade logistics for German and Dutch North Sea corridors.
United Kingdom
Contracts for Difference auctions allocate seabed leases for 14-16 MW turbines in Scottish and English waters. The country's net-zero grid code tightens fault-ride-through requirements for ENTSO-E synchronization. Aberdeen and Hull port clusters specialize in floating substructure assembly for Kincardine-scale arrays.
Wind Power Generators Market Competitive Environment
Listed leaders compete with private specialists across nacelle platform standardization and floating substructure deployment. The market structure concentrates around three European OEMs with integrated offshore service networks and three Chinese challengers scaling direct-drive architectures. Strategic archetypes include full-scope integrated providers, component-specialist licensors, and regional turnkey assemblers. Dominant competitive moves encompass backward integration into magnet supply chains and joint ventures with heavy-lift vessel operators.
Among European-listed fabricators, Vestas Wind Systems AS and Siemens Gamesa Renewable Energy SA exemplify the full-scope integrated archetype with North Sea corridor positioning. GE Vernova occupies a position representing the American engineering-conglomerate approach to turbine rating class competition. These three anchor the premium-tier procurement patterns visible across Danish, German, and US East Coast lease rounds.
| Leading Market Players |
|---|
| Vestas Wind Systems AS |
| Siemens Gamesa Renewable Energy SA |
| GE Vernova |
| Xinjiang Goldwind Science and Technology Co. Ltd. |
| Nordex SE |
| ENERCON GmbH |
| Ming Yang Smart Energy Group Limited |
| Suzlon Energy Ltd. |
| Envision Energy |
| Others |
Value Chain & Pricing Dynamics
Vacuum-interrupter substitution for sulfur hexafluoride switchgear simultaneously redraws component sourcing geography toward European electrical equipment fabricators and compresses pricing flexibility for nacelle OEMs facing 18-24 month certification cycles. This forced redesign dynamic concentrates pricing power with certified suppliers while penalizing late adopters with stranded inventory.
Pricing Analysis
Current-generation 12-15 MW offshore turbines command substantial premiums over prior-generation 8-10 MW units, while next-generation 20+ MW prototypes remain pre-commercial. Pricing stratifies across premium, standard, and economy tiers driven by foundation-integration complexity and grid-code certification level. Cost compression in the standard tier is intensifying because monopile steel rolling capacity concentrates in three European yards. Utility-scale developers exhibit lowest price sensitivity due to long-term offtake structures, while agricultural distributed generators face acute capital constraint.
Supply Chain Analysis
Port congestion at Yangtze River Delta assembly hubs and container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for magnet and power electronics shipments. Neodymium processing draws from Chinese facilities, silicon carbide substrates rest on Japanese and American wafer production, and blade carbon fiber sources from German and American precursor plants. Single-source vulnerability concentrates in rare earth magnet supply chains. Distribution runs through port-centric nacelle assembly clusters serving North Sea and US East Coast lease rounds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across floating platform subsystems where demand-side shift toward 60+ meter water depths creates specialist vendor niches outside integrated OEM hierarchies.
For Market Incumbents: Secure captive magnet supply through backward integration into neodymium processing or long-term offtake agreements with Chinese separation facilities. Anchor service network density across German and Danish North Sea ports to defend against emerging floating platform specialists. The threat of silicon carbide inverter commoditization demands accelerated power electronics R&D lock-in.
For New Entrants and Emerging Players: Differentiate on floating platform electrical system integration where incumbent OEMs maintain capability gaps. Target Scotland and Portugal demonstration arrays as the most penetrable geography. Pursue joint development structures with European energy majors seeking technology diversification.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed heavy-lift vessel operators and magnet recycling specialists. Five-to-ten year viability hinges on IRA domestic content threshold evolution and EU F-Gas enforcement trajectory. Monitor Bureau of Ocean Energy Management lease round participation rates as inflection indicator for US capital commitment velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Supply | Captive neodymium access insulates generator manufacturers from Chinese export quota volatility. |
| Floating Platform Joint Venture | Partnerships with Portuguese and Scottish array developers accelerate 60+ meter water depth commercialization. |
| Silicon Carbide Inverter Scale-Up | Wafer supply agreements with Japanese substrate producers secure converter loss reduction below 2%. |
| Heavy-Lift Vessel Charter Consolidation | Installation slot control tightens commissioning schedules for US East Coast IRA safe harbor deadlines. |
| Vacuum-Interrupter Certification Investment | EU F-Gas compliance ahead of 2027 cutoff eliminates SF6 redesign penalties for North Sea deployments. |
Study Parameters
The analysis maps nacelle platform architectures, power electronics configurations, and foundation integration tiers, each validated through utility procurement officers, IPP project developers, EPC contractors, and grid interconnection specialists. Primary fieldwork combined structured interviews with secondary validation against EIA generation databases, IEA renewable technology reports, FERC interconnection filings, and Bureau of Ocean Energy Management lease round disclosures. Bottom-up project pipeline aggregation triangulates against top-down OEM order book analysis.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation across turbine rating class, foundation type, grid connection voltage level, and regional regulatory cluster. CAGRs derived from capacity addition trajectories, unit pricing trends, and technology substitution curves. Forecast inputs incorporated installation vessel availability constraints and rare earth magnet price volatility assumptions.
Forecasts assume regulatory continuity in US IRA tax credit structures and EU F-Gas phase-down timelines; material policy shifts would require re-modeling. Technology disruption risk from next-generation superconducting generators or alternative drivetrain architectures could accelerate substitution curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Europe Generator Sets Market
Generators
Power Generator Rental Market
Generators
Portugal Gas Generator Market
Generators
India Generator Sets Market
Generators
Generator (Up to 20 Kva) Market
Generators
Multi Fuel Generators Market
Generators
Asia-Pacific Portable Generator Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Telecom Generator Market
Generators
Home Standby Gensets Market
Generators
Middle East Portable Generator Market
Generators
Onboard Marine Gensets Market
Generators
North America Diesel Generator Market
Generators
Digital Inverter Generator Market
Generators
Boiler Turbine and Generator BTG Sales Market
Generators
Africa Portable Generator Market