
 Industrial Generator Sets Market | 2026-2036
Industrial Generator Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Generator Sets Market Outlook
Aftermarket service revenue is reshaping profit pools across the industrial generator sets landscape. Caterpillar Inc. leverages its global dealer network to capture long-term maintenance contracts. Cummins Inc. sustains competitive positioning through vertical integration into alternator and control system manufacturing. Kohler Co. anchors premium segments with specialized enclosures for healthcare and data center applications.
Industrial generator sets are engine-alternator assemblies that convert mechanical energy into electrical power, typically rated from 10 kW to over 3,000 kW and designed for continuous, prime, or standby duty cycles. These systems employ diesel, natural gas, or dual-fuel engines coupled with synchronous generators to deliver stable voltage and frequency for critical infrastructure. Natural gas deployments are gaining share as methane infrastructure expands and emission thresholds tighten across jurisdictions. The above 500 kW power rating segment carries the deepest margin pools due to engineering complexity and site-specific integration requirements. Portable units face commoditization pressure in construction applications where rental fleets dominate procurement.
EPA Tier 4 Final standards in the United States and EU Stage V regulations in Europe are forcing engine manufacturers to integrate selective catalytic reduction and diesel particulate filters into compact power-dense packages. India's CPCB IV+ norms and China's National VI-equivalent standards for non-road engines are creating parallel certification burdens for multinational suppliers. Stakeholders must monitor how battery-hybrid load-following architectures displace traditional prime-rated generators in renewable-microgrid configurations.
Market Dynamics
EPA Tier 4 Final emission standards are compressing diesel engine architectures while battery-hybrid load-following systems penetrate prime-rated installations, forcing incumbent manufacturers to redesign core power-dense packages around dual-fuel flexibility and selective catalytic reduction integration.
Growth Catalysts
- Data center power resilience mandates:Hyperscale operators in the United States and India are specifying N+1 redundancy configurations, driving procurement of above 500 kW standby generator sets with sub-10-second start capabilities.
- EU Stage V emission frameworks:European non-road mobile machinery regulations are accelerating natural gas and dual-fuel engine certifications, expanding addressable markets for methane infrastructure corridors in Germany and the Netherlands.
- Selective catalytic reduction advances:Compact SCR systems with integrated diesel particulate filters are enabling Tier 4 Final compliance without package enlargement, preserving transportability for rental fleet operators.
Market Restraints
- Platinum group metal cost volatility:Palladium and rhodium price swings in catalytic converter substrates compress margin stability for engine manufacturers dependent on exhaust aftertreatment.
- Alternator copper concentration:Winding supply chains cluster in Chinese smelting and wire-drawing facilities, exposing non-integrated assemblers to concentrate risk during commodity squeeze cycles.
- Battery energy density thresholds:Lithium-ion systems below four-hour duration economics cannot displace diesel prime power in remote mining camps, perpetuating fossil dependency in off-grid heavy industry.
Strategic Opportunities
- Healthcare microgrid certification:Joint Commission accreditation standards for hospital emergency power are creating specification pull for specialized acoustic enclosures with seismic compliance in California and Texas facilities.
- Renewable-hybrid control convergence:Synchronous generator-battery inverters with active load-sharing algorithms are opening prime-rated displacement opportunities in solar-diesel microgrids across Australian remote communities.
- India CPCB IV+ compliance services:Retrofit kit installation and engine remanufacturing for existing generator fleets represent attach-rate expansion for service networks in Maharashtra and Gujarat industrial corridors.
Industry Challenges
- Emissions calibration technician scarcity:EPA-certified diagnostic capability for SCR/DPF troubleshooting concentrates among dealership networks, constraining independent service provider market entry.
- Site-specific integration engineering:Above 1,000 kW installations require acoustic, fuel system, and switchgear customization that extends project timelines and strains application engineering bandwidth.
- Dual-fuel certification harmonization:Divergent natural gas quality specifications between North American pipeline standards and European EN 16726 create redundant homologation burdens for multinational product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Generator Sets Market |
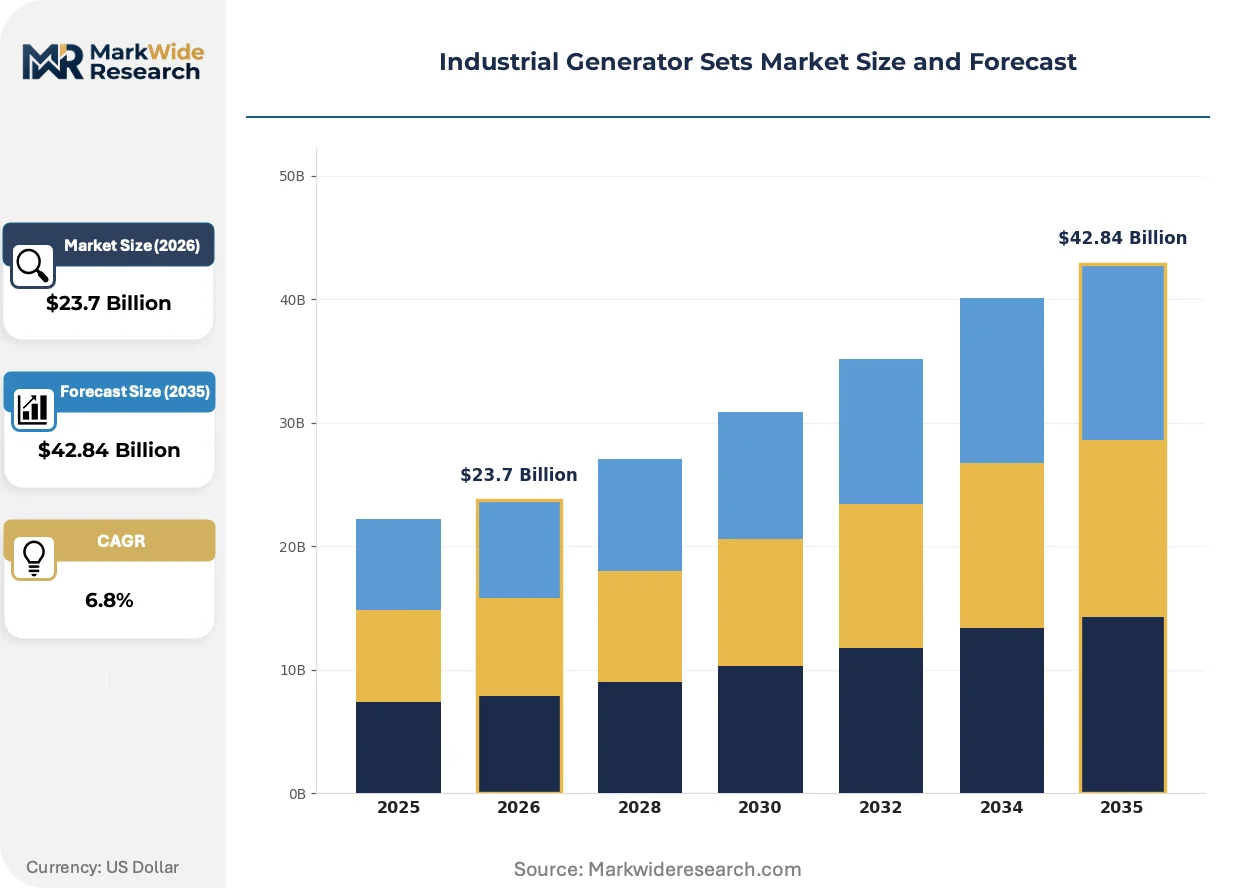
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Rating: Up to 100 kW, 100-300 kW, 300-500 kW, Above 500 kW Fuel Type: Diesel, Natural Gas, Propane, Hybrid Deployment Type: Portable, Standby, Prime, Continuous End User: Construction, Mining, Healthcare, Manufacturing |
| Companies Covered | Kohler Co., Mitsubishi Heavy Industries, Ltd., Caterpillar Inc., Briggs & Stratton, Kubota Corporation, Cummins Inc., Rolls-Royce plc, Atlas Copco AB, Generac Power Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Generator Sets Market Strategic Shifts
Digital twin architectures and predictive maintenance platforms are virtualizing traditional service relationships, while regulatory compression on diesel emissions accelerates fuel-flexible engine development and procurement models pivot toward power-as-a-service frameworks.
Generator set control systems with cloud-connected telemetry are virtualizing conventional maintenance dispatch. Data center operators in Northern Virginia and Dallas-Fort Worth are adopting these platforms fastest, compressing mean-time-to-repair intervals and shifting supplier value capture from hardware margin to recurring software subscriptions.
EPA Tier 4 Final and EU Stage V regulations are forcing selective catalytic reduction and diesel particulate filter integration into previously compact engine envelopes. Industrial engine manufacturers are responding with modular aftertreatment architectures that preserve service access, though these add package weight and cooling load that complicates rooftop installations in urban data centers.
Power purchase agreements with embedded generator maintenance are displacing traditional capital procurement in commercial and light industrial segments. Equipment lessors in the United States are bundling fuel management, remote monitoring, and preventive maintenance into single-contract structures, concentrating buyer relationships with national rental fleet operators rather than distributed dealer networks.
Industrial Generator Sets Market Segmentation
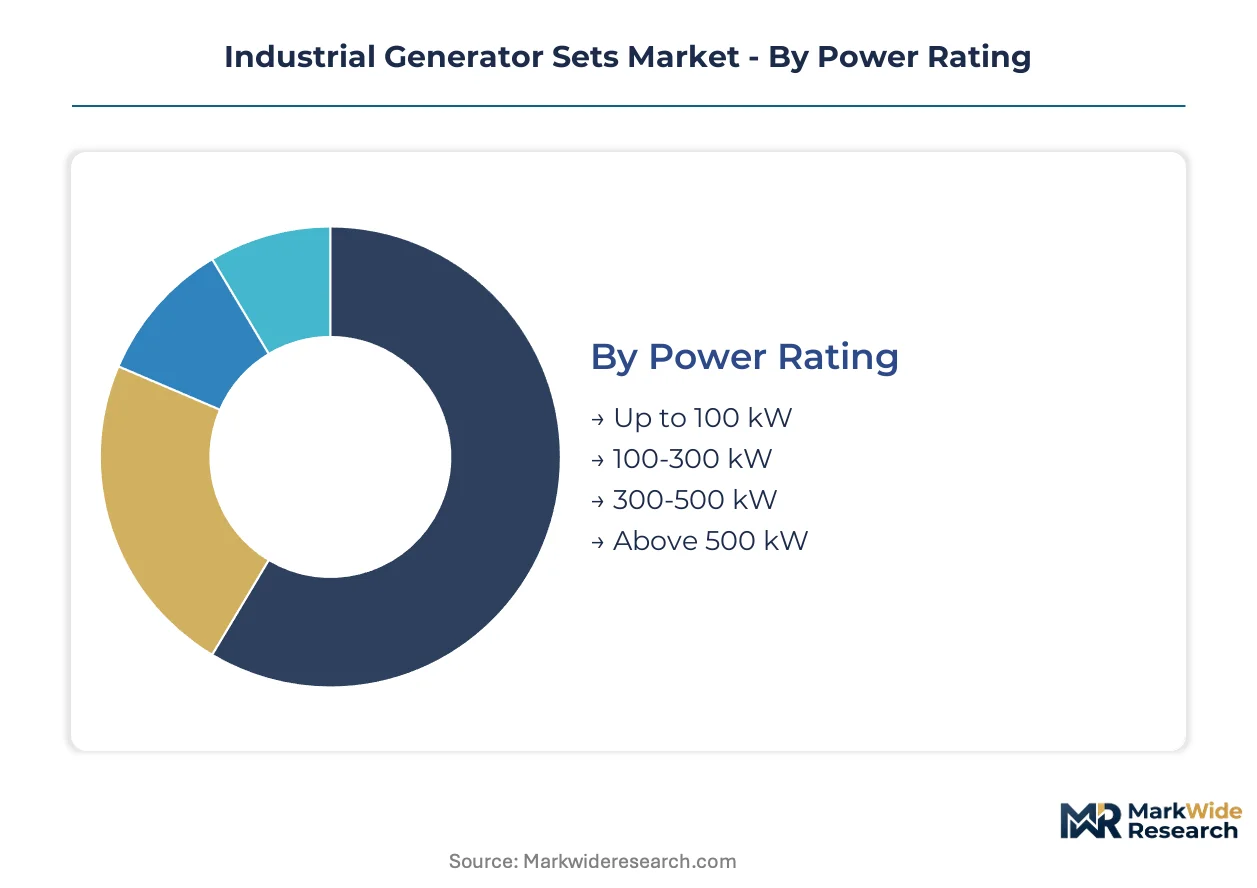
Industrial generator sets fragment across power ratings, fuel technologies, and duty cycles that each demand distinct service architectures. Understanding these divisions clarifies where aftermarket revenue concentrates and which configurations justify premium engineering investment.
Power Rating:
After-sales-service intensity escalates dramatically with kW output, as larger units require specialized technicians for SCR calibration and alternator rewinding that smaller units rarely need.
- Above 500 kW:Engine-alternator assemblies rated above 500 kW integrate selective catalytic reduction, diesel particulate filters, and site-specific acoustic enclosures. Data center operators in Northern Virginia and Dallas-Fort Worth specify these units for N+1 redundancy with sub-10-second start requirements, driving the deepest margin pools through engineering complexity and custom integration.
- 300-500 kW:This bracket serves manufacturing facilities and hospital campuses requiring prime or continuous duty cycles. India's Maharashtra and Gujarat industrial corridors show concentrated procurement here, where CPCB IV+ compliance retrofit services expand attach rates for authorized dealer networks.
- 100-300 kW:Commercial building standby applications dominate this segment, with standardized enclosures and shorter installation timelines.
- Up to 100 kW:Portable construction and light commercial units face commoditization pressure from rental fleet procurement models.
By volume, up to 100 kW leads. By growth pace, above 500 kW is ahead.
Fuel Type:
Emission threshold compression across jurisdictions is redistributing demand toward methane-capable architectures and away from conventional diesel dominance.
- Natural Gas:Spark-ignited engines burning pipeline methane achieve lower NOx and particulate emissions without aftertreatment complexity. Germany and the Netherlands show accelerating deployment along established infrastructure corridors, as EU Stage V frameworks penalize diesel alternatives in non-road mobile applications.
- Diesel:Compression-ignition architectures retain dominance in remote mining camps and heavy industrial prime power where fuel logistics favor liquid energy density. EPA Tier 4 Final compliance forces selective catalytic reduction and diesel particulate filter integration, adding package weight and cooling load that complicates rooftop data center installations.
- Propane:LPG-burning units serve niche applications with stored fuel requirements, including telecommunications shelters and rural healthcare facilities.
- Hybrid:Synchronous generator-battery inverter combinations with active load-sharing algorithms penetrate solar-diesel microgrids across Australian remote communities, displacing traditional prime-rated fossil units.
By installed base, diesel dominates. By expansion trajectory, hybrid configurations are climbing the fastest.
Deployment Type:
Procurement economics diverge sharply between capital purchase and power-as-a-service models, with rental fleet operators capturing an expanding share of portable and standby segments.
- Standby:Emergency power systems activate automatically upon grid failure, requiring sub-10-second response for life safety loads. Healthcare facilities in California and Texas drive specification pull for seismic-compliant acoustic enclosures meeting Joint Commission accreditation standards.
- Prime:Continuous operation as primary power source demands engineered durability and fuel efficiency optimization. Remote mining operations in Western Australia and Chilean copper belts sustain diesel dependency here, as four-hour lithium-ion economics remain insufficient for heavy industrial off-grid demand.
- Portable:Trailer-mounted or skid-based units serve construction sites and temporary events through rental channel procurement, compressing hardware margins.
- Continuous:Base-load operation at fixed installations parallels prime duty but with stricter maintenance intervals and lubricant monitoring protocols.
By revenue concentration, standby leads. By contract duration, prime and continuous generate superior service annuity streams.
End User:
Regulatory compliance burdens and criticality thresholds create distinct specification environments across vertical applications.
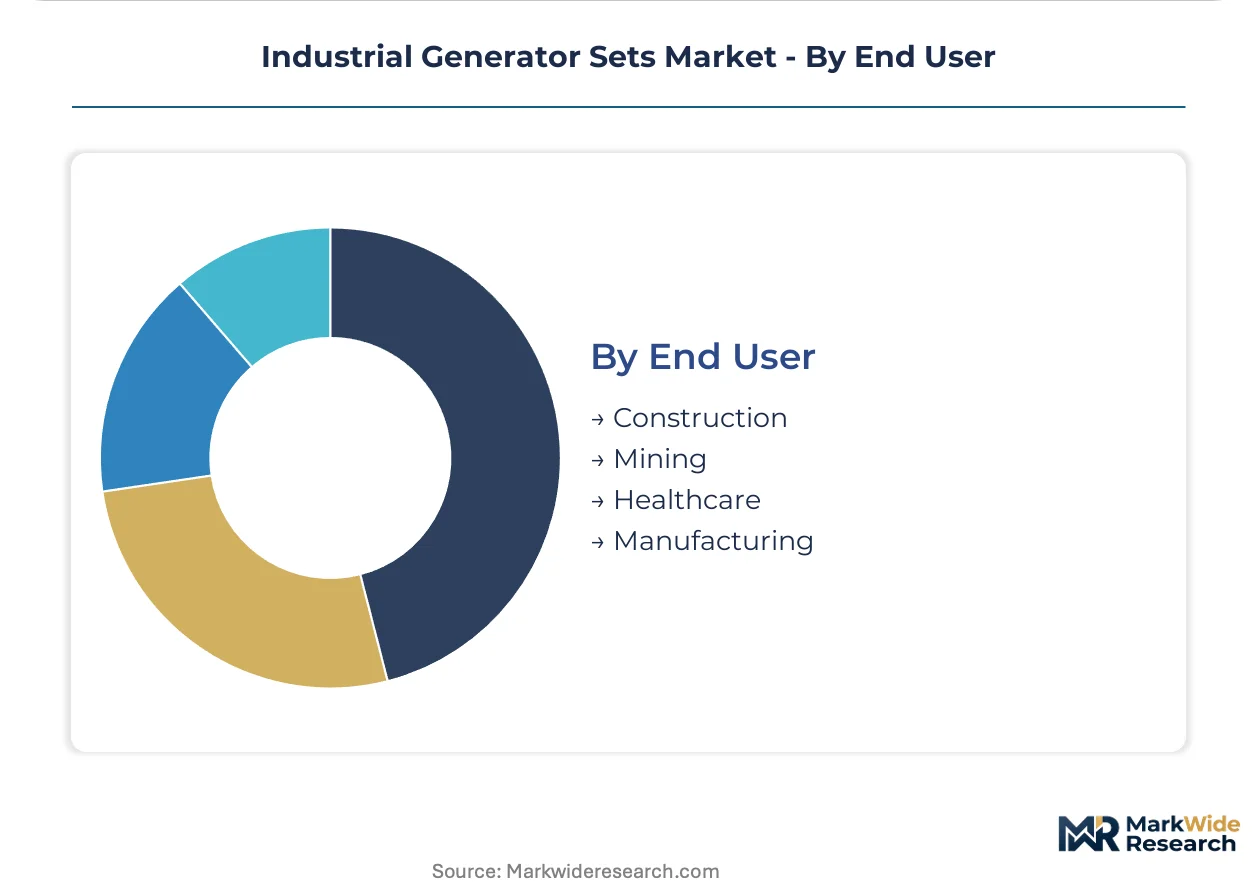
- Healthcare:Hospital emergency power mandates Joint Commission accreditation with specialized seismic and acoustic requirements. California and Texas facilities anchor premium enclosure demand, where generator availability directly affects patient safety metrics and liability exposure.
- Data Center:Hyperscale operators specify N+1 redundancy with redundant fuel systems and remote monitoring telemetry. Northern Virginia's concentration of cloud infrastructure drives the most sophisticated procurement standards for above 500 kW standby configurations.
- Mining:Remote extraction operations depend on prime-rated diesel units where grid extension proves uneconomical and battery duration falls short of heavy equipment loads.
- Construction:Temporary power needs favor portable rental fleet procurement, commoditizing hardware and concentrating buyer relationships with national lessors.
- Manufacturing:Continuous and prime duty cycles for production line resilience vary with grid reliability across industrial corridors.
By specification complexity, healthcare leads. By procurement volume, data center and construction dominate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engine manufacturing concentrates in industrial corridors where emission standards and data center construction intersect. Four countries anchor demand generation and supply-side investment across distinct regulatory environments.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives above 500 kW standby procurement with sub-10-second start requirements. EPA Tier 4 Final standards compress diesel engine architectures through selective catalytic reduction mandates. Caterpillar Inc. and Cummins Inc. leverage domestic manufacturing footprints to capture maintenance contract renewals across these clusters.
China
Industrial infrastructure resilience programs prioritize backup power for manufacturing corridors in Jiangsu and Guangdong provinces. National VI-equivalent standards for non-road engines create certification burdens for multinational suppliers seeking market entry. Domestic engine manufacturers accelerate natural gas platform development along methane pipeline networks in the Yangtze River Delta.
Germany
EU Stage V frameworks penalize diesel alternatives in non-road mobile machinery, accelerating natural gas and dual-fuel certifications. Industrial users along the Rhine corridor deploy methane-capable units where pipeline infrastructure supports fuel switching. Engineering-intensive above 500 kW installations concentrate in Baden-Württemberg automotive supplier parks.
India
Maharashtra and Gujarat industrial corridors show concentrated procurement in the 300-500 kW bracket for prime and continuous duty cycles. CPCB IV+ norms for existing generator fleets create retrofit service opportunities for authorized dealer networks. Data center operators in Mumbai and Hyderabad specify N+1 redundancy configurations following grid reliability concerns.
Australia
Remote mining operations in Western Australia sustain diesel prime power demand where battery duration falls short of heavy equipment loads. Solar-diesel microgrids penetrate remote communities through synchronous generator-battery inverter combinations with active load-sharing algorithms. Off-grid heavy industry perpetuates fossil dependency despite emission threshold compression elsewhere.
Industrial Generator Sets Market Competitive Environment
Vertically integrated conglomerates and specialized power system engineers split the market across distinct capability tiers. The vendor base clusters around three strategic archetypes: full-spectrum industrial equipment manufacturers with captive engine production, dedicated generator set assemblers with outsourced powertrain sourcing, and rental fleet operators bundling hardware with power-as-a-service contracts. Competitive dynamics center on M&A activity consolidating regional service networks and strategic partnerships securing alternator winding supply.
Within the full-spectrum tier, Caterpillar Inc. and Cummins Inc. anchor positions through backward integration into engine manufacturing and control system production. Kohler Co. occupies a premium specialization vector with healthcare and data center enclosure engineering. Mitsubishi Heavy Industries, Ltd. and Rolls-Royce plc represent industrial conglomerate entries leveraging aerospace and heavy machinery engineering heritage. These groupings exemplify how competitive positioning depends on vertical scope rather than hardware differentiation alone.
| Leading Market Players |
|---|
| Kohler Co. |
| Mitsubishi Heavy Industries, Ltd. |
| Caterpillar Inc. |
| Briggs & Stratton |
| Kubota Corporation |
| Cummins Inc. |
| Rolls-Royce plc |
| Atlas Copco AB |
| Generac Power Systems, Inc. |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Rotterdam container freight corridors transmit cost volatility into generator set landed prices, amplifying margin compression for non-integrated assemblers while rewarding manufacturers with captive alternator winding capacity and established regional fabrication footprints.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across the industrial generator sets landscape. Three-tier pricing structure across premium, standard, and economy levels separates healthcare-grade seismic enclosures from rental fleet portable units and construction-site standby configurations. Price differentiation hinges on aftertreatment complexity and certification grade, with SCR-integrated above-500 kW systems commanding substantial premiums over basic prime power units. Pricing pressure stems from platinum group metal cost swings in catalytic substrates, squeezing margin stability for engine manufacturers. Rental fleet procurement channels exhibit highest price sensitivity, while data center operators prioritize availability guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from 90 to 120 days dominate supplier-financing arrangements for alternator and control system procurement, straining working capital for independent assemblers without captive manufacturing. Geographic supply concentration centers on China for copper wire drawing and rare earth processing, Germany for precision engine components, and the United States for emissions control module assembly. Raw material dependencies include copper windings, platinum group metals for catalytic substrates, and high-grade steel for enclosures. Single-source vulnerability concentrates in Chinese smelting facilities for alternator copper. Distribution runs through authorized dealer networks for above-300 kW installations and national rental fleet operators for portable segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial generator sets sit in early-cycle expansion as data center power resilience mandates penetrate secondary markets and emission threshold compression accelerates fuel-flexible platform replacement timelines.
For Market Incumbents: Entrench service network density in Northern Virginia and Dallas-Fort Worth data center corridors to capture long-term maintenance contract renewals. Deepen backward integration into alternator manufacturing to insulate margin pools from copper concentrate risk. Battery-hybrid displacement in prime-rated applications represents the most credible substitution threat requiring dual-fuel platform investment. For New Entrants and Emerging Players: Build out CPCB IV+ retrofit service capabilities in Maharashtra and Gujarat industrial corridors where existing diesel fleet compliance creates attach-rate expansion opportunities. India's 300-500 kW prime duty segment offers the most penetrable white space for authorized service network establishment. Partner with domestic engine remanufacturing facilities to bypass capital-intensive clean-sheet platform development. For Investors and Strategic Acquirers: Specialized acoustic enclosure engineers with Joint Commission healthcare certification anchor the most defensible acquisition target archetype in this market. Long-term viability favors service-annuity models over hardware-margin dependence as power-as-a-service frameworks expand. Watch battery energy density thresholds crossing four-hour duration economics as the critical inflection signal for prime-rated diesel displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Platform Certification | EU Stage V compliance opens German and Dutch methane corridor deployments. |
| Retrofit Service Network Expansion | CPCB IV+ compliance in Maharashtra creates attach-rate growth for authorized dealers. |
| Predictive Maintenance Platform Deployment | Cloud-connected telemetry shifts value capture from hardware to software subscriptions. |
| Acoustic Enclosure Engineering Investment | Joint Commission seismic standards in California and Texas anchor premium positioning. |
| Power-as-a-Service Contract Structuring | Bundled fuel and maintenance offerings concentrate buyer relationships with national lessors. |
Study Parameters
A standing panel of maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads provided ongoing calibration across the primary research phase. Field interviews with data center infrastructure planners and hospital facilities managers in the United States, Germany, India, and China supplied demand-side validation. Secondary sources included EPA certification databases, EU Stage V homologation records, customs trade data for alternator and engine component flows, and SEC filings from publicly traded industrial equipment manufacturers. Bottom-up unit shipment estimates triangulated against top-down power infrastructure investment data.
Scenario bracketing around battery energy density trajectories and emission standard phase-in timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include power rating tiers, fuel technology platforms, duty cycle classifications, and end-use verticals. CAGRs derived from installed base turnover rates and replacement demand elasticity. Industry-specific forecast inputs encompassed data center construction permitting data and mining camp electrification project pipelines.
Stress conditions across platinum group metal price bands, container freight rate volatility, and grid reliability deterioration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding emission standard enforcement consistency and battery cost decline curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Middle East and Africa Gas Generator Market
Generators
Middle East Portable Generator Market
Generators
South America Gas Generator Market
Generators
South Africa Diesel Generator Market
Generators
Onboard Marine Gensets Market
Generators
Generator Sets Market
Generators
Silent Generator Market
Generators
Telecom Generator Market
Generators
United States Diesel Generator Market
Generators
Gasoline Gensets Market
Generators
Turbo Generator Market
Generators
Reciprocating Power Generating Engine Market
Generators
Wind Power Generators Market
Generators
Residential Gas Generator Market
Generators
Heat Recovery Steam Generator Sales Market
Generators
Containerized Solar Generators Market