
 Asia-Pacific Portable Generator Market | 2026-2036
Asia-Pacific Portable Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Portable Generator Market Outlook
Construction sector procurement is shifting toward higher-capacity portable units for remote infrastructure builds across Southeast Asia. Yamaha Motor Co., Ltd. leverages its inverter technology leadership to dominate premium residential segments in Japan and Australia. Kohler Co. anchors its position through diesel generator specialization for mining and heavy construction applications. Generac Power Systems competes aggressively on gasoline-powered residential units through expanded distribution in India and Thailand.
A portable generator is a self-contained engine-alternator assembly producing alternating current electricity, typically rated from under 2 kW to over 10 kW output, designed for mobile deployment without permanent installation. These units serve critical functions where grid connectivity is unavailable, unreliable, or insufficient for operational continuity across commercial, industrial, and emergency response contexts. Inverter generators command margin premiums due to clean power output essential for sensitive electronics, while conventional gasoline generators retain volume leadership across residential and events applications. Diesel generators concentrate in construction and emergency services where runtime duration and fuel efficiency override first-cost sensitivity.
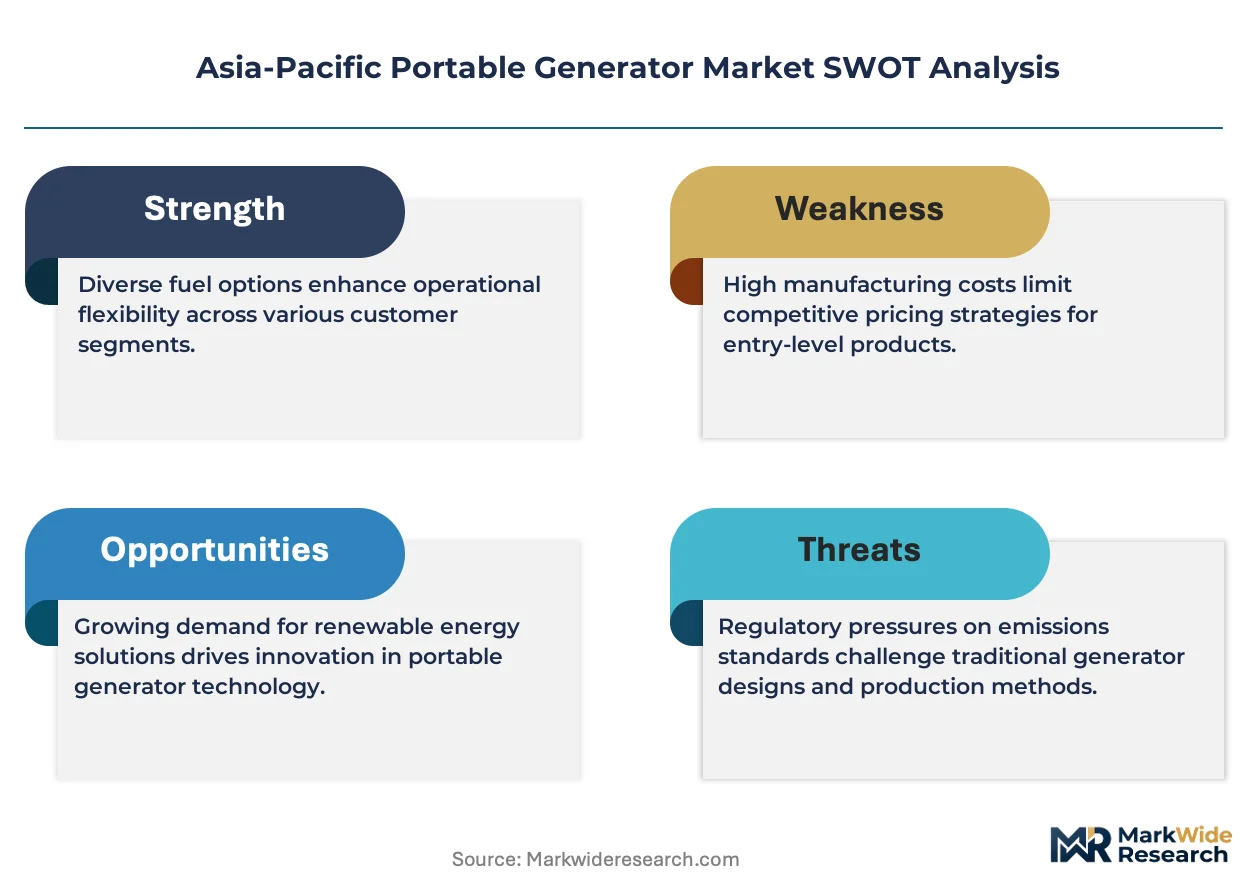
Japan's METI enforces stringent noise and emissions standards that shape product design priorities for manufacturers targeting developed Asia-Pacific markets. India's BIS and the ASEAN harmonized technical regulations on small engine emissions create compliance layering that favors established players with certification resources. China's MIIT and GB standards on fuel efficiency add further specification complexity for cross-border suppliers. Stakeholders must monitor regulatory divergence between developed and emerging Asia-Pacific economies when configuring product portfolios and localization strategies.
Market Dynamics
Indonesia's archipelago infrastructure buildout is concentrating portable generator demand around higher-capacity diesel units, while India's BIS emission mandates force rapid product redesign cycles across the supply base.
Growth Catalysts
- ASEAN harmonized technical regulations:Unified small engine emission standards across Southeast Asia reduce certification duplication costs for manufacturers with regional assembly footprints.
- Remote construction electrification:Mining and heavy infrastructure projects across Papua New Guinea and Myanmar drive procurement of 10 kW+ diesel generator sets with extended runtime specifications.
- Inverter technology maturation:Clean power output capabilities now match conventional units at competitive first-cost positions, opening residential segments in Japan and Australia to premium positioning.
Market Restraints
- Copper and steel price volatility:Alternator windings and enclosure materials expose manufacturers to commodity input cost swings that compress margin buffers on fixed-price contracts.
- China-centric engine sourcing:Concentration of small gasoline engine production in Zhejiang and Chongqing provinces creates geographic supply risk amplified by port congestion and trade documentation delays.
- Battery energy storage substitution:Lithium-ion power stations below 3 kW output are capturing camping and light residential applications where noise sensitivity and fuel logistics dominate purchase criteria.
Strategic Opportunities
- Philippines rural electrification:The country's Barangay electrification program and island grid extensions create sustained demand for 5-8 kW portable units with multi-fuel flexibility.
- Dual-fuel generator development:LPG-gasoline hybrid systems address Indonesia's subsidized fuel access constraints while meeting METI noise standards for developed market export.
- E-commerce spare parts channels:Direct-to-consumer carburetor, filter, and control module sales bypass traditional dealer networks and capture aftermarket revenue from aging installed base units.
Industry Challenges
- BIS certification timeline compression:India's mandatory engine emission testing and factory audit requirements extend product launch cycles by 8-14 months for new market entrants.
- After-sales technician scarcity:Remote deployment sites across Southeast Asia lack trained service personnel for electronic fuel injection diagnostics and inverter module replacement.
- Legacy fleet interoperability:Grid-tie synchronization and smart load management integration with existing construction site power distribution requires custom engineering on project-specific bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Portable Generator Market |
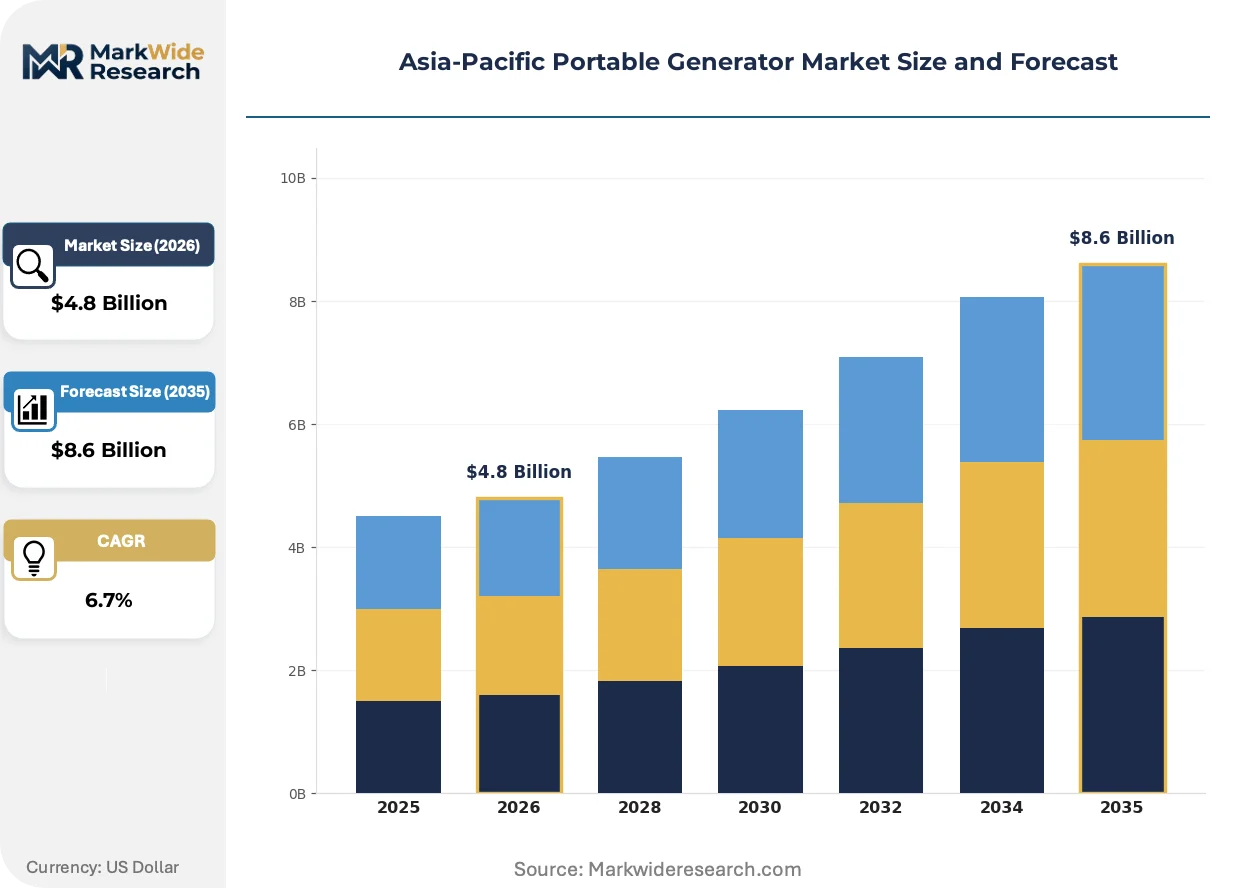
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inverter Generators, Conventional Generators, Solar Generators, Diesel Generators End User: Residential, Construction, Events, Emergency Services Fuel Type: Gasoline, LPG, Propane, Biofuel Power Rating: Under 2 kW, 2-5 kW, 5-10 kW, Over 10 kW |
| Companies Covered | Yamaha Motor Co., Ltd., Kohler Co., Generac Power Systems, Atlas Copco AB, Cummins Inc., Caterpillar Inc., Briggs & Stratton Corporation, Wacker Neuson SE, Honda Motor Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Portable Generator Market Strategic Shifts
Product architecture is bifurcating between premium inverter platforms for developed Asia-Pacific markets and ruggedized conventional units for emerging economy infrastructure deployment, with regulatory compliance costs driving portfolio specialization.
Hybrid power systems combining small gasoline engines with lithium-ion buffer batteries are expanding into telecom tower backup and remote monitoring station applications across Indonesia and the Philippines. Tower operators in archipelago locations are adopting these units to reduce fuel logistics costs and extend maintenance intervals. The technology is expanding into construction site rental fleets where runtime flexibility and noise compliance create rental rate premiums.
Japan's METI has tightened stationary engine noise limits to 60 dB(A) at 7 meters for residential-adjacent applications, forcing redesign of cooling airflow paths and enclosure damping materials. Manufacturers targeting Australian and Japanese markets now engineer dual-certified platforms meeting both METI and local council noise ordinances. The regulation most affects 2-5 kW residential inverter segments where premium positioning depends on quiet operation claims.
Rental channel consolidation across Thailand and Vietnam is compressing purchase decision cycles from seasonal bidding to monthly equipment pool refresh programs. Major construction contractors now specify generator availability through multi-year fleet management agreements rather than spot procurement. This shift concentrates volume with distributors offering logistics integration and on-site technical support capabilities.
Asia-Pacific Portable Generator Market Segmentation
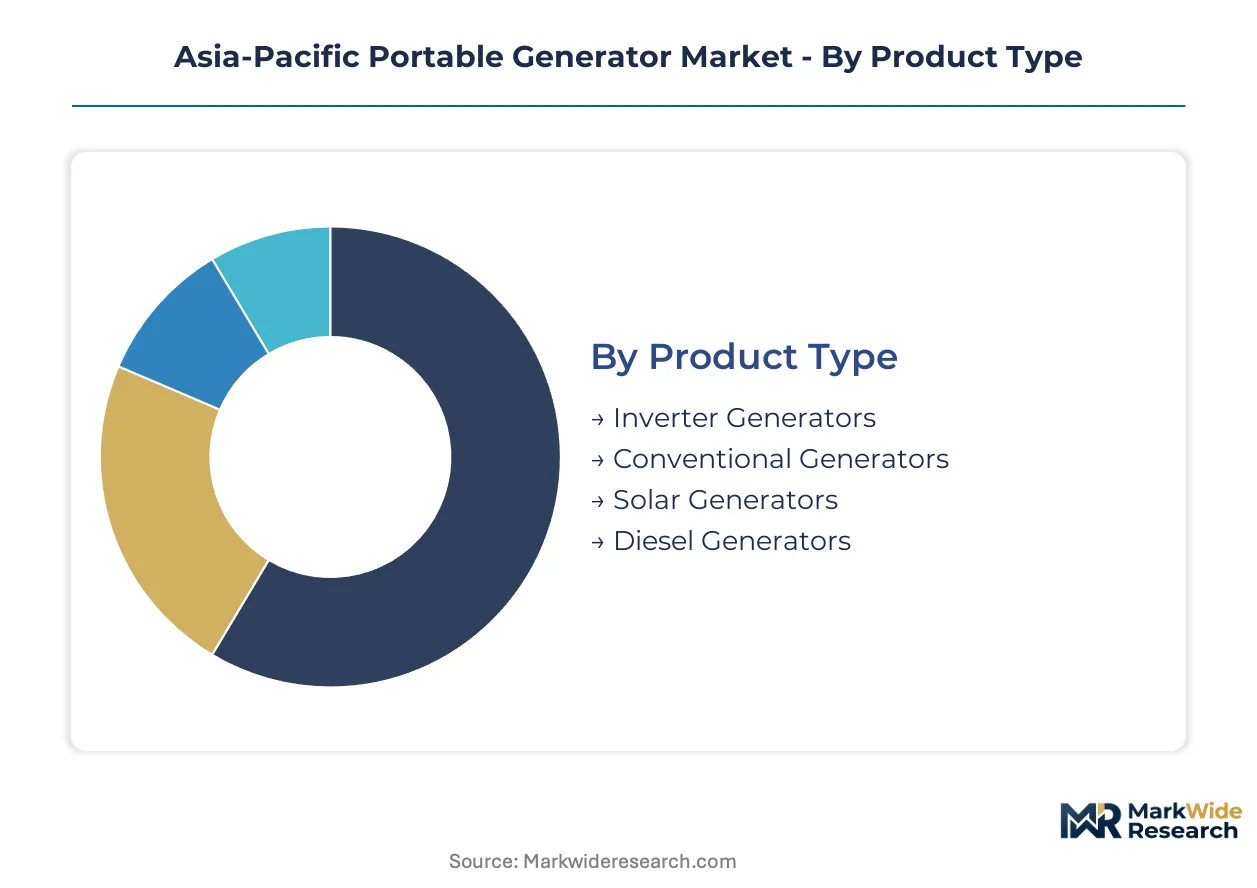
Portable generator procurement patterns diverge sharply across the Asia-Pacific based on grid reliability, fuel access logistics, and noise regulation stringency. Understanding these segment boundaries enables manufacturers to align certification investments with actual demand concentration rather than theoretical market size.
Product Type:
Buyer priorities split between power quality sensitivity and runtime economics, with developed markets paying premiums for waveform fidelity while emerging economies prioritize fuel efficiency and mechanical durability.
- Inverter Generators:These units employ high-frequency alternators with rectifier-inverter stages to produce THD below 3%, essential for Japan's residential electronics protection and Australia's home office backup demand. METI noise limits at 60 dB(A) and Australian council ordinances drive enclosure engineering that adds 15-20% to bill-of-material costs.
- Diesel Generators:Compression-ignition engines deliver 30-40% better fuel efficiency than gasoline equivalents, concentrating demand in Indonesia's archipelago mining camps and Papua New Guinea remote construction where fuel logistics dominate operating economics. Extended runtime specifications of 12-24 hours between refueling command price premiums of 25-35% over gasoline units.
- Conventional Generators:Direct-drive alternator designs dominate Thailand and Vietnam rental fleets where first-cost sensitivity outweighs noise concerns for temporary construction electrification.
- Solar Generators:Lithium-ion buffered systems below 3 kW are displacing gasoline units in Philippines island tourism and Australian camping retail where silent operation and zero fuel logistics justify 2-3x first-cost multiples.
Conventional generators lead volumes today; solar generators are gaining share fastest in sub-3 kW residential applications.
End User:
Procurement authority and decision speed vary dramatically, from household discretionary purchases to multi-year fleet agreements negotiated by construction conglomerates.
- Construction:Heavy infrastructure contractors across Myanmar and Laos specify 10 kW+ diesel units with synchronized paralleling capability for tower crane and concrete batching operations. Rental channel consolidation in Thailand has compressed equipment refresh cycles from annual bidding to quarterly pool adjustments, concentrating volume with distributors offering integrated logistics.
- Residential:Japanese and Australian households prioritize inverter platforms for electronics protection during grid instability, while Indian residential demand concentrates in 2-5 kW gasoline units for scheduled load-shedding backup. BIS certification timelines of 8-14 months constrain new entrant access to this price-sensitive segment.
- Emergency Services:Disaster response agencies in Philippines and Indonesia specify multi-fuel flexibility and rapid-deployment skids for typhoon and seismic event response.
- Events:Festival and wedding rental operators in India and Vietnam favor 5-10 kW gasoline units with noise-compliant enclosures for urban venue restrictions.
Construction commands the largest revenue pool; residential inverter adoption is climbing the fastest in developed Asia-Pacific markets.
Fuel Type:
Fuel availability infrastructure and subsidy regimes create divergent total-cost-of-ownership calculations that override first-price comparisons.
- Gasoline:Widely distributed retail networks and established small-engine supply chains from Zhejiang and Chongqing provinces sustain volume leadership across residential and events applications. Price volatility and storage safety regulations constrain adoption in institutional procurement.
- LPG:Indonesia's subsidized LPG cylinder distribution network and lower per-kWh fuel costs drive hybrid LPG-gasoline system development for cost-conscious buyers. Dual-fuel carburetion adds 8-12% to engine cost but delivers 20-30% operating savings where LPG access is reliable.
- Propane:Cylinder exchange infrastructure in Australia and Japan supports camping and light commercial applications where fuel stability during long storage periods matters more than running cost minimization.
- Biofuel:Ethanol-gasoline blends up to E20 compatibility are emerging in Thailand and Philippines national biofuel mandate compliance, requiring fuel system material upgrades that add marginal cost.
Gasoline retains volume dominance; LPG systems are expanding most quickly in Indonesia and Vietnam.
Power Rating:
Physical portability constraints and load aggregation requirements segment demand between handheld units, wheeled residential systems, and skid-mounted industrial sets.
- 5-10 kW:This band captures Philippines rural electrification programs and Indian small commercial backup where single-phase loads aggregate to 3-7 kW typical demand. Multi-fuel flexibility and electric start features command specification premiums in government tender evaluations.
- 2-5 kW:Wheeled residential units dominate Japanese and Australian premium segments where inverter technology and sub-65 dB(A) noise ratings justify 40-60% price premiums over conventional alternatives. Compact enclosure designs enable garage storage and residential-adjacent operation.
- Under 2 kW:Handheld inverter units serve Australian camping and Japan emergency kit markets where lithium-ion power stations are eroding gasoline unit growth.
- Over 10 kW:Skid-mounted diesel sets anchor mining and heavy construction rental fleets across Papua New Guinea and Indonesia where load aggregation and continuous duty cycles demand industrial alternator specifications.
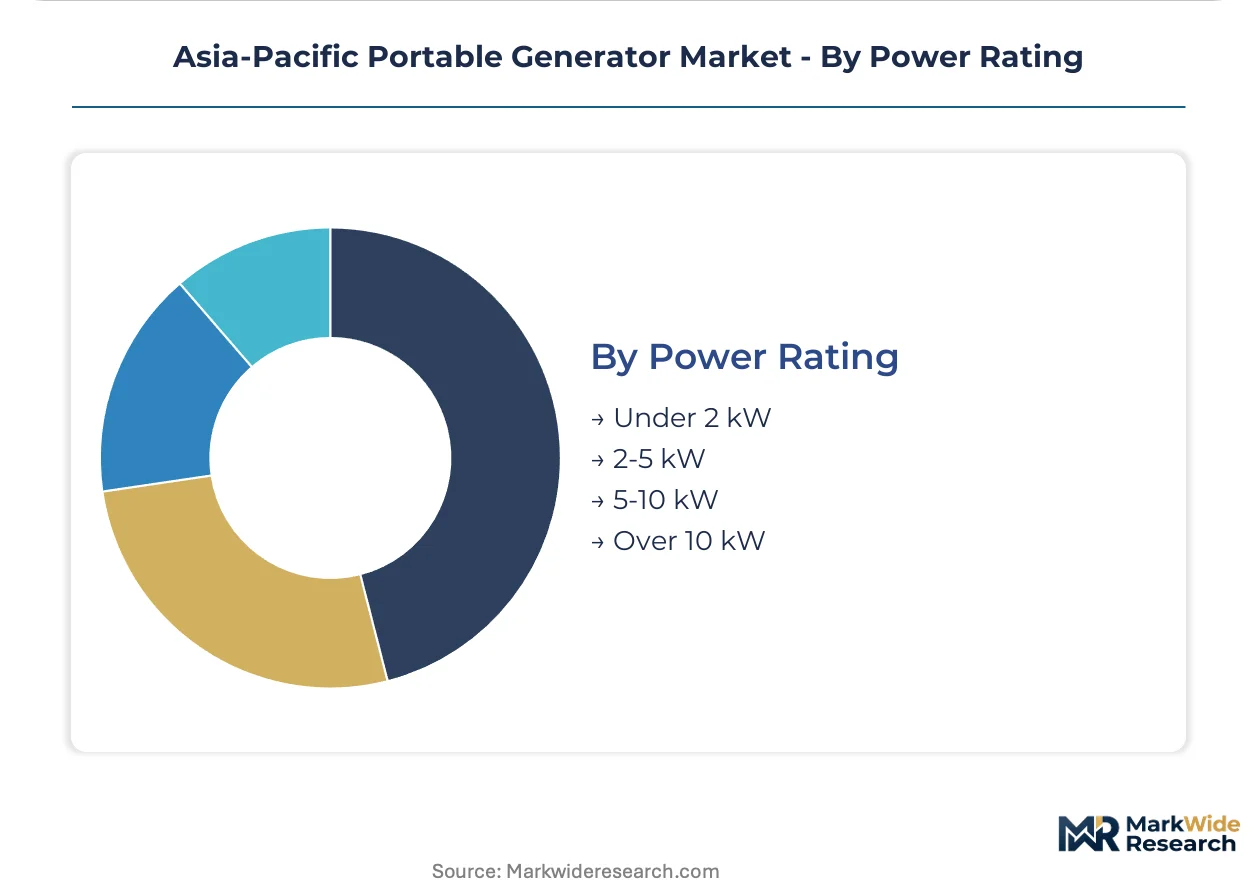
2-5 kW units generate the highest unit volumes; 5-10 kW systems show the steepest expansion trajectory in Southeast Asian infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as producers migrate assembly to Southeast Asian jurisdictions with streamlined certification pathways. Cost-of-compliance gaps between developed and emerging Asia-Pacific economies now exceed 20 percentage points on emission testing and factory audit requirements.
Indonesia
Archipelago infrastructure projects and rural electrification programs are concentrating demand around 5-10 kW diesel units with multi-fuel flexibility. The country's Ministry of Energy and Mineral Resources subsidizes LPG distribution networks that enable hybrid generator deployment. Mining camps across Papua and Kalimantan anchor procurement volumes for extended-runtime industrial sets.
India
Scheduled load-shedding in Maharashtra and Tamil Nadu sustains residential backup demand for 2-5 kW gasoline units despite lithium-ion substitution at the margin. BIS emission mandates and factory audit protocols extend product launch cycles by 8-14 months for new entrants. Manufacturing clusters in Pune and Chennai host assembly operations serving domestic and export markets.
Japan
METI noise limits at 60 dB(A) for residential-adjacent applications force enclosure engineering that adds 15-20% to bill-of-material costs. Premium inverter segments in Tokyo and Osaka metropolitan areas prioritize waveform fidelity for electronics protection. Kanto region distributors dominate channel consolidation for home office backup systems.
Australia
Council noise ordinances and camping retail expansion drive sub-3 kW inverter adoption in New South Wales and Queensland. TGA-equivalent electrical safety standards and parallel METI certification enable dual-market platform engineering. Mining services companies in Western Australia specify skid-mounted diesel sets for remote site electrification.
Vietnam
Construction rental fleet consolidation in Ho Chi Minh City and Hanoi has compressed equipment refresh cycles to quarterly pool adjustments. ASEAN harmonized technical regulations reduce certification duplication for regional assembly operations. Northern industrial zones host engine component sourcing for cross-border supply chains.
Asia-Pacific Portable Generator Market Competitive Environment
Portfolio diversification dominates the current landscape as established players bifurcate offerings between premium inverter platforms and ruggedized conventional units. The vendor base organizes around three strategic archetypes: Japanese precision-engineering specialists, American diesel-heavy equipment anchors, and European rental-channel integrators. Capacity expansion and technology licensing represent the two most visible competitive vectors as firms address regulatory divergence across developed and emerging markets.
Within the precision-engineering tier, Yamaha Motor Co., Ltd. and Honda Motor Co., Ltd. exemplify waveform-quality leadership targeting residential electronics protection. Kohler Co. anchors the diesel-specialist position for mining and heavy construction applications. Generac Power Systems occupies the gasoline-powered residential segment through distribution scale in price-sensitive emerging markets.
| Leading Market Players |
|---|
| Yamaha Motor Co., Ltd. |
| Kohler Co. |
| Generac Power Systems |
| Atlas Copco AB |
| Cummins Inc. |
| Caterpillar Inc. |
| Briggs & Stratton Corporation |
| Wacker Neuson SE |
| Honda Motor Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Construction rental fleet operators in Thailand and Vietnam command volume-based pricing leverage that compresses distributor margins on 5-10 kW diesel units while rewarding integrated logistics providers with multi-year contract premiums. Their consolidated procurement pools force manufacturers to absorb commodity volatility through fixed-price clauses or risk volume displacement to regional assembly competitors.
Pricing Analysis
Distributor margin layers of 18-25% on gasoline-powered residential units separate factory gate from retail shelf, with premium inverter segments in Japan and Australia supporting 40-60% markups over conventional alternatives. Price differentiation rests on METI noise certification and BIS emission compliance tiers rather than raw performance specifications. Pricing pressure stems from lithium-ion power station substitution below 3 kW, eroding growth in camping and light backup applications. Indian residential buyers exhibit highest price sensitivity, while Australian mining services companies accept 25-35% premiums for extended-runtime diesel specifications.
Supply Chain Analysis
Certification gating through BIS factory audits and METI noise testing extends supplier qualification timelines, favoring established players with dedicated compliance resources over cross-border entrants. Engine block casting and alternator winding production concentrates in China, Thailand, and India, with small gasoline engine supply anchored in Zhejiang and Chongqing provinces. Copper magnet wire and steel enclosure materials draw from commodity markets with volatile spot pricing. Single-source vulnerability runs through China-centric engine sourcing amplified by port congestion and documentation delays. Distribution runs through construction equipment rental networks and authorized dealer channels with aftermarket parts e-commerce emerging as a direct bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on inverter technology maturation enabling premium positioning in developed Asia-Pacific economies while diesel specialization captures infrastructure buildout economics in Indonesia and Papua New Guinea.
For Market Incumbents: Hedge lithium-ion substitution risk by accelerating hybrid power system development combining small gasoline engines with lithium-ion buffer batteries for telecom and construction rental applications. Deepen backward integration into alternator winding production to offset copper price volatility. Secure BIS pre-certification for engine platforms to compress India launch cycles before emission mandates tighten further. For New Entrants and Emerging Players: Enter via Philippines rural electrification programs and Indonesia's subsidized LPG network where multi-fuel flexibility commands specification premiums in government tenders. Target 5-8 kW portable units with electric start features for Barangay electrification deployment. Pursue e-commerce spare parts channels—carburetors, filters, control modules—to capture aftermarket revenue without dealer network investment. For Investors and Strategic Acquirers: Diesel-heavy equipment specialists and Japanese precision-engineering firms are the most active acquirers in this space, seeking inverter technology licenses and regional assembly footprints. Long-term viability favors manufacturers with dual-certified platforms spanning METI noise limits and ASEAN harmonized emission standards. Watch lithium-ion power station cost curves as the inflection signal for gasoline unit displacement rates in sub-3 kW residential segments.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Generator Development | LPG-gasoline hybrid systems address Indonesia's subsidized fuel access while meeting METI export standards. |
| ASEAN Assembly Footprint Expansion | Regional production in Thailand and Vietnam reduces BIS certification duplication costs for India market access. |
| Inverter Technology Licensing | Clean power waveform capabilities open premium residential segments in Japan and Australia to new entrants. |
| E-Commerce Aftermarket Channel | Direct-to-consumer spare parts sales bypass traditional dealer networks and capture aging fleet maintenance spend. |
| Hybrid Power System Integration | Gasoline-lithium buffer combinations reduce fuel logistics costs for Indonesian telecom tower operators. |
Study Parameters
Multiple input streams—primary interviews with construction fleet managers, generator distributor principals, and aftermarket service technicians; secondary validation through customs trade data, BIS certification registries, and METI noise compliance filings; plus bottom-up unit shipment aggregation and top-down market sizing reconciliation—were synthesized to produce segment-level estimates. Conversations with rental channel operators in Thailand and Vietnam, mining services procurement leads in Western Australia, and rural electrification program officials in the Philippines informed demand concentration assumptions. Cross-reference against ASEAN harmonized technical regulation documentation and India BIS factory audit protocols supplied regulatory compliance cost parameters.
Historical shipment trajectories were cross-referenced against expert panel inputs from OEM product planning directors and regional sales heads to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type (inverter, diesel, conventional, solar), end-use vertical (construction, residential, emergency services, events), fuel type (gasoline, LPG, propane, biofuel), and power rating tier. CAGRs were derived from elasticity-adjusted demand curves incorporating commodity price scenarios and substitution threat parameters. Industry-specific forecast inputs encompassed Indonesia archipelago infrastructure project pipelines and India scheduled load-shedding frequency by state utility.
Inputs from construction equipment rental databases and government tender announcement portals were available through the study window; gaps in real-time inventory positioning at distributor level introduce uncertainty bands around quarterly shipment timing assumptions. Forecasts reflect documented assumptions regarding BIS certification timeline stability and ASEAN regulatory harmonization progress. A model refresh is warranted upon material change in lithium-ion power station cost parity thresholds or METI noise limit enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Industrial Generator Sets Market
Generators
Middle-East and Africa Generator Sets Market
Generators
United States Portable Generator Market
Generators
India Diesel Generator Market
Generators
Tanzania Diesel Generator Market
Generators
Residential Generators Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Electric Generators Market
Generators
India Generator Sets Market
Generators
Wind Turbine Alternator Market
Generators
Asia Pacific Electric Generators Market
Generators
South America Gas Generator Market
Generators
India Portable Generator Market
Generators
Commercial Generator Market
Generators
Asia-Pacific Generator Sets Market
Generators
Portable Inverter Generators Market