
 Generator [Up to 100 Kva] Market | 2026-2036
Generator [Up to 100 Kva] Market Size, Share, and Industry Trends Forecast 2026-2036
Generator [Up to 100 Kva] Market Foresight
The EU Green Deal's push for low-emission backup power is expanding addressable demand for sub-100 kVA units across commercial and industrial sites. Cummins Inc. leverages its integrated engine-alternator manufacturing to sustain cost advantages in diesel-gas hybrid configurations. Generac Power Systems anchors its position through residential and small commercial channel density in North America. Kohler Co. differentiates via permanent magnet alternator technology for data center clients requiring harmonic distortion below 5%.
Generators rated up to 100 kVA convert mechanical energy into electrical output spanning 5–100 kilovolt-amperes, typically employing diesel or natural gas reciprocating engines driving synchronous or brushless alternators for prime or standby power at construction camps, telecom towers, and rural agricultural operations. Diesel generators retain the largest installed base due to fuel accessibility and capital cost thresholds, though gas generators gain share where pipeline infrastructure exists and emission regulations tighten. Digital control technology is displacing analog voltage regulation as telecom operators and data center managers demand remote monitoring, automatic load sharing, and predictive maintenance integration.
The EPA's Tier 4 Final standards for non-road diesel engines and the EU's Stage V emission regulations constrain product eligibility in their respective markets, while India's CEA notification on captive power plant emission limits shapes import and domestic manufacturing decisions. ISO 8528 performance classification and IEC 60034-1 electrical safety standards govern product certification for international market access. Stakeholders must monitor hydrogen generator cost curves and electrolyzer miniaturization trajectories to assess displacement risk for fossil-fueled units in backup applications.
Market Dynamics
India's Bureau of Indian Standards emission tightening for diesel gensets below 100 kVA is forcing widespread engine platform upgrades across the subcontinent, while telecom infrastructure expansion across Southeast Asian archipelagos sustains demand volatility that favors modular procurement.
Growth Catalysts
- Telecom backup power procurement:Southeast Asian operators are expanding genset orders as grid reliability fluctuates across Indonesia's island networks and Vietnam's manufacturing corridors.
- EU Green Deal low-emission mandates:Commercial and industrial sites across member states face backup power decarbonization deadlines that expand addressable demand for sub-100 kVA hybrid configurations.
- Digital control technology:Remote monitoring and predictive maintenance integration is displacing analog voltage regulation as data center managers and telecom operators mandate fleet connectivity.
Market Restraints
- EPA Tier 4 Final compliance costs:Non-road diesel engine certification expenses compress margins for sub-100 kVA manufacturers serving the US market.
- Natural gas pipeline infrastructure gaps:Gas generator penetration remains constrained outside established distribution networks in North America and Western Europe.
- Hydrogen generator cost curves:Electrolyzer miniaturization trajectories threaten long-term displacement of fossil-fueled backup units in premium applications.
Strategic Opportunities
- India CEA captive power notification:Emission limit enforcement creates upgrade cycles for existing installed base across Maharashtra and Gujarat industrial clusters.
- Permanent magnet alternator convergence:Data center harmonic distortion requirements below 5% open premium positioning for advanced alternator architectures.
- Diesel-gas hybrid channel innovation:Integrated engine-alternator manufacturers can capture retrofit demand through direct service contracting models.
Industry Challenges
- ISO 8528 certification timeline compression:Multi-standard compliance for international market access strains product development bandwidth.
- IEC 60034-1 electrical safety integration:Synchronous and brushless alternator platforms require redesign to satisfy evolving insulation and thermal protection thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generator [Up to 100 Kva] Market |
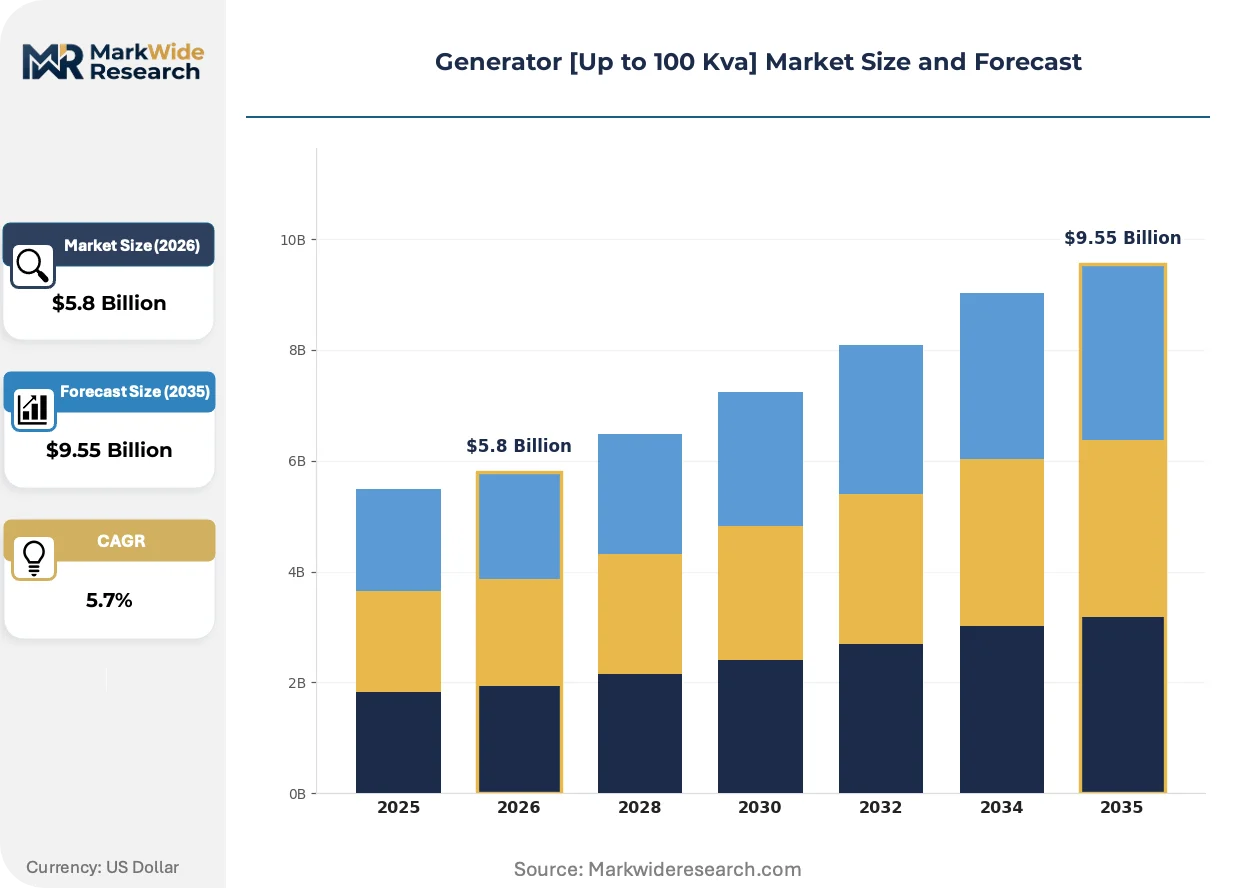
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generator, Gas Generator, Solar Generator, Battery Generator, Hydrogen Generator Technology: Brushless, Synchronous, Permanent Magnet, Asynchronous, Digital Control Application: Telecommunication Sites, Construction Sites, Data Centers, Emergency Backup, Agriculture End User: Telecom Operators, Building Contractors, IT Firms, Disaster Management Agencies, Farming Enterprises |
| Companies Covered | Cummins Inc., Generac Power Systems Inc., Caterpillar, Kohler Co., HIMOINSA, KOEL Green, Perkins, Atlas Copco, Multiquip Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generator [Up to 100 Kva] Market Shifts & Advancements
Generator architecture is converging around digital control layers that bridge operational technology with enterprise IT systems, compressing the traditional separation between power generation assets and facility management platforms.
Permanent magnet alternator technology is integrating harmonic distortion suppression capabilities that satisfy data center power quality specifications below 5% THD. Hyperscale operators in Northern Virginia and Frankfurt are specifying these configurations for edge computing nodes. The technology is integrating predictive maintenance algorithms that reduce unplanned downtime exposure for critical backup applications.
India's Bureau of Indian Standards tightened emission norms for diesel gensets below 100 kVA compels domestic and import manufacturers to deploy catalytic aftertreatment or migrate to gas engine platforms. Engine upgrade costs are reshaping procurement economics for construction camps and agricultural operations. Rural telecom tower operators are responding with accelerated gas generator trials where LNG logistics permit.
Telecom infrastructure buyers are consolidating vendor relationships around fleet management contracts that bundle equipment, fuel logistics, and predictive maintenance. Traditional equipment-only distribution channels face margin compression as operators seek operational expenditure predictability. This pattern concentrates in Indonesia's island networks where geographic dispersion amplifies service complexity.
Generator [Up to 100 Kva] Market Segmentation
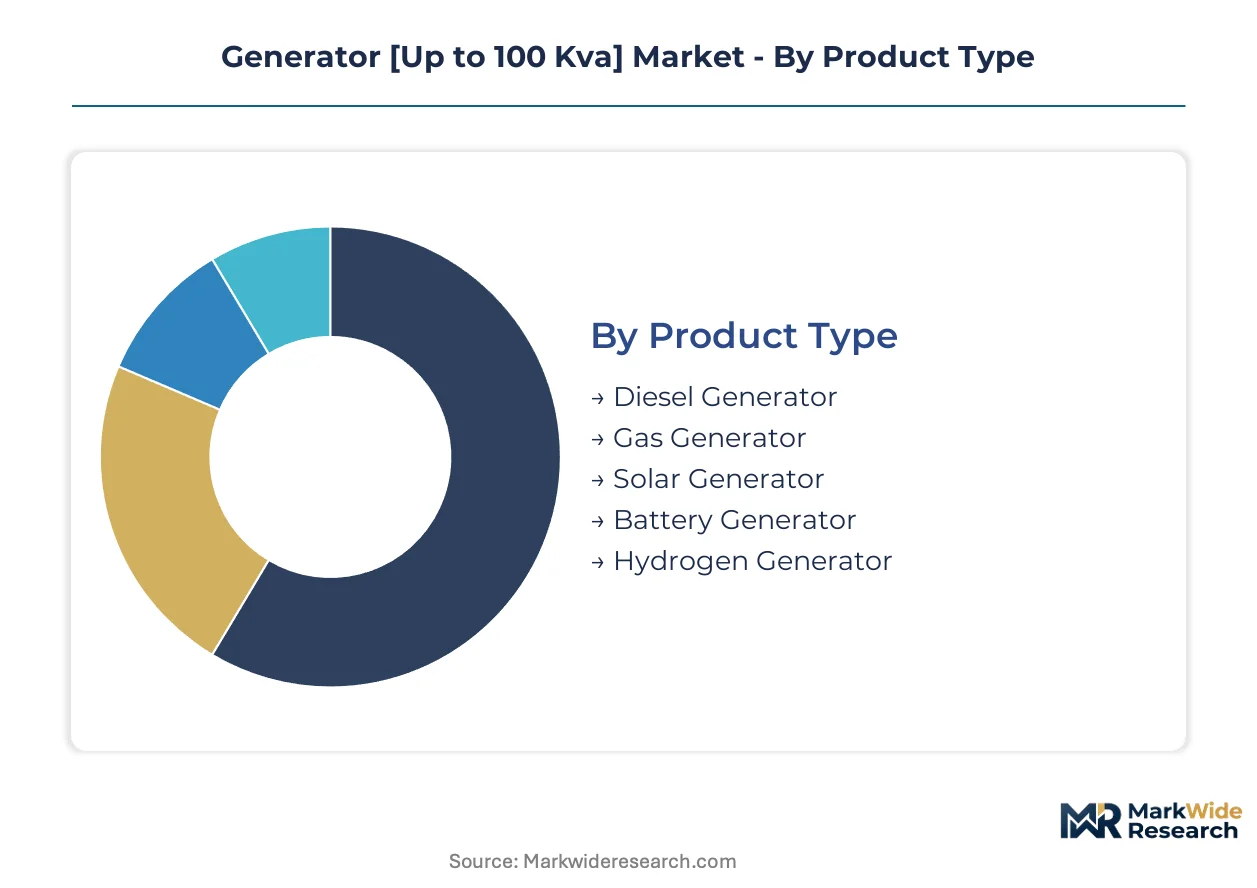
Segmentation in the sub-100 kVA generator market reveals how fuel choices, alternator architectures, and end-use requirements fragment procurement patterns across telecom infrastructure, construction logistics, and edge computing deployments.
Product Type:
Buyers select fuel platforms based on capital constraints, fuel logistics, and emission compliance timelines in their operating geographies.
- Diesel Generator:Reciprocating diesel engines driving synchronous alternators dominate installed base due to fuel accessibility and lower upfront capital. Demand concentrates in India's construction corridors and Indonesia's island telecom networks where BIS emission upgrades and LNG logistics gaps sustain diesel preference despite aftertreatment cost pressure.
- Gas Generator:Natural gas reciprocating engines offer lower particulate emissions and reduced fuel volatility exposure where pipeline infrastructure exists. Procurement is accelerating across EU commercial sites facing Green Deal decarbonization deadlines and Maharashtra industrial clusters responding to CEA captive power notifications.
- Solar Generator:PV-battery hybrid systems with diesel backup integration serve remote agricultural operations and rural telecom towers with predictable load profiles.
- Battery Generator:Lithium-ion based mobile power units address short-duration backup for urban construction and event infrastructure with noise restrictions.
- Hydrogen Generator:Proton exchange membrane fuel cell systems in sub-100 kVA ratings remain pilot-scale for premium data center edge nodes.
Diesel generator leads on scale; gas generator leads on momentum.
Technology:
Alternator architecture selection hinges on harmonic distortion tolerance, maintenance access economics, and digital integration requirements.
- Brushless:Self-exciting alternators with rotating rectifier assemblies eliminate brush maintenance and dominate construction site rentals. Brushless platforms anchor Cummins and Kohler product lines for telecom tower operators prioritizing service interval extension.
- Permanent Magnet:Rare-earth magnet rotors deliver sub-5% THD for hyperscale data center edge specifications in Northern Virginia and Frankfurt. Permanent magnet alternators are gaining share fastest among IT firms with power quality mandates.
- Synchronous:Conventional wound-field alternators with AVR voltage regulation serve agricultural and emergency backup applications with standard power quality requirements.
- Asynchronous:Induction generator configurations find limited application in variable-speed renewable hybrid systems.
- Digital Control:Microprocessor-based voltage regulation with IoT telemetry integration is displacing analog systems across telecom operator fleet contracts.
Brushless technology commands the largest installed footprint; permanent magnet architectures show steepest expansion trajectory.
Application:
Site-specific duty cycles, reliability tiers, and environmental exposure dictate generator specification and service contracting models.
- Telecommunication Sites:Continuous or prime power ratings for base transceiver stations and microwave relay towers across archipelagic geographies. Indonesian operators are consolidating vendor relationships around fuel-logistics-inclusive fleet management contracts.
- Data Centers:Tier III and Tier IV facilities specify permanent magnet alternators for edge computing nodes with harmonic distortion below 5% THD.
- Construction Sites:Portable rental fleets favor brushless diesel units with skid-mounted fuel tanks for mobility and rapid deployment.
- Emergency Backup:Hospitals and critical infrastructure mandate automatic transfer switch integration with sub-10-second start requirements.
- Agriculture:Irrigation pump sets and cold chain operations in rural India deploy low-cost synchronous alternators with manual start protocols.
Telecommunication sites anchor volume demand; data center applications command premium positioning.
End User:
Procurement sophistication varies from capital-purchase equipment ownership to operational expenditure-based service contracts.
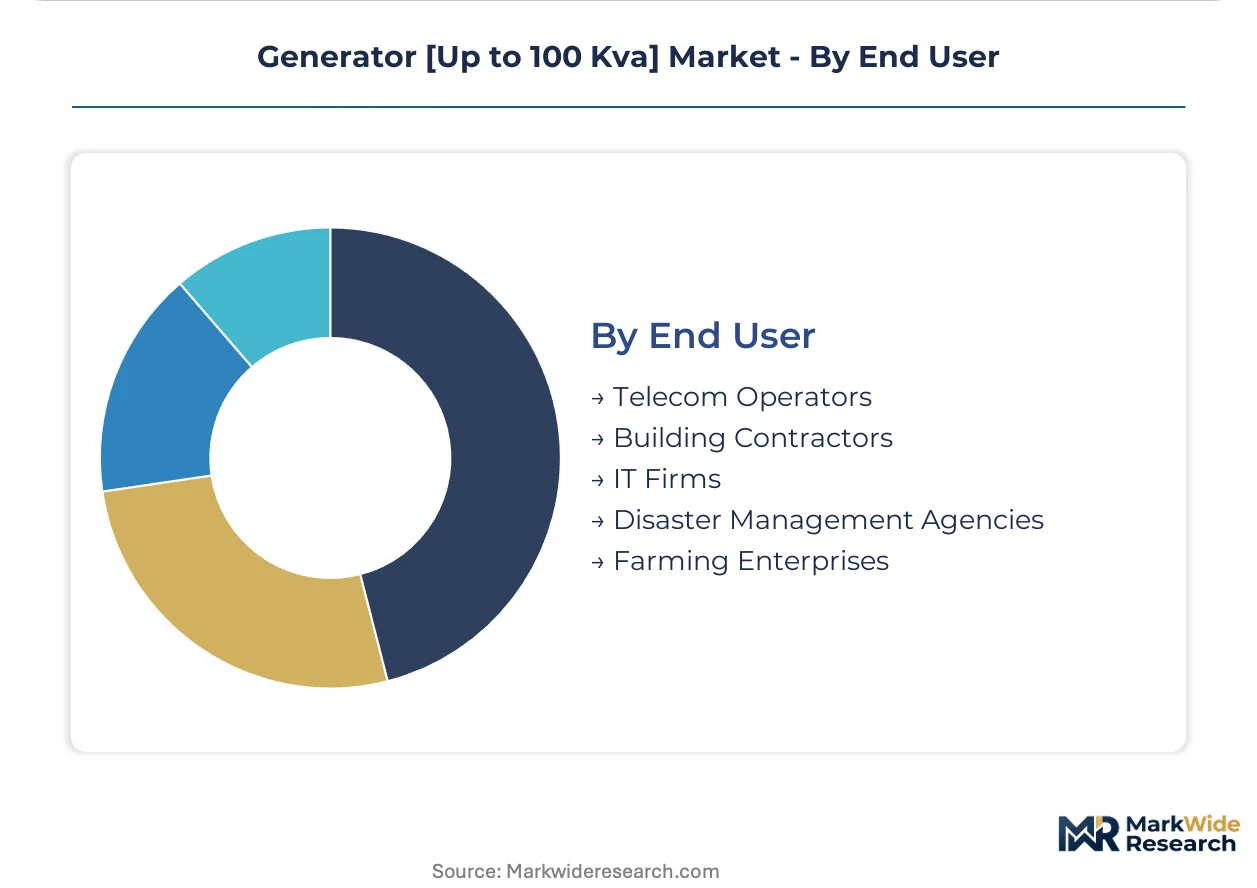
- Telecom Operators:Tower companies and mobile network operators across Southeast Asia are shifting from equipment purchase to power-as-a-service models bundling genset, fuel, and maintenance. Indosat and Viettel procurement patterns favor multi-year fleet management agreements over traditional distributor relationships.
- IT Firms:Hyperscale cloud providers and colocation operators specify permanent magnet alternators with predictive maintenance integration for edge facility deployments.
- Building Contractors:Rental fleet operators and construction project managers prioritize brushless diesel portability and rapid technician response networks.
- Disaster Management Agencies:Government emergency response units procure mobile generator trailers with multi-fuel capability and NATO plug standardization.
- Farming Enterprises:Agricultural cooperatives and plantation operators in India's Gujarat and Maharashtra states face CEA emission compliance upgrade cycles for existing captive power installations.
Telecom operators drive contract innovation; IT firms set technical specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools at Pune, Detroit, and Stuttgart anchor generator manufacturing and alternator design capabilities across three continents.
United States
Data center construction in Northern Virginia and hyperscale edge deployments across Dallas-Fort Worth drive demand for permanent magnet alternators with sub-5% harmonic distortion. EPA Tier 4 Final compliance costs compress margins for diesel engine manufacturers serving the non-road market. Michigan-based engineering clusters concentrate alternator design expertise for telecom and industrial applications.
India
Telecom tower densification across Maharashtra and Gujarat industrial corridors sustains procurement volumes for sub-100 kVA units. The Bureau of Indian Standards tightened emission norms for diesel gensets below 100 kVA, compelling catalytic aftertreatment retrofits. Construction camps in Karnataka and cold chain operations in Haryana face upgrade cycles for existing captive power installations.
Germany
EU Green Deal decarbonization deadlines for commercial backup power expand addressable demand for gas generator configurations. The Stage V emission regulations constrain diesel product eligibility while accelerating hybrid system trials. Industrial clusters in Baden-Württemberg concentrate precision alternator manufacturing for data center specifications.
Indonesia
Archipelagic telecom infrastructure across Java and Sumatra sustains volatile demand patterns favoring modular genset procurement. Geographic dispersion amplifies service complexity, driving operators toward fuel-logistics-inclusive fleet management contracts. Tower companies in Sulawesi and Kalimantan consolidate vendor relationships around multi-year power-as-a-service agreements.
Vietnam
Manufacturing corridor expansion in Bac Ninh and Hai Phong industrial zones sustains construction site power demand. Grid reliability fluctuations across northern provinces accelerate backup power procurement for foreign-invested factories. Domestic assembly operations in Ho Chi Minh City concentrate low-cost synchronous alternator production for agricultural applications.
Generator [Up to 100 Kva] Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the sub-100 kVA generator landscape. Integrated engine-alternator manufacturers retain cost advantages in diesel-gas hybrid configurations, while specialized alternator houses capture premium positioning through permanent magnet architectures. The vendor base separates into three archetypes: full-system integrators, component specialists, and regional assemblers. Competitive moves concentrate on digital control platform development and fleet management contract bundling.
Within the integrated-system tier, Cummins Inc. and Caterpillar exemplify capital-intensive manufacturing footprints spanning engine production through alternator assembly. Kohler Co. occupies a position emphasizing permanent magnet technology for power-quality-sensitive applications. These three anchors represent divergent strategic postures across cost leadership, technical differentiation, and channel density in North American and Asian markets.
| Leading Market Players |
|---|
| Cummins Inc. |
| Generac Power Systems Inc. |
| Caterpillar |
| Kohler Co. |
| HIMOINSA |
| KOEL Green |
| Perkins |
| Atlas Copco |
| Multiquip Inc. |
| Others |
Supply & Pricing Matrix
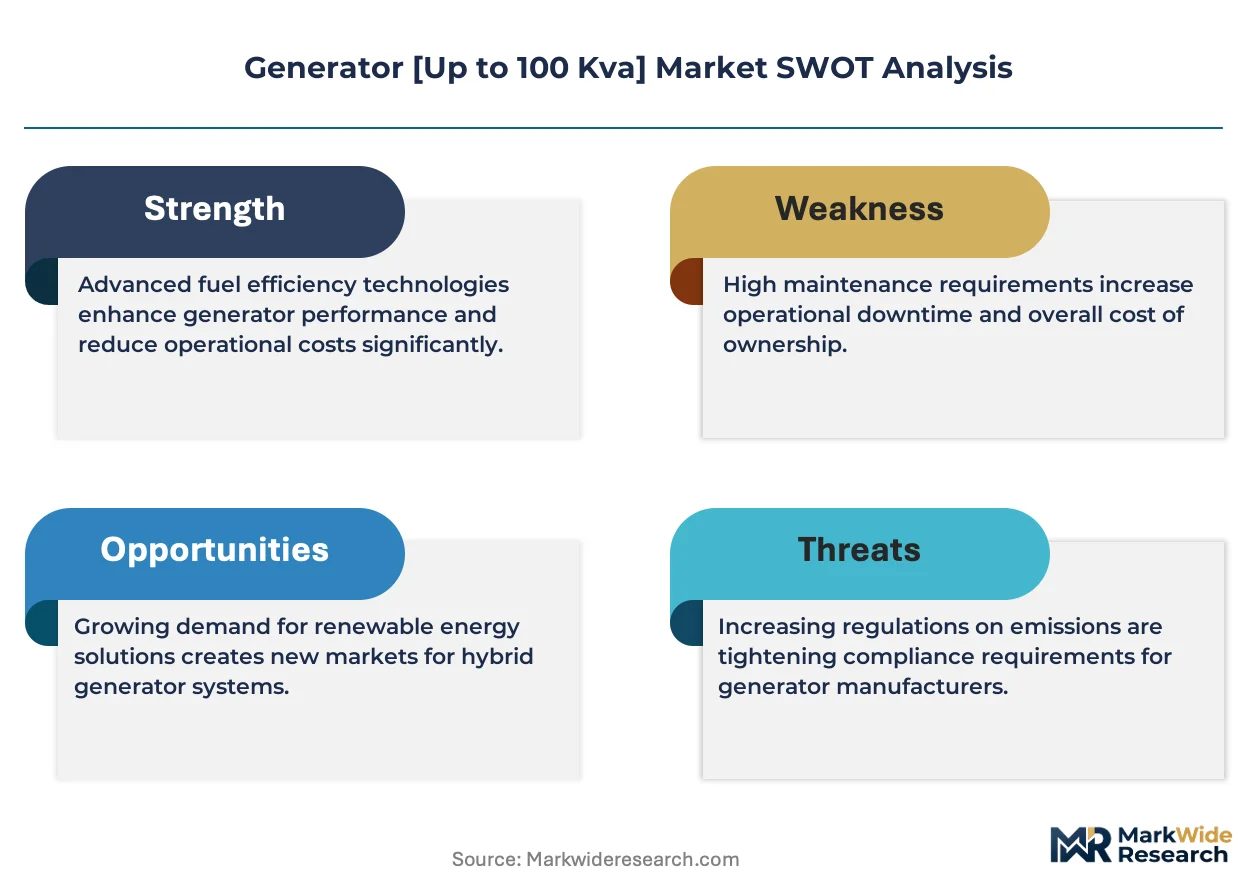
EPA Tier 4 Final emission mandates gate qualified supply for diesel generator platforms serving the US market, compressing manufacturer margins while elevating premium-tier pricing for compliant engine-alternator configurations. Buyers face bifurcated procurement economics between certified Tier 4 Final units and non-compliant inventory liquidated to less regulated geographies.
Pricing Analysis
Bundled fleet management contracts versus unbundled equipment-only sales split pricing architecture across telecom operator procurement. Three-tier pricing structure across premium permanent magnet alternators, standard brushless configurations, and economy synchronous units reflects certification grade and harmonic distortion performance. Pricing pressure stems from EPA compliance cost absorption in the US and BIS aftertreatment retrofits in India. Construction rental fleets exhibit highest price sensitivity; data center operators demonstrate lowest sensitivity to capital cost premiums for sub-5% THD specifications.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale data center operators and Tier 1 telecom tower companies mandate multi-supplier qualification for engine blocks and alternator assemblies. Manufacturing concentrates in the United States, India, and Germany for precision alternator winding and engine block casting. Rare-earth magnet supply for permanent magnet rotors draws from concentrated mining operations, creating single-source vulnerability for advanced alternator architectures. Distribution runs through authorized dealer networks with factory-direct service contracting for fleet management accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where emission standard ratcheting—India's BIS tightening for sub-100 kVA diesel gensets—forces recurring equipment replacement cycles across installed base.
For Market Incumbents: Extend digital control platform development to capture predictive maintenance revenue streams from telecom operator fleet contracts. Integrate backward control over alternator winding operations to defend margin position against catalytic aftertreatment cost pressure. Prioritize gas engine platform certification for EU Green Deal commercial backup deadlines. For New Entrants and Emerging Players: Begin with solar-diesel hybrid configurations for remote agricultural operations in India's Haryana and Karnataka states where grid reliability gaps and capital constraints intersect. Target Maharashtra industrial clusters responding to CEA captive power emission notifications with retrofit-focused service models. Deploy direct contracting with farming cooperatives bypassing traditional equipment distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers lacking integrated engine production but holding established service networks in Southeast Asian archipelagic markets. Long-term viability hinges on hydrogen generator cost curve displacement timelines for premium backup applications. Watch electrolyzer miniaturization announcements as inflection signal for fossil-fueled backup obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Alternator Scale-Up | Captures hyperscale data center edge specifications in Northern Virginia and Frankfurt requiring sub-5% THD. |
| Diesel-Gas Hybrid Platform Launch | Addresses EU Green Deal decarbonization deadlines and India's BIS emission compliance upgrade cycles. |
| Predictive Maintenance Integration | Converts telecom operator relationships from equipment transactions to recurring fleet management revenue. |
| CEA Notification Compliance Program | Unlocks Maharashtra and Gujarat industrial cluster retrofit demand for captive power installations. |
| Authorized Dealer Network Expansion | Secures channel density for construction rental fleet penetration in Vietnam's Bac Ninh manufacturing corridor. |
Research Methodology
Direct dialogue with generator OEM product managers, telecom tower procurement directors, data center facility engineers, and aftermarket service heads grounded qualitative findings in operational realities. Secondary validation drew from EPA certification databases, BIS notification records, EU Stage V regulatory filings, and customs trade data for engine-alternator import flows. Bottom-up unit shipment estimates across fuel type, alternator technology, and end-use application triangulated against top-down market value reconstruction.
Analytical lens combined bottom-up segment aggregation with top-down macro constraint calibration across the projection horizon. Segmentation dimensions spanned fuel platform, alternator architecture, application duty cycle, and regional regulatory framework. CAGRs derived from fitted growth curves anchored to disclosed equipment procurement patterns and emission compliance deadline impacts. Forecast inputs incorporated telecom infrastructure capex trajectories and electrolyzer cost curve assumptions for hydrogen displacement scenarios.
Several conditions sit outside the modeled scope, including military generator demand, marine propulsion applications, and residential standby power below 5 kVA ratings. Forecasts reflect assumptions regarding grid reliability trends, LNG infrastructure buildout pace, and rare-earth magnet supply stability. Deviation in hydrogen generator cost reduction velocity would shift the outlook materially for fossil-fueled backup positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
South America Diesel Generator Market
Generators
Gas Generator Sets Market
Generators
South Africa Diesel Generator Market
Generators
Dual-Fuel Generator Market
Generators
Asia-Pacific Gas Generator Market
Generators
Africa Diesel Generator Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Construction Generator Sets Market
Generators
South America Portable Generator Market
Generators
South America Generator Sets Market
Generators
Generator Rental Market
Generators
United States Diesel Generator Market
Generators
China Generator Sets Market
Generators
North West Europe Diesel Generator Market
Generators
US Generator Sales Market
Generators
Middle East and Africa Gas Generator Market