
 North America Shrimp Feed Market | 2026-2036
North America Shrimp Feed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Shrimp Feed Market Intelligence
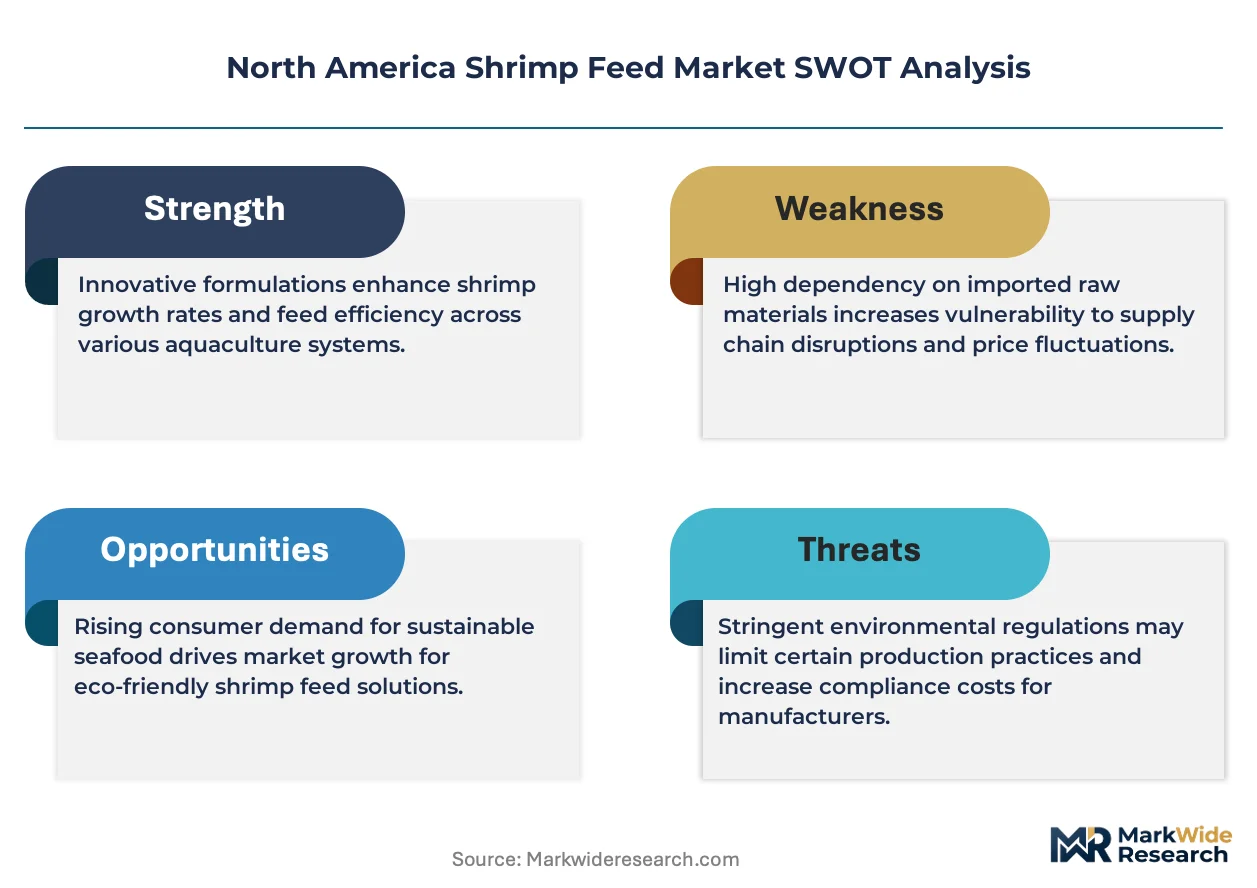
The EPA's revised Clean Water Act effluent guidelines for concentrated aquatic animal production is repositioning feed formulation priorities across North American shrimp operations. Cargill, Incorporated leverages its integrated supply chain from grain procurement to finished feed to sustain cost advantages in bulk deliveries to Gulf Coast aquaculture zones. ADM Animal Nutrition anchors its position through deep backward integration into oilseed processing, securing consistent supply of soy-based protein ingredients. Nutreco N.V. differentiates via advanced aquaculture nutrition research, competing on feed conversion ratio performance rather than commodity pricing alone.
North America shrimp feed comprises scientifically formulated diets containing proteins, lipids, carbohydrates, vitamins, and minerals engineered to optimize growth rates and survival in penaeid shrimp species, typically manufactured through extrusion or pelleting processes to achieve water stability in marine and brackish environments. Extruded feed dominates commercial aquaculture applications due to superior digestibility and reduced nutrient leaching in high-salinity conditions, while pellet feed occupies cost-sensitive farming segments where manual feeding practices persist. Plant-based ingredient sources are displacing fish meal in formulations as soybean meal and alternative protein concentrates advance on price stability and sustainability credentials, though omega-3 fatty acid enrichment remains critical for larval and broodstock diets.
The USDA's National Organic Program standards and FDA's animal food safety regulations under FSMA jointly shape ingredient sourcing protocols and manufacturing facility compliance requirements for shrimp feed producers operating in the United States. Mexico's aquaculture health regulator and Health Canada's CFIA feed division impose parallel import and safety standards that cross-border suppliers must navigate for market access. Stakeholders must monitor evolving state-level water quality permits and organic certification thresholds as these frameworks increasingly determine which formulation technologies and ingredient portfolios qualify for premium market segments.
Market Dynamics
The EPA's revised Clean Water Act effluent guidelines for concentrated aquatic animal production is compressing feed formulation economics across Gulf Coast operations, forcing mills to reformulate for higher digestibility and lower nitrogen discharge.
Growth Catalysts
- Intensive Farming Expansion:Commercial aquaculture operations across Texas and Louisiana are scaling penaeid shrimp production in climate-controlled greenhouse systems, creating concentrated demand for high-performance formulated feeds.
- USDA Organic Certification:The National Organic Program standards for aquaculture feed ingredients are opening premium pricing tiers for certified producers serving specialty retail channels.
- Extrusion Technology Maturation:Advanced extrusion processes delivering superior water stability in high-salinity conditions are enabling longer feeding intervals and reduced labor costs for pond operators.
Market Restraints
- Soybean Price Volatility:Feed mills face margin compression from fluctuating domestic soybean meal costs, the dominant protein source displacing fish meal in commercial formulations.
- Single-Region Supply Concentration:Warm-water shrimp farming clusters remain heavily concentrated along the Texas-Louisiana Gulf Coast, limiting geographic diversification of feed demand.
- Omega-3 Sourcing Bottleneck:Larval and broodstock diets require marine-derived omega-3 fatty acids that face supply constraints from reduced global fish oil production.
Strategic Opportunities
- Mexico Pacific Coast Expansion:Underdeveloped shrimp farming zones in Sinaloa and Sonora present white-space demand for feed suppliers with cross-border logistics capabilities.
- FSMA Compliance Services:FDA's Food Safety Modernization Act animal food regulations create advisory and testing service revenue streams for laboratories and consultants serving feed mills.
- Recirculating Aquaculture Systems:Closed-loop RAS installations in inland Texas and Arizona are generating demand for specialized low-waste feed formulations distinct from open-pond products.
Industry Challenges
- Aquaculture Nutrition Expertise Gap:Feed mills struggle to recruit formulators with specialized knowledge of penaeid shrimp metabolic requirements across different life stages.
- Multi-Jurisdiction Certification Complexity:Suppliers must simultaneously satisfy USDA organic protocols, FDA FSMA facility registrations, and Health Canada CFIA import standards for cross-border sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Shrimp Feed Market |
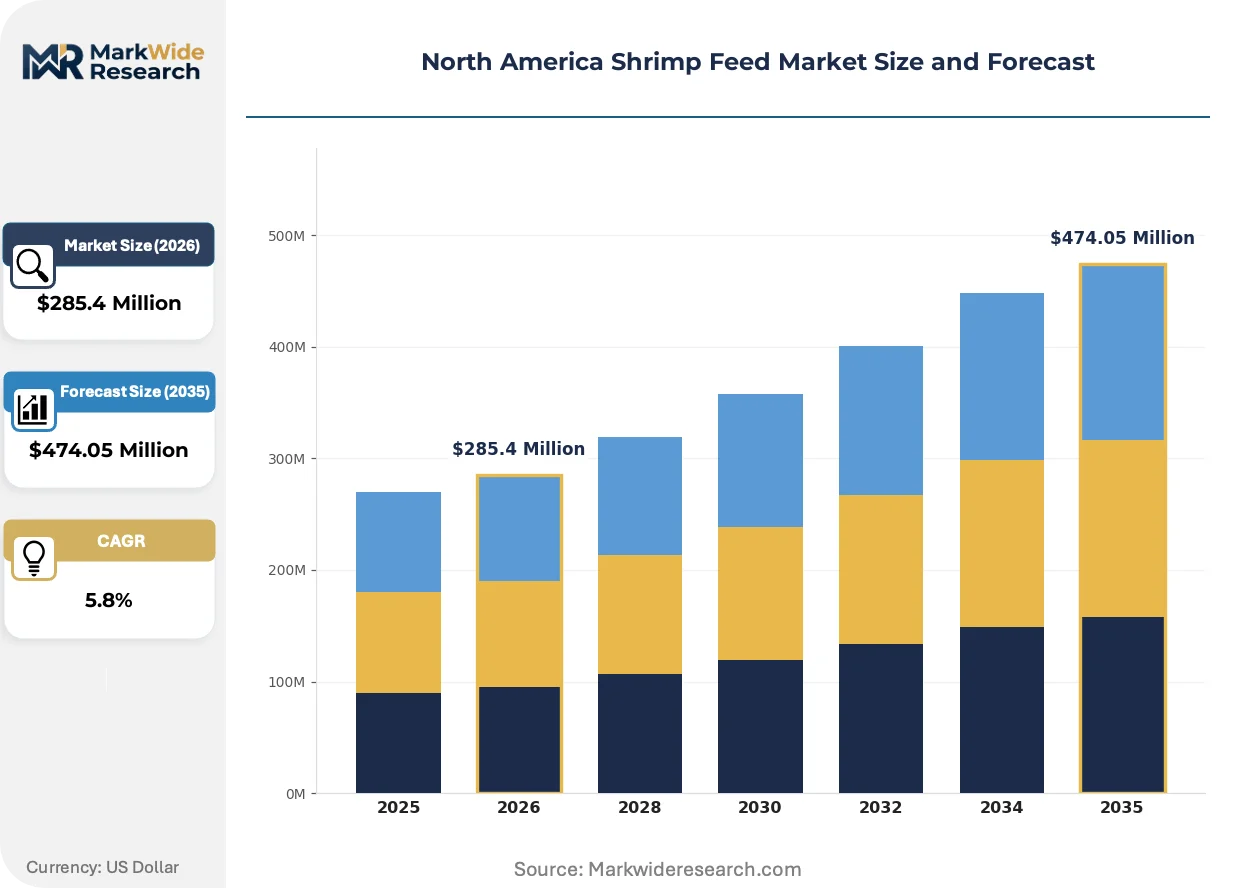
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded Feed, Pellet Feed, Liquid Feed, Granulated Feed Ingredient Source: Plant-Based, Fish Meal, Omega-3 Fatty Acids, By-products Application: Aquaculture, Research, Farming, Feed Manufacturing Packaging Type: Bags, Bulk, Tubs, Sachets |
| Companies Covered | ADM Animal Nutrition, Charoen Pokphand Foods Public Company Limited, Cargill, Incorporated, Rangen, Inc., Wilbur-Ellis Nutrition, LLC, Nutreco N.V., Alltech Inc., Land O'Lakes, BioMar Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Shrimp Feed Market Strategic Shifts & Innovations
Formulation science and manufacturing processes are advancing rapidly as environmental compliance tightens and ingredient economics shift. Three developments are restructuring competitive positioning among North American suppliers.
Extruded feed manufacturing is overtaking traditional pelleting methods across commercial Gulf Coast operations. The technology produces denser, more water-stable pellets that resist nutrient leaching in brackish pond conditions. Large-scale Texas and Louisiana farms are converting feed systems rapidly, compressing demand for legacy pelleting equipment and favoring suppliers with captive extrusion capacity.
The EPA's Clean Water Act discharge permit renewals are mandating lower total nitrogen and phosphorus effluent limits for coastal aquaculture facilities. Shrimp operators must document feed conversion efficiency and uneaten feed recovery rates to maintain operating licenses. Facilities in Louisiana's Vermilion Parish and Texas's Corpus Christi Bay area are investing in automated feeding systems that pair with high-digestibility formulations to meet permit conditions.
Direct procurement relationships between farm cooperatives and regional feed mills are displacing distributor intermediaries in volume purchasing. Large farming operations in Cameron Parish and Aransas County negotiate ingredient transparency and custom formulation terms directly with manufacturers. This channel compression is most visible among operations exceeding 500 acres of pond surface, where feed represents the dominant variable cost and justifies dedicated supply agreements.
North America Shrimp Feed Market Segmentation
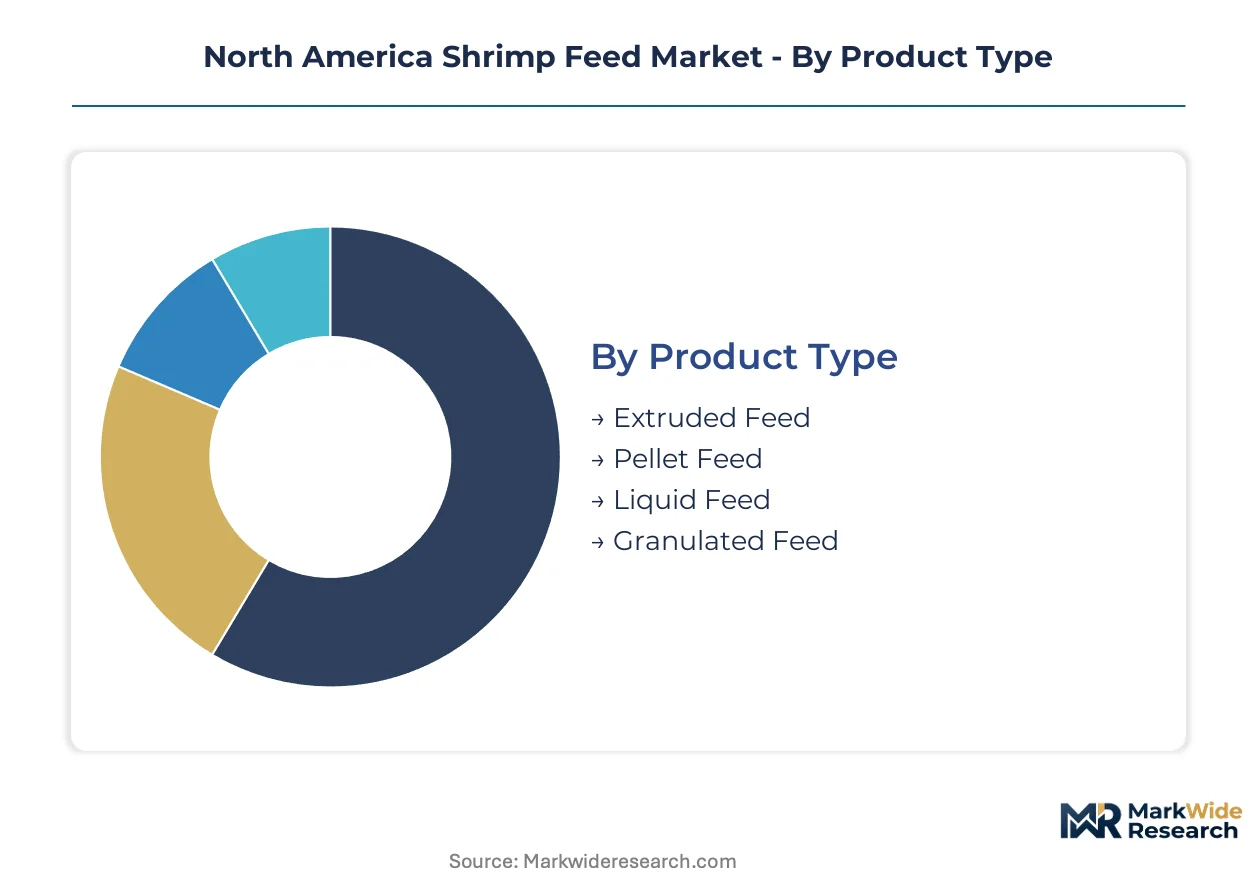
Shrimp feed segmentation in North America reflects divergent production technologies, regulatory compliance tiers, and supply chain configurations across Gulf Coast aquaculture clusters. Feed mills calibrate formulation portfolios against water stability requirements, organic certification thresholds, and the scale economics of customer operations.
Product Type:
Extrusion and pelleting technologies partition the market by water stability performance and capital intensity of manufacturing infrastructure.
- Extruded Feed:High-pressure thermal processing creates dense, water-stable pellets that resist nutrient leaching in brackish pond conditions. Texas and Louisiana commercial operations exceeding 500 acres deploy extruded formulations to support automated feeding systems and extended feeding intervals mandated by EPA discharge permits.
- Pellet Feed:Compression-formed feeds manufactured at lower capital cost serve manual feeding operations where labor absorption offsets digestibility trade-offs. Smaller farms in Vermilion Parish and Aransas County maintain pelleting procurement relationships for cost-sensitive grow-out phases.
- Liquid Feed:Suspended particulate formulations deliver micronutrients and medications directly to larval rearing tanks in hatchery operations.
- Granulated Feed:Intermediate density products occupy niche applications in nursery phase transitions between larval and grow-out diets.
Mature deployment sits with Pellet Feed. Newer deployment is concentrated in Extruded Feed.
Ingredient Source:
Protein and lipid sourcing strategies divide formulators between commodity price exposure and premium positioning through marine-derived inputs.
- Plant-Based:Soybean meal and alternative protein concentrates displace marine inputs across grow-out diets, anchored by ADM's oilseed processing integration and price stability relative to fish meal volatility. Texas and Louisiana mills source soy proteins from Midwest crushing facilities via rail and barge networks.
- Fish Meal:Peruvian anchovy and menhaden reduction products retain premium positioning in broodstock and early larval formulations where amino acid profiles remain unmatched by plant alternatives. Supply constraints from reduced global forage fish quotas compress availability for North American aquaculture.
- Omega-3 Fatty Acids:Marine oil enrichment remains mandatory for larval survival rates and reproductive performance in breeding populations.
- By-products:Poultry meal, feather meal, and rendering industry outputs provide cost-competitive protein in non-organic certified production tiers.
Cost-sensitive procurement clusters around Plant-Based. Premium positioning attaches to Fish Meal.
Application:
End-use segmentation tracks the divergence between commercial volume consumption and specialized formulations for non-production environments.
- Aquaculture:Commercial penaeid farming in Gulf Coast greenhouse and pond systems generates concentrated demand for high-performance feeds calibrated to specific growth stages and salinity conditions. Texas and Louisiana operators specify formulations against FCR targets tied to operating license renewals.
- Farming:Smallholder and cooperative operations in Mexico's Sinaloa and Sonora Pacific zones purchase bagged products through distributor channels distinct from bulk commercial procurement.
- Research:University and government laboratory facilities in Corpus Christi and Baton Rouge require experimental diets with controlled nutrient matrices for nutrition science trials.
- Feed Manufacturing:Toll processing and private label production for regional brands represents a contract manufacturing segment with distinct margin structures.
Volume concentration aligns with Aquaculture. Emerging demand surfaces in Farming.
Packaging Type:
Logistics configuration separates bulk commodity flows from packaged products serving fragmented downstream access points.
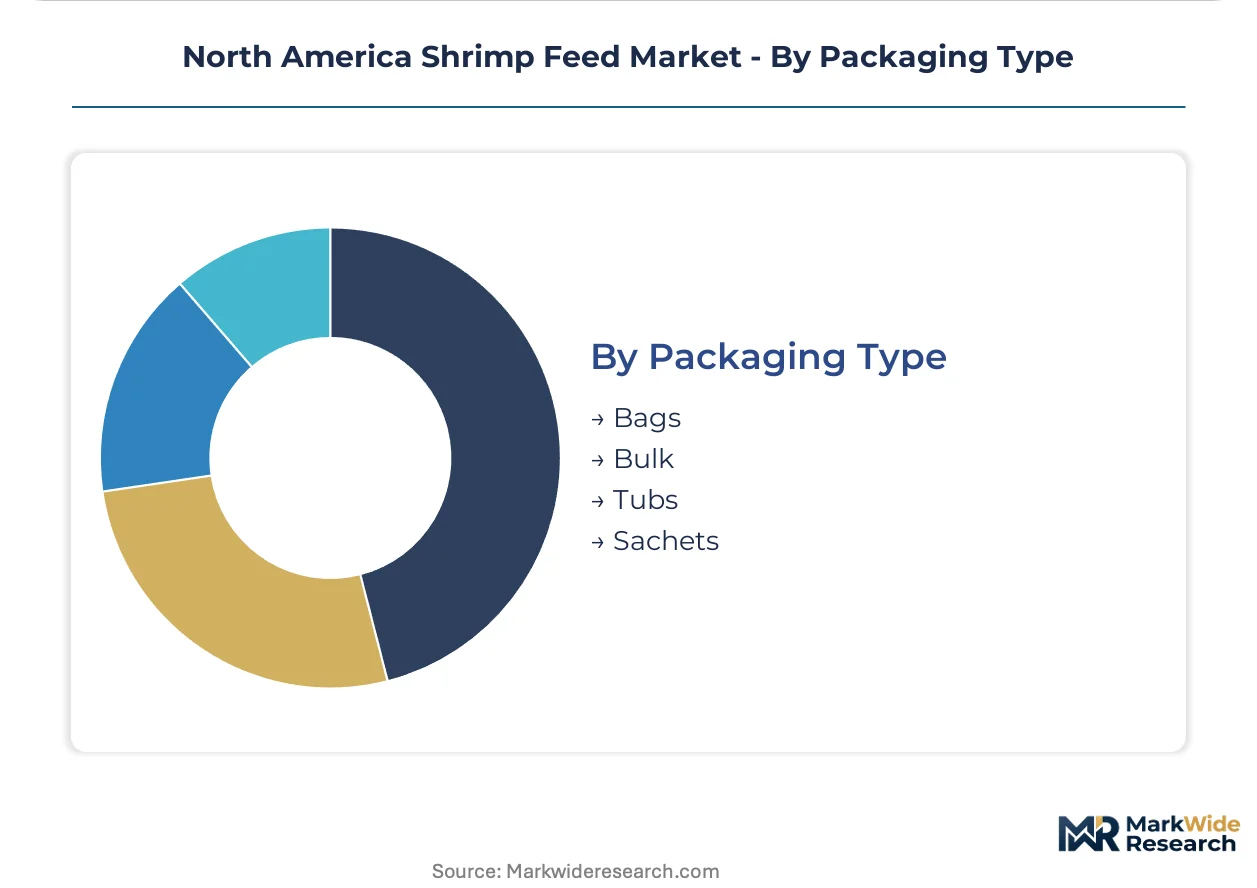
- Bulk:Pneumatic and auger delivery systems serve integrated farming operations with dedicated feed storage silos, minimizing per-unit packaging cost and supporting just-in-time inventory management across large pond complexes.
- Bags:25-50kg woven polypropylene sacks dominate distributor-mediated sales to smaller operations and cross-border shipments to Mexican farming zones lacking bulk handling infrastructure.
- Tubs:Moisture-resistant containers protect specialized larval diets and medication-supplemented formulations through extended storage periods.
- Sachets:Single-dose packaging supports research applications and precision supplementation protocols in hatchery environments.
Scale efficiency concentrates in Bulk. Accessibility requirements sustain Bags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corpus Christi Bay anchors North American shrimp feed demand through concentrated aquaculture operations and integrated supply chain infrastructure serving Gulf Coast farming clusters.
United States
Texas and Louisiana greenhouse systems drive intensive penaeid production requiring high-performance formulated feeds. The EPA's Clean Water Act discharge permits mandate lower nitrogen effluent limits, pushing operators toward extruded feed systems. Vermilion Parish and Cameron Parish farming cooperatives negotiate direct procurement agreements with regional mills for bulk deliveries.
Canada
Inland recirculating aquaculture installations in Alberta and British Columbia generate specialized demand for low-waste feed formulations distinct from open-pond products. Health Canada's CFIA feed division imposes parallel import and safety standards that cross-border suppliers must satisfy. Vancouver-area hatcheries source omega-3 enriched larval diets through dedicated supply channels.
Mexico
Sinaloa and Sonora Pacific coast zones present underdeveloped white-space demand for suppliers with cross-border logistics capabilities. Mexico's aquaculture health regulator enforces import and safety standards affecting feed formulation protocols. Mazatlán-based farming operations increasingly specify feed conversion ratio targets tied to export certification requirements.
North America Shrimp Feed Market Key Industry Players
The competitive structure tilts toward integrated agribusiness conglomerates with captive grain processing and oilseed crushing assets. Three to five multinational nutrition specialists compete alongside regional feed mills serving discrete geographic clusters. Dominant archetypes include backward-integrated commodity processors, aquaculture nutrition research specialists, and distributor-anchored regional formulators. Capacity expansion in extrusion technology and strategic partnerships for omega-3 sourcing represent the primary competitive moves reshaping supplier positioning.
Among North American integrated processors, Cargill, Incorporated and ADM Animal Nutrition exemplify the commodity-processor archetype through captive supply chain control from grain procurement to finished feed. Nutreco N.V. occupies a position within the nutrition-research tier, competing on feed conversion performance rather than commodity pricing alone. These three anchors illustrate how competitive advantage derives from either upstream raw material control or downstream formulation science specialization.
| Leading Market Players |
|---|
| ADM Animal Nutrition |
| Charoen Pokphand Foods Public Company Limited |
| Cargill, Incorporated |
| Rangen, Inc. |
| Wilbur-Ellis Nutrition, LLC |
| Nutreco N.V. |
| Alltech Inc. |
| Land O'Lakes |
| BioMar Group |
| Others |
Cost & Logistics Intelligence
Formulation chemist concentration along the Texas-Louisiana Gulf Coast creates labor-cost differentials that widen spreads between premium extruded feed tiers and economy pellet grades. EPA discharge permit compliance costs embed into pricing structures, pushing certified operators toward value-based contracts tied to feed conversion ratio guarantees rather than commodity spot terms.
Pricing Analysis
Value-based pricing anchored to feed conversion ratio outcomes dominates commercial aquaculture procurement, with Texas and Louisiana operators contracting for guaranteed performance metrics rather than per-ton commodity rates. Price differentiation separates USDA-certified organic formulations from conventional grow-out diets, while volume scale and automated delivery infrastructure compress unit costs for operations exceeding 500 acres. Pricing pressure stems from soybean meal volatility transmitted through ADM's crushing network, with cost-sensitive smaller farms in Vermilion Parish and Aransas County exhibiting highest price elasticity relative to integrated greenhouse operators.
Supply Chain Analysis
Certification gating through FDA FSMA facility registrations, USDA organic protocols, and Health Canada CFIA import standards fragments supplier eligibility across North American borders. Raw material sourcing concentrates in the United States for soybean meal and alternative proteins, Peru and Chile for fish meal and marine oils, and Canada for inland omega-3 enrichment facilities. Supply chain risk centers on single-source vulnerability for marine-derived omega-3 fatty acids facing reduced global forage fish quotas. Distribution runs through direct procurement relationships between large farm cooperatives and regional mills, displacing distributor intermediaries in bulk commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America shrimp feed market operates as a cost-of-compliance story where EPA Clean Water Act effluent guidelines erect barrier-to-entry moats favoring incumbent mills with captive extrusion capacity and established permit documentation.
For Market Incumbents: Anchor defensive positioning through backward integration into oilseed crushing assets and captive extrusion manufacturing to offset soybean price volatility. Consolidate channel control by acquiring regional distributor networks in Mexico's Sinaloa and Sonora Pacific zones before cross-border competitors establish logistics footholds. Priority investment in automated feeding system partnerships addresses the threat of EPA enforcement tightening uneaten feed recovery standards.
For New Entrants and Emerging Players: Advanced larval diet micro-encapsulation technology offers a technology-first wedge into the omega-3 enrichment segment where marine oil sourcing constraints limit incumbent capacity expansion. Target underpenetrated recirculating aquaculture system installations in inland Texas and Arizona with specialized low-waste formulations distinct from open-pond commodity products. Go-to-market execution through FSMA compliance advisory services builds trust relationships with smaller mills lacking in-house regulatory expertise.
For Investors and Strategic Acquirers: The window for entry favors aquaculture nutrition research specialists with demonstrated feed conversion ratio performance data and established university hatchery relationships. Long-term viability hinges on five-to-ten-year positioning around closed-loop system feed demand as freshwater scarcity pushes production inland. Acquisition target archetype: regional extrusion-capable mills with Health Canada import clearance and direct farm cooperative contracts. Signal to monitor: EPA effluent guideline revision announcements triggering permit renewal waves and equipment upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Extrusion Capacity Expansion | Captive high-pressure thermal processing secures water-stable pellet supply for automated feeding systems in Texas-Louisiana operations. |
| Omega-3 Sourcing Partnership | Long-term marine oil agreements with Peruvian and Chilean reduction facilities lock in larval diet raw material security. |
| FSMA Compliance Service Launch | Advisory and testing revenue streams capture margin from smaller mills navigating FDA facility registration requirements. |
| Mexico Pacific Coast Distribution Buildout | Cross-border logistics infrastructure captures white-space demand in Sinaloa and Sonora shrimp farming zones. |
| RAS-Optimized Formulation Development | Low-waste diets tailored to closed-loop inland systems address emerging demand from Texas and Arizona installations. |
Research Approach
Independent corroboration across feed mill operations managers, aquaculture farm procurement directors, and regulatory compliance officers underwrites the qualitative findings presented in this study. Primary fieldwork engaged formulation chemists, hatchery managers in Corpus Christi and Baton Rouge, and distribution channel partners serving Mexican Pacific coast zones. Secondary validation drew from EPA discharge permit filings, FDA FSMA facility registration databases, USDA National Organic Program certification records, and Health Canada CFIA import compliance documentation. Bottom-up volume estimates from individual farm operations triangulate against top-down market sizing derived from grain crushing capacity and oilseed processing throughput data.
Rate-of-change decomposition across the analysis window segments growth contributions by product type, ingredient source, application, and packaging configuration. The modeling framework incorporates feed conversion ratio performance trends, EPA effluent guideline enforcement intensity, and organic certification adoption patterns. CAGRs emerge from segmented base-year sizing projected through extrapolation of historical input cost trajectories and regulatory compliance cost absorption rates. Industry-specific forecast inputs include soybean meal price volatility indices and marine oil supply constraint indicators from global forage fish quota announcements.
Several conditions sit outside the modeled scope, including potential EPA effluent guideline revisions beyond current permit renewal timelines, trade policy disruptions affecting soybean or fish meal cross-border flows, and technological breakthroughs in plant-based omega-3 synthesis. Forecasts reflect assumptions regarding sustained warm-water shrimp farming concentration in Gulf Coast zones and continued displacement of fish meal by soy proteins in grow-out formulations. A model refresh is warranted upon material change in EPA enforcement posture or commercialization of viable larval diet alternatives to marine-derived omega-3 fatty acids.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Aquaponics Market
Aquaculture Innovations
Global Ornamental Fish Feed Market
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
APAC Aquafeed Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
Crab Market
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
Vietnam Aquafeed Market