
 Global Plant Based Fish Feed Market | 2026-2036
Global Plant Based Fish Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plant Based Fish Feed Market Outlook
Integrated salmon producers are redrawing procurement specifications away from traditional marine-based diets. BioMar Group leverages its Nordic R&D infrastructure to develop high-performance plant protein extrusions for cold-water species. Skretting anchors its competitive position through backward integration into specialty ingredient sourcing across European supply chains. ADM Animal Nutrition extends its oilseed processing dominance into aquafeed with dedicated extrusion capacity in North America.
Global plant based fish feed comprises formulated diets where fishmeal and fish oil are partially or fully replaced with terrestrial plant proteins, vegetable oils, and micronutrient premixes to meet species-specific amino acid and fatty acid profiles. Manufacturing employs twin-screw extrusion at moisture levels of 22-28% followed by vacuum coating of lipids to achieve target energy densities of 20-24 MJ/kg digestible energy. Pellet formulations dominate commercial aquaculture due to their mechanical durability in automated feeding systems and controlled sinking rates for species-specific feeding zones. Granule segments are gaining fastest in recirculating aquaculture systems where smaller particle sizes reduce waste loading and improve feed conversion ratios. Plant proteins as an ingredient category concentrate the largest margin pools, with pea and soy protein concentrates commanding premium positions over wheat gluten and sunflower meal.
The European Commission's F-Gas Regulation and EU Green Deal farm-to-fork targets are tightening permissible carbon intensity thresholds for imported feed ingredients, directly conditioning market access for non-European suppliers. Norway's national seafood regulator and the FDA in the United States enforce divergent maximum residue limits for pesticides in plant protein imports, fragmenting compliance architectures across Atlantic supply chains. REACH compliance for novel protein processing aids adds a secondary gatekeeping layer for European market entry. Stakeholders must monitor accelerating divergence between EU and North American regulatory timelines for novel feed ingredient approvals.
Market Dynamics
EU Green Deal feed sustainability mandates are forcing salmonid producers across Norway and Chile to redesign procurement specifications away from marine-based diets toward terrestrial protein formulations.
Growth Catalysts
- EU F-Gas Regulation:Carbon intensity thresholds for imported feed ingredients are conditioning market access and accelerating substitution toward plant-based alternatives in European aquaculture operations.
- Southeast Asian shrimp aquaculture:Cost volatility in fishmeal imports is redirecting formulation strategies toward soy and pea protein concentrates as primary protein sources.
- Twin-screw extrusion technology:Moisture-controlled processing at 22-28% levels enables high-performance plant protein extrusions that meet species-specific amino acid profiles for cold-water species.
Market Restraints
- Input cost volatility:Pea protein concentrate pricing fluctuates with North American pulse crop yields, compressing margin predictability for formulation specialists.
- Supply concentration risk:Specialty lipid coating systems for vacuum infusion concentrate among three European equipment manufacturers, creating single-source vulnerability.
- Technical limitation:Current plant protein formulations struggle to replicate the full fatty acid profile of fish oil for larval-stage nutrition in marine finfish hatcheries.
Strategic Opportunities
- Recirculating aquaculture systems:Granule formulations for reduced waste loading in indoor facilities represent underpenetrated demand across German and Dutch salmon smolt operations.
- EU Green Deal farm-to-fork targets:Mandatory sustainability thresholds create regulatory tailwind for domestic European protein processing infrastructure expansion.
- Precision fermentation convergence:Integration with algal omega-3 production technologies enables complete marine ingredient replacement in premium salmonid diets.
Industry Challenges
- Novel ingredient approval timelines:REACH compliance for protein processing aids creates 18-24 month European market entry delays for Asian suppliers.
- Formulation talent scarcity:Aquafeed-specific amino acid balancing expertise concentrates among retiring specialists at Nordic research institutions.
- Legacy system integration:Automated feeding systems at Chilean sea-pen operations require pellet durability recalibration for plant-based extrusion densities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plant Based Fish Feed Market |
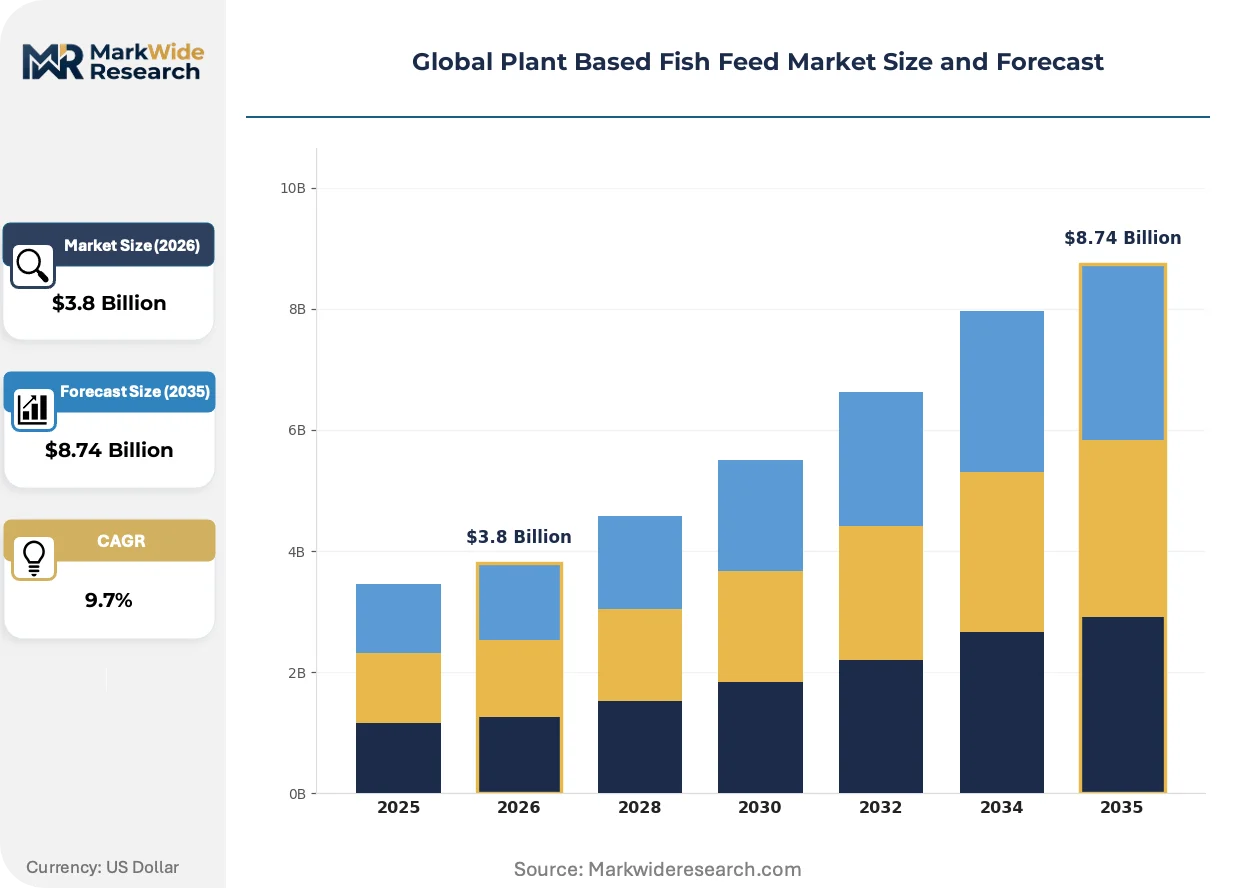
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Granules, Flakes, Powder End User: Aquaculture, Fish Farms, Hobbyists, Commercial Use Ingredient Type: Plant Proteins, Oils, Vitamins, Additives Distribution Channel: Online Retail, Distributors, Wholesale, Direct Sales |
| Companies Covered | Cargill Incorporated, Nutreco N.V., BioMar Group, Skretting, ADM Animal Nutrition, Kemin Industries, Aller Aqua, Prairie AquaTech, Roquette, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plant Based Fish Feed Market Strategic Shifts
Formulation science is advancing beyond simple fishmeal substitution toward precision-designed nutrient matrices that optimize feed conversion ratios across diverse aquaculture environments.
Single-cell protein derived from methanotrophic bacteria is fragmenting traditional ingredient sourcing models for high-value marine species. Norwegian salmon producers are trialing these formulations at commercial scale. The technology is fragmenting established procurement relationships between aquafeed manufacturers and commodity oilseed processors.
REACH authorization requirements for novel protein concentrates are tightening residue limit documentation across European supply chains. Industrial consequence falls heaviest on Southeast Asian soy protein exporters seeking market access. Shrimp feed formulators in Vietnam and Thailand are accelerating third-party certification investments to maintain EU import eligibility.
Buyer consolidation among integrated salmon producers is compressing supplier negotiation cycles from annual to quarterly frameworks. Distributors serving independent Vietnamese shrimp farms face disintermediation as direct procurement platforms expand. This pattern concentrates most visibly in Mekong Delta aquaculture clusters where feed represents sixty percent of operational expenditure.
Global Plant Based Fish Feed Market Segmentation
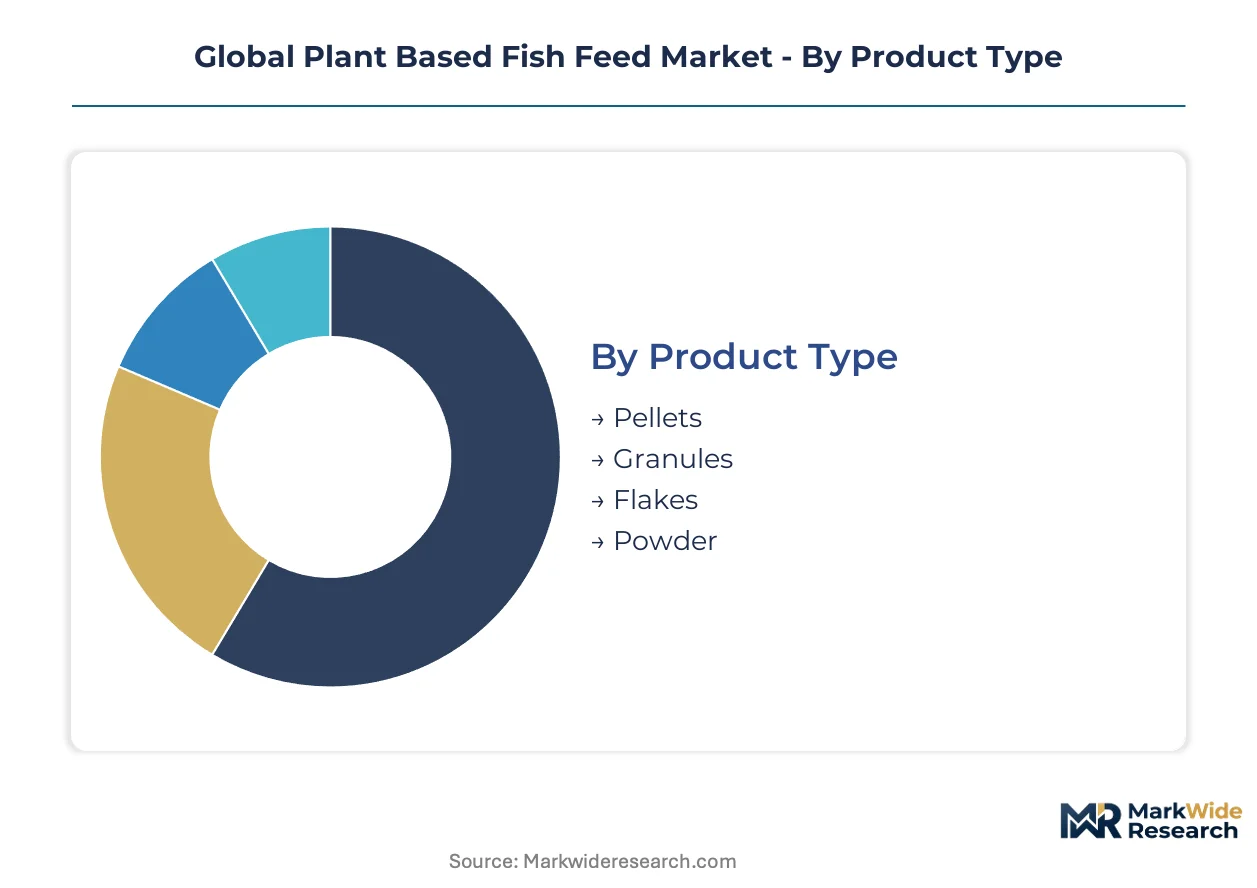
Form factor, end-use application, ingredient composition, and channel structure each condition pricing power and margin capture differently across plant-based aquafeed supply chains. Regulatory divergence on residue limits and sustainability certification requirements fragments segment performance across major consuming geographies.
Product Type:
REACH authorization timelines and FDA residue protocols differentiate mechanical durability requirements for automated feeding system compatibility across Atlantic supply chains.
- Pellets:Extruded formulations at 22-28% moisture achieve mechanical durability indices above 95% for pneumatic distribution in Norwegian and Chilean sea-pen operations. Salmonid producers across Bergen and Puerto Montt specify pellet geometries that withstand saltwater immersion stress without nutrient leaching.
- Granules:Smaller particle sizes reduce waste loading in recirculating aquaculture systems across German and Dutch smolt facilities. The EU F-Gas Regulation's carbon intensity thresholds accelerate specification shifts toward granule formats that optimize feed conversion ratios in indoor tank environments.
- Flakes:Surface-area-maximized formats serve ornamental and larval-stage nutrition in Southeast Asian hatcheries.
- Powder:Fine-ground formulations enable custom blending for specialty research applications and artisanal farm operations.
Pellets handle the majority of throughput; granules are expanding most quickly on share.
End User:
Scale concentration and procurement sophistication create three distinct margin tiers across the demand base.
- Aquaculture:Integrated salmon producers in Norway and shrimp operators across Vietnam's Mekong Delta drive formulation standardization at commercial scale. Quarterly procurement frameworks compress supplier negotiation cycles and reward backward-integrated feed manufacturers with captive oilseed processing capacity.
- Fish Farms:Mid-scale freshwater operations across Poland and Hungary prioritize cost stability over performance optimization, accepting higher feed conversion ratios in exchange for predictable ingredient sourcing.
- Hobbyists:Premium flake and granule demand concentrates in North American and European retail channels with certification-driven purchasing.
- Commercial Use:Institutional buyers including research facilities and public aquariums specify custom amino acid profiles for species conservation programs.
Aquaculture commands the dominant procurement volume; fish farms are climbing the fastest on participation.
Ingredient Type:
Supply concentration in North American pulse crops and European oilseed processing creates divergent cost volatility exposures across protein and lipid categories.
- Plant Proteins:Pea protein concentrates from Canadian prairie processing facilities and soy protein isolates from Midwest crushing plants anchor amino acid profiles for cold-water species. EFSA maximum residue limits for pesticides condition import eligibility for Southeast Asian soy exporters seeking EU market access.
- Oils:Vegetable lipid fractions achieve target energy densities of 20-24 MJ/kg through vacuum coating systems concentrated among three European equipment manufacturers.
- Vitamins:Micronutrient premixes address species-specific deficiencies in plant-based formulations lacking marine-derived micronutrients.
- Additives:Enzyme preparations and palatability enhancers compensate for reduced attractant properties of terrestrial protein sources.
Plant proteins handle the majority of formulation weight; oils are gaining share fastest on value contribution.
Distribution Channel:
Buyer consolidation and platform disintermediation are restructuring channel economics across independent and integrated customer segments.
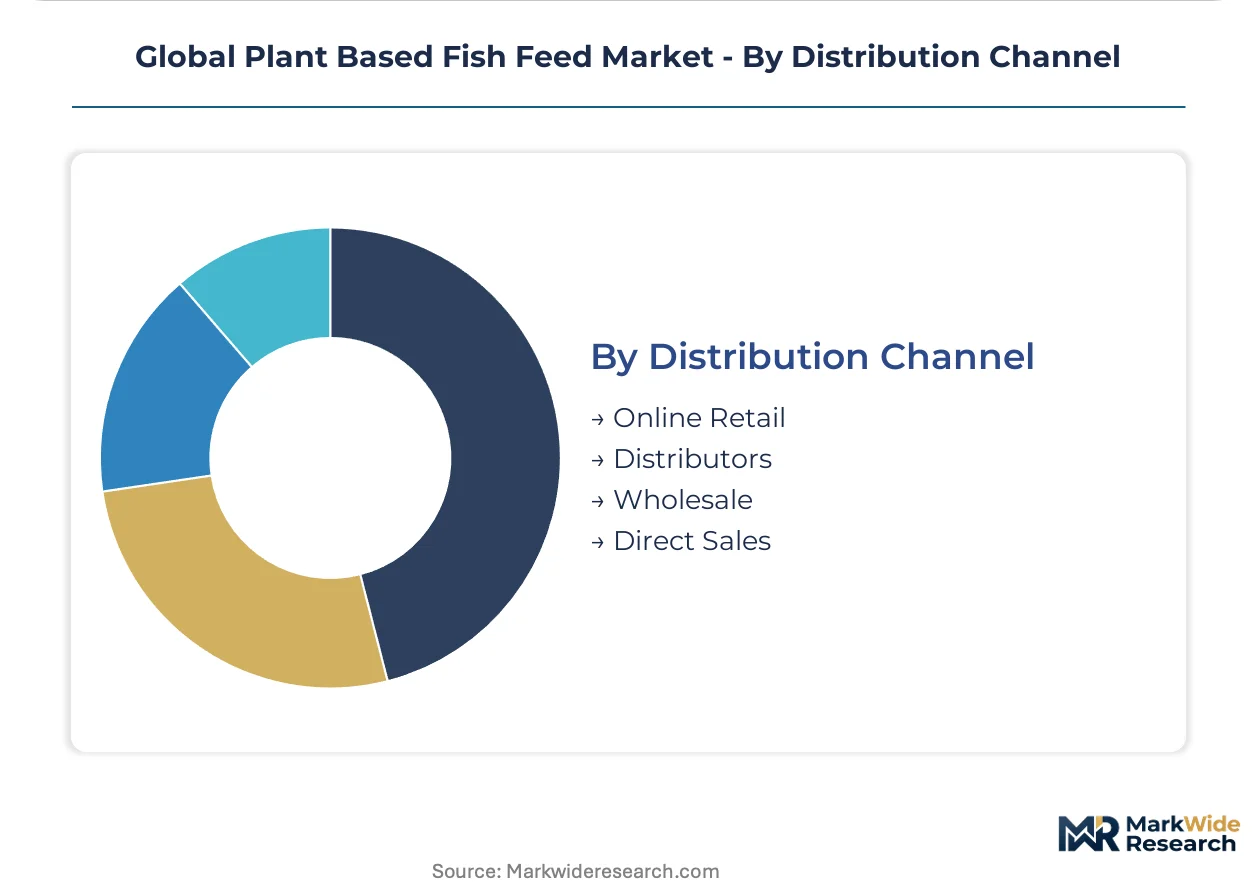
- Online Retail:Direct procurement platforms expand across Vietnamese shrimp farming clusters where feed represents sixty percent of operational expenditure, bypassing traditional distributor networks.
- Distributors:Regional stocking points serve fragmented independent farms across Indonesia and Bangladesh with credit terms and technical advisory services.
- Wholesale:Volume aggregation for cooperative purchasing among smallholder associations in India and Thailand.
- Direct Sales:Dedicated account management for integrated salmon producers with quarterly framework agreements and collaborative formulation development.
Direct sales handle the majority of revenue concentration; online retail is expanding most steeply on penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian salmon exporters supply European and Asian buyers with plant-protein-fed fish, while Vietnamese shrimp processors redirect formulation sourcing toward domestic soy crushing to reduce fishmeal import dependency.
Norway
Bergen-based salmon producers drive demand for high-performance pea protein extrusions in cold-water aquaculture. The country's national seafood regulator enforces strict maximum residue limits for pesticide contaminants in imported plant proteins. Integrated operations around Trøndelag cluster backward integration into specialty ingredient sourcing to secure supply chain control.
Vietnam
Mekong Delta shrimp farms absorb sixty percent of operational expenditure on feed, creating intense cost pressure for plant-based alternatives. The country's agricultural ministry implements traceability mandates for imported soy protein to ensure food safety compliance. Can Tho and An Giang provinces concentrate formulation trials for domestic soy crushing to displace volatile fishmeal imports.
United States
Midwest soy protein isolates from Illinois and Iowa crushing plants anchor amino acid profiles for domestic catfish and emerging salmonid recirculating systems. The FDA enforces divergent pesticide residue protocols compared to European counterparts, fragmenting export compliance architectures. Pacific Northwest smolt operations in Washington State trial granule formulations for indoor tank environments.
Germany
Baden-Württemberg and Lower Saxony host recirculating aquaculture facilities demanding reduced-waste granule formats. The EU F-Gas Regulation and REACH compliance requirements gatekeep market access for novel protein processing aids. Stuttgart-area equipment manufacturers concentrate vacuum coating system supply for lipid infusion at 20-24 MJ/kg energy densities.
Chile
Puerto Montt sea-pen operations expand procurement of soy and pea protein formulations for salmonid production. The national fisheries service aligns with EU Green Deal sustainability thresholds to maintain European export market access. Los Lagos region producers recalibrate automated feeding systems for plant-based extrusion densities.
Global Plant Based Fish Feed Market Competitive Environment
Listed leaders compete with private specialists across ingredient sourcing and formulation development. The vendor base concentrates among Nordic and North American oilseed processors with captive crushing capacity, mid-scale European extrusion specialists, and Asian distributors serving fragmented shrimp farming clusters. Three archetypes dominate: backward-integrated agribusiness conglomerates, dedicated aquafeed formulators with R&D infrastructure, and regional distributors with technical advisory capabilities. Competitive intensity manifests through quarterly procurement framework compression and collaborative formulation partnerships with integrated producers.
Within the backward-integrated tier, Cargill Incorporated and ADM Animal Nutrition represent agribusiness conglomerates leveraging oilseed processing dominance into aquafeed extrusion capacity. BioMar Group and Skretting exemplify dedicated aquafeed formulators with Nordic R&D infrastructure for cold-water species. Nutreco N.V. occupies a position bridging both archetypes through portfolio diversification across livestock and aquaculture nutrition.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Nutreco N.V. |
| BioMar Group |
| Skretting |
| ADM Animal Nutrition |
| Kemin Industries |
| Aller Aqua |
| Prairie AquaTech |
| Roquette |
| Others |
Value Chain & Pricing Dynamics
Quarterly procurement frameworks between integrated salmon producers and formulators lock in supply access for plant protein concentrates while compressing price visibility windows from annual to three-month cycles. This contract structure concentrates negotiation leverage among Nordic and Chilean buyers with backward-integrated crushing capacity, leaving independent Vietnamese shrimp farms exposed to spot market volatility in pea protein pricing.
Pricing Analysis
Next-generation twin-screw extrusion technology commands a 15-20% premium over legacy single-screw systems due to superior amino acid retention in cold-water species formulations. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with EU organic-certified concentrates capturing the highest tier. Cost compression in standard-grade soy protein isolates is intensifying because Midwest crushing capacity expansion outpaces near-term demand growth. Mid-scale Polish and Hungarian fish farms exhibit the highest price sensitivity, while Norwegian integrated producers prioritize performance optimization over unit cost.
Supply Chain Analysis
Inventory cycles for specialty lipid coating systems stretch 12-16 weeks due to European equipment manufacturer concentration, creating lead-time vulnerability for North American extrusion facilities. Supply concentrates in Canada for pea protein, the United States for soy isolates, and Germany for vacuum coating technology, with each node drawing from distinct agricultural and industrial bases. Single-source vulnerability pervades the three European manufacturers controlling vacuum infusion systems for 20-24 MJ/kg energy density targets. Distribution runs through direct sales channels for integrated salmon producers and distributor networks for fragmented Southeast Asian shrimp operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated aquaculture conglomerates across Norway and Chile, fragmenting supplier negotiation leverage and compressing margin capture for independent formulators without captive oilseed processing.
For Market Incumbents: Shield formulation expertise through accelerated R&D hiring at Nordic research institutions before specialist retirement waves peak. Deepen backward integration into Canadian pea protein crushing to offset Midwest soy price volatility and secure EU Green Deal-compliant supply chains. Priority investment in REACH-authorized processing aids prevents 18-24 month market entry delays for Asian-sourced alternatives. For New Entrants and Emerging Players: Anchor in German and Dutch recirculating aquaculture system clusters where granule demand for reduced waste loading remains underpenetrated by incumbent pellet specialists. Target mid-scale freshwater operations across Poland and Hungary with cost-stability value propositions rather than performance optimization narratives. Go-to-market leverage rests on technical advisory partnerships with regional distributor networks offering credit terms unavailable to direct procurement platforms. For Investors and Strategic Acquirers: Capital is best deployed toward aquafeed formulators with Nordic R&D infrastructure and established collaborative partnerships with integrated salmon producers. Long-term viability across the projection horizon hinges on precision fermentation convergence capabilities for complete marine ingredient replacement. The signal to watch is FDA-EU regulatory divergence on novel protein approval timelines, which would advantage domestic European processing infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Captive pea and soy protein supply secures margin control against North American pulse crop volatility. |
| REACH Authorization Investment | Novel protein processing aid compliance eliminates 18-24 month European market entry barriers for Asian competitors. |
| Granule Format Development | Reduced waste loading specifications penetrate German and Dutch recirculating aquaculture system demand. |
| Precision Fermentation Partnership | Algal omega-3 integration enables complete fish oil replacement in premium salmonid diet formulations. |
| Direct Procurement Platform Expansion | Bypassing distributor networks captures Vietnamese shrimp farm clusters where feed dominates operational expenditure. |
Study Parameters
A spread of perspectives from aquafeed formulation scientists, procurement directors at integrated salmon producers, specialty ingredient sourcing managers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary field engagement with Nordic R&D institutions and Southeast Asian shrimp farming cooperatives combined with secondary validation through EU F-Gas Regulation filings, FDA residue limit protocols, EFSA maximum residue documentation, and customs trade data for North American pulse crop flows. Bottom-up volume modeling across product type, end user, ingredient composition, and distribution channel segments triangulated against top-down macroeconomic indicators for the aquaculture sector.
Segmentation dimensions modeled include form factor specifications, species-specific nutritional requirements, sustainability certification tiers, and regional regulatory divergence patterns across the projection horizon. CAGRs were derived through growth driver elasticity analysis applied to baseline procurement volume data, with specific inputs from twin-screw extrusion technology adoption curves and EU Green Deal compliance timeline assumptions. The analytical framework incorporates backward integration intensity indices and direct procurement platform penetration rates as industry-specific forecast modifiers.
Decision-makers should treat outputs as directional under sustained EU sustainability mandate enforcement and stable North American pulse crop yield assumptions; material deviation in either would warrant model refresh. Specific risk factors include regulatory timeline acceleration for novel ingredient approvals and supply concentration disruption among European vacuum coating equipment manufacturers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
Qatar Fisheries and Aquaculture Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
Brazil Fisheries and Aquaculture Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
Aquaponics Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Saudi Arabia Aquaculture Market
Aquaculture Innovations
Norway Aquaculture Market
Aquaculture Innovations
Kuwait Fisheries and Aquaculture Market
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
Fish Farming Equipment Market
Aquaculture Innovations
Clams, Cockles, Ark Shells Market