
 Crab Market | 2026-2036
Crab Market Size, Share, and Industry Trends Forecast 2026-2036
Crab Market Analysis
Alaskan crab harvest quotas is hardening supply availability across North American distribution channels. Nippon Suisan Kaisha leverages vertical integration from vessel to retail shelf across Japanese and Southeast Asian markets. Clearwater Seafoods anchors premium positioning through MSC-certified snow crab and offshore harvesting operations in the North Atlantic. Thai Union Group PCL competes on scaled pasteurization capacity serving European and North American private-label contracts.
Crabs are decapod crustaceans with ten walking legs, harvested wild or aquacultured for human consumption across fresh, frozen, and value-added formats. Their meat delivers protein content exceeding most finfish species, with blue crab and snow crab commanding distinct texture and sweetness profiles for food manufacturing and premium dining. Frozen crab dominates volume throughput due to extended shelf stability and lower logistics spoilage rates versus live shipment. Processed crab, including pasteurized leg meat and claw segments, captures disproportionate margin pools as food service buyers prioritize labor-saving formats. Vacuum-sealed packaging is displacing traditional carton methods in retail channels, extending refrigerated shelf life while reducing freezer burn incidence.
NOAA Fisheries administers catch share programs and seasonal closures governing Bering Sea king crab access. China's SAMR enforces GB standards for heavy metal limits and labeling of imported crustacean products. The EU's IUU Regulation requires catch documentation for all crab entering European customs territory. Stakeholders must monitor quota allocation shifts between Russian Far East and Alaskan fisheries, as these determine raw material cost trajectories and processing plant utilization rates regardless of consumer demand signals.
Market Dynamics
Alaskan harvest quota reductions are compressing raw material availability across North American distribution channels, forcing processors to reconfigure supply relationships around Russian Far East and Canadian Atlantic fisheries.
Growth Catalysts
- Pasteurization technology advancement:High-pressure processing systems now extend refrigerated crab meat shelf life to 18 months, unlocking food service contract scale previously limited by spoilage risk.
- China's GB 31605-2020 standards:Tightened cold chain logistics requirements for aquatic products are filtering out non-compliant exporters, consolidating market access for certified Vietnamese and Thai processors.
- Ho Chi Minh City processing corridor:Concentrated shelling and leg-meat extraction capacity within 80 kilometers of Tan Son Nhat Airport reduces air freight transit time to European and Japanese buyers.
Market Restraints
- Input cost volatility:Diesel prices for crab vessel operations fluctuate with Brent crude movements, compressing margins for independent Alaskan and Russian Far East harvesters.
- Supply concentration risk:Russian Federation controls approximately 70% of global king crab biomass, creating single-source dependency for premium leg-meat segments.
- Substitution threat:Surimi-based imitation crab products capture price-sensitive retail and institutional food service volumes in Southeast Asian and Latin American markets.
Strategic Opportunities
- Underpenetrated Indian market:Coastal Maharashtra and Gujarat processing infrastructure remains underdeveloped for pasteurized crab exports, presenting first-mover positioning for cold chain investors.
- Regulatory tailwind from EU IUU Regulation:Catch documentation requirements favor MSC-certified suppliers with established chain-of-custody systems, rewarding compliant North Atlantic operators.
- Direct-to-restaurant distribution:Bypassing traditional seafood distributors, Vietnamese processors now ship vacuum-packed leg segments directly to Tokyo and Osaka izakaya chains via consolidated air cargo.
Industry Challenges
- Skill gap in thermal processing:Pasteurization line operators require HACCP certification combined with sensory grading expertise, a combination scarce in emerging processing hubs.
- Capex intensity for freezing infrastructure:Blast freezing to minus 40 degrees Celsius within four hours of harvest demands nitrogen-based tunnel systems exceeding $2 million per installation.
- Certification timeline compression:MSC reassessment cycles now occur every five years rather than seven, accelerating audit preparation costs for fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crab Market |
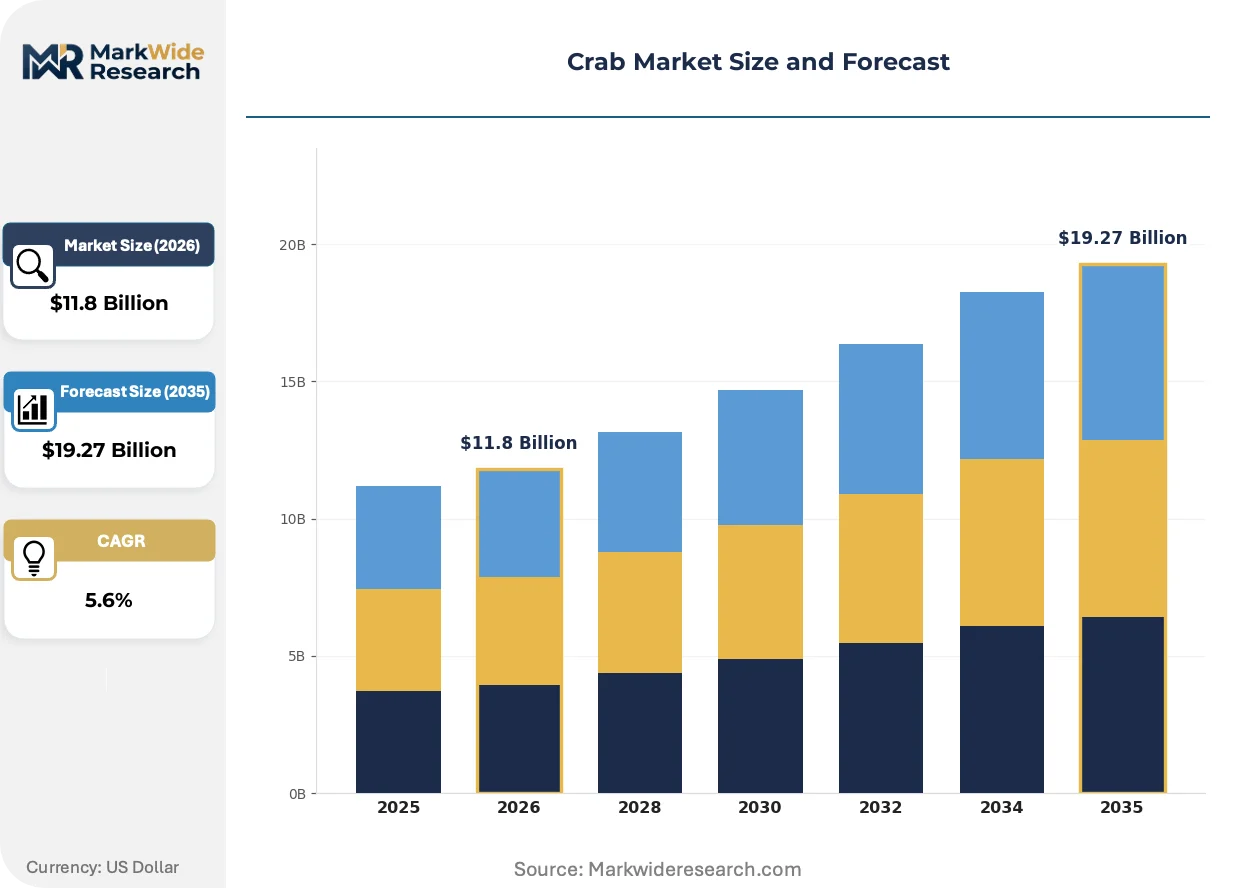
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Crab, Frozen Crab, Processed Crab, Crab Meat Distribution Channel: Supermarkets, Restaurants, Online Retail, Fishermen's Markets End User: Households, Food Service, Exporters, Processors Packaging Type: Carton, Vacuum-Sealed, Bulk, Retail Packs |
| Companies Covered | Nippon Suisan Kaisha (Nissui), Bumble Bee Foods LLC, Thai Union Group PCL, Clearwater Seafoods, Maruha Nichiro Corporation, Phillips Foods, Inc., Trident Seafoods, High Liner Foods Inc., Pacific Seafood Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crab Market Emerging Trajectories
Vacuum-sealed modified atmosphere packaging is displacing traditional carton methods across retail channels, while regulatory documentation requirements and procurement model evolution reshape competitive positioning.
High-pressure processing technology for crab meat pasteurization is expanding into premium food service segments. Institutional buyers in North American casino and resort dining operations now specify HPP-treated product for extended holding periods. This technology is expanding into markets previously served only by frozen blocks, compressing cold storage requirements and enabling just-inventory models.
China's SAMR enforcement of GB 31605-2020 cold chain standards is disqualifying non-compliant exporters from customs clearance. Vietnamese and Thai processors must now deploy temperature loggers from harvest vessel through final container loading. Small-scale Indonesian suppliers lacking integrated cold chain documentation are retreating from export markets, consolidating volume with certified operators.
Food service procurement is consolidating around direct processor relationships, bypassing traditional seafood distributors. Japanese izakaya chains and North American casino resort operators now negotiate annual volume contracts directly with Ho Chi Minh City processors. This disintermediation is most visible in Tokyo and Osaka, where consolidated air cargo shipments from Tan Son Nhat Airport arrive three times weekly with processor-branded packaging.
Crab Market Segmentation
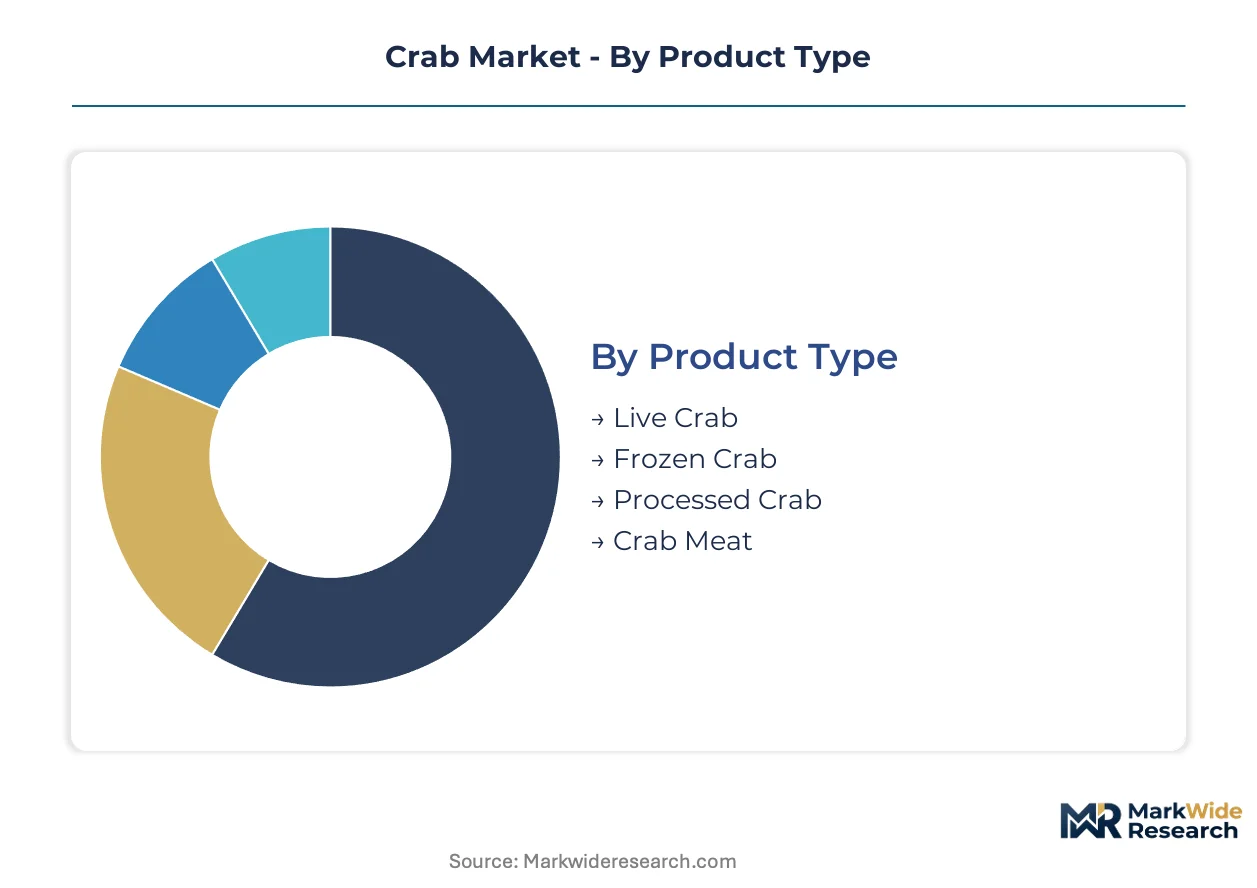
Crab market segmentation reveals how regulatory requirements, shelf-life demands, and procurement patterns fragment across product formats and channel structures. Each segment carries distinct certification burdens that determine market access and margin capture.
Product Type:
Certification requirements vary sharply across product types, with live and processed formats facing the most stringent health and traceability protocols.
- Frozen Crab:Blast-frozen at minus 40 degrees Celsius within four hours of harvest to preserve cellular structure. Demand concentrates in North American retail and European food service, where extended shelf stability reduces spoilage risk and enables centralized procurement from Russian Far East and Alaskan fisheries.
- Processed Crab:Pasteurized leg meat and claw segments undergo HACCP-certified thermal processing to achieve 18-month refrigerated shelf life. Japanese izakaya chains and North American casino resorts specify this format for labor savings and consistent portion control, though pasteurization line operators with combined HACCP and sensory grading expertise remain scarce.
- Live Crab:Requires continuous oxygenation and temperature control during transit, with mortality rates dictating pricing volatility in Asian wholesale markets.
- Crab Meat:Hand-picked or mechanically separated flesh sold in refrigerated or frozen blocks for food manufacturing applications.
Frozen crab sits at the top of the volume ranking, with processed crab climbing the fastest.
Distribution Channel:
Channel selection determines cold chain investment intensity and documentation requirements from harvest through final delivery.
- Restaurants:Direct procurement from Vietnamese processors via consolidated air cargo is displacing traditional seafood distributors in Tokyo and Osaka. Izakaya chains negotiate annual volume contracts for vacuum-packed leg segments, bypassing intermediaries to secure price stability and traceability documentation required by Japan's Ministry of Health, Labour and Welfare.
- Supermarkets:Retail chains specify MSC certification and vacuum-sealed modified atmosphere packaging to extend shelf life and reduce freezer burn incidence.
- Online Retail:E-commerce platforms require frozen or pasteurized formats with insulated packaging and temperature loggers to satisfy consumer expectations and regulatory compliance.
- Fishermen's Markets:Direct dockside sales of live and fresh-cooked crab dominate in coastal communities with limited cold chain infrastructure.
Restaurants command the highest margin capture, with online retail expanding most quickly.
End User:
End-user categories reflect divergent priorities around labor cost, certification documentation, and supply security.
- Food Service:Casino resorts, hotel chains, and institutional dining operations prioritize pasteurized crab meat for extended holding periods and reduced kitchen labor. Procurement teams specify high-pressure processed product and demand chain-of-custody documentation aligned with EU IUU Regulation requirements for European-sourced volume.
- Households:Retail consumers in North America and Europe drive demand for frozen whole crab and vacuum-sealed leg clusters, with purchasing decisions influenced by MSC certification and country-of-origin labeling.
- Exporters:Vietnamese and Thai processors serving European and Japanese markets must deploy temperature loggers from harvest vessel through container loading to satisfy China's SAMR enforcement of GB 31605-2020 cold chain standards.
- Processors:Secondary processors convert frozen raw material into value-added formats, requiring consistent supply from certified fisheries to maintain HACCP and BRC certification.
Food Service generates the steepest margin expansion, with Exporters gaining share fastest.
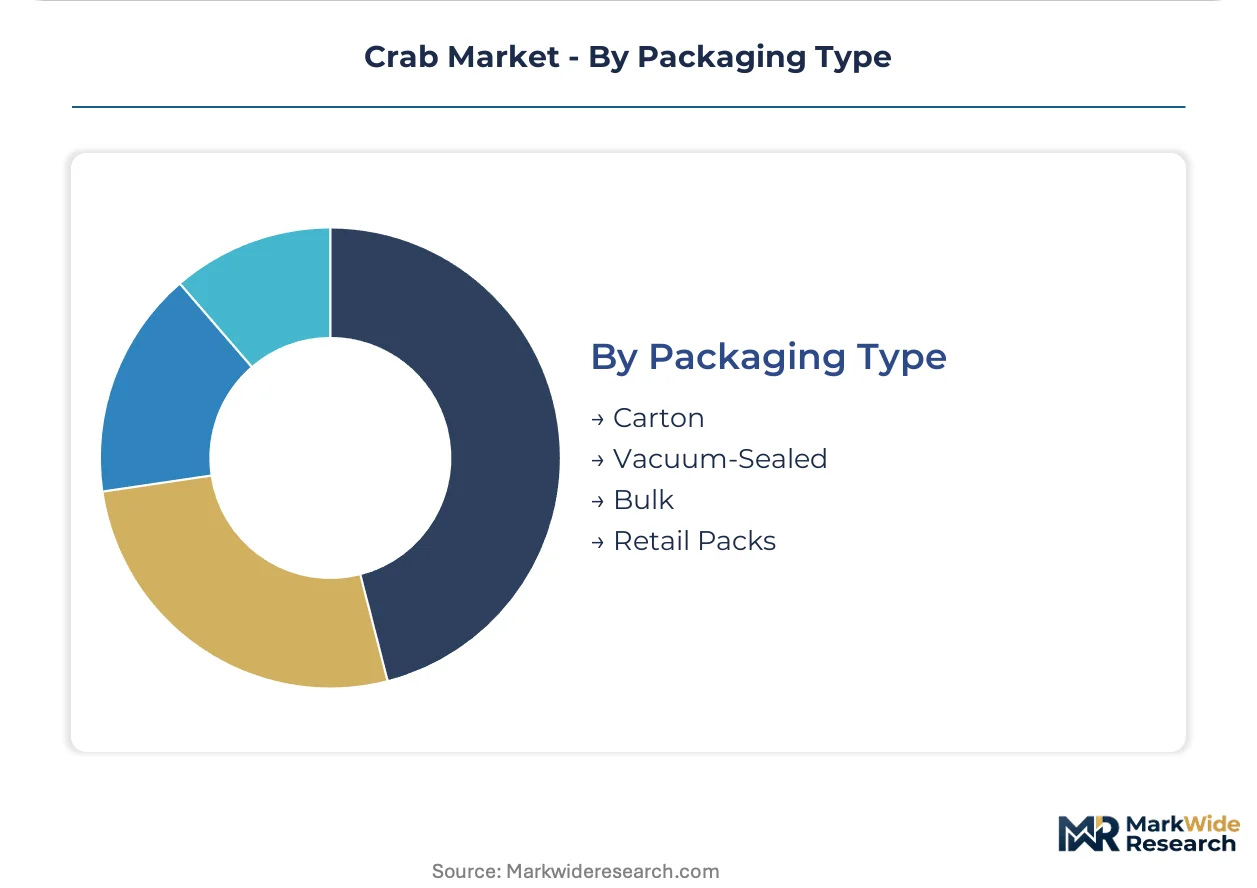
Packaging Type:
Packaging innovation is reshaping shelf-life economics and retail presentation standards across all product categories.
- Vacuum-Sealed:Modified atmosphere packaging displaces traditional carton methods, extending refrigerated shelf life while reducing freezer burn incidence. Retail chains in North America and Europe now mandate this format for premium positioning and waste reduction.
- Retail Packs:Pre-portioned clusters and leg segments in consumer-facing packaging command price premiums in supermarket chilled sections.
- Carton:Legacy packaging format for frozen blocks, gradually phased out in favor of vacuum-sealed alternatives.
- Bulk:Industrial totes and master cases for food service and processor customers, minimizing per-unit packaging cost.
Vacuum-sealed holds the top volume position, with Retail Packs climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia controls the dominant share of king crab biomass while Vietnam processes the majority of value-added exports, revealing a split between raw material concentration and manufacturing gravity.
Russia
Far Eastern fisheries supply approximately 70% of global king crab harvests, with Petropavlovsk-Kamchatsky serving as the primary landing and freezing hub. The Federal Agency for Fisheries administers catch quotas that directly determine raw material availability for international processors. Vladivostok-based cold storage facilities handle bulk exports to Asian and European markets.
United States
Alaskan Bering Sea operations face compressed harvest quotas that have tightened domestic supply availability. NOAA Fisheries manages catch share programs and seasonal closures governing king and snow crab access. Dutch Harbor and Kodiak maintain processing infrastructure for blast-freezing operations serving North American distribution channels.
Vietnam
Ho Chi Minh City anchors the dominant processing corridor for pasteurized crab meat exports to Japan and Europe. Vietnam's compliance with China's GB 31605-2020 cold chain standards has consolidated market access against non-certified regional competitors. Tan Son Nhat Airport proximity enables direct air freight consolidation for Tokyo and Osaka food service contracts.
Japan
Tokyo and Osaka izakaya chains drive premium demand for vacuum-packed leg segments with documented chain-of-custody. Japan's Ministry of Health, Labour and Welfare enforces strict import documentation aligned with EU IUU Regulation equivalents. Kansai and Kanto regions concentrate food service procurement teams negotiating direct annual volume contracts with Vietnamese processors.
Canada
Atlantic offshore harvesting operations supply MSC-certified snow crab to European and North American premium segments. Fisheries and Oceans Canada regulates Atlantic crab quotas with increasing alignment to EU documentation requirements. Newfoundland and Labrador processing plants serve as alternative supply sources when Alaskan quotas tighten.
Crab Market Vendor Landscape
North American harvesters anchor the raw material tier; Southeast Asian processors hold the value-added manufacturing position. Market structure splits between quota-controlled wild capture operations and scale-driven pasteurization specialists. Three archetypes dominate: vertically integrated Japanese conglomerates, North American quota holders with offshore Atlantic diversification, and Vietnamese-Thai processors competing on HACCP-certified capacity. Competitive moves concentrate on direct-to-restaurant distribution bypass and cold chain certification investments.
Among Japanese integrated conglomerates, Nippon Suisan Kaisha and Maruha Nichiro Corporation exemplify vessel-to-retail vertical control across domestic and Southeast Asian markets. Clearwater Seafoods occupies a position within the North Atlantic premium tier, while Thai Union Group PCL anchors scaled pasteurization capacity serving European and North American private-label demand. Phillips Foods and Trident Seafoods represent mid-scale North American processors navigating quota compression through supply relationship reconfiguration.
| Leading Market Players |
|---|
| Nippon Suisan Kaisha (Nissui) |
| Bumble Bee Foods LLC |
| Thai Union Group PCL |
| Clearwater Seafoods |
| Maruha Nichiro Corporation |
| Phillips Foods, Inc. |
| Trident Seafoods |
| High Liner Foods Inc. |
| Pacific Seafood Group |
| Others |
Supply Flow & Price Mechanics
Pasteurization line operators with combined HACCP certification and sensory grading expertise in the Ho Chi Minh City processing corridor command wage premiums that compress margins for mid-tier processors while widening spreads between MSC-certified premium leg-meat segments and standard frozen blocks.
Pricing Analysis
Capacity additions in Vietnam's pasteurization corridor are reshaping price floors for refrigerated crab meat exports to Japanese izakaya chains. Three-tier pricing structure across MSC-certified premium, HACCP-standard, and economy frozen blocks reflects certification grade and cold chain documentation completeness. Cost compression in the economy tier is intensifying because Indonesian suppliers lacking GB 31605-2020 compliance are retreating from export markets. Food service buyers in North American casino resorts exhibit lowest price sensitivity, while Southeast Asian retail channels show highest elasticity to surimi-based substitutes.
Supply Chain Analysis
Reverse logistics for temperature-compromised pasteurized containers flows back to Vietnamese processors for re-thermal processing or diversion to pet food manufacturers, reducing waste exposure for air freight consolidators. Raw material supply concentrates in the Russian Far East, Alaska, and Atlantic Canada, with king crab biomass drawing from Petropavlovsk-Kamchatsky landing hubs. Blast freezing infrastructure rests on nitrogen-based tunnel systems and diesel-powered vessel operations. Single-source vulnerability runs through Russian Federation quota administration. Distribution runs through direct processor-to-restaurant contracts bypassing traditional seafood distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Russian Far East raw material concentration and Vietnamese manufacturing labor costs, with China's GB standards creating regulatory screening that rewards compliant Southeast Asian processors.
For Market Incumbents: Acquire cold chain certification assets in Vietnam's Tan Son Nhat Airport corridor to defend against Thai Union Group PCL's scaled pasteurization expansion. Lock annual volume contracts with Tokyo and Osaka izakaya chains before new entrants secure direct air freight consolidation slots. Invest in HACCP-certified sensory grading training programs to address workforce scarcity that threatens throughput expansion.
For New Entrants and Emerging Players: Launch via direct-to-restaurant distribution to Maharashtra and Gujarat coastal processing zones, where pasteurized crab export infrastructure remains underdeveloped against Vietnamese competition. Target Indian food service buyers seeking alternatives to Southeast Asian supply concentration. Pursue MSC certification early to satisfy EU IUU Regulation documentation requirements for European market access.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Vietnamese processors lacking integrated cold chain documentation but possessing established HACCP line capacity. Long-term viability hinges on sustained compliance with tightening Chinese import standards and Japanese Ministry of Health documentation requirements. Monitor quota allocation shifts between Russian Far East and Alaskan fisheries as inflection indicator for raw material cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Certification Investment | GB 31605-2020 compliance unlocks Chinese customs clearance and consolidates market access against non-certified rivals. |
| Direct-to-Restaurant Distribution Launch | Bypassing traditional seafood distributors captures margin pools previously allocated to Tokyo and Osaka intermediaries. |
| MSC Certification Program | EU IUU Regulation catch documentation favors certified North Atlantic operators with established chain-of-custody systems. |
| High-Pressure Processing Capacity Expansion | HPP technology extends refrigerated shelf life to 18 months, enabling just-inventory models for casino resort buyers. |
| Backward Integration into Vessel Operations | Captive supply of Russian Far East king crab biomass reduces exposure to Federal Agency for Fisheries quota volatility. |
Methodological Framework
Bottom-up food service procurement modeling reconciled against top-down harvest quota tracking forms the analytical core of this study. Primary interviews with pasteurization line operators, cold chain logistics managers, Japanese izakaya chain procurement directors, and EU import compliance officers combined with secondary validation against NOAA Fisheries catch share databases, China's SAMR GB standard enforcement records, EU IUU Regulation documentation requirements, and Japanese Ministry of Health import inspection data. Triangulation between vessel-level harvest reports and processor export declarations ensures volume consistency.
Input-output matrices map raw material flows from Russian Far East, Alaskan, and Canadian Atlantic fisheries through Vietnamese and Thai processing hubs to end-use segments across food service, retail, and manufacturing channels. Segmentation dimensions include product format, distribution channel, end-user category, and packaging type, with CAGRs derived from elasticity modeling against protein substitution patterns and regulatory compliance cost trajectories. Forecast inputs incorporate diesel price volatility for vessel operations and nitrogen tunnel freezing capacity expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Russian quota administration shifts or Chinese customs enforcement intensity changes. Practitioners should monitor Federal Agency for Fisheries quota announcements and SAMR GB 31605-2020 audit frequency for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Brazil Fisheries and Aquaculture Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Global Ornamental Fish Feed Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Aquaculture Water Treatment Systems and Recirculating Aquaculture Systems (RAS) Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Ecuador Shrimp Feed Market
Aquaculture Innovations
Microalgae-Based Aquafeed Market
Aquaculture Innovations
Saudi Arabia Aquaculture Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
Global Precision Aquaculture Market