
 Agriculture Micronutrients Market | 2026-2036
Agriculture Micronutrients Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Micronutrients Market Intelligence
Specialty crop producers is reorganizing demand patterns across the agriculture micronutrients landscape, pulling volume away from broad-acre commodity farming toward high-value fruit and vegetable operations. Yara International ASA leverages its coastal manufacturing network to dominate liquid micronutrient supply in Mediterranean markets. Haifa Group Ltd. specializes in water-soluble formulations that anchor its position in protected-culture and hydroponic systems.
Agriculture micronutrients encompass essential mineral elements—zinc, iron, boron, manganese—required in trace quantities for plant metabolic functions, typically applied at concentrations below one kilogram per hectare to correct soil deficiencies and optimize photosynthetic efficiency. Zinc formulations lead product type revenue due to widespread deficiency in calcareous soils across South Asia and the Sahel, while foliar spray application captures the fastest growth trajectory as farmers seek rapid nutrient correction without soil fixation losses. Online retail channels remain nascent but expand fastest where agronomy services bundle digital soil testing with prescriptive micronutrient recommendations.
The EU Green Deal and REACH framework restrict cadmium and heavy-metal contaminants in fertilizer products, forcing reformulation investments that favor chelated and purified micronutrient sources. India's FSSAI and BIS standards on food safety and fertilizer quality create compliance thresholds that channel import demand toward certified suppliers. Stakeholders must monitor how carbon-accounting rules in the EU and emerging soil-health programs in Brazil reshape micronutrient procurement criteria without explicit carbon border adjustments.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing formulation timelines as fertilizer manufacturers face binding contaminant thresholds that require immediate chelation upgrades and supply-base audits across European operations.
Growth Catalysts
- Soil Health Programs:Brazil's national soil recovery initiative mandates micronutrient fortification for degraded pasturelands, pulling zinc and boron volumes into the Cerrado and Atlantic Forest biomes.
- REACH Contaminant Limits:The EU's tightened cadmium ceilings under REACH force purification investments that simultaneously open premium pricing tiers for certified low-impurity formulations.
- Foliar Spray Technology:Precision application equipment is miniaturizing droplet control, enabling smallholders in South Asia to bypass soil fixation losses through targeted leaf-level nutrient delivery.
Market Restraints
- Input Cost Volatility:Sulfuric acid and EDTA chelating agents fluctuate with energy markets, compressing margin stability for water-soluble formulation producers.
- Supply Concentration Risk:High-purity boron reserves cluster in Turkey's Emet and Kirka deposits, creating single-source vulnerability for global borate-dependent fertilizers.
- Substitution Threat:Microbial inoculants and biostimulants displace mineral micronutrients in organic-certified operations, particularly in Dutch and Danish greenhouse systems.
Strategic Opportunities
- Underpenetrated Smallholder Segments:Sub-Saharan Africa's cocoa and coffee cooperatives lack soil testing infrastructure, creating white space for bundled micronutrient-plus-diagnostics service models.
- Digital Agronomy Convergence:Satellite imagery and soil sensor networks converge to enable variable-rate micronutrient prescriptions, unlocking precision agriculture adoption in Australian broad-acre wheat belts.
- Carbon Accounting Tailwinds:The EU's CSRD disclosure requirements reward verified yield-per-input efficiency, directing procurement toward micronutrient suppliers with ISO 14064-certified carbon footprints.
Industry Challenges
- Analytical Talent Scarcity:Soil spectroscopy and plant tissue diagnostics require agronomists trained in ICP-MS interpretation, a skill gap acute in Southeast Asian extension services.
- Compliance Timeline Compression:India's BIS fertilizer quality standards demand retesting and relabeling cycles that strain smaller importers' regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Micronutrients Market |
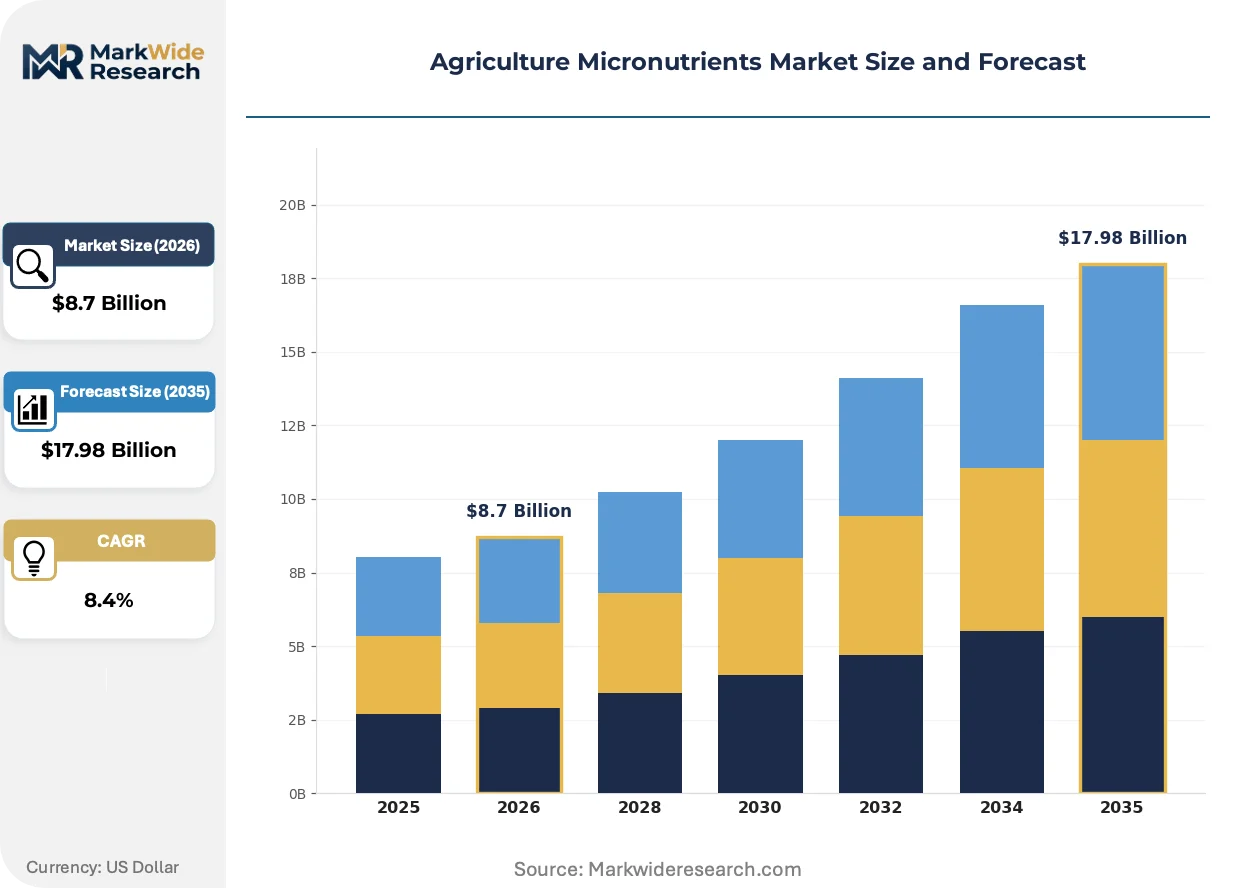
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Zinc, Iron, Boron, Manganese Application: Soil Treatment, Foliar Spray, Seed Treatment, Hydroponics Distribution Channel: Online Retail, Direct Sales, Distributors, Agronomy Services End User: Farmers, Agricultural Cooperatives, Research Institutions, Crop Producers |
| Companies Covered | BASF SE, Haifa Group Ltd., Yara International ASA, UPL Limited, Coromandel International Limited, Nutrien Ltd., The Mosaic Company, Valagro S.p.A., ICL Group Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Micronutrients Market Strategic Shifts & Innovations
Nano-encapsulation and precision delivery systems are compressing application rates while amplifying nutrient use efficiency, shifting competitive advantage toward formulation chemistry over commodity mineral sourcing.
Nano-fertilizer technology is miniaturizing nutrient particles to sub-100 nanometer scales, enabling foliar absorption through stomatal pathways previously inaccessible to conventional salts. Protected-culture tomato and pepper operations in Spain and Morocco adopt these formulations at accelerating pace. The technology is miniaturizing dosage requirements to grams-per-hectare levels, collapsing freight costs and enabling air-freight distribution to remote island agricultural systems.
The EU F-Gas Regulation and parallel REACH amendments restrict perfluorinated compounds in fertilizer packaging and coating materials, forcing substitution toward bio-based polymer barriers. Manufacturers serving Dutch and Belgian greenhouse clusters face immediate reformulation deadlines. Specialty liquid micronutrient suppliers with existing biodegradable container programs capture shelf-space advantages in German retail cooperatives.
Direct-to-farm digital platforms displace traditional agrochemical distributor networks in Indian Punjab and Haryana, where smartphone penetration enables soil-test-to-prescription turnaround in under 72 hours. Yara and Haifa pilot subscription models bundling seasonal micronutrient schedules with weather-indexed reapplication alerts. This channel shift concentrates most visibly in districts with high horticulture density and existing precision irrigation infrastructure.
Agriculture Micronutrients Market Segmentation
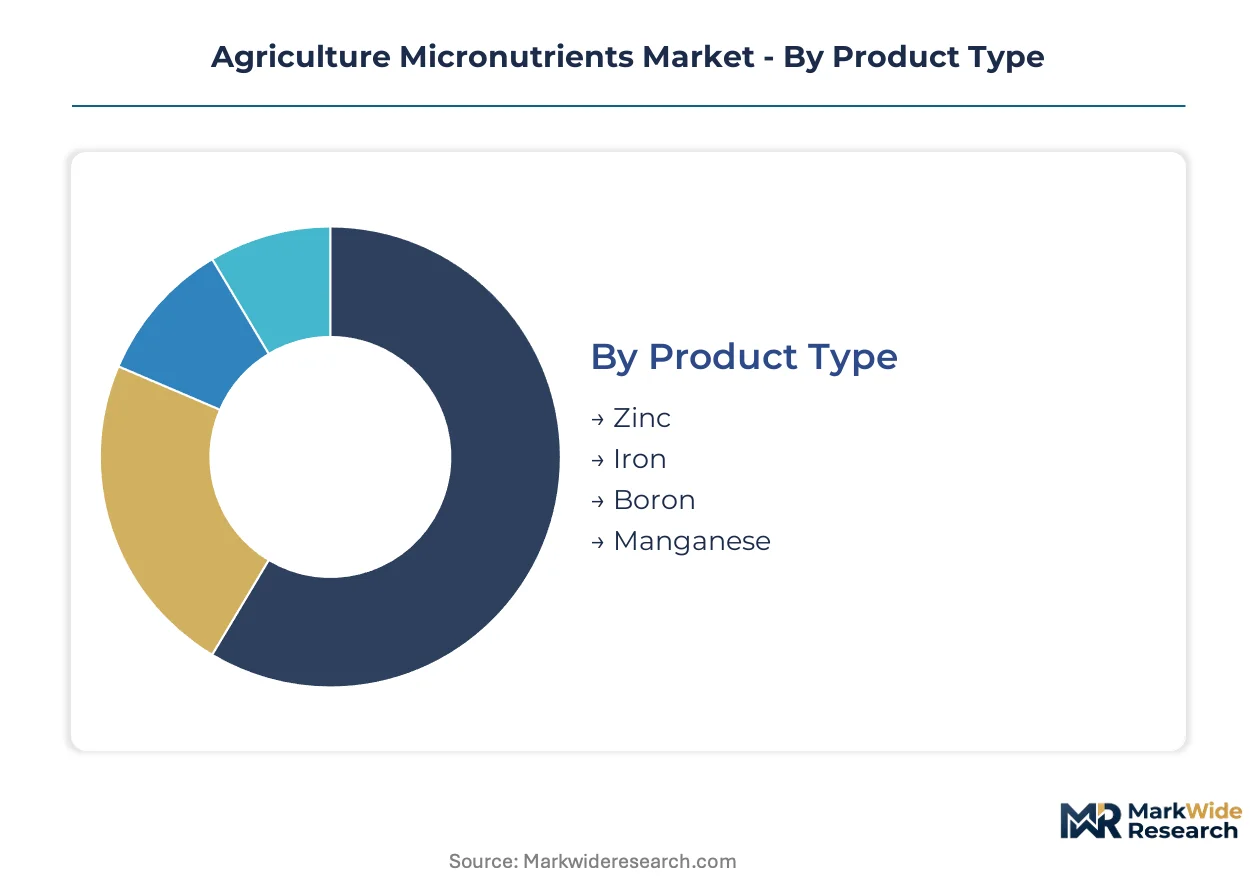
Micronutrient purchasing pathways fragment sharply between commodity grain belts and intensive horticulture zones. Channel selection determines formulation complexity, with liquid chelates flowing through specialized agronomy networks while dry salts dominate distributor-led broad-acre markets.
Product Type:
Channel-mix patterns diverge by mineral chemistry: zinc and boron formulations move heavily through direct sales to plantation operators, while manganese and iron products distribute more evenly across retail cooperatives.
- Zinc:Sulfate and oxide forms dominate calcareous soil correction programs across South Asia and the Sahel. Specialty crop growers in Spain and Morocco pull chelated zinc through Haifa's water-soluble channels for protected-culture vegetables.
- Boron:Solubor and boric acid variants anchor yield quality programs in oilseed and legume rotations. Turkey's Emet deposit concentration forces European blenders to maintain dual-source qualification protocols for supply security.
- Iron:EDDHA-chelated formulations command premium placement in high-pH vineyard and orchard systems where chlorosis correction demands foliar precision.
- Manganese:Carbonate and sulfate grades serve broad-acre cereal programs through distributor bulk-blending operations, with limited chelate uptake in high-value potato and sugar beet districts.
By volume, zinc leads. By growth pace, boron is ahead.
Application:
Margin structures favor precision delivery methods, with foliar and seed treatments capturing formulation premiums against commodity soil broadcast applications.
- Foliar Spray:Atomization equipment advances enable sub-100-micron droplet control for stomatal nutrient absorption. Indian Punjab horticulture clusters and Australian wheat belts drive hardware adoption for rapid deficiency correction without fixation losses.
- Soil Treatment:Granular and powder formulations integrate into bulk-blending operations for zinc-deficient rice-wheat rotations. Basal application remains cost-dominant for smallholders lacking spray equipment access.
- Seed Treatment:Film-coat and slurry applications concentrate in hybrid maize and soybean programs where early root establishment determines yield potential. Brazil's Cerrado expansion pulls manganese and zinc seed treatments through multinational supply agreements.
- Hydroponics:Water-soluble A and B tank mixes require analytical-grade purity for recirculating systems. Dutch and Belgian greenhouse clusters specify sub-10-ppm heavy-metal thresholds under EU Green Deal contaminant rules.
Soil treatment holds volume dominance. Foliar spray climbs fastest on precision agriculture tailwinds.
Distribution Channel:
Customer scale dictates channel selection, with smallholders fragmenting across mobile-enabled platforms while plantation operators consolidate through direct manufacturer relationships.
- Agronomy Services:Bundled soil testing and prescription services capture margin in districts with established precision irrigation infrastructure. Yara's subscription models in Indian Haryana combine seasonal schedules with weather-indexed reapplication alerts.
- Distributors:Regional cooperatives and independent ag-retailers dominate zinc and manganese volume in North American corn-soy belts and Black Sea wheat zones, with inventory financing as a key competitive lever.
- Direct Sales:Plantation and estate agriculture in Southeast Asian palm oil and Brazilian citrus bypass intermediaries for container-scale liquid formulation contracts.
- Online Retail:Smartphone-enabled platforms displace traditional networks where last-mile logistics mature, concentrated in Indian districts with high horticulture density and existing cold-chain infrastructure.
Distributors handle the largest tonnage. Online retail expands most quickly where digital soil-test integration matures.
End User:
Procurement sophistication separates commercial crop producers from subsistence operators, with cooperatives serving as critical aggregation points for technical advisory and volume pricing.
- Crop Producers:Specialty vegetable and fruit operations in Mediterranean basin and California Central Valley specify chelated formulations with certified contaminant documentation for export compliance.
- Agricultural Cooperatives:Brazilian coffee and cocoa cooperatives aggregate smallholder demand for soil testing and micronutrient procurement, creating service-model white space in Sub-Saharan Africa's underpenetrated extension systems.
- Farmers:Individual smallholders in South Asia and Southeast Asia access micronutrients through government subsidy programs and retail counter sales, with limited soil diagnostics driving commodity-grade purchasing.
- Research Institutions:University and government trial stations source analytical-grade materials for cultivar nutrient response studies and regional deficiency mapping programs.
Farmers constitute the largest user base by headcount. Crop producers drive value concentration through premium formulation specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey's Emet and Kirka borate deposits supply European blenders with high-purity boron, while Indian zinc sulfate flows to calcareous soil programs across South Asia and the Sahel corridor.
India
Smallholder intensification in rice-wheat rotations drives zinc and boron uptake across Punjab and Haryana. FSSAI and BIS standards on fertilizer quality create compliance thresholds that channel import demand toward certified suppliers. Direct-to-farm digital platforms in Haryana displace traditional distributor networks where smartphone penetration enables rapid soil-test-to-prescription turnaround.
Brazil
The national soil recovery initiative mandates micronutrient fortification for degraded pasturelands across the Cerrado and Atlantic Forest biomes. ANVISA regulations align with EU contaminant standards for export-oriented citrus and soybean operations. Manganese and zinc seed treatments concentrate in Mato Grosso and Goiás through multinational supply agreements with hybrid maize programs.
Spain
Protected-culture tomato and pepper operations in Almería and Murcia adopt nano-encapsulated formulations at accelerating pace. The EU F-Gas Regulation and REACH amendments restrict perfluorinated compounds in fertilizer packaging, forcing substitution toward bio-based polymer barriers. Haifa Group's water-soluble channels anchor chelated zinc placement for Mediterranean horticulture exports.
United States
Specialty crop producers in California Central Valley specify chelated formulations with certified contaminant documentation for export compliance to Asian markets. EPA and USDA oversight on heavy-metal thresholds in fertilizer products shapes procurement criteria for organic-certified operations. Bulk-blending cooperatives in Iowa and Illinois dominate zinc and manganese volume for corn-soy rotations.
Netherlands
Greenhouse clusters in Westland and Aalsmeer specify sub-10-ppm heavy-metal thresholds for recirculating hydroponic systems under EU Green Deal rules. ECHA's tightened cadmium ceilings force purification investments that open premium pricing tiers for certified low-impurity formulations. Yara's coastal manufacturing network dominates liquid micronutrient supply to Belgian and German retail cooperatives.
Agriculture Micronutrients Market Key Industry Players
Player mix skews toward integrated fertilizer majors with coastal manufacturing networks and specialty chelate formulators with water-soluble expertise. Tiered concentration separates multinational nutrient conglomerates from regional blenders and niche hydroponic specialists. Two dominant competitive moves are chelation technology licensing for contaminant compliance and direct-to-farm digital platform deployment for smallholder channel capture.
Among European integrated majors, BASF SE and Yara International ASA exemplify the coastal manufacturing archetype with Mediterranean liquid formulation dominance. Haifa Group Ltd. occupies a position within the specialty water-soluble tier, anchoring protected-culture supply channels. ICL Group Ltd. represents the borate-integrated model with captive mineral sourcing. These three company structures illustrate how geographic origin and corporate suffix patterns align with distinct competitive positioning in micronutrient supply.
| Leading Market Players |
|---|
| BASF SE |
| Haifa Group Ltd. |
| Yara International ASA |
| UPL Limited |
| Coromandel International Limited |
| Nutrien Ltd. |
| The Mosaic Company |
| Valagro S.p.A. |
| ICL Group Ltd. |
| Others |
Cost & Logistics Intelligence
Coastal liquid formulation capacity utilization at Yara's Mediterranean plants anchors price floors for chelated micronutrients, compressing margin space for inland dry-salt competitors while rewarding scale investments in Rotterdam and Tarragona that serve EU Green Deal compliance demand.
Pricing Analysis
Conventional sulfate-oxide formulations trade at commodity-grade price points against premium chelated alternatives and emerging nano-encapsulated tiers. Price differentiation separates EDDHA-chelated iron for vineyard chlorosis correction from bulk-blended zinc sulfate for rice-wheat rotations, with certification grade under REACH cadmium thresholds commanding substantial premia. Cost compression in standard-grade boric acid intensifies because Turkish Emet deposit concentration limits alternative sourcing. Smallholder cooperatives in Sub-Saharan Africa exhibit highest price sensitivity, while Dutch greenhouse clusters purchasing analytical-grade hydroponic inputs show least.
Supply Chain Analysis
Turkish Straits transit underwrites European borate supply security, with alternative Indian Ocean routing adding weeks to delivery schedules. High-purity boron concentrates in Turkey's Emet and Kirka deposits, while zinc sulfate manufacturing clusters in India and China, and EDDHA chelate production centers in Western Europe. Raw material dependencies encompass sulfuric acid for sulfate production, EDTA and EDDHA chelating agents, and analytical-grade mineral feedstocks. Single-source vulnerability for global borate supply creates structural risk exposure. Distribution runs through agronomy service networks for precision formulations and bulk-blending cooperatives for commodity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cooperative aggregation in Brazil's coffee sector and digital platform consolidation in Indian Punjab, shifting procurement leverage toward volume-aggregated smallholders.
For Market Incumbents: Fortify coastal manufacturing positions in Rotterdam and Tarragona against Turkish borate supply disruption through dual-source qualification protocols. Deepen backward integration into captive sulfuric acid production to offset energy-linked input volatility. Invest in ISO 14064 carbon footprint certification to capture EU CSRD disclosure-driven procurement preference. For New Entrants and Emerging Players: Soil testing infrastructure gaps in Sub-Saharan African cocoa cooperatives present white-space entry points where incumbents under-serve extension service demand. Target Ghana and Côte d'Ivoire cooperative bundling models combining diagnostics with prescriptive micronutrient schedules. Deploy satellite-enabled variable-rate prescription platforms as differentiated go-to-market anchor in Australian wheat belts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation chemistry specialists with nano-encapsulation capabilities over commodity mineral traders. Long-term viability rests on regulatory compliance architecture and precision agriculture integration depth. Acquisition target archetype: water-soluble specialists with protected-culture channel control and biodegradable packaging programs. Watch EU cadmium threshold enforcement stringency as inflection indicator for purification investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Chelate Technology Licensing | REACH cadmium compliance opens premium pricing tiers for certified low-impurity formulations. |
| Direct-to-Farm Digital Platform Deployment | Smartphone penetration in Indian Punjab enables soil-test-to-prescription turnaround under 72 hours. |
| Backward Integration into Sulfuric Acid | Captive production insulates margin stability from energy market volatility. |
| Nano-Encapsulation R&D Investment | Sub-100 nanometer particle scales enable stomatal absorption pathways for foliar efficiency gains. |
| Biodegradable Packaging Transition | EU F-Gas Regulation compliance captures shelf-space advantages in German retail cooperatives. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with fertilizer formulation chemists, plantation agronomists, cooperative procurement managers, and regulatory affairs specialists at EU and Indian compliance bodies; and secondary validation through customs trade databases, BIS fertilizer quality filings, ECHA REACH registration data, and SEC disclosures from listed nutrient majors. Bottom-up volume modeling triangulated against top-down value estimates from regional production capacity and import flow analysis.
Across the projection horizon, analytical frameworks segmented demand by mineral chemistry, application method, distribution channel architecture, and end-user procurement sophistication. CAGRs derived from fitted growth curves calibrated to historical adoption patterns in zinc-deficient calcareous soil zones and precision agriculture diffusion rates in protected-culture horticulture. Forecast inputs incorporated EU Green Deal implementation timelines and Brazilian soil recovery initiative mandate compliance schedules.
Forecasts assume regulatory continuity in EU REACH cadmium ceilings and India's BIS fertilizer quality standards; material policy shifts would require re-modeling. Specific risk factors encompass Turkish borate supply disruption, sulfuric acid price volatility, and microbial inoculant substitution acceleration in organic-certified operations. Practitioners should keep alternative scenarios live as EU carbon-accounting disclosure requirements and Brazilian pastureland recovery enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
CBD Plant Nutrients Market
Agricultural Chemicals
Feed Pelletizing Agents Market
Agricultural Chemicals
Organic Bromide Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
Asia-Pacific Feed Antibiotics Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
Auxin Substitutes Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
Asia-Pacific Feed Antioxidants Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
ASEAN Livestock Disinfectant Market
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market