
 North America Aqua Feed Market | 2026-2036
North America Aqua Feed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aqua Feed Market Analytics
Formulation service revenue is narrowing as compound feed manufacturers internalize nutritional design capabilities. Cargill, Incorporated leverages its integrated supply chain from grain procurement to finished aquafeed production across the Great Lakes and Gulf Coast. Alltech Inc. differentiates through yeast-based additive platforms that address gut health in high-density recirculating systems. Nutreco N.V. anchors its North American position through Skretting's salmon and trout feed specialization in the Northeast and Pacific Northwest.
North America aqua feed comprises nutritionally complete diets formulated for aquatic species, typically containing 25-45% crude protein, lipid profiles adjusted for species-specific metabolism, and binders that maintain pellet integrity in water for 2-10 minutes. These feeds sustain intensive aquaculture production where natural forage cannot meet biomass density requirements. Fish feed occupies the dominant volume position given salmonid and tilapia farming scale, while shrimp feed represents the fastest-expanding category as Gulf Coast and Mexican Pacific producers adopt intensive pond systems. Vegetable protein sources are displacing fish meal in grower diets as price volatility and sustainability certification pressures reshape ingredient procurement.
The FDA's Veterinary Feed Directive restricts medically important antimicrobial use in aquafeed, compelling reformulation toward probiotics and phytogenic alternatives. The USDA's National Organic Program and Canadian Food Inspection Agency standards govern certified organic feed claims, creating dual compliance obligations for cross-border suppliers. The EPA's Clean Water Act permitting for concentrated aquatic animal production facilities indirectly constrains feed conversion efficiency targets. Stakeholders must monitor evolving state-level nutrient discharge regulations and ingredient traceability mandates that will determine facility expansion viability and feed cost structures.
Market Dynamics
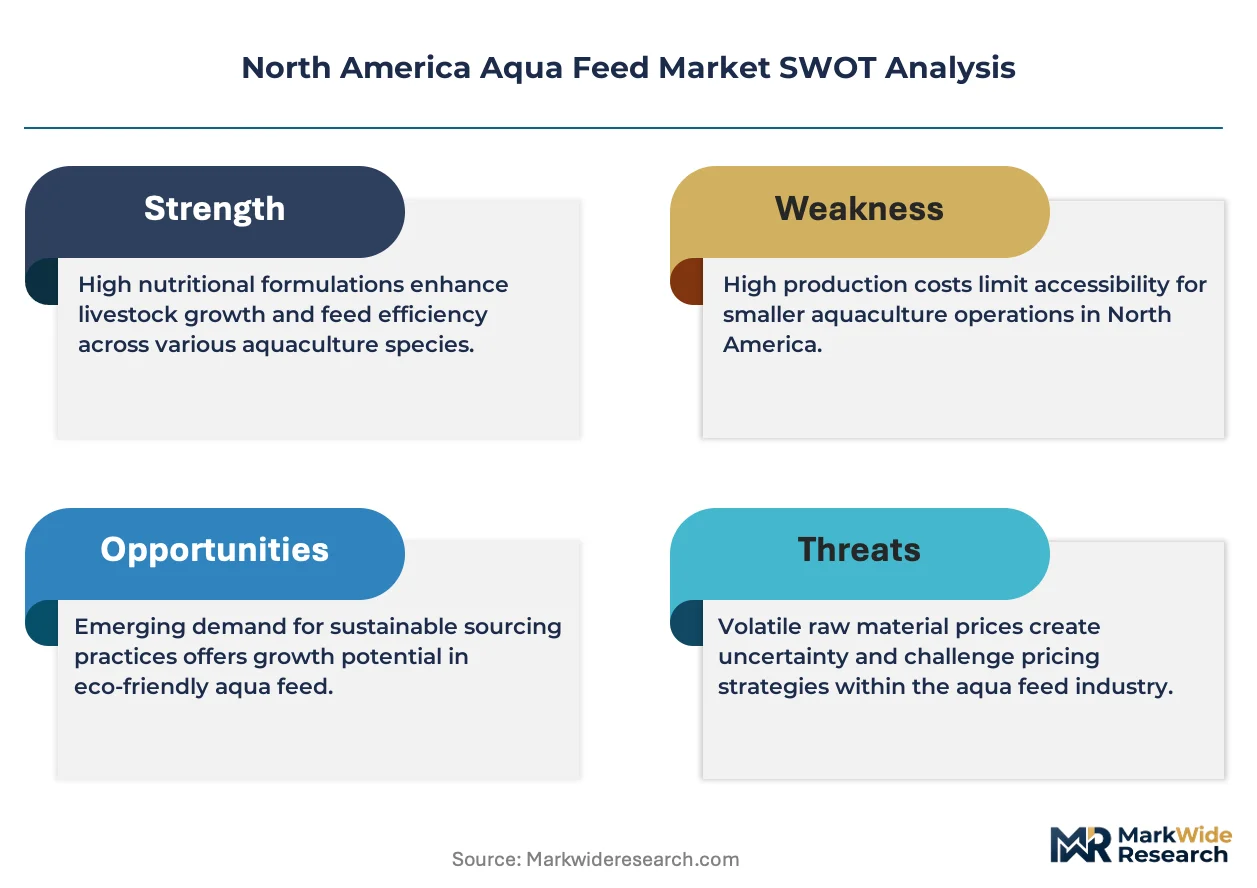
The FDA's Veterinary Feed Directive has triggered a wholesale reformulation of medicated aquafeed, forcing manufacturers to abandon long-standing antibiotic-dependent protocols in favor of probiotic and phytogenic alternatives. This regulatory pivot compresses margins while accelerating R&D cycles across the supply base.
Growth Catalysts
- Salmonid farm expansion:British Columbia and Maine operators are scaling intensive production systems, creating sustained demand for high-protein grower diets with optimized feed conversion ratios.
- Regulatory clarity:The USDA's National Organic Program standards for aquafeed certification are enabling premium pricing tiers for compliant producers serving retail and foodservice channels.
- Recirculating aquaculture system proliferation:Closed-containment facilities across Washington and Oregon require specialized feed formulations with enhanced water stability and reduced nitrogenous waste output.
Market Restraints
- Fish meal price volatility:Peruvian anchovy harvest fluctuations and El Niño disruptions transmit directly into input cost instability for marine protein-dependent formulations.
- Great Plains grain concentration:Corn and soybean meal sourcing remains geographically concentrated, exposing compounders to regional drought and logistics bottlenecks.
- Antibiotic residue detection limits:The FDA's zero-tolerance enforcement for chloramphenicol and nitrofuran residues in imported aquaculture products restricts formulation flexibility for export-oriented farms.
Strategic Opportunities
- Gulf Coast shrimp intensification:Texas and Louisiana producers are converting extensive pond operations to high-density systems, opening demand for specialized shrimp feeds with enhanced attractability profiles.
- Insect protein integration:Black soldier fly meal is achieving cost parity with fish meal in grower diets, offering a defensible sustainability narrative for certified producers.
- Direct-to-farm distribution:Bypassing traditional feed dealer networks through containerized bulk delivery is capturing margin from large-scale salmonid operators in the Pacific Northwest corridor.
Industry Challenges
- Aquaculture nutritionist scarcity:The specialized skill set bridging aquatic physiology, feed manufacturing, and regulatory compliance commands premium compensation and constrains expansion timelines.
- Organic certification timelines:The USDA's three-year transition requirement for feed ingredient sourcing creates working capital strain for producers targeting certified organic aquaculture channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aqua Feed Market |
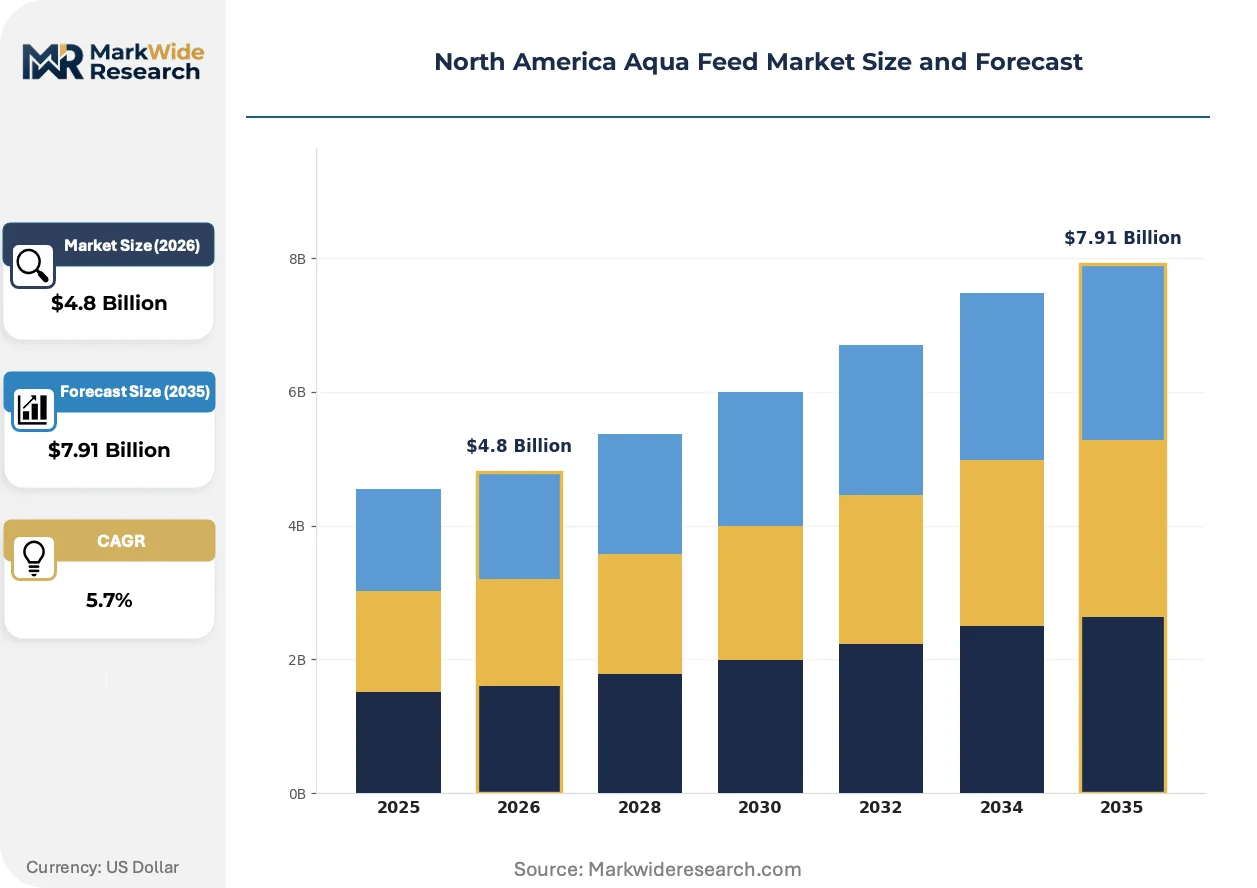
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Feed, Shrimp Feed, Mollusk Feed, Crustacean Feed Ingredient Type: Vegetable Protein, Fish Meal, Fish Oil, Additives Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers End User: Fish Farms, Aquaculture, Research Institutes, Commercial Feeders |
| Companies Covered | Cargill, Incorporated, Alltech Inc., Nutreco N.V., Archer Daniels Midland Company, Adisseo, Wilbur-Ellis Nutrition, LLC, Ridley Corporation Limited, Purina Animal Nutrition LLC, Land O'Lakes, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aqua Feed Market Evolving Landscape
Precision nutrition platforms and alternative protein sourcing are converging to reshape formulation economics, while regulatory pressure on antimicrobial use accelerates adoption of functional feed additives. These forces are compressing traditional compound feed margins while opening specialized service revenue streams.
Single-cell protein derived from methanotrophic bacteria is rendering obsolete conventional fish meal inclusion rates in salmonid grower diets. Norwegian-backed facilities in the Pacific Northwest are commissioning commercial-scale production, with British Columbia farm operators piloting 30% fish meal replacement formulations. The technology is rendering obsolete historical dependency on marine capture fisheries for protein supply security.
The EPA's Clean Water Act nutrient discharge permitting framework is tightening total nitrogen and phosphorus limits for concentrated aquatic animal production facilities in Washington and Idaho. This regulatory pressure is forcing feed manufacturers to reformulate with reduced crude protein levels and enhanced amino acid crystalline supplementation. Salmon smolt producers in the Columbia River basin are absorbing premium pricing for low-pollution feeds to secure operating permit renewals.
Subscription-based feed management programs are displacing spot purchasing arrangements among mid-scale tilapia operators in Texas and Florida. These bundled offerings combine formulated diets with real-time growth monitoring and inventory optimization, capturing multi-year contract value. The model is most visible in the southeastern United States where vertically integrated processor-producer relationships dominate procurement authority.
North America Aqua Feed Market Segmentation
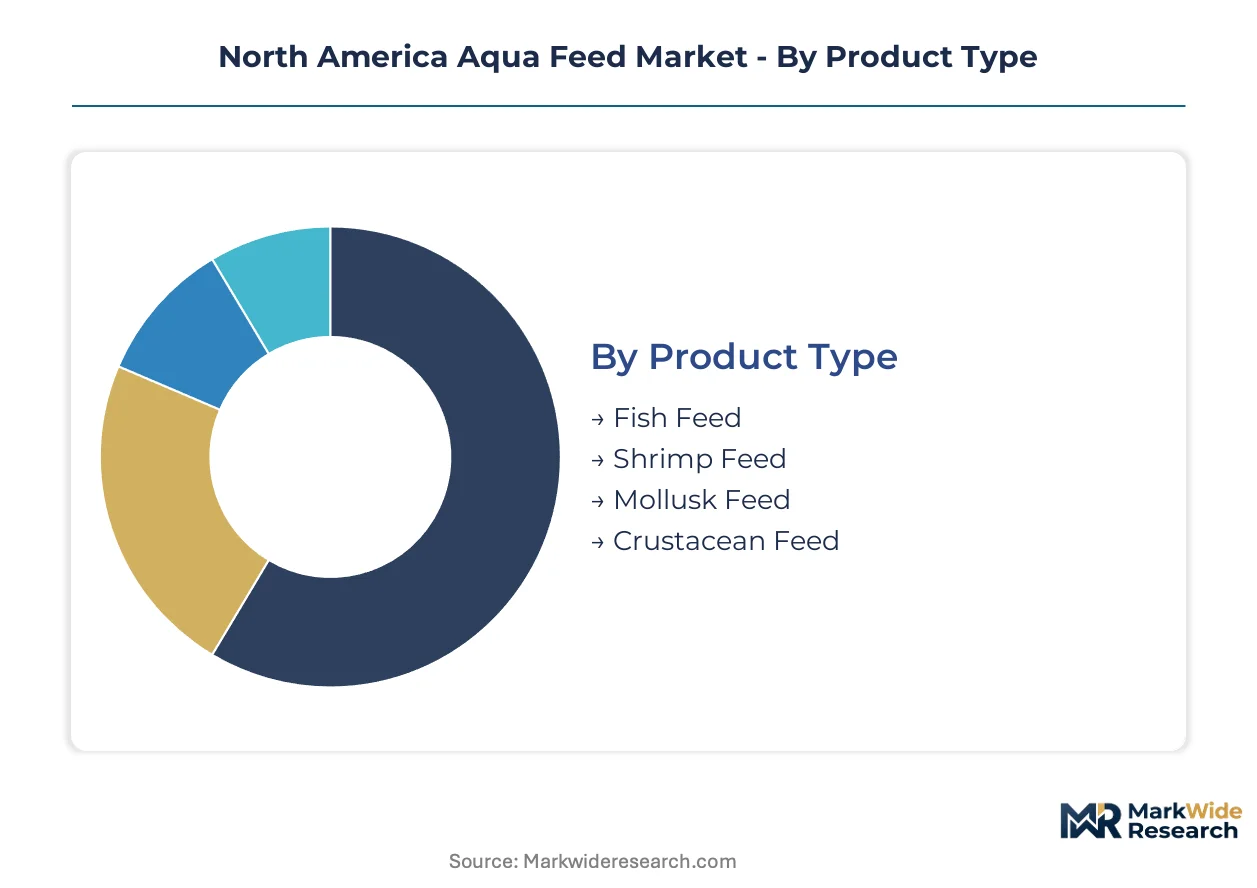
Segmentation in North America aqua feed reveals how protein sourcing, species specialization, and procurement channels determine margin structure. Each dimension carries distinct regulatory exposure and capital intensity requirements.
Product Type:
Application focus distinguishes volume leaders from emerging categories as species farming intensifies across coastal and inland systems.
- Fish Feed:Formulations contain 25-45% crude protein with lipid profiles calibrated for salmonid metabolism. British Columbia and Maine salmon farms sustain demand for high-performance grower diets with optimized feed conversion ratios. This segment commands the established base.
- Shrimp Feed:Specialized diets feature enhanced attractability profiles and water-stable binders for intensive pond operations. Texas and Louisiana producers converting to high-density systems drive procurement volume. The steepest expansion runs through shrimp feed.
- Mollusk Feed:Microalgae-based formulations support oyster and mussel hatchery operations in Washington and Chesapeake Bay waters.
- Crustacean Feed:Crayfish and crab diets serve regional markets in Louisiana bayous and Pacific Northwest coastal ponds.
Fish feed anchors revenue stability. Shrimp feed gains share fastest as Gulf Coast intensification accelerates.
Ingredient Type:
Cost tier positioning reflects protein source economics and sustainability certification pressures reshaping procurement.
- Vegetable Protein:Soybean meal and corn gluten meal displace marine proteins in grower diets as price volatility and ASC certification requirements reshape formulation. The Pacific Northwest corridor leads adoption of high-inclusion vegetable protein diets for salmon smolt production. Vegetable protein commands the established base.
- Fish Meal:Peruvian anchovy harvest fluctuations transmit directly into input cost instability for marine protein-dependent formulations. British Columbia farms pilot 30% replacement rates using single-cell protein alternatives. The steepest contraction runs through fish meal.
- Fish Oil:Omega-3 fatty acid profiles remain critical for broodstock and early-stage diets despite partial replacement by algal oils.
- Additives:Probiotics, phytogenics, and yeast-based platforms address gut health in recirculating systems following FDA Veterinary Feed Directive restrictions.
Vegetable protein secures volume leadership. Additive categories climb fastest as antibiotic alternatives proliferate.
Distribution Channel:
Customer type determines service intensity and margin capture across fragmented and consolidated buyer bases.
- Direct Sales:Containerized bulk delivery bypasses dealer networks to capture margin from large-scale salmonid operators in Washington and Oregon. Long-term contracts bundle formulated diets with real-time growth monitoring. Direct sales commands the established base.
- Wholesalers:Traditional feed dealers serve mid-scale tilapia operators in Texas and Florida through spot purchasing arrangements now displaced by subscription programs. The steepest compression runs through wholesalers.
- Offline Retail:Regional distributors maintain inventory for small-scale farms and hobbyist aquaculture in southeastern states.
- Online Retail:E-commerce platforms emerge for specialty additives and probiotic supplements targeting research institutes and niche producers.
Direct sales anchors producer relationships. Online retail expands fastest as digital procurement penetrates specialty inputs.
End User:
Volume concentration varies dramatically between commercial production systems and institutional demand.
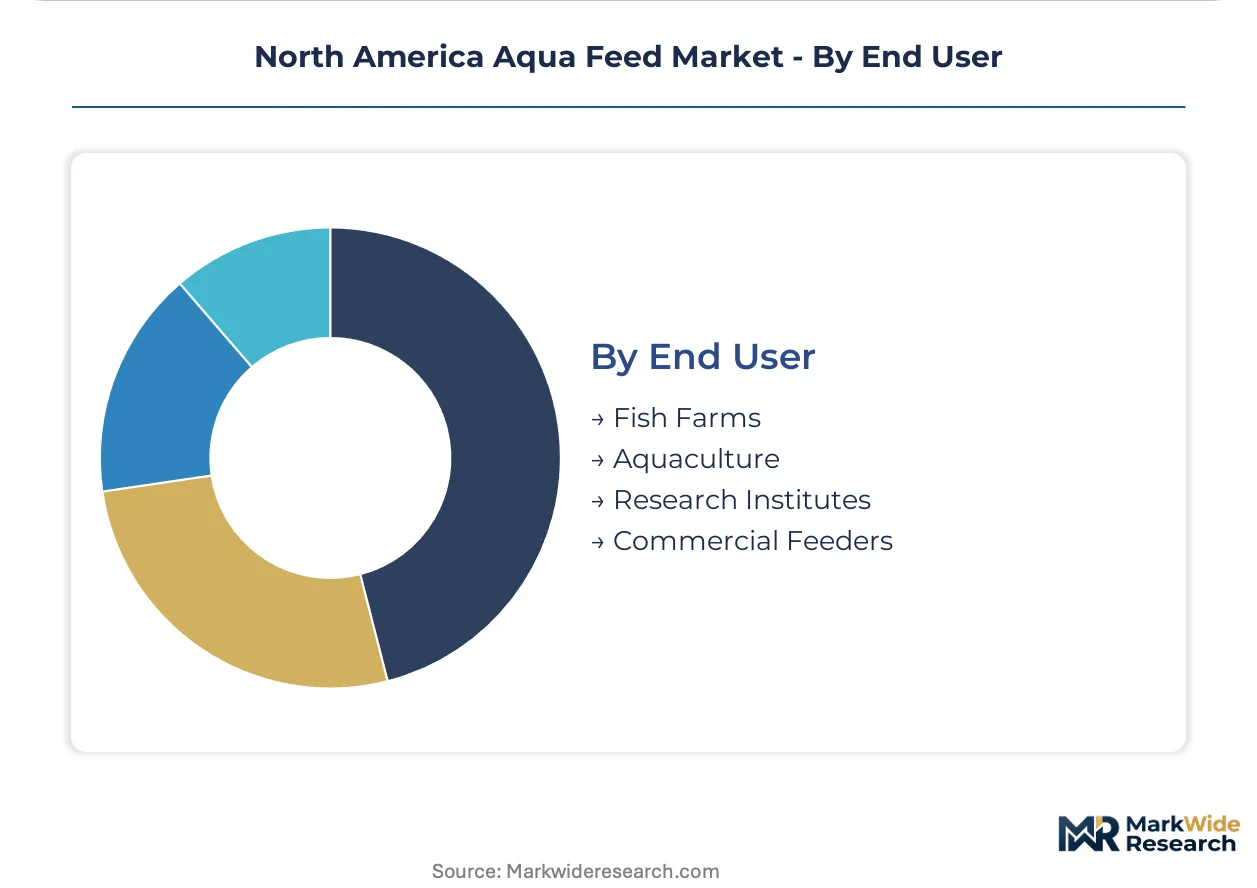
- Fish Farms:Intensive salmonid and tilapia operations in British Columbia, Maine, and the Great Lakes drive bulk procurement of complete diets with certified ingredient traceability. Fish farms command the established base.
- Aquaculture:Shrimp pond systems across Texas, Louisiana, and Mexican Pacific waters require specialized feeds with enhanced water stability. The steepest expansion runs through aquaculture.
- Commercial Feeders:Independent nutritionists and small compounders purchase base mixes and premixes for custom formulation.
- Research Institutes:University and government hatcheries in Washington and Florida procure experimental diets for breeding program development.
Fish farms dominate procurement volume. Aquaculture applications gain share fastest as shrimp intensification spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the Pacific Northwest corridor demonstrate the least price elasticity, absorbing premium pricing for low-pollution formulations to secure EPA permit renewals. Gulf Coast shrimp operators exhibit the highest sensitivity, converting to intensive systems only when feed costs align with export market returns.
United States
Washington and Oregon salmon farms drive demand for specialized feeds with enhanced water stability and reduced nitrogenous waste. The EPA's Clean Water Act permitting framework tightens total nitrogen and phosphorus discharge limits for concentrated aquatic animal production facilities. Columbia River basin smolt producers absorb premium pricing for low-pollution feeds to secure operating permit renewals.
Canada
British Columbia salmonid farming operations scale intensive production systems, creating sustained demand for high-protein grower diets with optimized feed conversion ratios. The Canadian Food Inspection Agency standards govern certified organic feed claims, creating dual compliance obligations for cross-border suppliers. Vancouver Island and mainland coastal facilities pilot single-cell protein formulations achieving 30% fish meal replacement rates.
Mexico
Sinaloa and Sonora shrimp producers along the Mexican Pacific accelerate adoption of intensive pond systems, opening procurement volume for specialized feeds with enhanced attractability profiles. The country's national agricultural regulator monitors antibiotic residue thresholds in export-oriented aquaculture products. Guaymas-Empalme processing clusters integrate vertically into feed sourcing to control input cost volatility.
North America Aqua Feed Market Competitive Landscape
Capability concentration sits with specialized nutrition platforms; scale advantage sits with integrated grain-to-feed supply chains. The market structure tiers between multinational compounders with captive ingredient sourcing and regional specialists with species-specific formulation expertise. Three archetypes dominate: integrated agribusiness conglomerates, dedicated aquaculture nutrition platforms, and diversified animal health companies. Consolidation through backward integration into alternative protein production and forward integration into direct-to-farm distribution networks reshapes competitive positioning.
Among integrated supply chain operators, Cargill, Incorporated and Archer Daniels Midland Company represent the scale-driven tier with grain procurement-to-finished feed production capabilities. Nutreco N.V. occupies a position within the specialized aquaculture nutrition archetype through its Skretting salmon and trout feed focus. Alltech Inc. exemplifies the functional additive platform approach, anchoring differentiation through yeast-based technologies addressing gut health in high-density recirculating systems.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Alltech Inc. |
| Nutreco N.V. |
| Archer Daniels Midland Company |
| Adisseo |
| Wilbur-Ellis Nutrition, LLC |
| Ridley Corporation Limited |
| Purina Animal Nutrition LLC |
| Land O'Lakes |
| Others |
Value Network & Pricing Analysis
Undercapacity in single-cell protein fermentation capacity across the Pacific Northwest is compressing formulation margins while elevating premiums for low-pollution certified feeds. This utilization imbalance forces compounders to absorb higher input costs or pass them to EPA-constrained salmonid operators in Washington and Idaho.
Pricing Analysis
Subscription-based feed management programs now drive lifetime value capture, displacing spot purchasing among mid-scale tilapia operators. Three-tier pricing structure across premium certified-organic, standard commercial-grade, and economy bulk commodity levels reflects USDA National Organic Program compliance costs and EPA discharge permit requirements. Pricing pressure stems from fish meal volatility transmitted through Peruvian anchovy harvest fluctuations. Gulf Coast shrimp producers exhibit highest sensitivity, while Columbia River basin salmon farms absorb premiums to secure operating permits.
Supply Chain Analysis
Upstream feedstock sourcing draws from Great Plains grain concentration, Peruvian marine protein harvests, and emerging Pacific Northwest single-cell protein facilities. Corn and soybean meal dependence rests on regional drought exposure, while fish meal hinges on El Niño disruptions. Single-source vulnerability concentrates in Peruvian anchovy fisheries for marine protein inputs. Distribution runs through direct-to-farm containerized bulk delivery for large-scale operators, supplemented by traditional dealer networks serving fragmented mid-scale producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America aqua feed represents early-cycle expansion as shrimp intensification across Texas and Louisiana accelerates adoption of specialized high-density formulations. This penetration tailwind creates asymmetric opportunity for positioned suppliers.
For Market Incumbents: Pre-empt margin compression by securing backward integration into alternative protein production, particularly black soldier fly meal and methanotrophic bacterial biomass. Lock in long-term offtake agreements with British Columbia salmon operators before single-cell protein achieves cost parity. Defend position by embedding real-time growth monitoring services that raise switching costs for Pacific Northwest contract customers.
For New Entrants and Emerging Players: Mexican Pacific shrimp ponds in Sinaloa and Sonora represent the most penetrable white-space target, given vertical integration gaps at Guaymas-Empalme processing clusters. Enter through specialized attractability formulations for intensive pond systems, leveraging direct technical sales teams rather than dealer networks. Partner with regional distributors for logistics coverage while building species-specific formulation credibility.
For Investors and Strategic Acquirers: Capital is best deployed toward functional additive platforms with FDA Veterinary Feed Directive-compliant probiotic and phytogenic portfolios, given regulatory tailwinds and aquaculture nutritionist scarcity. Acquisition targets should demonstrate captive ingredient sourcing or direct-to-farm distribution density. Monitor EPA Clean Water Act permit renewal timelines as inflection indicators for low-pollution feed demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Protein | Black soldier fly meal production insulates margins from Peruvian anchovy volatility. |
| Direct-to-Farm Distribution Buildout | Containerized bulk delivery captures margin from Washington and Oregon salmon operators. |
| Functional Additive Platform Expansion | Probiotic and phytogenic portfolios address FDA Veterinary Feed Directive compliance requirements. |
| Subscription-Based Feed Management Launch | Bundled diet and monitoring services lock in multi-year contracts with Texas tilapia producers. |
| Certified Organic Feed Line Development | USDA National Organic Program compliance opens premium pricing tiers for retail channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aquaculture nutritionists, compound feed plant managers, salmon farm procurement directors, shrimp pond operators, and regulatory compliance officers at FDA and EPA. Secondary validation drew from FDA Veterinary Feed Directive filings, EPA Clean Water Act permit databases, USDA National Organic Program standards, Canadian Food Inspection Agency guidelines, and customs trade data on fish meal imports. Bottom-up volume modeling triangulated against top-down market sizing across ingredient type, species application, and distribution channel dimensions.
Calibration anchored historical consumption patterns to facility expansion announcements and permit issuance timelines across the analysis window. Segmentation modeling incorporated product type, ingredient source, distribution channel, and end-user facility scale. CAGRs derived from regression analysis against protein sourcing cost trajectories and regulatory compliance adoption curves, with scenario weighting for El Niño frequency and organic certification transition rates.
Practitioners should monitor Peruvian anchovy quota announcements, EPA nutrient discharge limit revisions, and single-cell protein facility commissioning schedules for early signals of forecast deviation. Cross-checking against FAO aquaculture production statistics and trade flow data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
Aquaculture Healthcare Market
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Norway Aquaculture Market
Aquaculture Innovations
Qatar Fisheries and Aquaculture Market
Aquaculture Innovations
Crab Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Thailand Aquafeed Market
Aquaculture Innovations
Global Precision Aquaculture Market
Aquaculture Innovations
Global Plant Based Fish Feed Market