
 China Shrimp Market | 2026-2036
China Shrimp Market Size, Share, and Industry Trends Forecast 2026-2036
China Shrimp Market Intelligence
Multi-source procurement from both domestic ponds and Southeast Asian suppliers is decoupling from the old single-origin model that once dominated China's shrimp trade. Thai Union Group PCL leverages its integrated aquaculture and processing footprint across Thailand to secure consistent supply into Chinese ports. Clearwater Seafoods anchors its positioning through Arctic-cold chain specialization, delivering premium shell-on product to high-end buyers. Avanti Feeds competes on feed-to-farm integration, controlling input costs for producers serving export and domestic channels alike.
China shrimp comprises decapod crustaceans of the order Decapoda, typically Penaeus vannamei or Penaeus monodon species, harvested at 20-50 grams individual weight and processed under HACCP protocols for human consumption across retail and foodservice channels. Frozen shrimp dominates volume throughput due to extended shelf life and suitability for cross-province logistics, while fresh shrimp commands margin concentration in tier-one cities with same-day delivery infrastructure. Online retail channels are expanding fastest among distribution pathways, though traditional fish markets still occupy the volume core in secondary cities.
SAMR enforces GB standards for aquaculture drug residues and labeling, while MEE monitors wastewater discharge from coastal processing clusters; both frameworks elevate compliance costs for smaller pond operators. China's dual carbon goals are pushing processing facilities toward energy-efficient cold storage and renewable-powered logistics. Stakeholders must monitor how provincial enforcement intensity and green infrastructure mandates reshape supplier viability across the Yangtze River Delta and Pearl River Delta processing belts.
Market Dynamics
China's shrimp sector is undergoing a structural pivot from import-dependent supply chains toward domestic pond intensification and cross-border Southeast Asian partnerships, reshaping procurement geography and cold-chain investment priorities.
Growth Catalysts
- GB Standards Compliance:SAMR enforcement of aquaculture drug residue limits is filtering out subscale pond operators and concentrating volume among certified processors in Shandong and Guangdong provinces.
- Foodservice Premiumization:Domestic restaurant chains are expanding shell-on and value-added shrimp SKUs, pulling higher-margin product through upgraded port-of-entry inspection lanes.
- Cold-Chain Infrastructure:Provincial governments in the Pearl River Delta are subsidizing renewable-powered refrigerated warehousing, extending shelf-life viability for inland distribution.
Market Restraints
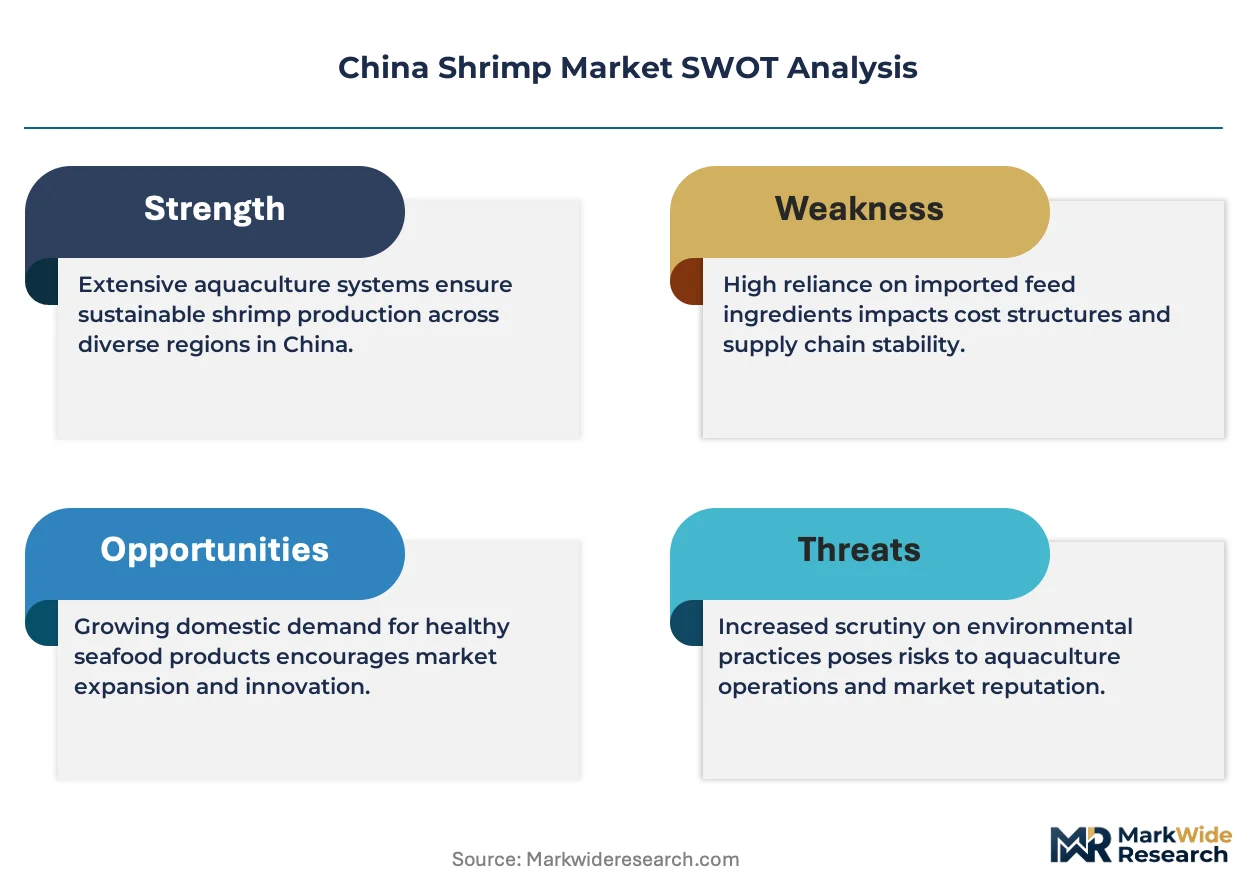
- Feed Cost Volatility:Soybean and fishmeal input prices fluctuate with South American harvest cycles, compressing margins for non-integrated pond operators in Fujian.
- Single-Origin Dependency Risk:Processing clusters remain concentrated in coastal provinces, exposing supply continuity to typhoon disruption and MEE wastewater enforcement actions.
- Species Substitution Pressure:Tilapia and pangasius fillets compete for frozen retail case space in tier-two cities, limiting shrimp volume expansion in price-sensitive channels.
Strategic Opportunities
- Western Province Penetration:Chengdu and Chongqing foodservice markets show underdeveloped cold-chain coverage, creating first-mover advantage for bonded-zone processors.
- Dual Carbon Tailwinds:MEE carbon intensity benchmarks for processing facilities reward solar-powered cold storage adopters with expedited environmental permitting.
- Live-Shrimp Channel Innovation:Same-day delivery platforms in Shanghai and Beijing are opening dedicated live-tank fulfillment centers, bypassing traditional wholesale wet markets.
Industry Challenges
- HACCP Certification Bottlenecks:Smaller processors in Zhejiang face extended audit timelines as SAMR inspector capacity lags behind facility expansion.
- Genetic Broodstock Access:Domestic hatcheries remain dependent on imported specific-pathogen-free vannamei broodstock, exposing supply to biosecurity trade restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Shrimp Market |
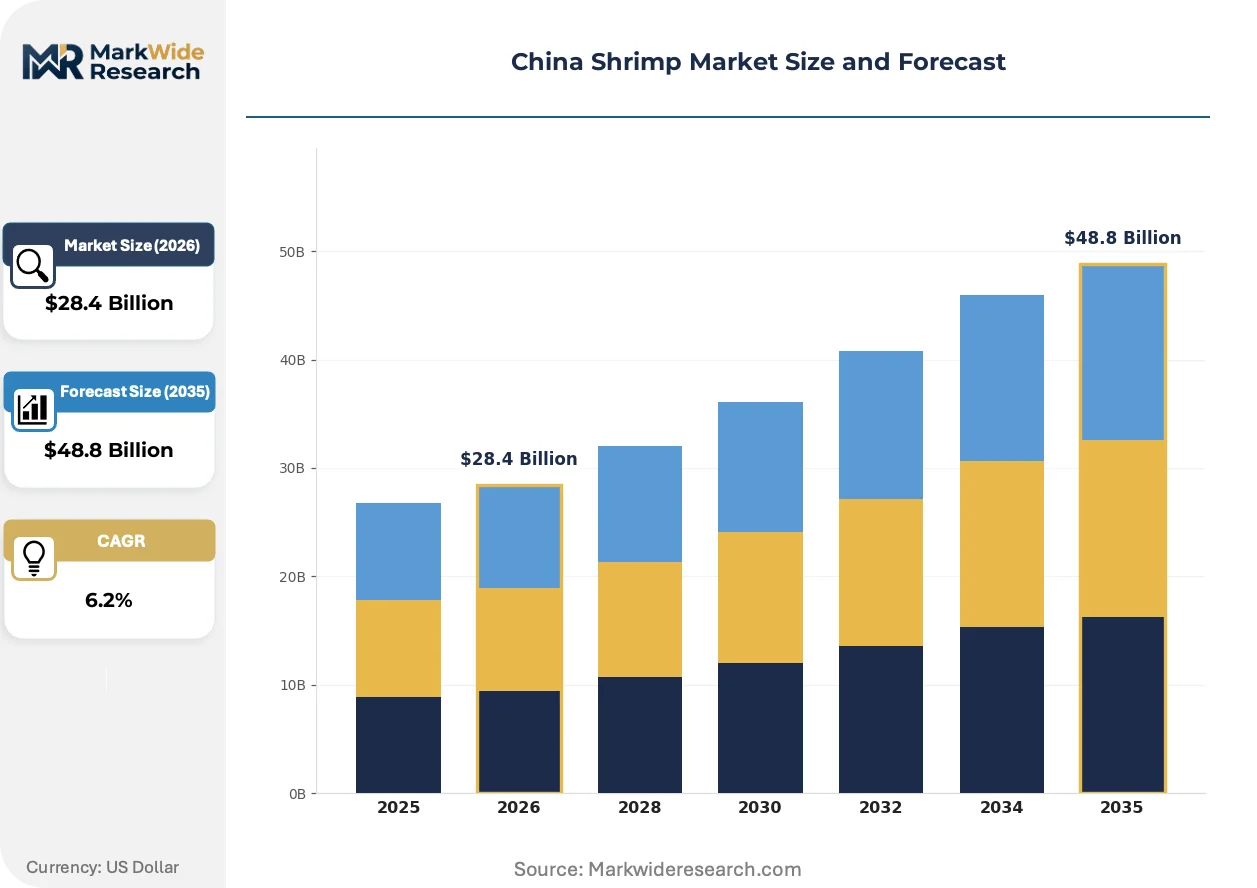
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $48.8 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Shrimp, Fresh Shrimp, Dried Shrimp, Cooked Shrimp Distribution Channel: Supermarkets, Online Retail, Fish Markets, Restaurants Size: Small Shrimp, Medium Shrimp, Large Shrimp, Jumbo Shrimp Quality Grade: Grade A, Grade B, Grade C, Others |
| Companies Covered | Surapon Foods, Mazzetta Company, Thai Union Group PCL, Nordic Seafood, Aqua Star, Avanti Feeds, Clearwater Seafoods, Waterbase, High Liner Foods, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Shrimp Market Strategic Shifts & Innovations
Digital traceability platforms and renewable cold-chain retrofits are converging to reshape how shrimp moves from pond to plate, with regulatory compliance becoming a competitive differentiator rather than a baseline cost.
Blockchain-enabled batch tracking is consolidating quality verification across multi-source supply chains. Major foodservice distributors in Guangzhou and Shenzhen are mandating farm-to-fork data integration for contracted suppliers. This technology compression is eliminating information asymmetry between importers and domestic pond operators, squeezing intermediaries who previously arbitraged quality opacity.
MEE wastewater discharge permits are tightening effluent standards for coastal processing belts. Facilities in Shandong must now install closed-loop water treatment or face production halts during audit periods. High-throughput exporters are responding by relocating secondary processing to inland bonded zones with lower environmental enforcement intensity.
Direct sourcing contracts between restaurant chains and single-origin farms are displacing traditional wholesale market purchasing in tier-one cities. Haidilao and similar operators now specify pond location and harvest date on menus. This traceability-driven preference shift is most visible in Beijing, where consumers pay measurable premiums for documented cold-chain integrity.
China Shrimp Market Segmentation
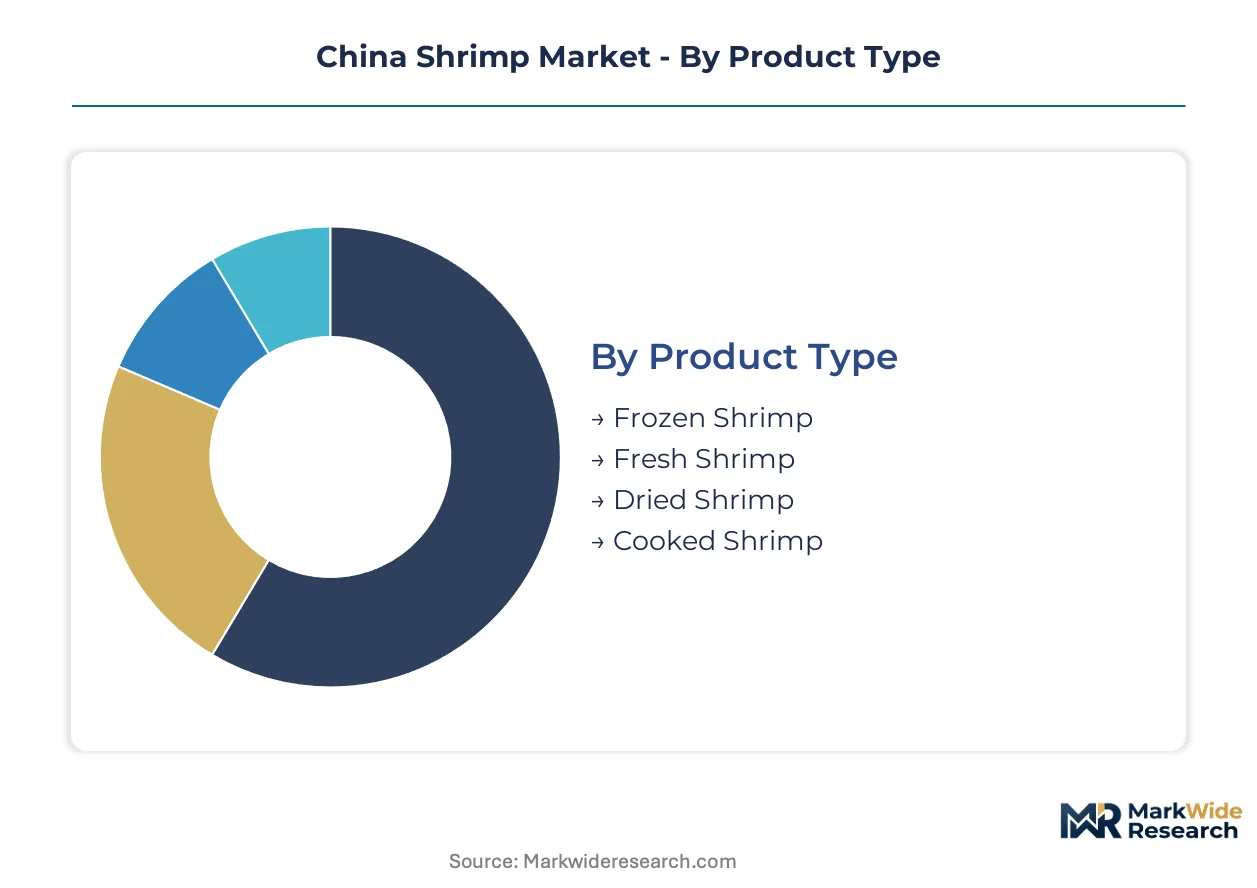
China shrimp procurement is fragmenting across product formats and channel tiers as foodservice buyers and retail platforms impose divergent handling specifications. SAMR traceability mandates and cold-chain maturity gaps are forcing suppliers to specialize rather than span all segments.
Product Type:
Upgrade cycles in processing technology and cold-chain infrastructure are reshaping which product formats capture margin versus volume in Chinese distribution.
- Frozen Shrimp:Individual quick-frozen (IQF) product dominates cross-province logistics due to shelf stability and HACCP compliance portability. Demand concentrates in Shandong and Guangdong processing clusters serving inland supermarket chains, constrained by MEE energy intensity benchmarks for blast freezing operations.
- Fresh Shrimp:Live or chilled product requires same-day delivery infrastructure and commands premium positioning in Beijing and Shanghai foodservice. Cold-chain gaps in western provinces limit penetration beyond tier-one city boundaries.
- Dried Shrimp:Traditional preservation format anchors ingredient supply for Cantonese and Fujianese restaurant kitchens, with volume concentrated in legacy wet market channels.
- Cooked Shrimp:Value-added ready-to-eat SKUs target convenience-oriented urban consumers through online retail platforms, constrained by shorter shelf windows and stricter SAMR labeling requirements.
Frozen shrimp sits at the top of the volume ranking, with cooked shrimp climbing the fastest as meal-prep habits penetrate tier-one cities.
Distribution Channel:
Cost tier stratification across channel types determines which suppliers can absorb compliance overhead versus competing on price.
- Supermarkets:Branded packaged shrimp with full GB labeling compliance and barcode traceability, concentrated in Carrefour and RT-Mart systems across Yangtze River Delta cities.
- Online Retail:Direct-to-consumer platforms including Freshippo and JD Fresh are expanding fastest, leveraging bonded-zone cold storage for imported product and same-day delivery promises.
- Fish Markets:Traditional wholesale wet markets in Guangzhou and Qingdao remain volume anchors for restaurant procurement, though SAMR hygiene enforcement is thinning operator counts.
- Restaurants:Direct contracting between chain operators and certified processors is displacing spot-market purchasing, with Haidilao and similar brands specifying pond origin documentation.
Online retail is expanding most quickly, while fish markets retain the largest transaction volume base.
Size:
Application-driven demand patterns split the size spectrum between foodservice portion control and retail value perception.
- Small Shrimp:20-30 count per pound product serves dumpling filling and processed food manufacturing, concentrated in Shandong frozen processing for export reprocessing.
- Medium Shrimp:30-40 count standard for hotpot and stir-fry applications across mid-tier restaurant chains, with volume concentrated in Pearl River Delta distribution.
- Large Shrimp:20-25 count product commands premium positioning in shell-on grilling applications, with demand clustering in Shenzhen and Beijing high-end foodservice.
- Jumbo Shrimp:15 count and below product targets banquet service and gift packaging, constrained by limited domestic pond yield and import dependency for consistent supply.
Medium shrimp holds the volume lead, with jumbo shrimp gaining share fastest as premium foodservice expands.
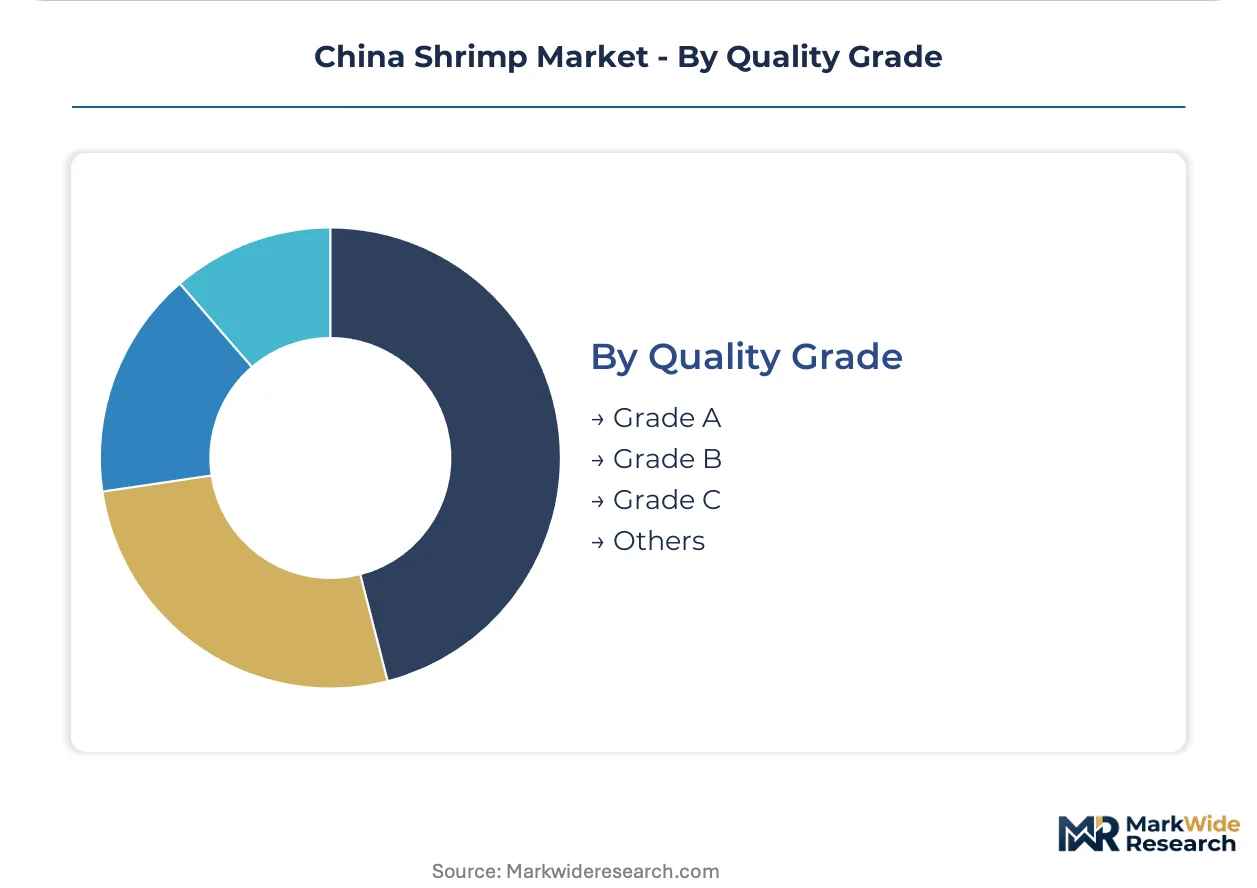
Quality Grade:
Margin concentration and certification burden separate grade tiers, with SAMR residue testing creating enforceable quality boundaries.
- Grade A:Specific-pathogen-free certification, antibiotic-free documentation, and full cold-chain traceability for export-qualified and tier-one city premium channels, concentrated in integrated Thai Union and Clearwater supply contracts.
- Grade B:Domestic GB-compliant product with standard HACCP processing for mainstream retail and restaurant chains, representing the volume core of Shandong and Fujian processing output.
- Grade C:Basic safety-compliant product for price-sensitive secondary city markets and institutional catering, facing margin compression from feed cost volatility.
- Others:Ungraded or commodity auction product for processing into surimi and feed inputs, concentrated in spot-market coastal trading.
Grade B product dominates transaction volume, with Grade A expanding most steeply as traceability premiums harden in Beijing and Shanghai.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coastal processing clusters are migrating inland to exploit compliance-cost arbitrage, as MEE wastewater enforcement tightens effluent standards in traditional production belts while bonded zones in western provinces offer expedited permitting.
Guangdong Province
Foodservice premiumization and live-shrimp logistics dominate demand in Shenzhen and Guangzhou. SAMR hygiene enforcement is thinning wet market operator counts in the Pearl River Delta. Processing capacity concentrates in Zhanjiang and Shantou, where integrated exporters are retrofitting solar-powered cold storage to meet dual carbon benchmarks.
Shandong Province
Frozen shrimp exports and supermarket supply chains anchor volume demand across Qingdao and Yantai. GB standards compliance costs are filtering out subscale pond operators in the Jiaodong Peninsula. The Weihai processing cluster is consolidating among HACCP-certified facilities capable of cross-province supermarket distribution.
Fujian Province
Feed-to-farm integration and medium-size shrimp portioning serve hotpot chain procurement from Xiamen and Fuzhou. MEE coastal discharge permits are forcing secondary processing relocation to inland bonded zones. The Ningde aquaculture belt is specializing in broodstock hatchery supply for domestic vannamei production.
Sichuan-Chongqing
Hotpot restaurant expansion and underdeveloped cold-chain coverage create first-mover opportunities in Chengdu and Chongqing foodservice. Provincial infrastructure subsidies are attracting bonded-zone processors to western logistics hubs. Same-day delivery platforms are piloting live-tank fulfillment centers to bypass traditional wholesale markets.
Jiangsu Province
Yangtze River Delta supermarket chains and online retail platforms drive branded packaged shrimp demand through Nanjing and Suzhou. SAMR traceability mandates are mandating barcode integration for Carrefour and RT-Mart suppliers. The Nantong processing corridor is specializing in IQF product for inland distribution.
China Shrimp Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue traceability-certified premium positioning through direct restaurant contracting. The vendor base splits between integrated aquaculture-to-processing operators and specialized cold-chain distributors. Three archetypes dominate: Southeast Asian supply-integrated multinationals, Arctic-cold chain specialists, and domestic feed-to-farm integrators. Capacity expansion and backward integration into hatchery control represent the dominant competitive vectors.
Among Thailand-based supply-integrated operators, Thai Union Group PCL anchors the multinational archetype with pond-to-port control. Clearwater Seafoods exemplifies the Arctic-cold chain specialist tier through premium shell-on positioning. Avanti Feeds occupies the feed-to-farm integration archetype, controlling input costs for producers serving export and domestic channels alike.
| Leading Market Players |
|---|
| Surapon Foods |
| Mazzetta Company |
| Thai Union Group PCL |
| Nordic Seafood |
| Aqua Star |
| Avanti Feeds |
| Clearwater Seafoods |
| Waterbase |
| High Liner Foods |
| Others |
Cost & Logistics Intelligence
Family-owned pond operators across Fujian and Guangdong provinces anchor production volume, yet their fragmented ownership limits collective bargaining power against feed suppliers and concentrates margin compression among non-integrated processors. SAMR residue enforcement and MEE wastewater standards are forcing capital expenditure that smaller operators cannot absorb, accelerating consolidation toward Thai Union and Clearwater contract structures where pricing discipline aligns with certified cold-chain investment.
Pricing Analysis
Retailer markup layers dominate final price formation, with RT-Mart and Carrefour systems extracting margin for barcode traceability and GB-compliant labeling that wet market channels bypass. Three-tier pricing structure across Grade A certified, Grade B standard, and Grade C commodity product reflects certification burden and cold-chain integrity rather than species differentiation alone. Cost compression in Grade C tiers is intensifying because soybean and fishmeal input volatility transmits directly to non-integrated pond operators. Price-sensitive institutional catering and secondary city wet markets absorb Grade C volume, while Beijing and Shanghai foodservice buyers show lowest sensitivity for documented pond-origin product.
Supply Chain Analysis
Broodstock supply rests on specific-pathogen-free vannamei imports from Hawaii and Florida hatcheries, exposing domestic production to biosecurity trade restrictions that disrupt spawning cycles. Feed formulation draws from South American soybean meal and Peruvian fishmeal, with Thai and Vietnamese processors competing for the same input pools. Single-source vulnerability in genetic stock creates propagation risk that domestic hatcheries cannot yet mitigate. Distribution runs through bonded-zone cold storage in Qingdao and Zhanjiang, with same-day delivery platforms bypassing traditional wholesale layers in tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China shrimp operates as a regulatory compounder where SAMR GB standards enforcement and MEE dual carbon mandates are accelerating demand for certified, traceable supply that commands premium positioning. Compliance investment is becoming the primary margin determinant across all procurement channels.
For Market Incumbents: Hedge against feed cost volatility through backward integration into hatchery control or long-term offtake contracts with Southeast Asian suppliers. Defensive consolidation around HACCP-certified processing capacity in Shandong and Guangdong protects against SAMR inspector capacity bottlenecks that delay competitor facility approvals. Channel control through direct restaurant contracting with Haidilao-tier operators insulates against spot-market price erosion.
For New Entrants and Emerging Players: Capture underdeveloped cold-chain coverage in Chengdu and Chongqing foodservice markets where bonded-zone processing infrastructure attracts provincial subsidy. Live-shrimp same-day delivery platforms represent the most penetrable channel innovation, with dedicated tank fulfillment centers bypassing legacy wholesale structures. Go-to-market positioning should anchor on traceability certification that commands measurable premiums in western province expansion.
For Investors and Strategic Acquirers: Valuations sit cheapest among subscale Fujian pond operators facing MEE wastewater compliance deadlines and SAMR residue enforcement actions. Long-term viability over the projection horizon favors integrated aquaculture-to-processing footprints with captive broodstock access and renewable cold-chain infrastructure. Watch for biosecurity trade restrictions on imported SPF vannamei broodstock as the inflection signal that revalues domestic hatchery capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Hatchery Backward Integration | Captive SPF broodstock supply insulates production from import restriction volatility. |
| Renewable Cold-Chain Retrofit | Solar-powered storage secures MEE expedited permitting for facility expansion. |
| Direct Restaurant Contracting | Pond-origin documentation commands premium positioning in Beijing and Shanghai foodservice. |
| Western Province Bonded-Zone Entry | Chengdu and Chongqing infrastructure subsidies reduce compliance-cost burden versus coastal belts. |
| Blockchain Traceability Deployment | Farm-to-fork data integration meets Freshippo and JD Fresh supplier mandates. |
Research Approach
Bottom-up foodservice and retail channel modeling reconciled against top-down import and domestic production tracking forms the analytical core of this study. Primary interviews with aquaculture farm managers, cold-chain logistics operators, restaurant procurement directors, and SAMR compliance officers combined with secondary validation from customs trade records, GB standards filings, MEE discharge permit databases, and supermarket chain supplier disclosures. Triangulation across pond-level yield estimates and port-of-entry inspection volume data ensures supply-side coverage integrity.
Historical trendline analysis of processing capacity expansion, cold-chain infrastructure deployment, and certification adoption rates informed the projection framework across the analysis window. Segmentation dimensions modeled include product format, quality grade, distribution channel, and regional cold-chain maturity. CAGRs were derived from weighted growth contributions across these segments, with feed cost indices and regulatory enforcement intensity schedules serving as key forecast inputs.
Feed commodity price spikes, biosecurity trade restrictions on broodstock imports, and MEE enforcement intensity variation across provincial jurisdictions are the dominant revision risks to modeled outcomes. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Ornamental Tropical Fish Feed Market
Aquaculture Innovations
Global Aquaculture Vaccine Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Perch Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
Europe Organic Aquaculture Market
Aquaculture Innovations
Sandfish Market
Aquaculture Innovations
Clams, Cockles, Ark Shells Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Aquaculture Additives Market