
 Egypt Aquafeed Market | 2026-2036
Egypt Aquafeed Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Aquafeed Market Intelligence
Premium protein specification tiers is collapsing the gap between commodity and performance feeds across Egyptian aquaculture zones. Skretting Egypt leverages its marine research station in Suez to develop species-specific formulations for Mediterranean seabass. BioMar sustains a competitive position through its concentrated production footprint near Damietta, reducing logistics costs for Delta-based farms. Grand Group for Fish Feed Manufacturing dominates the domestic mid-tier segment with grain-forward formulations tailored to local tilapia genetics.
Egypt aquafeed denotes nutritionally complete compounded diets formulated from fish meal, soybean meal, wheat bran, and vitamin-mineral premixes, extruded or pelleted to specified water stability and protein digestibility coefficients for intensive pond and cage systems. Fish feed occupies the dominant volume position given tilapia's national production supremacy, while shrimp feed represents the fastest-expanding margin pool as brackwater operations expand along the Red Sea coast. Ingredient-type segmentation reveals grain products anchoring cost structures, though plant-based substitution is accelerating as fish meal import costs pressure formulation economics.
The General Organization for Veterinary Services enforces feed safety protocols through factory inspection regimes and mycotoxin threshold monitoring, while the Ministry of Agriculture and Land Reclamation administers aquaculture licensing that predicates farm establishment on verified feed sourcing. The Egyptian Organization for Standardization and Quality adopts ISO-compliant nutritional labeling mandates that restrict market access for unregistered imports. Stakeholders must monitor how the Central Agency for Public Mobilization and Statistics expands production data collection requirements, as compliance costs will reshape competitive economics for smaller independent mills.
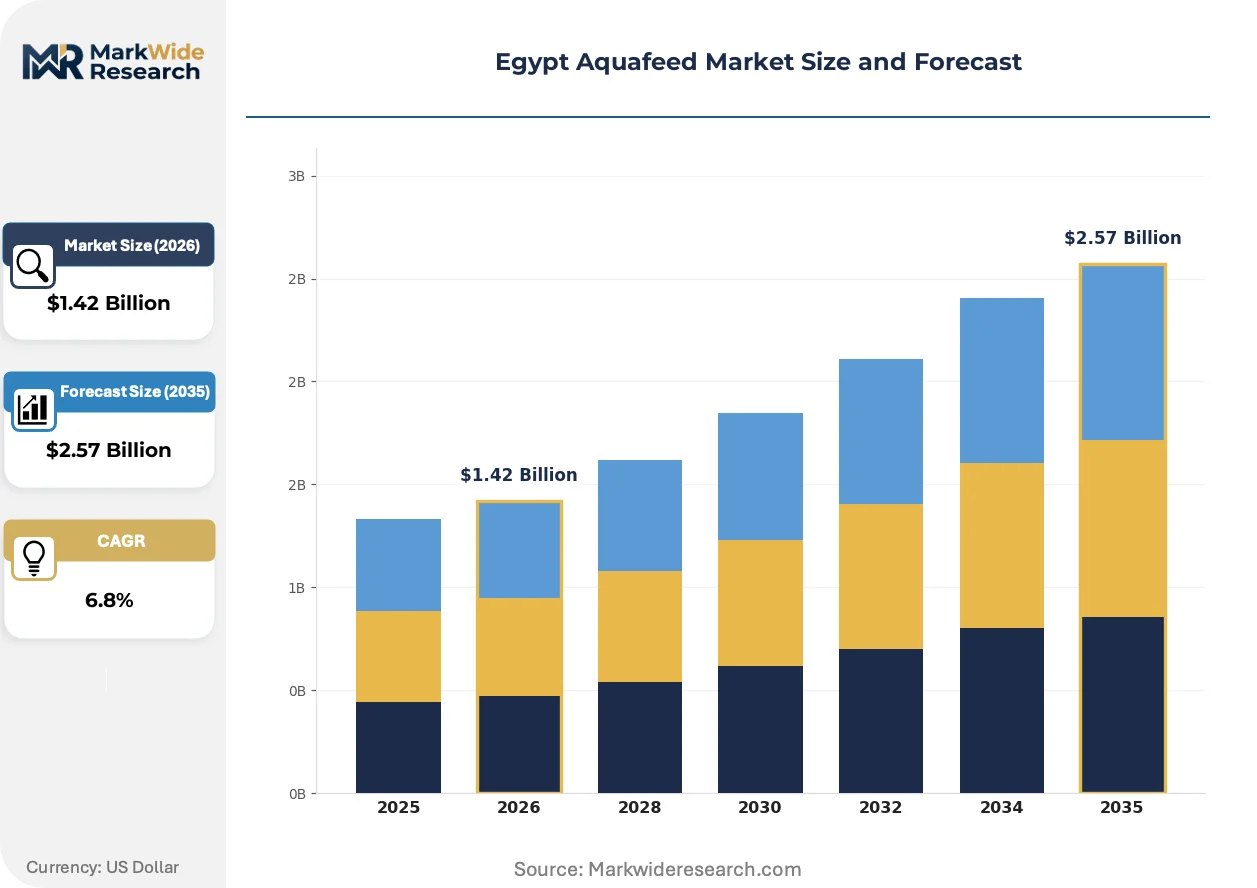
Market Dynamics
Ingredient substitution economics and traceability mandates from the Central Agency for Public Mobilization and Statistics are compressing formulation margins while forcing capital deployment into digital supply chain infrastructure across Egyptian aquafeed manufacturing.
Growth Catalysts
- Government hatchery expansion:Ministry of Agriculture and Land Reclamation subsidized broodstock programs in Kafr El-Sheikh Governorate are expanding tilapia seed supply, directly lifting feed offtake from contracted pond clusters.
- ISO-compliant labeling mandates:Egyptian Organization for Standardization and Quality nutritional disclosure rules are filtering out unregistered imports, clearing shelf space for compliant domestic producers.
- Brackwater shrimp farming:Red Sea coastal salinity-tolerant operations are diversifying species mix beyond tilapia dominance, creating demand for specialized high-protein formulations.
Market Restraints
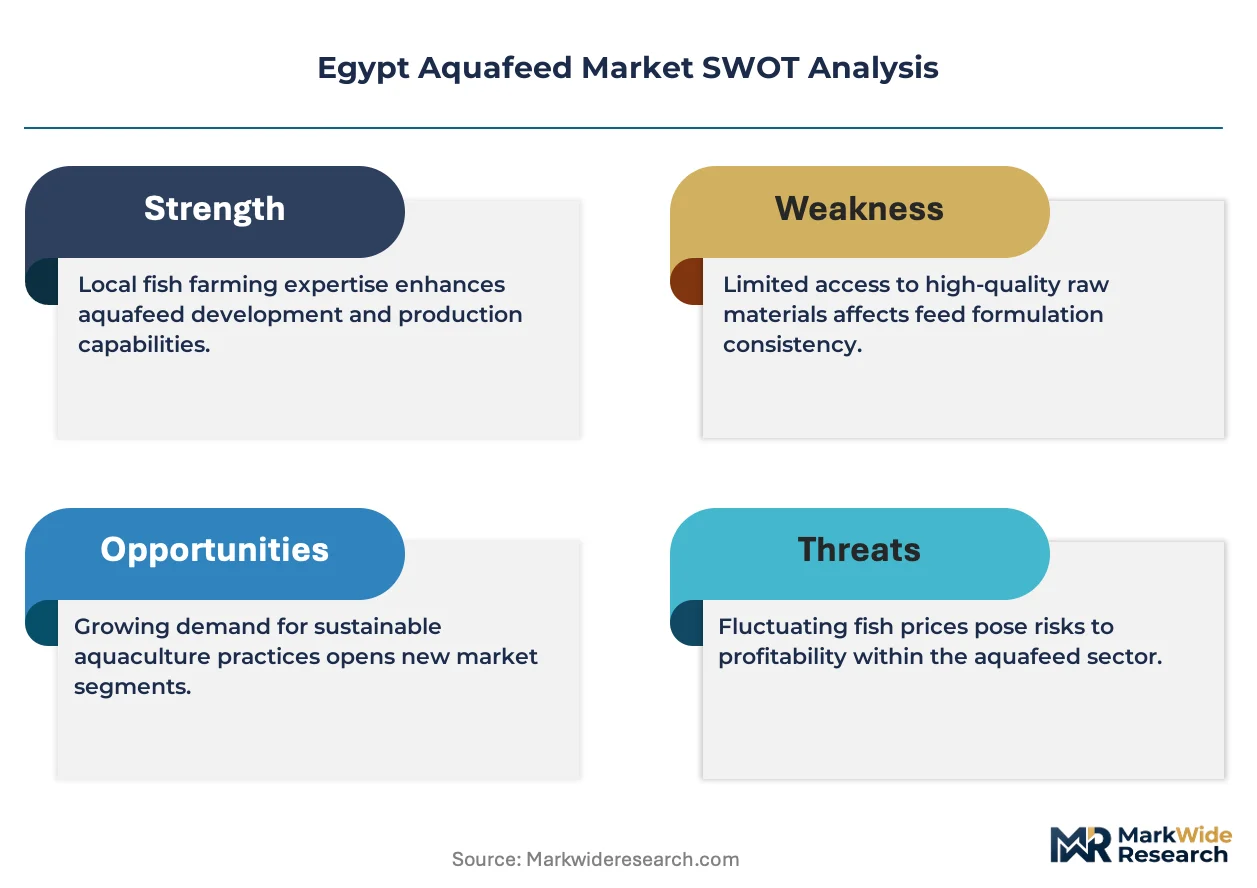
- Fish meal import cost volatility:Dollar-denominated marine protein sourcing exposes mills to exchange rate swings that destabilize margin structures on performance-tier feeds.
- Delta logistics concentration:Damietta-to-Kafr El-Sheikh corridor bottlenecks create single-point failure risk for just-in-time delivery to intensive pond systems.
- Wheat bran quality inconsistency:Local grain milling byproduct variability forces over-formulation to hit protein guarantees, inflating raw material burn rates.
Strategic Opportunities
- Mediterranean seabass cage expansion:Suez Canal zone marine finfish operations offer premium feed margin capture for species-specific extruded diets with enhanced water stability.
- Plant-protein convergence:Fermented soybean meal and insect meal processing investments can displace marine ingredients while satisfying General Organization for Veterinary Services safety protocols.
- Direct farm contracting:Bypassing distributor layers through mill-to-pond volume agreements reduces working capital cycles and locks in offtake visibility.
Industry Challenges
- Traceability system integration:Central Agency for Public Mobilization and Statistics data reporting upgrades demand ERP overhauls that strain smaller independent mill technical capacity.
- Formulation chemist scarcity:Specialized aquatic nutrition expertise concentrates at multinational R&D stations, constraining domestic mid-tier product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Aquafeed Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Feed, Shrimp Feed, Mollusk Feed, Specialty Feed Ingredient Type: Plant-Based, Animal By-Products, Fish Meal, Grain Products End User: Aquaculture Farms, Feed Mills, Research Institutions, Traders Distribution Channel: Online Retail, Wholesale, Direct Sales, Distributors |
| Companies Covered | Nutreco, Aquavet Egypt, Skretting Egypt, Coppens International, BioMar, Grand Group for Fish Feed Manufacturing, Zeigler Feed, Alltech, AQUA GROUP Egypt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Aquafeed Market Strategic Shifts & Innovations
Extrusion technology advances and regulatory data mandates are reshaping how Egyptian mills balance cost structures against performance specifications in a market tilting toward species-specific nutrition.
Single-screw extruder retrofits with enhanced starch gelatinization control are displacing conventional pelleting lines in Delta-based facilities serving intensive tilapia operations. Feed compounders adopting these systems report improved pellet durability indices that reduce pond waste ratios. The capital transition is compressing equipment supplier lead times while elevating technical service expectations.
Egyptian Organization for Standardization and Quality ISO-aligned nutritional labeling enforcement is compelling reformulation transparency across all registered feed categories. Mills must now disclose digestible amino acid profiles rather than crude protein proxies, altering competitive positioning between commodity and performance tiers. Smaller domestic manufacturers face compliance timeline pressure that favors integrated quality management investments.
Farm procurement consolidation through cooperative buying groups is aggregating volume leverage previously fragmented across individual pond operators. These collectives in Kafr El-Sheikh and Damietta governorates negotiate direct mill contracts with payment term extensions that strain independent distributor economics. Channel restructuring is most advanced where government hatchery affiliation creates pre-qualified supplier shortlists.
Egypt Aquafeed Market Segmentation
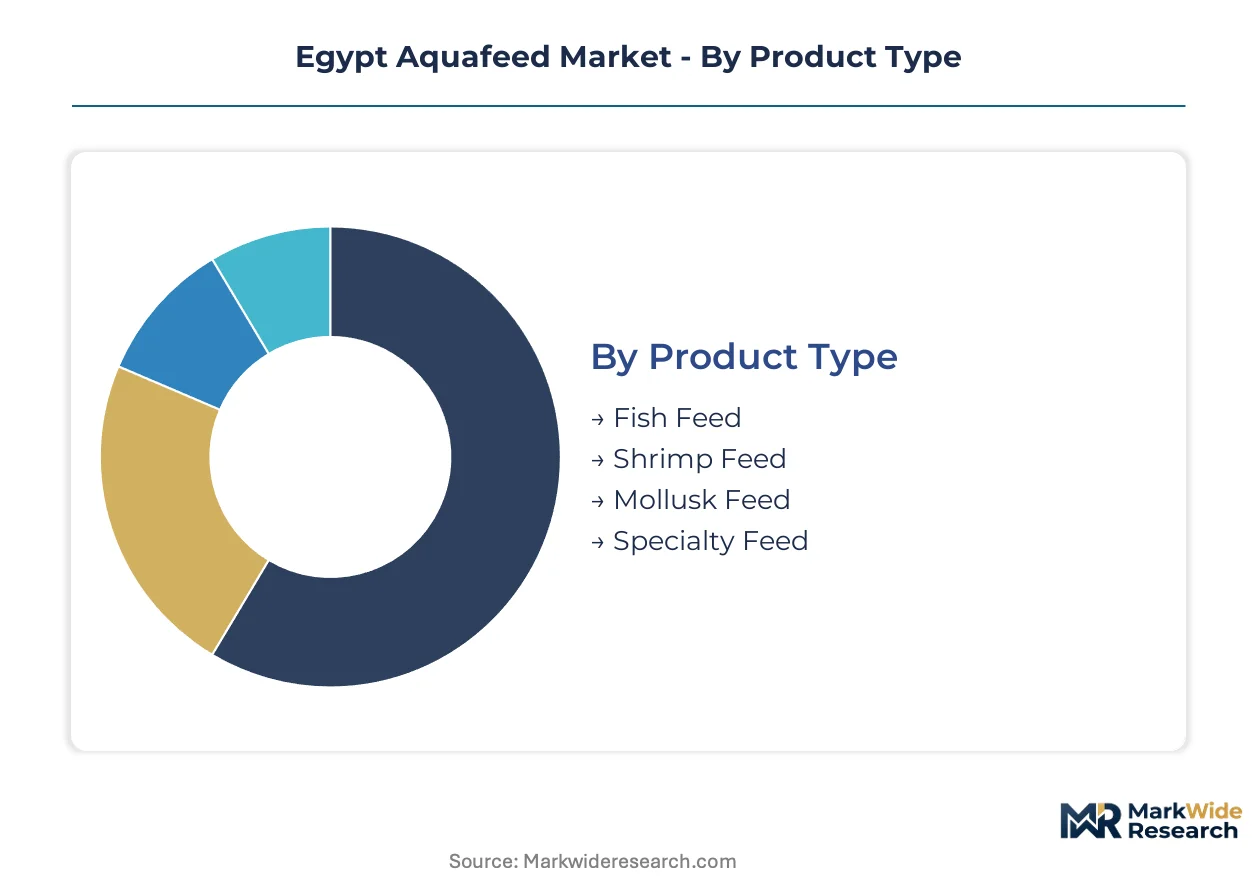
Egyptian aquafeed segmentation reflects regulatory pressure on formulation transparency and species-specific nutrition mandates from the General Organization for Veterinary Services. Distinct product tiers, ingredient sourcing strategies, and channel structures create divergent margin profiles across the Nile Delta and Red Sea production zones.
Product Type:
The General Organization for Veterinary Services enforces differentiated mycotoxin thresholds and water stability standards across aquatic species categories, elevating compliance costs for specialty formulations versus commodity tilapia diets.
- Fish Feed:Nutritionally complete extruded or pelleted diets formulated from fish meal, soybean meal, and wheat bran for intensive tilapia pond and cage systems. Kafr El-Sheikh Governorate clusters consume the majority of volumes as government hatchery expansion lifts seed supply and contracted feed offtake.
- Shrimp Feed:High-protein formulations with enhanced amino acid density for brackwater salinity-tolerant operations along the Red Sea coast. Brackwater farming diversification beyond tilapia dominance creates specialized formulation demand that carries premium margin structures.
- Mollusk Feed:Microalgae-supplemented diets for bivalve hatchery operations with strict particle size specifications.
- Specialty Feed:Species-specific extruded diets for Mediterranean seabass cage systems in the Suez Canal zone.
Established volume favors fish feed; emerging adoption favors shrimp feed.
Ingredient Type:
Cost tier differentiation separates commodity grain-based formulations from performance-tier marine protein diets, with dollar-denominated fish meal imports compressing mid-tier margin structures.
- Grain Products:Wheat bran and corn byproducts anchor cost structures across domestic mid-tier manufacturing. Local milling variability forces over-formulation to hit protein guarantees, inflating raw material burn rates at Grand Group for Fish Feed Manufacturing and similar producers.
- Plant-Based:Fermented soybean meal and insect meal processing investments displace marine ingredients while satisfying General Organization for Veterinary Services safety protocols. Substitution economics accelerate as import cost volatility pressures formulation decisions.
- Fish Meal:Dollar-denominated marine protein sourcing exposes mills to exchange rate swings that destabilize performance-tier feed margins.
- Animal By-Products:Poultry meal and rendered proteins with restricted application under ISO-compliant labeling mandates.
Cost concentration sits with grain products; margin expansion potential sits with plant-based alternatives.
End User:
Customer type determines procurement scale, with cooperative buying groups aggregating previously fragmented pond operator volumes.
- Aquaculture Farms:Intensive pond and cage operators in Kafr El-Sheikh and Damietta governorates negotiating direct mill contracts with extended payment terms.
- Feed Mills:Compounding facilities requiring traceability system upgrades to meet Central Agency for Public Mobilization and Statistics data reporting mandates.
- Traders:Independent distributors facing margin compression as farm collectives bypass traditional channel layers.
- Research Institutions:Skretting Egypt's marine research station in Suez and academic partners driving species-specific formulation development.
Volume leverage concentrates at aquaculture farms; technical service demand concentrates at feed mills.
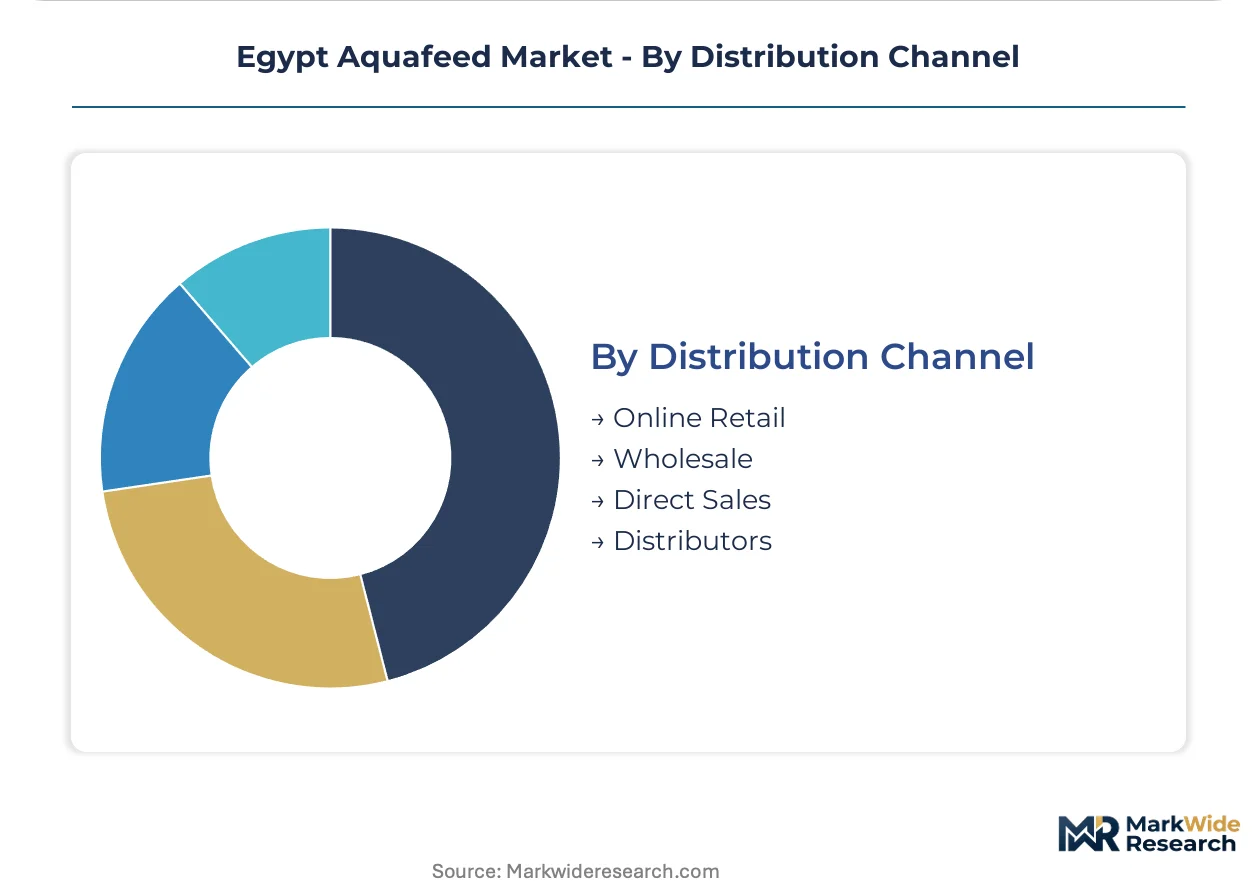
Distribution Channel:
Channel structure reflects logistics concentration risk along the Damietta-to-Kafr El-Sheikh corridor.
- Direct Sales:Mill-to-pond volume agreements reducing working capital cycles and locking in offtake visibility for intensive operations.
- Distributors:Traditional layer facing strain from cooperative buying group consolidation and payment term extensions.
- Wholesale:Aggregated supply for smaller independent pond operators without hatchery affiliation.
- Online Retail:Emerging trace for specialty additives and premixes with documented ISO-compliant nutritional labeling.
Channel power shifts toward direct sales; wholesale retains fragmented farm access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed buyers in Kafr El-Sheikh Governorate display acute price sensitivity to wheat bran fluctuations, while Mediterranean seabass operators near Suez absorb premium formulation costs with minimal volume elasticity.
Kafr El-Sheikh Governorate
Intensive tilapia pond clusters drive concentrated feed offtake as government hatchery subsidies expand seed supply. The Ministry of Agriculture and Land Reclamation predicates farm licensing on verified feed sourcing from registered mills. Damietta-to-Kafr El-Sheikh corridor logistics concentrate delivery infrastructure, creating single-point failure risk during peak stocking seasons.
Damietta Governorate
Coastal cage systems and processing infrastructure anchor compound feed demand for export-oriented production. BioMar maintains production proximity here to reduce logistics costs for Delta-based farms. Factory inspection regimes from the General Organization for Veterinary Services enforce mycotoxin thresholds that elevate compliance investments for local mills.
Suez Governorate
Mediterranean seabass cage operations in the Suez Canal zone command premium margins for species-specific extruded diets with enhanced water stability. Skretting Egypt leverages its marine research station here to develop high-performance formulations. The Central Agency for Public Mobilization and Statistics tightened aquaculture data reporting requirements, compelling traceability system upgrades across regional supply chains.
Red Sea Coastal Zone
Brackwater shrimp farming operations diversify species mix beyond tilapia dominance, generating demand for specialized high-protein formulations. Salinity-tolerant production systems carry premium margin structures relative to freshwater pond economics. Grand Group for Fish Feed Manufacturing and domestic mid-tier suppliers compete for offtake from expanding coastal farm clusters.
Nile Delta Periphery
Fragmented independent pond operators aggregate through cooperative buying groups to negotiate direct mill contracts with extended payment terms. ISO-compliant nutritional labeling mandates from the Egyptian Organization for Standardization and Quality filter out unregistered imports, clearing procurement pathways for compliant domestic producers. Channel restructuring bypasses traditional distributor layers, compressing intermediary economics.
Egypt Aquafeed Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Egyptian aquafeed sector. Multinational compounders with dedicated R&D stations command formulation expertise and species-specific development velocity, while domestic grain-forward manufacturers anchor cost structures through localized ingredient sourcing. Three archetypes define competitive positioning: integrated nutrition multinationals, regional production specialists, and domestic mid-tier formulators. Capacity expansion and direct farm contracting represent the dominant competitive moves as mills seek offtake visibility and distributor bypass.
Within the multinational tier, Skretting Egypt and BioMar occupy positions defined by marine research infrastructure and concentrated production footprints respectively. Nutreco represents the integrated nutrition archetype through its global formulation capabilities adapted to regional species requirements. Among domestic manufacturers, Grand Group for Fish Feed Manufacturing exemplifies the grain-forward mid-tier segment with formulations tailored to local tilapia genetics. These named entities anchor industry structure without exhaustively mapping competitive dynamics.
| Leading Market Players |
|---|
| Nutreco |
| Aquavet Egypt |
| Skretting Egypt |
| Coppens International |
| BioMar |
| Grand Group for Fish Feed Manufacturing |
| Zeigler Feed |
| Alltech |
| AQUA GROUP Egypt |
| Others |
Cost & Logistics Intelligence
Fermented soybean meal displacement of fish meal is redrawing raw material sourcing maps across Egyptian aquafeed manufacturing while compressing formulation economics at performance-tier price points. This substitution dynamic simultaneously concentrates procurement leverage among Delta-based grain processors and erodes margin buffers for mills dependent on dollar-denominated marine protein imports.
Pricing Analysis
Technical service contracts and formulation consulting fees anchor lifetime value capture for multinational compounders serving Mediterranean seabass operators near Suez. Three-tier pricing structure across premium, standard, and economy levels separates species-specific extruded diets from commodity tilapia pellets and grain-forward mid-tier formulations. Cost compression in the standard tier is intensifying because wheat bran quality inconsistency forces over-formulation to hit protein guarantees. Cooperative buying groups in Kafr El-Sheikh display acute price sensitivity to grain fluctuations, while Red Sea shrimp farms absorb premium formulations with minimal volume elasticity.
Supply Chain Analysis
Strategic stockpiling of fish meal and soybean meal dominates inventory strategy among Egyptian mills seeking to buffer exchange rate volatility and seasonal import disruptions. Raw material sourcing draws from Argentina and Brazil for soybean derivatives, Peru and Chile for marine protein, and domestic Delta milling operations for wheat bran. Single-source vulnerability concentrates in the Damietta-to-Kafr El-Sheikh logistics corridor, where corridor bottlenecks create delivery failure risk during peak stocking seasons. Distribution runs through direct mill-to-pond volume agreements for intensive operations, with wholesale channels retaining access to fragmented independent pond operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egyptian aquafeed fragmentation creates niche capture opportunities as species diversification beyond tilapia demands specialized formulation capabilities that mid-tier domestic mills struggle to deliver.
For Market Incumbents: Fortify traceability infrastructure ahead of Central Agency for Public Mobilization and Statistics data reporting expansions that will disqualify non-compliant suppliers from government hatchery-affiliated procurement. Deepen backward integration into fermented soybean meal processing to reduce exposure to dollar-denominated fish meal volatility while satisfying General Organization for Veterinary Services safety protocols. For New Entrants and Emerging Players: Egyptian Organization for Standardization and Quality ISO-compliant certification fast-track offers market entry pathway through nutritional labeling transparency that filters out unregistered imports. Target Red Sea coastal brackwater shrimp operations with high-protein formulations carrying premium margin structures unavailable in commoditized tilapia segments. Pursue direct farm contracting with cooperative buying groups to bypass distributor layers and secure payment term extensions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with domestic mid-tier formulators like Grand Group for Fish Feed Manufacturing that lack technical capacity for traceability system upgrades but hold established Delta customer relationships. Five-to-ten year viability hinges on plant-protein substitution economics displacing marine ingredients at scale. Monitor Central Agency for Public Mobilization and Statistics compliance timeline enforcement as inflection indicator for consolidation pressure on independent mills.| Strategic Initiative | Industry Significance |
|---|---|
| Traceability System Integration | Central Agency for Public Mobilization and Statistics mandates compel ERP overhauls that reshape competitive economics for smaller mills. |
| Plant-Protein Processing Investment | Fermented soybean meal and insect meal facilities displace dollar-denominated fish meal while satisfying General Organization for Veterinary Services protocols. |
| Direct Farm Contracting | Mill-to-pond volume agreements reduce working capital cycles and lock in offtake visibility from Kafr El-Sheikh cooperative buying groups. |
| Species-Specific R&D Station Expansion | Skretting Egypt's marine research station in Suez demonstrates premium margin capture through Mediterranean seabass formulation development. |
| Backward Integration into Grain Milling | Captive wheat bran supply stabilizes input quality and reduces over-formulation burn rates at domestic mid-tier manufacturers. |
Research Approach
Desk research of Egyptian Organization for Standardization and Quality regulatory filings, Ministry of Agriculture and Land Reclamation licensing records, and Central Agency for Public Mobilization and Statistics aquaculture production databases preceded structured interviews with feed mill operations managers, aquaculture farm procurement heads, and General Organization for Veterinary Services inspection officers. Primary fieldwork with Delta-based cooperative buying groups and Red Sea coastal shrimp farm operators combined with secondary validation against trade customs data and industry association publications. Bottom-up volume aggregation across governorates triangulated against top-down market sizing from registered mill capacity declarations.
Variance decomposition across the projection horizon isolates volume drivers from price effects within each product and ingredient segment. Segmentation dimensions modeled include species category, protein specification tier, sourcing strategy, and regional production cluster. CAGRs derive from trend extrapolation of hatchery expansion programs, brackwater farm development permits, and substitution elasticity estimates for plant-based ingredients. Forecast inputs incorporate General Organization for Veterinary Services mycotoxin threshold enforcement timelines and exchange rate scenarios affecting dollar-denominated marine protein imports.
Decision-makers should treat outputs as directional under assumptions of continued government hatchery subsidy continuity and ISO-compliant labeling mandate enforcement; material deviation would warrant model refresh. Revision becomes warranted when fish meal import cost volatility or traceability compliance timeline acceleration crosses thresholds that reshape mill competitive economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Crab Market
Aquaculture Innovations
Aquaponics Market
Aquaculture Innovations
Fish Farming Equipment Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
Bacterial Diagnostics in Aquaculture Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
North America Shrimp Feed Market
Aquaculture Innovations
Aquaculture Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market