
 Global Forage Seeds Market | 2026-2036
Global Forage Seeds Market Size, Share, and Industry Trends Forecast 2026-2036
Global Forage Seeds Market Analysis
Commodity seed trading margins is narrowing as breeders shift toward proprietary trait licensing and direct-to-farmer distribution. DLF Seeds A/S leverages its European breeding network to dominate perennial ryegrass development. Corteva Inc. anchors its position through transgenic alfalfa traits and integrated crop protection bundles. Bayer AG competes via its corn silage genetics pipeline and digital agronomy platforms tied to seed prescriptions.
Forage seeds are reproductive plant materials cultivated specifically for animal feed production, erosion management, and soil rehabilitation, typically selected for crude protein content, fiber digestibility, and regional climate adaptation through open-pollinated or hybrid breeding programs. Grass seeds occupy the largest volume share due to established pasture renewal cycles across temperate grazing systems. Legume seeds represent the fastest-expanding category as nitrogen-fixing varieties reduce synthetic fertilizer dependency. Coated seeds capture expanding margin pools where polymer and rhizobia inoculant treatments command premium pricing over raw seed forms.
The USDA regulates forage seed certification through official seed testing protocols, while the EU Green Deal and REACH frameworks constrain chemical treatment options and mandate traceability in seed coatings. Brazil's national agricultural regulator enforces phytosanitary standards on imported germplasm that shape supplier market access. Stakeholders must monitor evolving carbon accounting methodologies that could revalue legume-based rotations against pure grass systems.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing synthetic input dependency across temperate pasture systems, forcing nitrogen-fixing legume varieties into rotation cycles previously dominated by pure grass monocultures. Breeders now face simultaneous pressure from sustainability mandates and rancher demand for digestibility metrics.
Growth Catalysts
- EU Green Deal nitrogen mandates:Brussels' Farm to Fork targets for synthetic fertilizer reduction create compulsory pull-through for clover and alfalfa rotations across French and German dairy operations.
- Brazilian pasture reconstruction:Ranchers in Mato Grosso and Goiás are replanting degraded grazing lands with drought-tolerant brachiaria hybrids following consecutive El Niño dry cycles.
- Precision inoculant coating:Polymer-encapsulated rhizobia treatments are raising germination rates in marginal soils, expanding addressable acreage for legume establishment in Australian and Argentine dryland zones.
Market Restraints
- Phosphate and potash cost volatility:Fertilizer input spikes compress margins for coated seed producers who bundle nutrient priming into premium formulations.
- Germplasm import concentration:Brazilian ranchers depend on Australian and African breeding material for tropical grass varieties, exposing supply chains to ANVISA phytosanitary clearance delays.
- Transgenic trait regulatory fragmentation:Corteva's glyphosate-tolerant alfalfa faces asynchronous approval timelines between USDA deregulation and EU GMO import restrictions, complicating variety deployment.
Strategic Opportunities
- Carbon credit monetization:Methodologies under development at Verra and Gold Standard could revalue legume-based rotations as verifiable soil carbon sinks, creating new revenue streams for seed-adjacent service providers.
- Direct-to-rancher digital channels:DLF Seeds and regional cooperatives are bypassing traditional distributor networks through prescription platforms that match variety to soil microbiome data.
- India's fodder deficit zones:Punjab and Haryana dairy cooperatives under FSSAI quality pressure are tripling silage seed procurement as commercial milk collection expands.
Industry Challenges
- Certification timeline compression:OECD seed scheme harmonization remains incomplete, forcing duplicate field trials across EU member states for variety registration.
- Genomic IP licensing complexity:Stacked trait packages involving multiple CRISPR edits and background germplasm create royalty stacking disputes between public breeders and commercial licensors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Forage Seeds Market |
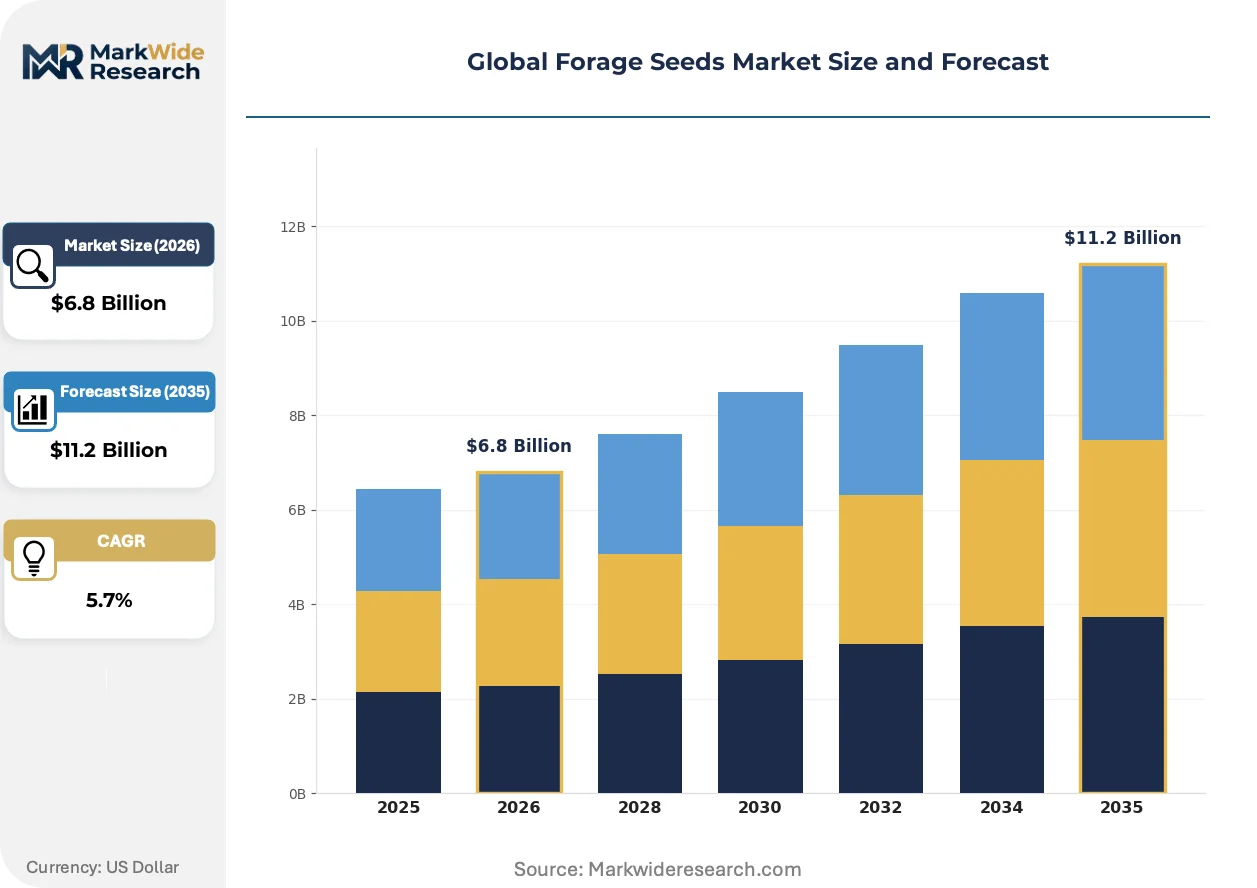
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Grass Seeds, Legume Seeds, Mixtures, Cover Crops Application: Animal Feed, Erosion Control, Bioenergy Production, Soil Improvement Form: Raw Seeds, Coated Seeds, Pelleted Seeds, Treated Seeds Distribution Channel: Direct Sales, Online Retail, Agricultural Stores, Wholesalers |
| Companies Covered | DLF Seeds A/S, Royal Barenbrug Group, Allied Seed LLC, Corteva Inc., S&W Seed Company, Forage Genetics International LLC, Bayer AG, Land O'Lakes Inc., Advanta Seeds, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Forage Seeds Market Emerging Trajectories
Biological seed treatments and digital agronomy platforms are converging to displace commodity trading models, while regulatory carbon accounting threatens to restructure varietal preference hierarchies entirely.
RNA interference-based fungal resistance is migrating from greenhouse vegetable applications into open-field forage establishment. Ryegrass breeders in New Zealand and Denmark are deploying spray-induced gene silencing against crown rust pathogens. Large-scale dairy cooperatives in the Netherlands are piloting treated seed lots that reduce fungicide dependency during establishment phases. The technology is migrating from specialty horticulture into broad-acre forage systems through coating-compatible delivery formulations.
REACH chemical restriction schedules are eliminating neonicotinoid seed treatments previously standard in European grass seed coatings. ECHA's 2023-2028 sunset dates for clothianidin and thiamethoxam force reformulation toward biological alternatives. German and Danish seed processors are accelerating microbial inoculant partnerships to maintain treatment efficacy without synthetic actives. Legume-coated products face parallel pressure as polymer binder chemistries come under substance evaluation.
Rancher buying committees are consolidating procurement authority previously dispersed across individual farm managers. Brazilian integrated crop-livestock operations in Mato Grosso do Sul are centralizing variety selection through technical staff rather than decentralized pasture managers. This concentration compresses supplier negotiation cycles and privileges breeders with integrated crop protection bundles. The pattern is most visible in operations above ten thousand hectares where silage and grazing decisions merge under single agronomy directors.
Global Forage Seeds Market Segmentation
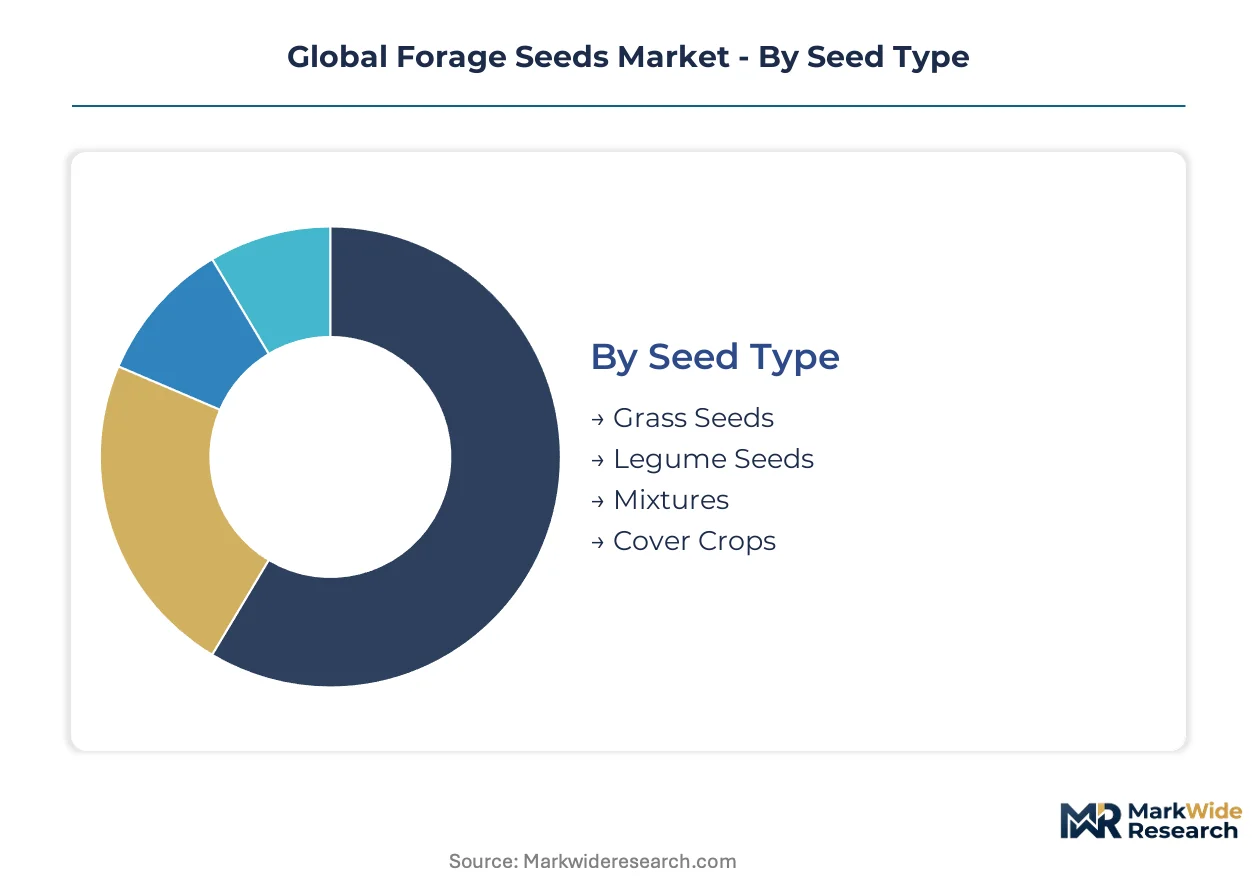
Forage seed purchasing decisions cascade through multiple technical and commercial dimensions. Breeders and distributors must align variety selection with specific end-use performance requirements, regulatory constraints on seed treatments, and evolving procurement channel preferences across dairy and beef operations.
Seed Type:
Mature grass varieties dominate established temperate pasture systems, while emerging legume categories capture sustainability-driven rotation mandates.
- Grass Seeds:Perennial ryegrass and tall fescue varieties constitute the foundational germplasm for dairy grazing systems across New Zealand, Ireland, and the US Midwest. Demand concentrates in French and German dairy cooperatives where Farm to Fork nitrogen reduction targets force clover-grass mixtures into rotation cycles previously managed as pure grass monocultures.
- Legume Seeds:Alfalfa, clover, and vetch varieties deliver nitrogen fixation services that displace synthetic fertilizer applications in pasture renovation programs. Brazilian ranchers in Mato Grosso and Goiás are expanding alfalfa establishment for integrated crop-livestock systems following consecutive drought cycles that degraded pure grass stands.
- Mixtures:Pre-formulated grass-legume blends simplify establishment decisions for mid-scale operators lacking technical agronomy staff.
- Cover Crops:Annual ryegrass and brassica varieties serve dual-purpose soil protection and emergency forage roles in North American corn-soy rotations.
Grass Seeds retains volume leadership; Legume Seeds holds the steepest expansion curve.
Application:
Volume concentrates in livestock nutrition, while regulatory pressure on land management creates adjacent demand in environmental services.
- Animal Feed:Silage and grazing establishment drives procurement for dairy cattle, beef finishing, and sheep operations across temperate and tropical zones. US dairy cooperatives in Wisconsin and California are specifying high-performance alfalfa varieties with elevated crude protein and fiber digestibility metrics to meet processor milk quality premiums.
- Erosion Control:Rapid-establishment grass varieties stabilize disturbed soils on infrastructure corridors and reclaimed mining sites. Australian state road authorities in Queensland and New South Wales specify certified germplasm for slope stabilization contracts with mandatory establishment timelines.
- Bioenergy Production:Dedicated biomass crops including switchgrass and miscanthus serve anaerobic digestion feedstock requirements in German and Danish biogas installations.
- Soil Improvement:Deep-rooted radish and legume varieties penetrate compaction layers in annual cropping systems across the US Corn Belt and Canadian Prairies.
Animal Feed commands procurement volume; Soil Improvement is climbing the fastest as carbon accounting methodologies mature.
Form:
Raw commodity trading yields to value-added treatments as ranchers prioritize establishment reliability and input substitution.
- Raw Seeds:Uncoated germplasm serves price-sensitive bulk purchasers with in-house treatment capabilities. Argentine dryland operators in Buenos Aires Province source raw legume seed for on-farm rhizobia inoculation using established fermentation protocols.
- Coated Seeds:Polymer-encapsulated treatments integrate rhizobia inoculants, micronutrients, and moisture-retention polymers into single-application products. REACH chemical restrictions in the EU are eliminating neonicotinoid-based coatings, forcing reformulation toward biological actives and mineral-based binders.
- Pelleted Seeds:Compressed formulations improve handling and metering accuracy for precision drilling equipment in UK and Dutch grassland renovation programs.
- Treated Seeds:Fungicide and insecticide applications protect germination phases in high-value legume establishment where seed cost justifies chemical protection.
Raw Seeds maintains price-sensitive volume; Coated Seeds is gaining share fastest through premium positioning and regulatory tailwinds.
Distribution Channel:
Procurement authority is consolidating from decentralized farm managers toward technical staff in large integrated operations.
- Direct Sales:Breeder-to-rancher relationships dominate variety selection for operations above ten thousand hectares. DLF Seeds and Corteva are deploying prescription platforms that match variety to soil microbiome data, bypassing traditional distributor markups in Brazilian Mato Grosso do Sul integrated crop-livestock systems.
- Online Retail:E-commerce penetration accelerates for standardized varieties where certification and germination testing documentation is digitized. Australian pasture renovation suppliers are piloting direct-to-farmer platforms with integrated soil testing kits and variety recommendation algorithms.
- Agricultural Stores:Local retail networks retain relevance for mid-scale operators requiring immediate availability and credit terms.
- Wholesalers:Regional distributors aggregate volume for smaller cooperatives lacking direct breeder relationships.
Direct Sales captures margin concentration; Online Retail is expanding most quickly through platform investments and digitized certification workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Brazilian ranchers exhibit acute sensitivity to seed costs following drought-induced pasture losses, while US dairy cooperatives prioritize performance metrics over unit pricing. European buyers occupy a middle position, balancing sustainability premiums against input substitution economics.
United States
Dairy cooperatives in Wisconsin and California drive demand for high-performance alfalfa with elevated crude protein and fiber digestibility. The USDA regulates seed certification through official testing protocols that shape variety registration timelines. Iowa and Minnesota host concentrated breeding operations where integrated crop protection bundles dominate procurement decisions.
Brazil
Ranchers in Mato Grosso and Goiás are replanting degraded grazing lands with drought-tolerant brachiaria hybrids after consecutive El Niño dry cycles. ANVISA enforces phytosanitary standards on imported germplasm that create clearance delays for Australian and African breeding material. The integrated crop-livestock operations in Mato Grosso do Sul are consolidating procurement authority under technical agronomy directors.
Germany
French and German dairy cooperatives face compulsory nitrogen reduction targets under the EU Green Deal's Farm to Fork strategy. ECHA's REACH framework eliminates neonicotinoid seed treatments through 2023-2028 sunset dates for clothianidin and thiamethoxam. Seed processors in Lower Saxony are accelerating microbial inoculant partnerships to maintain coating efficacy without synthetic actives.
Australia
Dryland operators in New South Wales and Queensland source raw legume seed for on-farm rhizobia inoculation using established fermentation protocols. State road authorities specify certified germplasm for slope stabilization contracts with mandatory establishment timelines. Pasture renovation suppliers are piloting direct-to-farmer platforms with integrated soil testing kits and variety recommendation algorithms.
India
Dairy cooperatives in Punjab and Haryana under FSSAI quality pressure are tripling silage seed procurement as commercial milk collection expands. The country's national agricultural regulator enforces variety registration requirements that slow foreign germplasm introduction. Karnataka and Maharashtra host emerging processing clusters where fodder deficit zones concentrate demand for high-yielding varieties.
Global Forage Seeds Market Vendor Landscape
Specialized breeding networks and integrated agrochemical conglomerates split the market into distinct competitive spheres. Breeders with proprietary trait portfolios command premium positioning in legume segments, while commodity grass seed trading consolidates around regional processing scale. Three archetypes dominate: European perennial ryegrass specialists, North American transgenic trait licensors, and diversified seed-chemical integrators. Competitive moves center on direct-to-farmer distribution bypass and biological coating reformulation.
Within the specialized breeding tier, DLF Seeds A/S and Royal Barenbrug Group occupy positions anchored in European germplasm networks. Corteva Inc. exemplifies the integrated trait-licensing archetype through its transgenic alfalfa portfolio. Among diversified agrochemical-seed conglomerates, Bayer AG represents the scale-driven competitive position. These three company groupings illustrate the market's structural division between proprietary genetics, regional breeding depth, and bundled input platforms.
| Leading Market Players |
|---|
| DLF Seeds A/S |
| Royal Barenbrug Group |
| Allied Seed LLC |
| Corteva Inc. |
| S&W Seed Company |
| Forage Genetics International LLC |
| Bayer AG |
| Land O'Lakes Inc. |
| Advanta Seeds |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European grass seed processing is compressing breeder margins and accelerating consolidation toward direct-to-rancher distribution models. This utilization dynamic forces processors to absorb coating reformulation costs while rancher buying committees extract volume discounts.
Pricing Analysis
After-sales service revenue from technical agronomy support and prescription platform subscriptions drives lifetime value more than seed unit margins. Three-tier pricing structure across certified, standard, and utility germplasm tiers reflects OECD seed scheme certification levels and digestibility performance metrics. Cost compression in coated seed formulations is intensifying because REACH chemical restrictions eliminate neonicotinoid actives. Brazilian integrated crop-livestock operations exhibit acute price sensitivity following drought-induced pasture losses, while US dairy cooperatives prioritize fiber digestibility premiums over unit cost.
Supply Chain Analysis
Contract breeding capacity concentrates in Danish and Dutch processing facilities that handle DLF Seeds and Royal Barenbrug germplasm networks. Geographic supply concentration centers on Denmark, the Netherlands, and the United States for temperate varieties, with Australian and African breeding programs supplying Brazilian tropical grass material. Raw material dependencies include polymer coating chemistries, rhizobia inoculant strains, and micronutrient priming formulations. Single-source vulnerability runs through ANVISA phytosanitary clearance bottlenecks for South American germplasm imports. Distribution runs through direct breeder relationships for large integrated operations and agricultural retail networks for mid-scale ranchers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
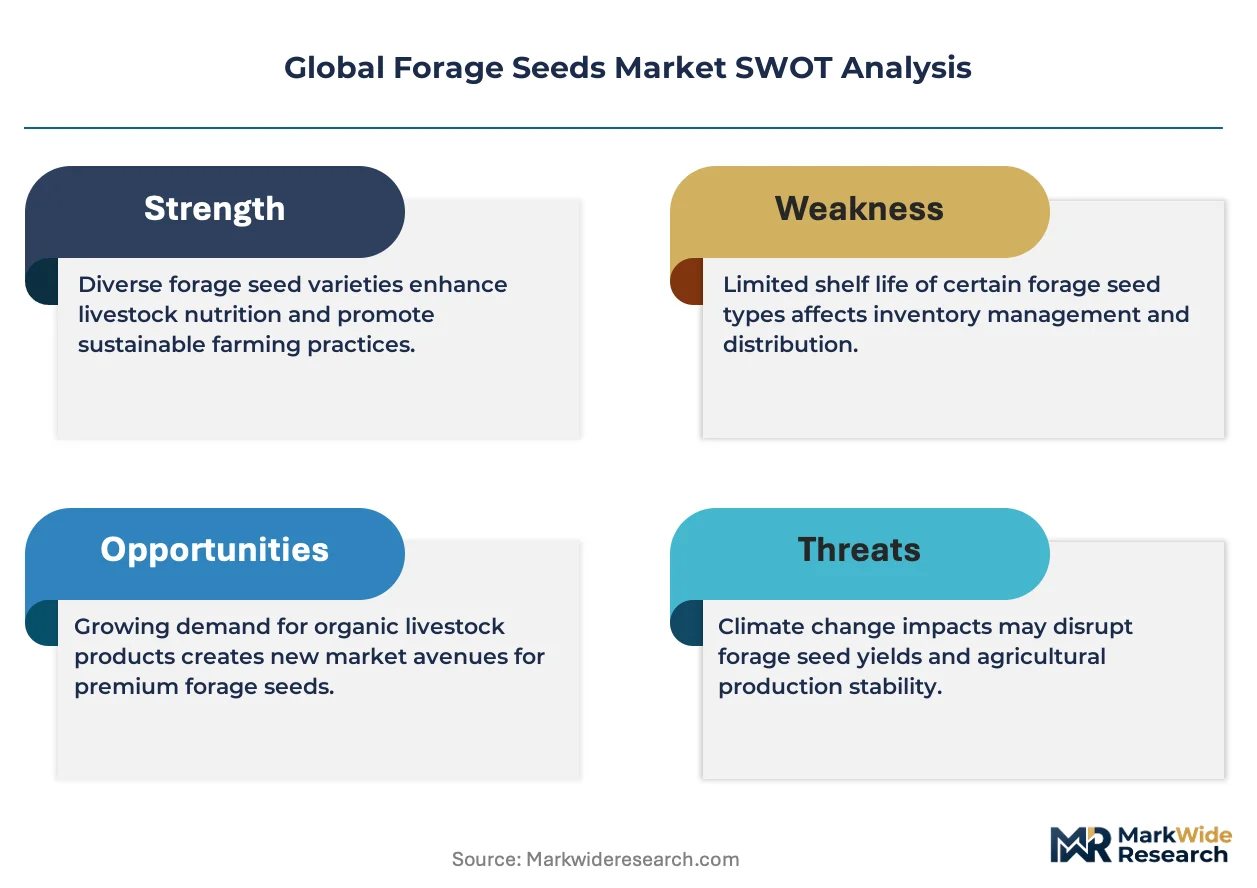
The EU Green Deal's nitrogen mandate represents a regulatory inflection that will restructure varietal preference hierarchies toward legume-intensive rotations, creating high-growth disruption for breeders with nitrogen-fixing portfolios.
For Market Incumbents: Build regulatory compliance moats through accelerated microbial inoculant partnerships that satisfy ECHA REACH sunset timelines for synthetic seed treatments. Incumbent breeders should secure backward integration into rhizobia fermentation capacity to control coating input costs against phosphate and potash volatility. Defensive moves must counter genomic IP licensing complexity that creates royalty stacking disputes with public breeding programs. For New Entrants and Emerging Players: India's fodder deficit zones in Punjab and Haryana represent the most penetrable entry point for silage-focused germplasm suppliers without established distribution footprints. Mid-scale Brazilian ranchers in Goiás rebuilding degraded pastures after El Niño cycles offer white-space demand for drought-tolerant brachiaria hybrids. Go-to-market execution should leverage direct-to-rancher digital platforms with integrated soil microbiome testing kits. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across biological seed treatment processing as microbial coating partnerships displace in-house chemical formulation infrastructure. Long-term viability over the coming decade favors specialized breeding networks with proprietary nitrogen-fixing trait portfolios over commodity grass seed traders. Acquisition targets should display direct-to-farmer prescription platform capabilities. The signal to watch is Verra and Gold Standard carbon credit methodology finalization for legume-based rotation verification.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Coating Reformulation | REACH chemical restrictions force microbial inoculant partnerships to maintain treatment efficacy without neonicotinoid actives. |
| Direct-to-Rancher Platform Deployment | Prescription algorithms matching variety to soil microbiome data bypass traditional distributor markups in Brazilian Mato Grosso. |
| Carbon Credit Methodology Alignment | Verra and Gold Standard soil carbon verification protocols could revalue legume rotations as monetizable sinks. |
| Backward Integration into Inoculant Production | In-house rhizobia fermentation capacity insulates coating input costs from phosphate and potash volatility. |
| Precision Inoculant Coating Scale-Up | Polymer-encapsulated treatments expand addressable acreage for legume establishment in Australian and Argentine dryland zones. |
Methodological Framework
Desk research of OECD seed scheme registration databases, USDA certification protocols, and ANVISA phytosanitary clearance records preceded structured interviews with breeding program directors, seed processing facility managers, rancher cooperative procurement officers, and agricultural retail channel partners. Primary fieldwork across Danish, Dutch, and Brazilian processing clusters combined with secondary validation from EU Green Deal regulatory filings and ECHA REACH substance evaluations. Bottom-up acreage estimates and top-down breeder revenue triangulation anchored segmentation outputs.
Assumptions regarding EU Farm to Fork nitrogen reduction enforcement timelines and Brazilian pasture reconstruction cadence were held fixed while El Niño recurrence frequency and carbon credit methodology adoption rates were varied across sensitivity bands. Segmentation modeling spanned seed type, application end-use, treatment form, and distribution channel dimensions across the projection horizon. CAGRs derived from breeder shipment data and cooperative procurement surveys, with digestibility metric premiums and coating treatment penetration as key forecast inputs.
Stress conditions across germplasm import clearance delays, polymer binder chemistry regulatory restrictions, and genomic IP litigation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of ANVISA phytosanitary queue lengths and ECHA substance evaluation schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seeds
Wax Gourd Seed Market
Seeds
South America Chia Seeds Market
Seeds
Africa Sorghum Seed Market
Seeds
Asparagus Seeds Market
Seeds
Asia-Pacific Chia Seed Market
Seeds
Southeast Asia Vegetable Seed Market
Seeds
Grass Seed Market
Seeds
Asia Pacific Tomato Seed Oil Market
Seeds
Native Grass Seeds Market
Seeds
Okra Seed Market
Seeds
Field Crop Seeds Market
Seeds
Citrus Seeds Market
Seeds
Flower Seed Market
Seeds
Global Onion Seed Market
Seeds
South America Seed Market
Seeds
Global Maize Seed Market