
 Manufactured Garden Soil Market | 2026-2036
Manufactured Garden Soil Market Size, Share, and Industry Trends Forecast 2026-2036
Manufactured Garden Soil Market Insights
North American peat harvesting regions are fragmenting as climate-related extraction restrictions tighten. The Scotts Miracle-Gro Company leverages its retail distribution network to sustain shelf dominance across big-box garden centers. Klasmann-Deilmann GmbH anchors European supply through specialized substrate formulations for professional horticulture. FoxFarm Soil & Fertilizer Co. differentiates via premium organic positioning and targeted craft-cultivator channels.
Manufactured garden soil denotes engineered growing media blended from organic and mineral constituents to standardized physical and chemical parameters, typically including controlled porosity, pH buffering capacity, and nutrient retention profiles for predictable plant establishment. Potting mix formulations command premium margin pools due to container gardening's expansion in urban residential settings, while peat moss material sourcing faces structural pressure from sustainability-driven substitution toward coco coir alternatives. Landscaping applications maintain volume leadership across commercial and municipal project pipelines, though hydroponics represents the fastest-growing application segment as controlled-environment agriculture scales.
EPA compost quality guidelines and state-level organic certification standards in California and Oregon shape product compliance costs and labeling requirements for interstate commerce. REACH restrictions on peat extraction in Europe redirect formulation strategies toward renewable substrate materials. Stakeholders must monitor evolving carbon-accounting frameworks for soil amendments and assess whether backward integration into composting infrastructure or partnerships with regional waste processors offers more durable cost structures.
Market Dynamics
EPA compost quality guidelines and emerging state-level organic certification standards are forcing manufacturers to reconfigure raw material sourcing and testing protocols, compressing margins while creating compliance-driven competitive separation.
Growth Catalysts
- Container gardening expansion:Urban residential settings in the United States are driving premium potting mix consumption as balcony and rooftop cultivation normalizes among apartment dwellers.
- Controlled-environment agriculture scaling:Hydroponics applications are accelerating demand for engineered substrates with precise porosity and nutrient retention specifications.
- California and Oregon organic certification standards:Interstate commerce requirements for labeled organic products are pulling manufacturers toward certified composting partnerships and traceable supply chains.
Market Restraints
- Peat moss supply concentration:Climate-related extraction restrictions in Canadian and Irish harvesting regions are constraining traditional substrate volumes and elevating input cost volatility.
- Coco coir substitution economics:Sri Lankan and Indian coconut processing capacity limits create supply bottlenecks for the primary peat alternative, fragmenting formulation reliability.
- REACH peat extraction restrictions in Europe:ECHA regulations are redirecting continental manufacturers toward renewable materials, compressing margins during transition periods.
Strategic Opportunities
- Municipal composting infrastructure partnerships:Regional waste processors in the United States offer backward integration pathways that stabilize feedstock costs and carbon-accounting credentials.
- Direct-to-craft-cultivator channels:Premium organic positioning through specialized hydroponics retailers captures margin pools unavailable through big-box distribution.
- Carbon-accounting frameworks for soil amendments:Emerging verification standards create first-mover advantages for manufacturers with documented lifecycle emissions data.
Industry Challenges
- Compost quality testing capacity:EPA emerging standards for contaminant thresholds require laboratory infrastructure investments that smaller regional blenders struggle to fund.
- Formulation chemistry expertise:pH buffering and nutrient retention engineering demands specialized agronomists whose scarcity limits product line expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manufactured Garden Soil Market |
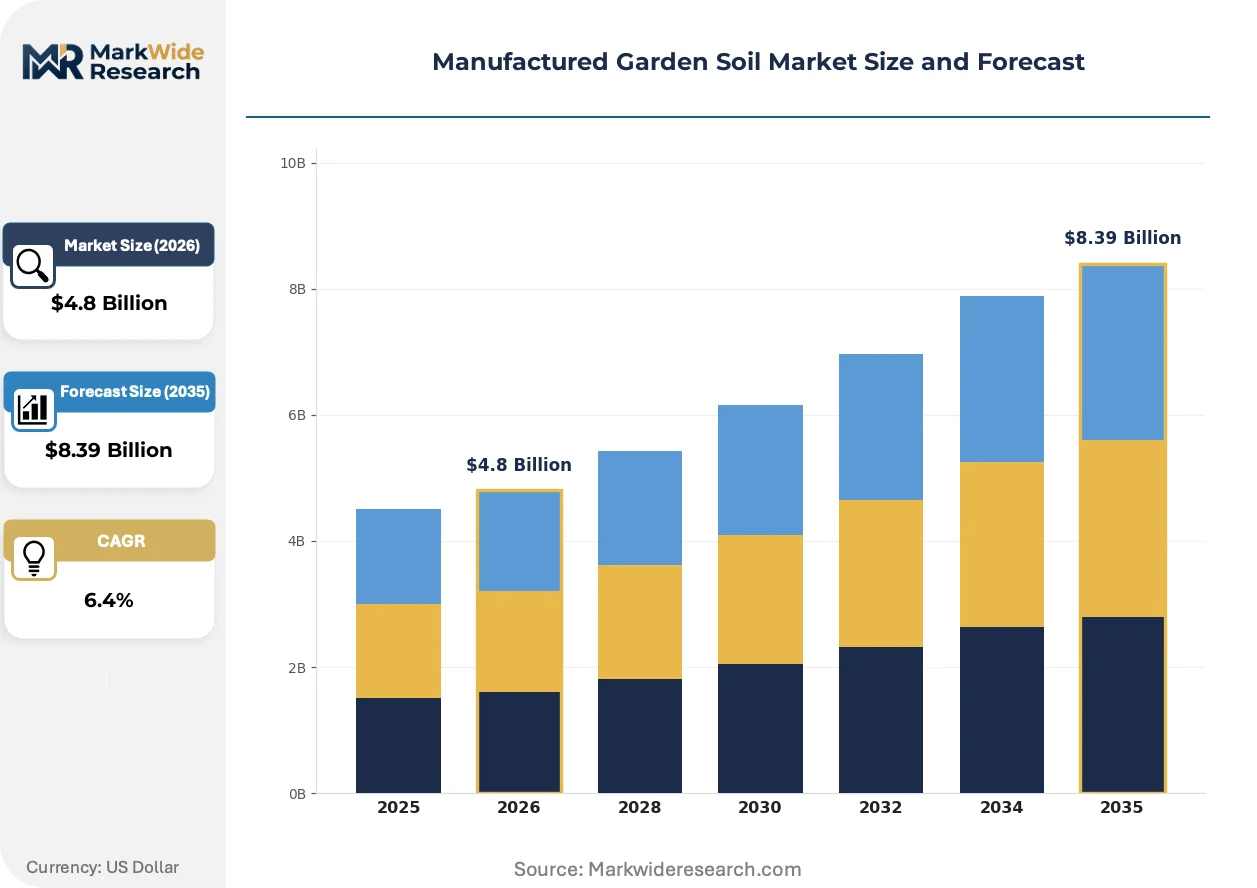
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potting Mix, Seed Starting Mix, Lawn Soil, Garden Soil Material: Coco Coir, Peat Moss, Compost, Perlite Application: Indoor Gardening, Outdoor Gardening, Landscaping, Hydroponics Brand: Miracle-Gro, FoxFarm, Black Gold, Espoma |
| Companies Covered | The Scotts Miracle-Gro Company, Boxley Materials Company, Klasmann-Deilmann GmbH, FoxFarm Soil & Fertilizer Co., ASB Grünland Helmut Aurenz GmbH, Boughton Loam & Turf Management, Resource Management Inc., Casella Organics Inc., Tim O’Hare Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manufactured Garden Soil Market Trends and Innovations
Formulation science and distribution architecture are converging to reshape how engineered growing media reach end-users, with digital tools and regulatory pressure as twin accelerants.
Sensor-integrated substrate monitoring is virtualizing the relationship between growers and their media. Commercial greenhouse operators in the Netherlands and California are deploying IoT-enabled pots that transmit moisture, pH, and nutrient data in real time. This capability is virtualizing traditional agronomic consulting services, compressing the value captured by standalone soil testing laboratories.
REACH restrictions on peat extraction in Europe are redirecting formulation strategies toward renewable substrate materials. ECHA's tightening thresholds on extraction volumes have triggered accelerated R&D spending on wood fiber, bark, and biochar alternatives. Professional horticulture segments in Germany and the Netherlands are responding with pilot programs testing fully peat-free formulations in large-scale ornamental production.
Subscription-based replenishment models are fragmenting traditional retail purchasing patterns for residential gardeners. Direct-to-consumer channels in the United States are displacing seasonal big-box stocking with automated delivery schedules calibrated to planting zones. Urban clusters in the Southeast and Southwest exhibit the highest conversion rates, where lawn-to-garden conversions sustain recurring media consumption.
Manufactured Garden Soil Market Segmentation
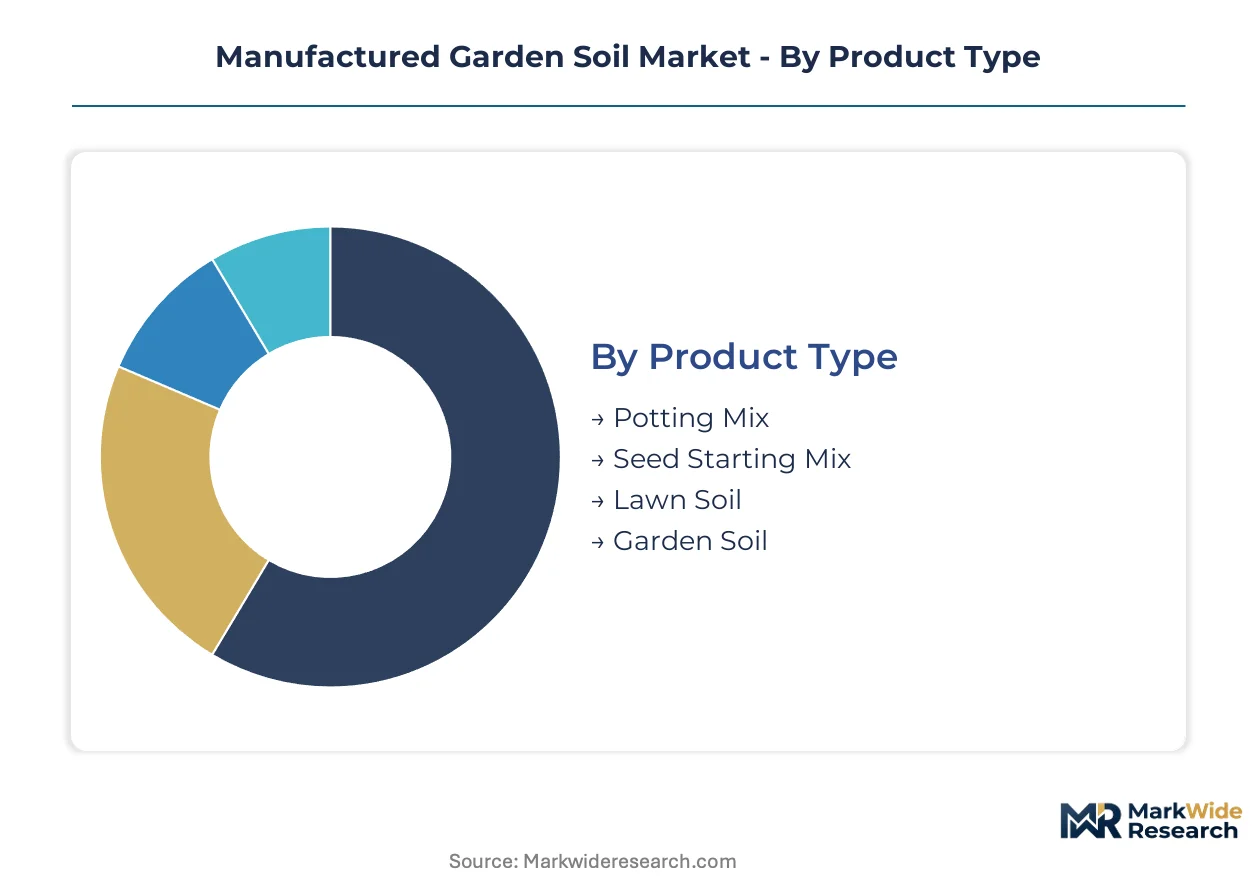
Engineered growing media demands precise specification matching across cultivation contexts. Segmentation reveals how formulation chemistry, sourcing constraints, and end-use requirements create distinct competitive arenas with divergent margin structures and compliance burdens.
Product Type:
Application intensity and container geometry dictate formulation density and drainage specifications across residential and commercial deployments.
- Potting Mix:Engineered for containerized cultivation with controlled porosity, pH buffering, and sustained nutrient release for confined root zones. Demand concentrates in United States urban residential balconies and rooftop gardens where space constraints elevate premium formulation willingness.
- Garden Soil:Blended for in-ground planting with higher mineral content and bulk density for structural stability in open beds. Suburban developments across the United States Southeast and Southwest drive volume procurement through landscaping contractors and municipal project pipelines.
- Seed Starting Mix:Fine-textured, sterile medium optimized for germination with minimal nutrient load to prevent seedling burn.
- Lawn Soil:Topdressing formulations designed for turf establishment with specific sand-to-organic ratios for drainage.
Garden soil commands the established base. The steepest expansion runs through potting mix.
Material:
Feedstock sourcing geography and extraction regulation severity determine supply security and carbon-accounting credibility for manufacturers.
- Peat Moss:Traditional substrate with superior water retention and cation exchange capacity derived from sphagnum deposits. Canadian and Irish harvesting regions face climate-related extraction restrictions that constrain volumes and elevate input cost volatility for North American and European blenders.
- Coco Coir:Renewable coconut husk fiber alternative with comparable aeration properties and neutral pH. Sri Lankan and Indian processing capacity limits create supply bottlenecks that fragment formulation reliability for manufacturers transitioning from peat-dependent recipes.
- Compost:Decomposed organic matter providing microbial diversity and slow-release nutrients subject to EPA emerging contaminant thresholds.
- Perlite:Expanded volcanic glass additive for drainage enhancement with energy-intensive production concentrated in specific geological regions.
Peat moss retains the dominant share. Coco coir is climbing the fastest amid sustainability-driven substitution.
Application:
Cultivation environment control level and scale economics separate hobbyist consumption from commercial procurement patterns.
- Landscaping:Large-scale outdoor installations across commercial properties, municipal parks, and residential developments requiring bulk volume with standardized performance. United States suburban expansion in the Southeast and Southwest sustains steady demand through contractor channels with price-sensitive procurement.
- Hydroponics:Soilless cultivation systems demanding engineered substrates with precise porosity, inert chemistry, and sterility for nutrient solution control. Controlled-environment agriculture scaling in the Netherlands and California accelerates specification refinement and premium pricing acceptance.
- Indoor Gardening:Residential container cultivation in space-constrained urban dwellings with aesthetic and convenience priorities.
- Outdoor Gardening:Traditional in-ground and raised-bed cultivation with seasonal purchasing patterns and weather-dependent timing.
Landscaping anchors volume leadership. Hydroponics shows the steepest expansion trajectory.
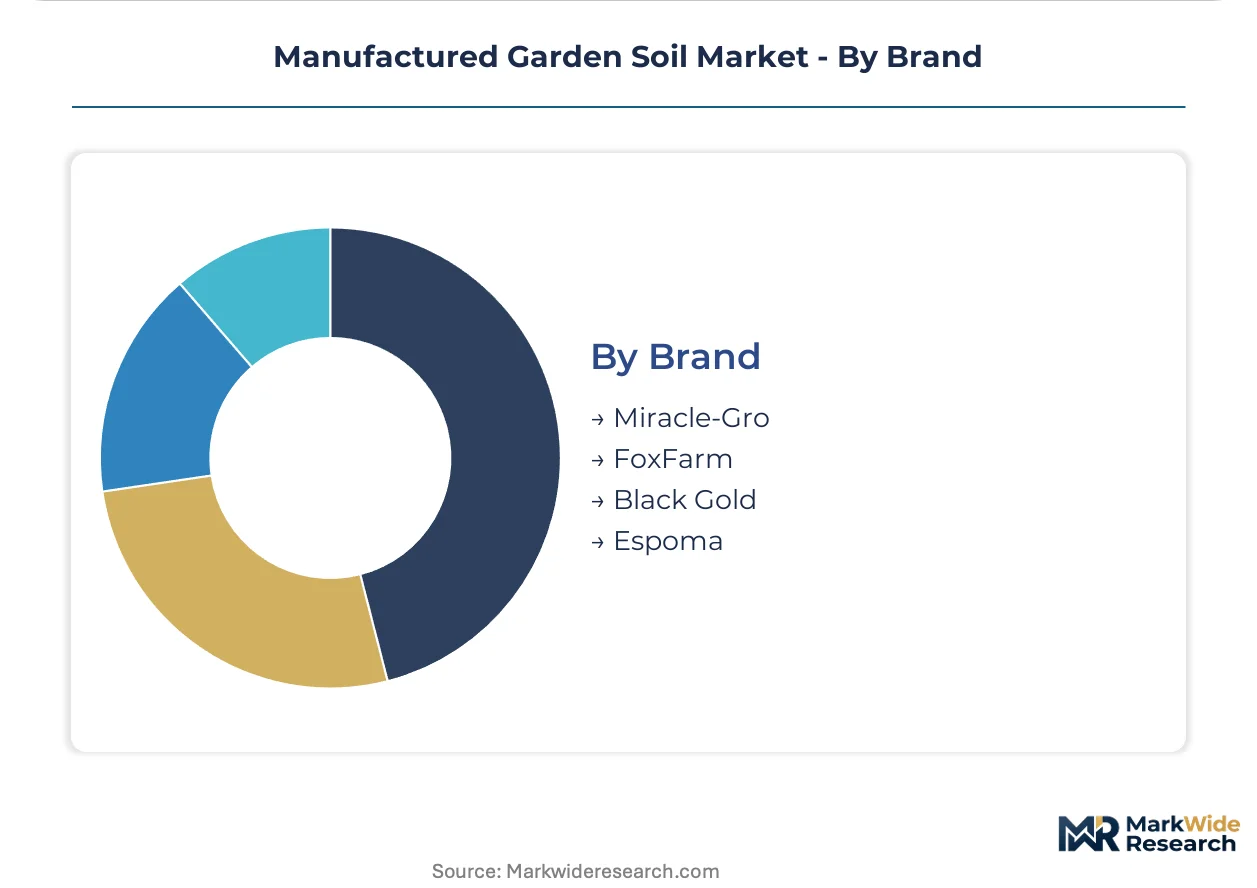
Brand:
Distribution channel access and certification positioning separate mass-market penetration from premium segment capture.
- Miracle-Gro:Mass-market leader leveraging retail distribution network dominance across big-box garden centers with standardized formulations for casual gardeners.
- FoxFarm:Premium organic positioning through specialized hydroponics retailers and craft-cultivator channels with targeted nutrient recipes.
- Black Gold:Regional strength in organic certification compliance for West Coast markets with compost-based formulations.
- Espoma:Heritage organic brand emphasizing natural ingredients and environmental stewardship for established gardener loyalty.
Miracle-Gro commands shelf presence. FoxFarm gains share fastest in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's bulk cargo handling infrastructure underwrites Northwestern Europe's substrate distribution hub status, moving peat alternatives and compost feedstocks across continental supply chains.
United States
Suburban development pipelines in Texas and Florida drive bulk landscaping procurement through contractor networks. EPA compost quality guidelines force reformulation investments for interstate organic certification compliance. The Southeast's lawn-to-garden conversion clusters around Atlanta and Charlotte sustain recurring residential media consumption.
Germany
Professional horticulture operations in Lower Saxony and Bavaria pilot peat-free substrate programs at scale. ECHA's REACH extraction thresholds redirect R&D spending toward wood fiber and biochar alternatives. The Emsland region's greenhouse complexes test fully renewable formulations for ornamental production.
Netherlands
Controlled-environment agriculture in Westland and Aalsmeer accelerates demand for precision-engineered hydroponic media. EU Green Deal carbon-accounting frameworks pressure substrate manufacturers toward documented lifecycle emissions. Wageningen's agritech corridor hosts pilot programs for sensor-integrated growing systems.
Canada
Climate-related harvesting restrictions in Quebec and New Brunswick constrain traditional peat moss volumes for North American blenders. Health Canada's PMMA guidelines on soil amendment contaminants shape export testing protocols. The Prairie Provinces' municipal composting infrastructure expands regional feedstock alternatives.
United Kingdom
Defra's peat reduction targets drive substitution toward coco coir and green waste compost in commercial landscaping. The Southeast's garden center retail density concentrates distribution network investments. Yorkshire's waste processing partnerships offer backward integration pathways for regional manufacturers.
Manufactured Garden Soil Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material processing and formulation chemistry. The market structures around three tiers: mass-market retailers with shelf dominance, premium organic specialists with cultivator channel access, and regional blenders with municipal contract relationships. Consolidation pressure concentrates at the top tier while fragmentation persists among compost-based regional operators. Dominant competitive moves include municipal infrastructure partnerships for feedstock security and direct-to-cultivator channel development for margin capture.
Among mass-market platform operators, The Scotts Miracle-Gro Company occupies the retail network anchor position. Klasmann-Deilmann GmbH represents the European professional horticulture specialist archetype with substrate formulation depth. FoxFarm Soil & Fertilizer Co. exemplifies premium organic positioning through specialized hydroponics retail channels.
| Leading Market Players |
|---|
| The Scotts Miracle-Gro Company |
| Boxley Materials Company |
| Klasmann-Deilmann GmbH |
| FoxFarm Soil & Fertilizer Co. |
| ASB Grünland Helmut Aurenz GmbH |
| Boughton Loam & Turf Management |
| Resource Management Inc. |
| Casella Organics Inc. |
| Tim O'Hare Associates |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Sri Lankan coco coir processing plants is elevating input cost volatility for manufacturers transitioning from peat-dependent formulations, compressing margins while forcing tiered pricing adjustments across premium and economy product lines.
Pricing Analysis
Volume-discount tiering structures separate bulk landscaping contractors from residential gardeners, with procurement scale driving 30-40% price spreads between pallet and single-bag transactions. Price differentiation rests on organic certification grade and EPA compliance testing depth, with California and Oregon interstate standards commanding premiums. Cost compression in the mid-tier is intensifying because coco coir substitution economics fragment formulation reliability. Municipal project buyers exhibit highest price sensitivity; craft-cultivator channels through hydroponics retailers show lowest.
Supply Chain Analysis
Upstream feedstock sourcing draws from Canadian peat bogs, Sri Lankan coconut processing facilities, and Indian coir mills, creating geographic fragmentation that elevates logistics complexity. Raw material dependencies center on sphagnum moss volumes, coconut husk fiber availability, and compost feedstock quality. Supply chain risk concentrates in single-source vulnerability for coco coir given South Asian processing capacity constraints. Distribution runs through big-box garden center networks for mass-market penetration, with direct-to-cultivator channels capturing premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufactured garden soil markets fragment across certification tiers and application specializations, with EPA emerging standards and state-level organic requirements creating compliance-driven niches that reward targeted positioning.
For Market Incumbents: Build regulatory compliance moats through backward integration into municipal composting infrastructure. Secure EPA-certified laboratory testing capacity to outpace smaller regional blenders on contaminant threshold documentation. Channel control through exclusive hydroponics retailer partnerships defends premium positioning against mass-market private label encroachment.
For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription replenishment for urban balcony gardeners in the Southeast and Southwest. Target carbon-accounting verification as a first-mover wedge, documenting lifecycle emissions for soil amendments ahead of emerging frameworks. Go-to-market through sensor-integrated substrate pilot programs with commercial greenhouse operators virtualizes traditional agronomic consulting relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward regional compost-based blenders with municipal waste processor partnerships and established organic certification compliance. Long-term viability over the next decade hinges on feedstock security amid peat extraction restrictions and coco coir supply bottlenecks. Watch for ECHA REACH threshold tightening as inflection signal accelerating renewable substrate R&D spending.
| Strategic Initiative | Industry Significance |
|---|---|
| Municipal Composting Infrastructure Partnership | Secures traceable feedstock supply and carbon-accounting credentials for EPA compliance. |
| Direct-to-Cultivator Channel Development | Captures premium margin pools unavailable through big-box garden center distribution networks. |
| Peat-Free Formulation R&D Program | Positions manufacturers ahead of ECHA REACH extraction restrictions in European markets. |
| Sensor-Integrated Substrate Pilot | Virtualizes agronomic consulting services through IoT-enabled moisture and pH monitoring. |
| Carbon-Accounting Verification Investment | Creates first-mover advantage as EU Green Deal frameworks pressure documented lifecycle emissions. |
Research Methodology
A standing panel of substrate formulation chemists, municipal composting facility operators, hydroponics retail buyers, and landscaping procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA compost quality guideline drafts, state-level organic certification databases, ECHA REACH regulatory filings, and customs trade data on peat and coco coir imports. Bottom-up volume modeling across product type, material, and application segments triangulated against top-down market sizing.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with segmentation dimensions spanning cultivation environment, feedstock composition, and distribution channel architecture. CAGRs were derived from weighted average growth across modeled segments, incorporating urban residential container gardening penetration rates and controlled-environment agriculture capacity expansion as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in construction activity indices and suburban development permitting would shift the trajectory. Forecasts reflect documented assumptions on regulatory implementation timelines and substitution elasticity between peat and renewable substrates. Cross-checking against USDA horticultural consumption surveys and EPA waste characterization studies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Elaeis Guineensis Kernel Oil Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Tunisia Agriculture Market
Agriculture and Agri Products
Coir Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Corn Co-Products Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
North America Bee Products Market
Agriculture and Agri Products
Floriculture Market
Agriculture and Agri Products
Vietnam Shrimp Feed Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
Cattle Feed Concentrate Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Uncaria Tomentosa Market