
 North America Shrimp Market | 2026-2036
North America Shrimp Market Size, Share, and Industry Trends Forecast 2026-2036
North America Shrimp Market Analytics
The split between premium wild-caught and commodity aquaculture supply is realigning procurement strategies across the value chain. Beaver Street Fisheries leverages its Jacksonville processing infrastructure to sustain volume throughput for foodservice distributors. Sysco Corporation anchors its national distribution network with frozen and breaded shrimp portfolios designed for institutional buyers. Mazzetta Company LLC specializes in value-added cooked and breaded formats that command differentiated placement in retail channels.
Shrimp comprises decapod crustaceans of the infraorder Caridea and suborder Dendrobranchiata, typically harvested at 20-30 grams per individual for commercial processing and consumed as a high-protein, low-fat seafood protein across retail and foodservice applications. Frozen shrimp dominates volume flows through supermarket and foodservice channels where extended shelf life reduces spoilage risk across dispersed North American distribution networks. Fresh shrimp occupies premium positioning in coastal seafood markets and upscale restaurant segments where perishability is managed through rapid turnover. The breaded and cooked product lines concentrate margin pools in processing value-addition, with High Liner Foods Inc. and Trident Seafoods Corp. competing for frozen prepared placement.
The FDA enforces Seafood HACCP regulations mandating hazard controls at critical processing points, while NOAA Office of Law Enforcement monitors illegal, unreported, and unregulated fishing compliance for imported supply. These frameworks elevate compliance costs for smaller importers and favor scaled operators with dedicated quality assurance infrastructure. Stakeholders must monitor evolving traceability mandates and cold-chain integrity standards as determinants of market access.
Market Dynamics
The FDA's tightening Seafood HACCP traceability mandates are compressing supplier margins while concentrating import flows through scaled processors with dedicated compliance infrastructure. This regulatory pressure is accelerating consolidation across the Gulf Coast processing corridor.
Growth Catalysts
- Seafood HACCP Modernization:The FDA's enhanced record-keeping requirements for imported shrimp are rewarding large-scale importers with integrated quality assurance systems, pushing volume toward compliant operators.
- Foodservice Menu Expansion:Institutional buyers across the United States are broadening applications for value-added breaded and cooked formats, creating pull-through demand for processed product lines.
- IQF Processing Technology:Individual quick freezing advances are extending shelf life and preserving texture quality, enabling broader distribution reach for domestic Gulf Coast harvesters.
Market Restraints
- Feed Cost Volatility:Aquaculture operations face input price swings from soybean meal and fish oil markets, compressing margins for farmed supply dependent on formulated diets.
- Asian Supply Concentration:Import dependency on Ecuador, India, and Indonesia creates exposure to currency fluctuations and shipping lane disruptions affecting landed costs.
- Wild Stock Variability:Gulf of Mexico brown shrimp populations fluctuate with hypoxic zone expansion, constraining reliable volume from domestic trawl fisheries.
Strategic Opportunities
- Traceability Technology Convergence:Blockchain and DNA-based species verification are converging to create premium positioning for verified-sustainable supply chains commanding price premiums.
- Retail Ready-to-Cook Segments:Supermarket chains are expanding refrigerated case space for marinated and seasoned raw formats, opening margin pools beyond frozen commodity blocks.
- USDA Organic Certification Pathway:Emerging federal organic aquaculture standards create a regulatory tailwind for producers investing in compliant pond systems and feed sourcing.
Industry Challenges
- HACCP Specialist Scarcity:Qualified seafood safety coordinators command premium wages, constraining smaller processors from maintaining compliant operations without outsourcing.
- Cold-Chain Capex Burden:Blast freezing and controlled-atmosphere storage requirements demand capital intensity that disadvantages regional players against national distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Shrimp Market |
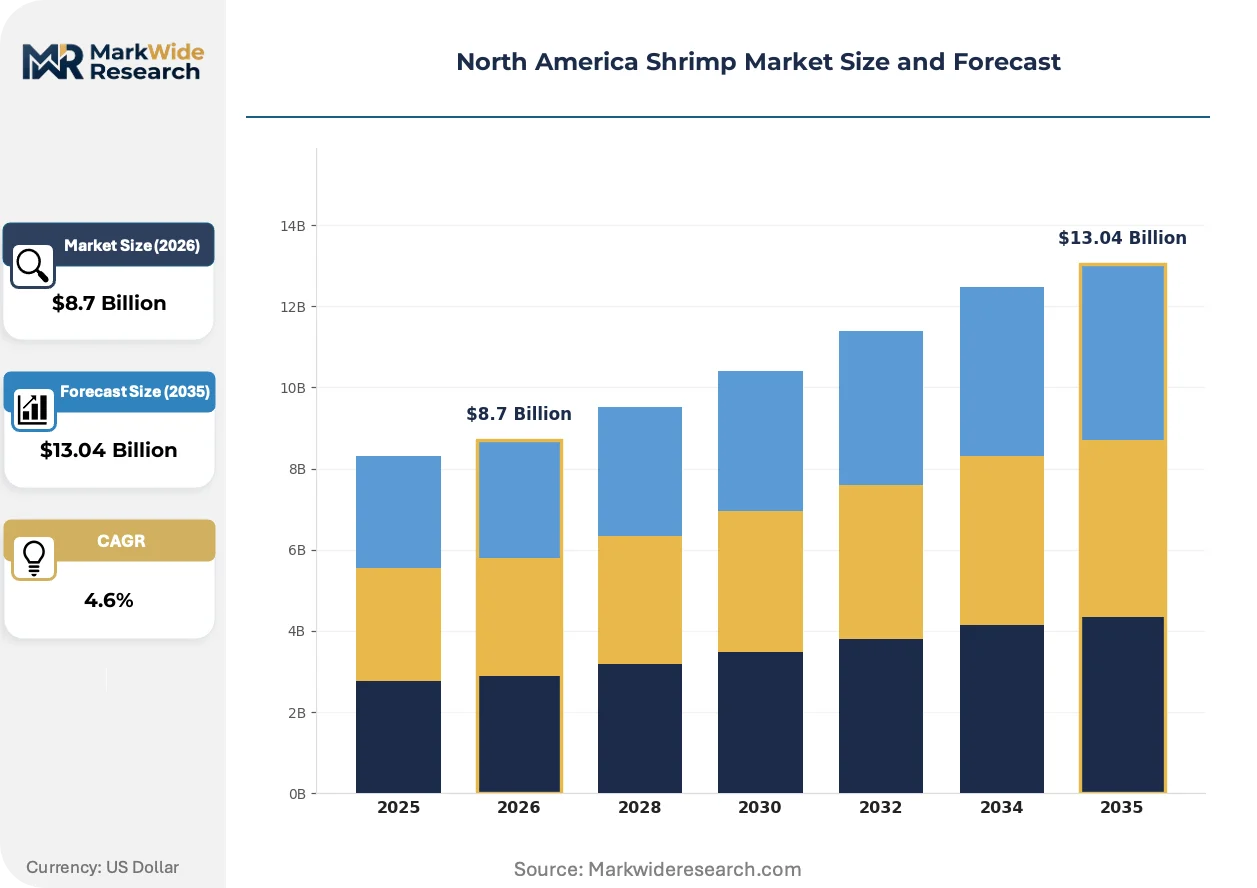
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Shrimp, Frozen Shrimp, Breaded Shrimp, Cooked Shrimp Size: Shrimp Sizes, Jumbo, Medium, Small Distribution Channel: Supermarkets, Online Retail, Seafood Markets, Restaurants End User: Households, Food Service, Processing Companies, Exporters |
| Companies Covered | Admiralty Island Fisheries Inc., Beaver Street Fisheries, Dulcich Inc., Pacific American Fish Company Inc., Sysco Corporation, Trident Seafoods Corp., Thai Union, Mazzetta Company LLC, High Liner Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Shrimp Market Evolving Landscape
Processing technology and regulatory compliance are converging to reshape competitive positioning across the North American shrimp supply chain. These developments are compressing legacy operating models while creating openings for technology-advantaged operators.
High-pressure processing is rewriting safety protocols for raw value-added products. This non-thermal pasteurization technology inactivates Vibrio pathogens while preserving sensory qualities. Major foodservice distributors are adopting HPP-treated peeled shrimp for extended refrigerated shelf life. The technology is compressing the traditional frozen-or-fresh binary and enabling new product formats.
The FDA's enhanced traceability rule under the Food Safety Modernization Act is mandating electronic record-keeping from harvest to retail. This regulation forces importers to implement interoperable data systems linking foreign suppliers to domestic buyers. Smaller traders lacking IT infrastructure are exiting the import channel, accelerating volume concentration.
Direct procurement from aquaculture cooperatives is displacing traditional layered broker networks. Large restaurant chains are establishing preferred supplier agreements with Ecuadorian and Indian farming operations, bypassing multiple intermediaries. This pattern is most visible in quick-service seafood franchises seeking cost predictability and volume security.
North America Shrimp Market Segmentation
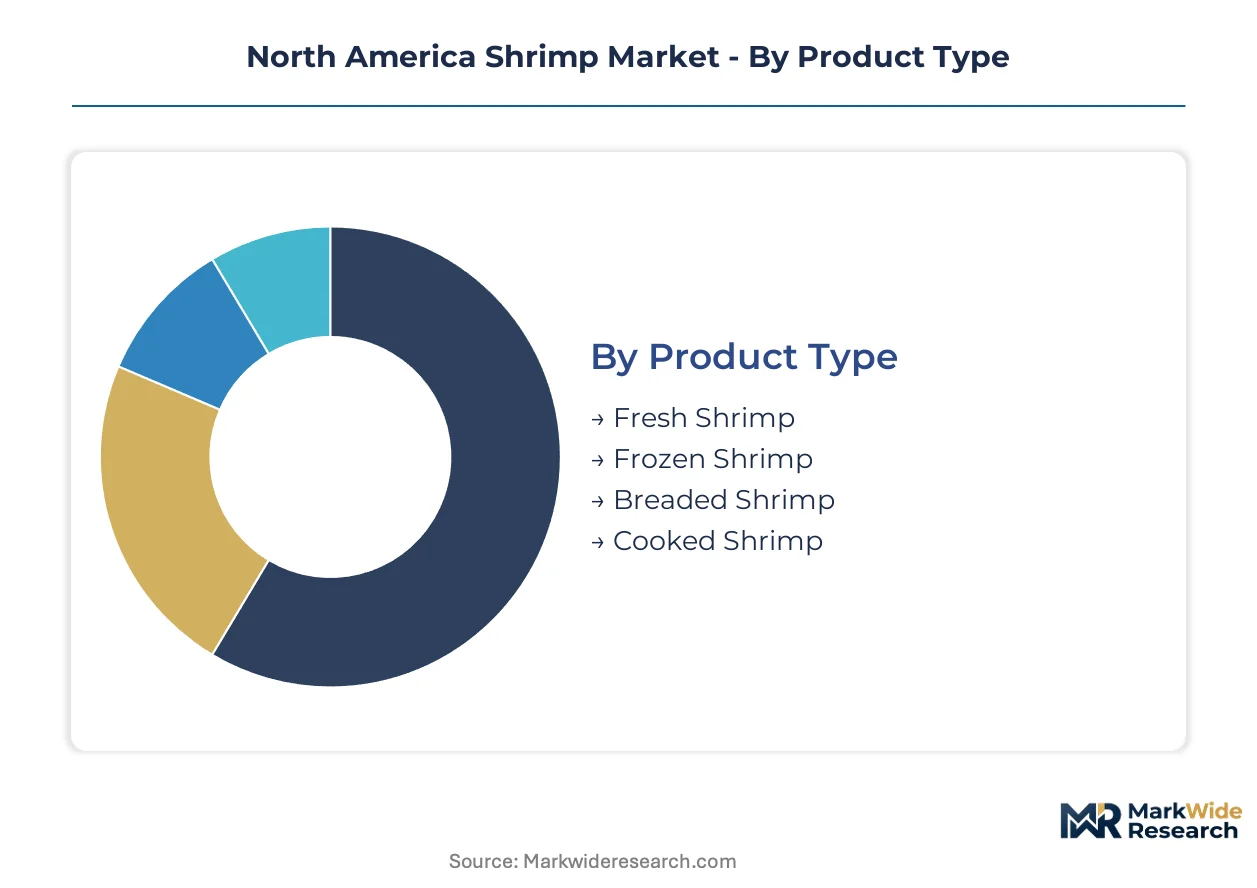
Shrimp supply chains fragment across product formats, size grades, and channel pathways that each demand distinct cold-chain infrastructure and margin structures. Understanding these segment boundaries clarifies where capital deployment yields sustainable returns versus commodity trap exposure.
Product Type:
Supply concentration in frozen formats shapes procurement economics across the Gulf Coast processing corridor.
- Frozen Shrimp:Individual quick freezing preserves texture integrity through blast freezing at minus 40 degrees Celsius, enabling transcontinental distribution from Louisiana-Texas processing hubs. Foodservice distributors anchor procurement volumes here, though energy costs compress margins for regional operators lacking scale.
- Breaded Shrimp:Value-added coating applications command placement premiums in quick-service restaurant supply contracts. Sysco Corporation and similar institutional distributors concentrate procurement through dedicated processing lines that integrate breading, par-frying, and flash-freezing in single-pass operations.
- Fresh Shrimp:Rapid-turnover coastal markets in Gulf states manage perishability through direct dock-to-retail logistics.
- Cooked Shrimp:Peeling and cooking operations cluster near processing infrastructure to minimize handling damage.
Today's leader: Frozen Shrimp. Tomorrow's challenger: Breaded Shrimp.
Size:
Cost tier differentiation separates commodity volume from premium positioning across restaurant menu engineering.
- Jumbo:Counts below 15 per pound signal premium sourcing for steakhouse and upscale casual placements. Gulf Coast brown shrimp landings supply this tier, though hypoxic zone variability constrains reliable volume.
- Medium:The workhorse grade for foodservice breading operations and retail frozen blocks. Ecuadorian and Indian aquaculture feed this segment's scale requirements through containerized import flows.
- Shrimp Sizes:Standardized count-per-pound nomenclature enables procurement transparency.
- Small:Salad and stuffing applications absorb volume in processed food manufacturing.
Medium dominates volume flows. Jumbo captures margin expansion.
Distribution Channel:
Customer type fragmentation creates divergent service requirements between retail and foodservice pathways.
- Restaurants:Institutional buyers specify portion-controlled formats with consistent sizing for menu cost engineering. Direct procurement from aquaculture cooperatives is displacing traditional broker layers in this channel.
- Supermarkets:Retail ready-to-cook segments are expanding refrigerated case space for marinated raw formats. High Liner Foods Inc. and Trident Seafoods Corp. compete for frozen prepared placement here.
- Seafood Markets:Coastal independent retailers source fresh product through dockside relationships.
- Online Retail:Direct-to-consumer frozen delivery requires specialized insulated packaging.
Restaurants drive volume concentration. Supermarkets enable margin diversification.
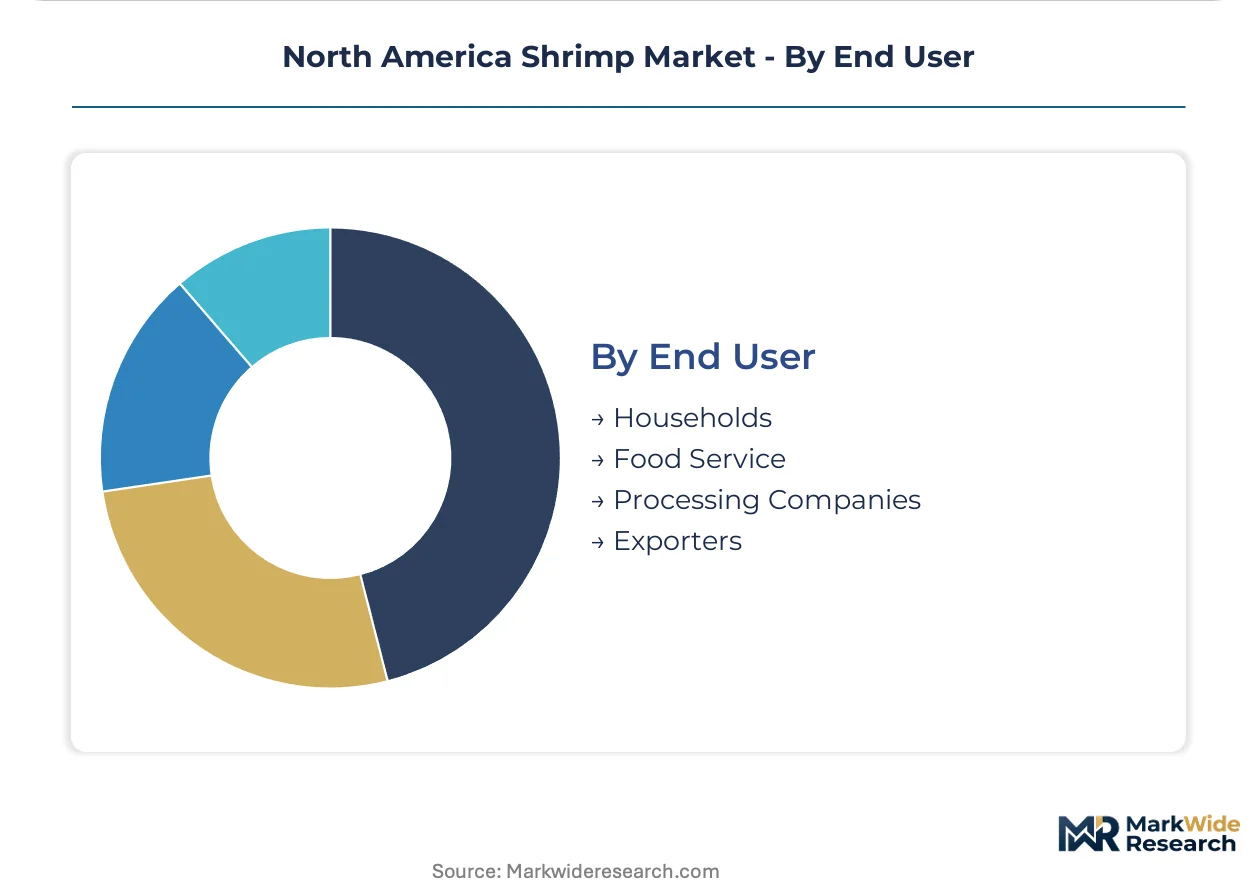
End User:
Application maturity separates established consumption patterns from emerging demand formation.
- Food Service:Quick-service seafood franchises and casual dining chains establish preferred supplier agreements for cost predictability. FDA Seafood HACCP compliance requirements favor scaled operators with dedicated quality assurance infrastructure.
- Households:Retail frozen and fresh purchases concentrate in coastal metropolitan areas with established seafood consumption habits.
- Processing Companies:Further value-addition for breaded and cooked formats absorbs raw material supply.
- Exporters:Re-export flows to Asian markets leverage North American cold-chain infrastructure.
Food Service anchors current demand. Households show emerging trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing expertise concentrates along the Gulf Coast where generations of seafood workers anchor domestic capacity. Canadian cold-chain infrastructure extends Pacific and Atlantic harvest reach into inland distribution networks. Mexican aquaculture development in Sonora and Sinaloa feeds cross-border supply integration.
United States
Louisiana and Texas processing corridors absorb Gulf of Mexico wild harvests and Ecuadorian import volumes for redistribution. FDA Seafood HACCP enforcement tightens traceability mandates that favor scaled operators with dedicated compliance staff. The Port of New Orleans and Houston Ship Channel anchor containerized import flows from Latin American aquaculture cooperatives.
Canada
Atlantic provincial fisheries in New Brunswick and Nova Scotia supply coldwater shrimp species for premium retail positioning. Health Canada and CFIA enforce parallel seafood safety protocols that align with US import requirements. Vancouver's Pacific processing infrastructure handles Asian import transhipment and domestic spot prawn season distribution.
Mexico
Sonora and Sinaloa coastal aquaculture zones expand pond production for export-oriented supply chains. Mexican federal fisheries regulations under CONAPESCA coordinate with US FDA import inspection protocols. Mazatlán processing clusters integrate hatchery-to-export operations serving California and Texas distribution hubs.
North America Shrimp Market Competitive Landscape
Capital-heavy processors with dedicated cold-chain infrastructure compete with asset-light distributors leveraging third-party freezing and logistics networks. The supplier base fragments across integrated Gulf Coast operators, national foodservice distributors, and specialized value-added processors. Three archetypes dominate: vertically integrated harvester-processors controlling dock-to-distribution flows; institutional distributors commanding national frozen and breaded portfolios; and value-added specialists concentrating margin in cooked and seasoned formats. Competitive dynamics center on HACCP compliance infrastructure investment and direct procurement relationships with Ecuadorian and Indian aquaculture cooperatives.
Among integrated processor-distributors, Sysco Corporation exemplifies the institutional distribution archetype with national frozen and breaded shrimp portfolios designed for foodservice volume. Beaver Street Fisheries occupies a position within the Gulf Coast processing corridor, leveraging Jacksonville infrastructure for throughput scale. Trident Seafoods Corp. represents the value-added processing tier competing for retail prepared placement alongside High Liner Foods Inc.
| Leading Market Players |
|---|
| Admiralty Island Fisheries Inc. |
| Beaver Street Fisheries |
| Dulcich Inc. |
| Pacific American Fish Company Inc. |
| Sysco Corporation |
| Trident Seafoods Corp. |
| Thai Union |
| Mazzetta Company LLC |
| High Liner Foods Inc. |
| Others |
Value Network & Pricing Analysis
Wild-caught Gulf brown shrimp versus commodity aquaculture supply creates a sharp bifurcation that manifests in both landed cost structures and cold-chain investment requirements. Premium wild tiers command dockside auction premiums that reflect daily catch variability, while imported aquaculture volumes flow through long-term offtake contracts with Ecuadorian and Indian cooperatives that stabilize unit economics for foodservice distributors.
Pricing Analysis
The bundled-versus-unbundled service split separates commodity frozen blocks from value-added breaded and cooked formats. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and HACCP compliance infrastructure, with FDA-verified supply commanding placement premiums in institutional channels. Pricing pressure stems from feed cost volatility in aquaculture operations, compressing margins for farmed supply dependent on soybean meal and fish oil markets. Quick-service restaurant chains exhibit highest price sensitivity through volume tender processes, while upscale steakhouse buyers prioritize consistent sizing over per-pound cost.
Supply Chain Analysis
Domestic-content preferences embedded in federal procurement guidelines and Gulf Coast state sourcing mandates are reshaping import dependency patterns. Supply concentrates in Ecuador, India, and Indonesia for aquaculture feedstock, with Louisiana and Texas processing corridors handling redistribution. Raw material flows hinge on formulated feed inputs, broodstock genetics, and cold-storage energy costs. Single-source vulnerability runs through concentrated Latin American pond production exposed to climate disruption. Distribution runs through Sysco Corporation and similar institutional distributors with national frozen and breaded portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America shrimp market functions as a stable compounder anchored by protein demand inelasticity and recurring foodservice procurement cycles. Regulatory compliance barriers and capital-intensive cold-chain requirements protect incumbent positions while limiting disruptive entry.
For Market Incumbents: Acquire dedicated HACCP compliance infrastructure and certified cold-chain assets to consolidate Gulf Coast processing capacity. Scale operators should pursue backward integration into Ecuadorian aquaculture cooperatives to secure volume predictability and cost transparency. Emerging traceability mandates from FDA Seafood HACCP modernization threaten smaller regional processors lacking dedicated quality assurance staff, favoring scaled players with IT-enabled record-keeping systems. For New Entrants and Emerging Players: USDA organic aquaculture standards in the United States open a window for certified pond systems and premium retail positioning. White-space targets include refrigerated ready-to-cook marinated formats in supermarket chains and direct-to-consumer frozen delivery with specialized insulated packaging. The most penetrable segment sits in retail organic certification, where compliant feed sourcing and pond management create differentiation from commodity imports. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale processors possessing Gulf Coast dock access and underutilized blast freezing capacity. Long-term viability centers on operators capable of bridging wild harvest variability with stable aquaculture offtake across a five-to-ten year holding period. The signal to watch is consolidation velocity in the Louisiana-Texas corridor as HACCP specialist scarcity and cold-chain capex burdens force smaller players toward exit.| Strategic Initiative | Industry Significance |
|---|---|
| HACCP Infrastructure Investment | FDA compliance mandates reward scaled operators with dedicated quality assurance systems and electronic record-keeping. |
| Direct Aquaculture Procurement | Preferred supplier agreements with Ecuadorian and Indian cooperatives bypass broker layers and secure volume predictability. |
| IQF Technology Upgrade | Individual quick freezing at minus 40 degrees Celsius extends shelf life and preserves texture for broader distribution reach. |
| Traceability Technology Deployment | Blockchain and DNA-based species verification create premium positioning for verified-sustainable supply chains. |
| Retail Ready-to-Cook Expansion | Supermarket chains are expanding refrigerated case space for marinated raw formats beyond frozen commodity blocks. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market informing triangulation. The analysis combines structured interviews with seafood processing executives, foodservice procurement directors, cold-chain logistics operators, and regulatory compliance officers alongside secondary validation. Secondary sources include FDA Seafood HACCP enforcement records, NOAA fisheries landings data, CFIA seafood safety protocols, and customs import documentation. Bottom-up volume modeling and top-down value reconciliation anchor analytical integrity.
Granularity extends to product type, size grade, distribution channel, and end-user application across the projection horizon. Segmentation dimensions encompass frozen versus fresh versus value-added formats, jumbo through small count-per-pound tiers, restaurant versus supermarket versus seafood market channels, and foodservice versus household versus processing company end users. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Feed cost indices and currency fluctuation assumptions inform aquaculture supply modeling.
Forecast precision tightens around the base case; tail outcomes carry wider variance under hypoxic zone expansion in the Gulf of Mexico and shipping lane disruption scenarios affecting Asian import flows. Projections reflect documented assumptions regarding HACCP compliance adoption rates and cold-chain infrastructure investment cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Global Aquaculture Vaccine Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
Global Aquafeed and Aquaculture Additives Market
Aquaculture Innovations
Oman Aquaculture Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
South America Aqua Feed Market
Aquaculture Innovations
Tilapia Market
Aquaculture Innovations
Kuwait Fisheries and Aquaculture Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
Thailand Aquafeed Market
Aquaculture Innovations
Aquaponics Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
Saudi Arabia Aquaculture Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
APAC Aquafeed Market
Aquaculture Innovations
North America Shrimp Feed Market