
 Global Aquafeed and Aquaculture Additives Market | 2026-2036
Global Aquafeed and Aquaculture Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aquafeed and Aquaculture Additives Market Analysis
A shortage of aquatic nutrition specialists and feed formulators with marine biology credentials is redrawing competitive boundaries across the aquafeed value chain. Cargill leverages its integrated oilseed processing infrastructure to secure consistent lipid supply chains for high-performance fish diets. DSM anchors its position through proprietary vitamin and carotenoid premix technologies that reduce oxidative stress in farmed Atlantic salmon. Biomar competes via species-specific formulation capabilities spanning cold-water and tropical aquaculture systems.
Aquafeed and aquaculture additives encompass formulated nutritional inputs and functional compounds—including amino acid premixes, probiotic blends, and astaxanthin concentrates typically dosed at 50-100 mg per kilogram of feed—engineered to optimize growth rates, disease resistance, and flesh pigmentation in intensive fish and shellfish production. Dietary Supplements dominates value capture as marine-derived omega-3 and nucleotide formulations command premium positioning in salmonid and shrimp diets. Feed Additives represents the fastest-expanding category as water-stable probiotic coatings and phytogenic acidifiers displace antibiotic growth promoters under tightening residue standards. Medicinal Ingredients maintains concentrated margin pools where vaccine-adjuvant feed delivery systems address vibriosis and streptococcal infections in warm-water species.
The EU Green Deal's Farm to Fork strategy and REACH chemical registration protocols are elevating formulation transparency requirements and restricting certain synthetic pigment sources across European aquaculture supply chains. Norway's national food safety authority and Vietnam's fisheries quality control department enforce divergent maximum residue limits that compel multinational suppliers to maintain parallel product portfolios. China's Ministry of Agriculture and Rural Affairs mandates feed additive catalog updates that periodically delist growth-promoting compounds, forcing reformulation cycles across Asian contract manufacturers. Stakeholders must monitor regulatory divergence between import markets and pre-validate additive compliance pathways before committing capital to regional production assets.
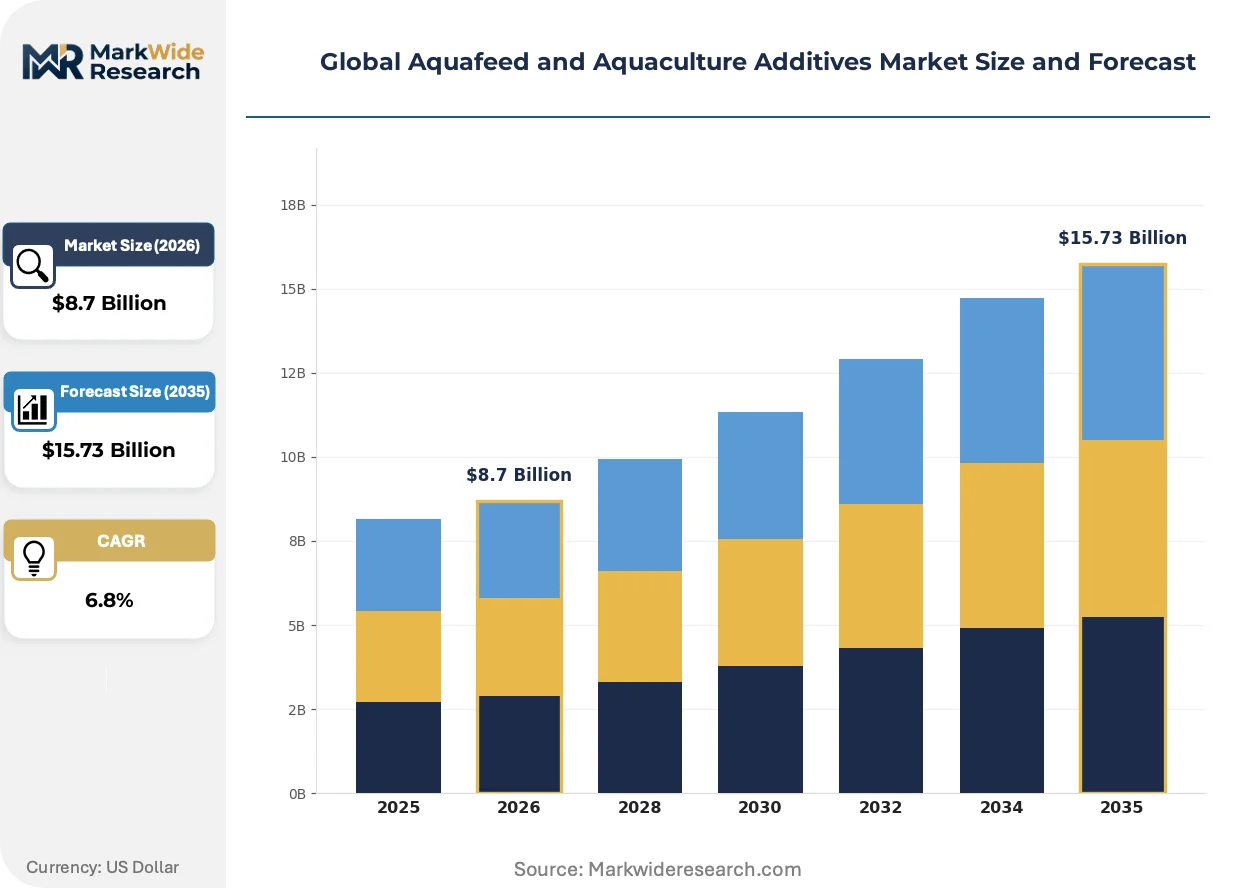
Market Dynamics
Feed additive reformulation cycles are compressing as residue limit divergence between import jurisdictions forces parallel product portfolios. Suppliers must pre-validate compliance pathways across Norway, Vietnam, and China before deploying regional production assets.
Growth Catalysts
- Farm to Fork residue tightening:The EU Green Deal is accelerating shifts toward functional feed additives as synthetic pigment sources face restriction across European aquaculture supply chains.
- Integrated farming system scaling:Vietnam's Mekong Delta aquaculture cluster is concentrating demand for species-specific additive protocols in shrimp and pangasius operations.
- Antibiotic growth promoter displacement:Water-stable probiotic coatings and phytogenic acidifiers are capturing volume as regulatory pressure intensifies on legacy prophylactic use.
Market Restraints
- Marine lipid supply concentration:Fish oil and algal DHA sourcing remains vulnerable to Peruvian anchovy quota volatility and climate-driven El Niño disruption.
- Specialist talent scarcity:The shortage of feed formulators with marine biology credentials limits formulation innovation velocity across mid-tier suppliers.
- REACH registration burden:ECHA chemical catalog protocols elevate compliance costs for novel additive introduction into European markets.
Strategic Opportunities
- India's brackishwater expansion:Andhra Pradesh and Tamil Nadu shrimp zones remain underpenetrated by premium functional additive suppliers serving export-oriented operations.
- Vaccine-adjuvant feed delivery:Warm-water species vibriosis management is opening margin pools for medicinal ingredient categories with therapeutic positioning.
- Carbon-accounting certification:EU CSRD disclosure requirements create preference premiums for feed producers with verified scope-three emission tracking.
Industry Challenges
- Parallel portfolio complexity:Divergent maximum residue limits between Norway's food safety authority and Vietnam's fisheries quality control department strain inventory and labeling systems.
- Catalog delistation risk:China's Ministry of Agriculture and Rural Affairs mandates periodic feed additive catalog updates that force unplanned reformulation without transition timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aquafeed and Aquaculture Additives Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Feed Additives, Medicinal Ingredients, Nutritional Enhancers Application: Fish Farming, Shellfish Production, Aquatic Species Management, Hatchery Operations Distribution Channel: Direct Sales, Wholesale Distribution, E-commerce Platforms, Retail Markets End User: Aquaculture Farms, Research Institutions, Government Agencies, Private Sector |
| Companies Covered | Cargill, Alltech, DSM, Biomar, Evonik Industries, Kemin Industries, Nutreco, BASF, Ridley Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aquafeed and Aquaculture Additives Market Emerging Trajectories
Precision nutrition platforms and regulatory transparency tools are compressing traditional formulation development timelines. Digital traceability systems now accompany physical additive delivery.
Microencapsulated probiotic strains with water-stable coatings are displacing antibiotic growth promoters in intensive salmonid and shrimp diets. Norwegian and Chilean contract manufacturers are adopting these platforms at scale to meet EU import residue standards. The technology is displacing legacy prophylactic protocols that previously dominated warm-water species production.
China's Ministry of Agriculture and Rural Affairs catalog update mechanism is forcing reformulation transparency across Asian contract manufacturing. Producers must now document additive withdrawal periods and residue accumulation profiles before market authorization. Warm-water species feed categories face the most frequent delistation exposure, compressing product lifecycle planning horizons.
Integrated farming clusters in Vietnam's Mekong Delta are consolidating procurement authority toward fewer, larger additive suppliers with multi-species formulation capabilities. Volume aggregation is replacing fragmented distributor networks as farming cooperatives scale. This concentration is most visible in shrimp and pangasius operations targeting EU and US retail certification requirements.
Global Aquafeed and Aquaculture Additives Market Segmentation
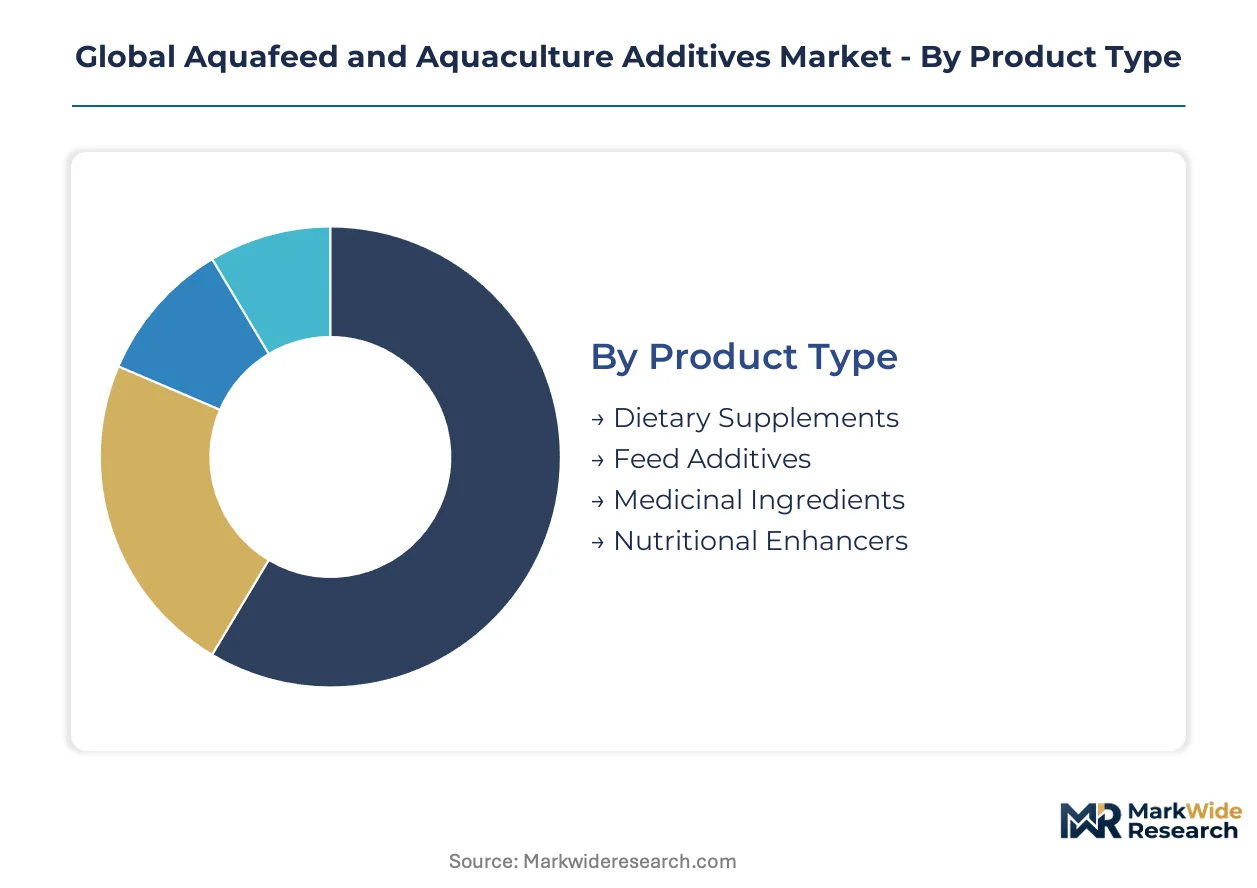
Channel configuration varies sharply across additive categories. Premium functional ingredients favor direct technical relationships with large farming cooperatives, while commodity nutritional inputs move through wholesale networks serving fragmented hatchery operations.
Product Type:
Direct sales channels dominate high-margin specialty additives where technical service bundling justifies relationship-based procurement. Wholesale distribution handles volume nutritional inputs where price transparency and logistics efficiency outweigh formulation support needs.
- Dietary Supplements:Marine-derived omega-3 concentrates and nucleotide formulations engineered for salmonid flesh quality and shrimp stress resistance. Norwegian and Vietnamese contract manufacturers concentrate procurement of these premium inputs as integrated farming systems scale and EU retail certification requirements tighten.
- Feed Additives:Functional compounds including water-stable probiotic coatings, phytogenic acidifiers, and astaxanthin concentrates typically dosed at 50-100 mg per kilogram of feed. Mekong Delta shrimp operations and Chilean salmon farms are displacing antibiotic growth promoters through these platforms as residue limits diverge between import jurisdictions.
- Medicinal Ingredients:Vaccine-adjuvant feed delivery systems targeting vibriosis and streptococcal infections in warm-water species.
- Nutritional Enhancers:Amino acid premixes and vitamin fortification packages for basal diet optimization.
By volume, Nutritional Enhancers leads. By growth pace, Feed Additives is expanding most quickly.
Application:
Cost tier differentiation separates intensive commercial operations from research and conservation applications. Premium pricing attaches to species-specific protocols serving export-certified production, while economy formulations serve domestic market hatcheries.
- Fish Farming:Atlantic salmon and pangasius operations drive species-specific additive demand as flesh pigmentation and growth optimization requirements intensify.
- Shellfish Production:Shrimp farming concentrates additive-intensive feeding protocols in Vietnam's Mekong Delta and India's brackishwater zones.
- Aquatic Species Management:Broodstock conditioning and genetic improvement programs requiring specialized nutritional support.
- Hatchery Operations:Larval-stage microdiets and early nutrition protocols for fry development and survival rate improvement.
Commercial production applications generate the largest revenue pools. Hatchery Operations shows the steepest technology upgrade trajectory as early nutrition science advances.
Distribution Channel:
Customer scale determines channel selection. Large integrated farming cooperatives bypass intermediaries for direct manufacturer relationships, while smaller operations depend on distributor networks for inventory access and credit terms.
- Direct Sales:Technical service-intensive relationships with multinational aquafeed manufacturers and large farming cooperatives.
- Wholesale Distribution:Regional feed compounders and mid-tier farming operations accessing standardized additive portfolios through distributor inventory.
- E-commerce Platforms:Emerging procurement channel for smaller hatcheries and specialized research quantities bypassing traditional distribution minimums.
- Retail Markets:Limited presence concentrated in hobbyist aquarium and ornamental fish segments.
Wholesale Distribution moves the highest tonnage. E-commerce Platforms are gaining share fastest among non-integrated farming operations.
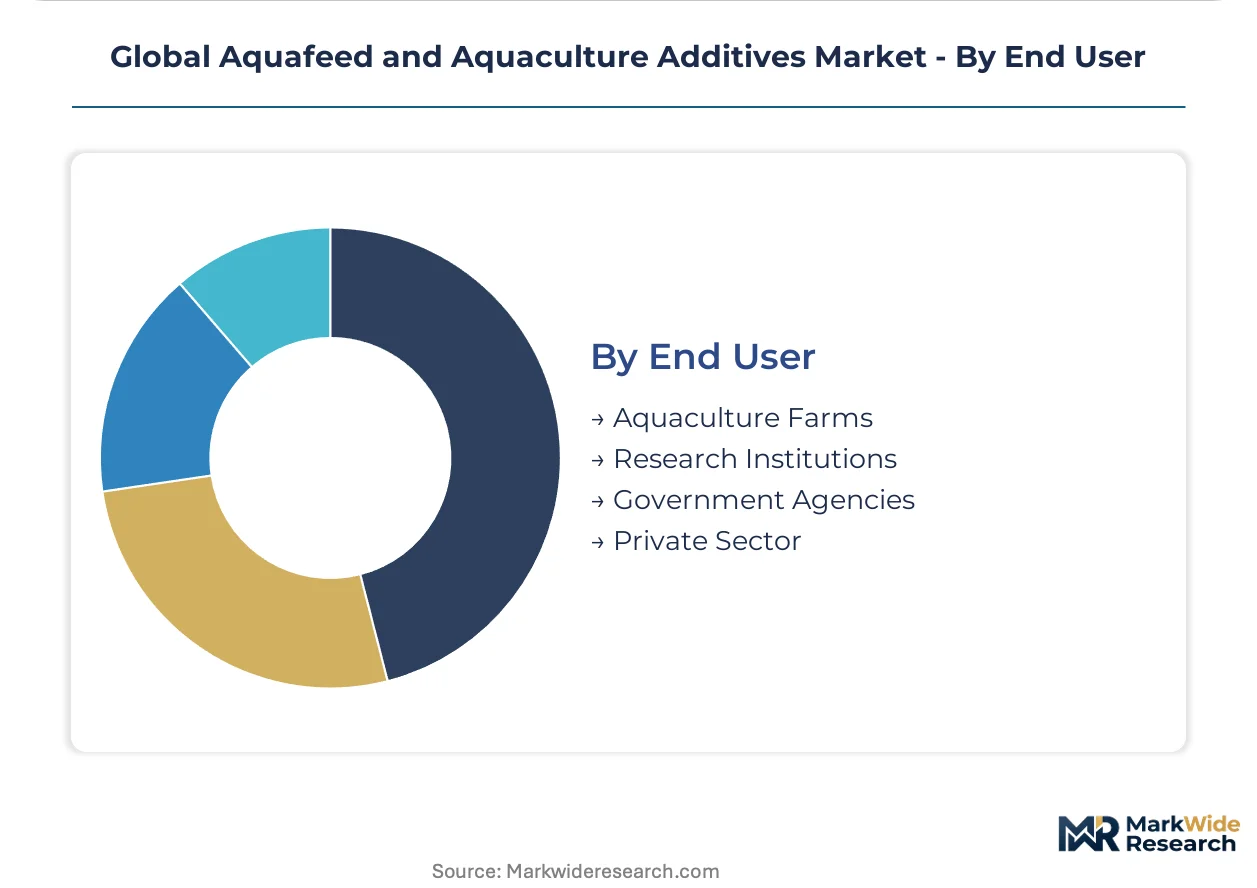
End User:
Maturity gradients separate established commercial farming from emerging research applications. Volume concentrates in scaled production, while margin pools attach to specialized research and therapeutic protocols.
- Aquaculture Farms:Commercial production operations spanning intensive salmonid cages, shrimp ponds, and pangasius raceways.
- Research Institutions:Universities and aquaculture technology centers developing next-generation nutritional protocols and stress resistance formulations.
- Government Agencies:Fisheries extension services and quality control departments mandating additive catalog compliance and residue monitoring.
- Private Sector:Aquafeed manufacturers, ingredient traders, and certification bodies supporting supply chain transparency.
Aquaculture Farms represent the dominant volume segment. Research Institutions show the fastest budget expansion as precision nutrition platforms commercialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major aquafeed markets. Norway prioritizes salmonid flesh quality and pigment compliance, while Vietnam concentrates on shrimp antibiotic displacement. China's regulatory volatility forces rapid reformulation cycles distinct from stable EU protocols.
Norway
Atlantic salmon farming drives demand for carotenoid premixes and oxidative stress reducers. The Norwegian Food Safety Authority enforces strict maximum residue limits that exceed EU baselines. Bergen and Trondheim host formulation R&D clusters serving North Sea cage operations.
Vietnam
Mekong Delta shrimp and pangasius expansion concentrates additive procurement among farming cooperatives. The fisheries quality control department maintains divergent residue standards from European import markets. Can Tho and An Giang provinces aggregate volume demand for water-stable probiotic coatings.
China
Domestic aquaculture scale sustains massive amino acid and vitamin premix consumption. The Ministry of Agriculture and Rural Affairs mandates periodic additive catalog updates that delist growth promoters without transition timelines. Guangdong and Hainan provinces face the most frequent reformulation pressure in warm-water species feed.
Chile
Salmonid export certification requirements elevate functional additive specifications above regional peers. SERNAPESCA residue monitoring aligns with EU retail standards for antibiotic-free claims. Puerto Montt and Chiloé Island processing clusters source species-specific formulations for cold-water production.
India
Andhra Pradesh and Tamil Nadu brackishwater shrimp zones remain underpenetrated by premium functional additive suppliers. The Food Safety and Standards Authority of India tightens import residue surveillance on export-oriented operations. Visakhapatnam and Nellore districts concentrate contract manufacturing for Middle Eastern and European buyers.
Global Aquafeed and Aquaculture Additives Market Vendor Landscape
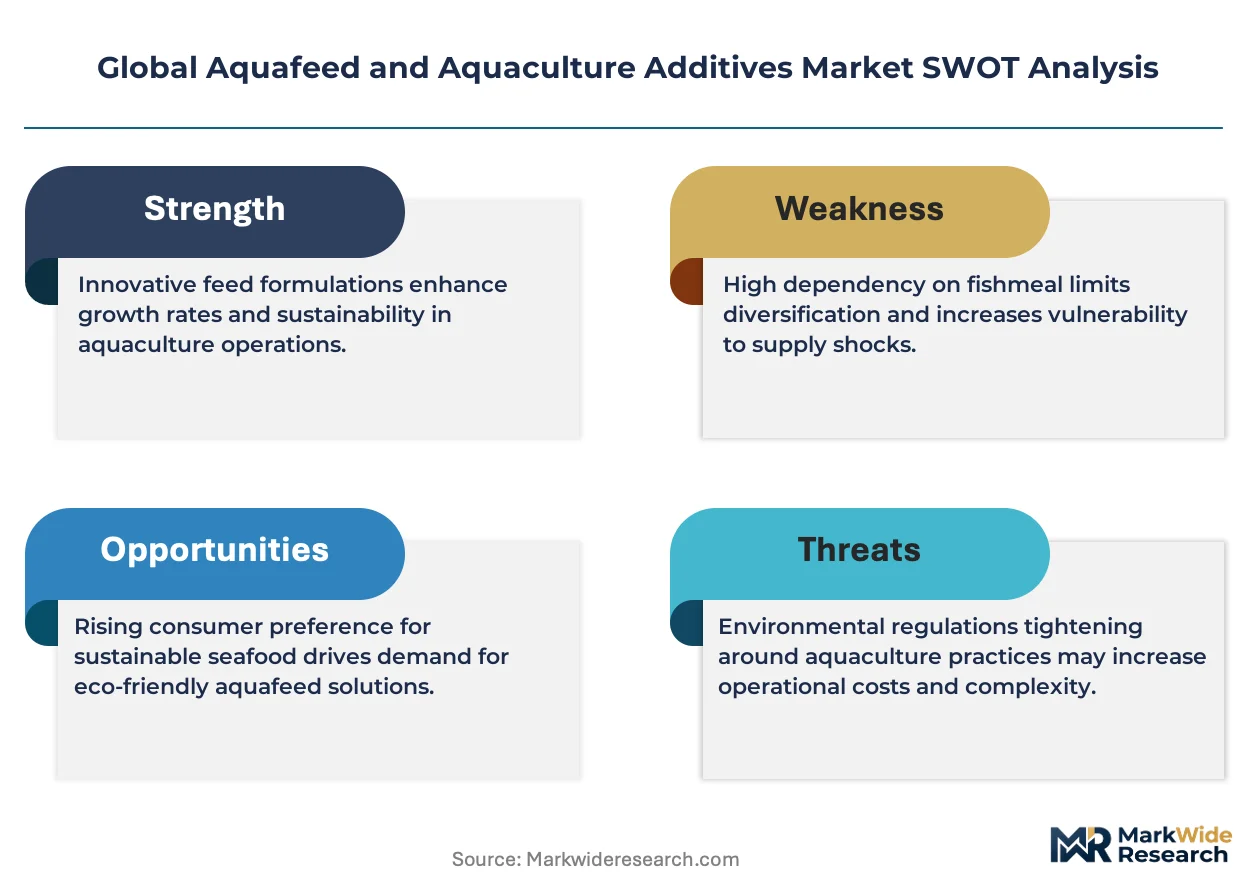
A small set of integrated leaders sits above a broader specialist tier in aquafeed additives. Oilseed processors and chemical conglomerates occupy the upper tier through captive supply chains, while marine biology specialists compete on formulation velocity. Three archetypes dominate: integrated agribusinesses with lipid infrastructure, life-science multinationals with vitamin premix IP, and species-specific contract manufacturers. Competitive moves center on backward integration into algal DHA sourcing and parallel portfolio maintenance for divergent regulatory jurisdictions.
Among integrated agribusinesses, Cargill anchors the lipid supply tier through oilseed processing infrastructure. DSM occupies the life-science specialist position with proprietary vitamin and carotenoid technologies. Biomar exemplifies the species-specific formulation archetype spanning cold-water and tropical systems.
| Leading Market Players |
|---|
| Cargill |
| Alltech |
| DSM |
| Biomar |
| Evonik Industries |
| Kemin Industries |
| Nutreco |
| BASF |
| Ridley Corporation |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for Peruvian fish oil concentrates concentrate pricing power among vertically integrated compounders with cold-storage assets in Bergen and Puerto Montt. Contract structures and supply geography together determine margin capture across functional additive tiers.
Pricing Analysis
Long-term offtake agreements covering 60-70 percent of marine lipid volumes anchor pricing stability for Norwegian and Chilean salmon feed compounders, while spot procurement dominates probiotic and phytogenic acidifier transactions among Vietnamese shrimp cooperatives. Price differentiation separates EU retail-certified additive bundles from economy-grade hatchery inputs, with certification tier and volume scale as primary drivers. Pricing pressure stems from REACH registration cost recovery demands on novel European additives. Smallholder hatcheries in India's brackishwater zones exhibit highest price sensitivity; integrated Mekong Delta cooperatives prioritize technical service bundling over unit cost.
Supply Chain Analysis
Peruvian anchovy landing volatility at the Strait of Magellan transshipment node exposes global omega-3 concentrate flows to El Niño disruption cycles. Raw material sourcing concentrates in Peru for fishmeal, China for algal DHA fermentation, and Norway for high-purity astaxanthin extraction. The chain rests on marine lipid seasonality, vitamin premix chemical inputs, and water-stable coating polymers. Single-source vulnerability runs through Peruvian quota-dependent suppliers. Distribution runs through direct technical sales to integrated cooperatives and wholesale networks serving fragmented hatcheries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EU, Vietnamese, and Chinese residue protocols fragments procurement authority, creating specialist formulation niches for suppliers with parallel portfolio capabilities.
For Market Incumbents: Secure backward integration into algal DHA cultivation to reduce Peruvian anchovy quota exposure, and lock multi-year technical service contracts with Mekong Delta cooperatives before volume aggregation consolidates procurement. DSM and Biomar face emerging competition from Chinese state-backed compounders with catalog-compliant warm-water portfolios. Certification investment in EU Green Deal traceability systems offers defensive positioning. For New Entrants and Emerging Players: Differentiate on species-specific formulation velocity for India's underpenetrated Andhra Pradesh shrimp zones, where export-oriented operations lack premium functional additive relationships. Target vaccine-adjuvant feed delivery systems for vibriosis management as medicinal ingredient margins detach from commodity nutritional inputs. Go-to-market through direct technical partnerships with large farming cooperatives bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance burdens and catalog delistation risks favor scaled suppliers with parallel R&D infrastructure across cold-water and tropical protocols. Acquisition targets include mid-tier contract manufacturers with validated residue pathways in both EU and Asian jurisdictions. Watch China's Ministry of Agriculture catalog update frequency as an inflection signal for reformulation cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algal DHA | Reduces exposure to Peruvian anchovy quota volatility for Norwegian compounders. |
| Parallel Portfolio Maintenance | Enables simultaneous compliance with EU REACH and Vietnamese fisheries residue standards. |
| Species-Specific Formulation Partnerships | Captures Mekong Delta cooperative procurement as volume aggregation displaces distributors. |
| Vaccine-Adjuvant Feed Delivery Development | Opens therapeutic margin pools for vibriosis management in warm-water shrimp operations. |
| Carbon-Accounting Certification Investment | Creates preference premiums under EU CSRD scope-three disclosure requirements for feed producers. |
Methodological Framework
Cross-validation between trade flow databases and regulatory filing records anchors the qualitative findings on catalog delistation patterns and residue limit divergence. Primary interviews with aquafeed formulation directors, fisheries quality control officers, and marine lipid procurement managers combined with secondary validation through customs export data, EU ECHA registration filings, and Vietnamese Ministry of Agriculture circulars. Bottom-up additive consumption estimates and top-down aquaculture production statistics triangulate market sizing.
Sensitivity analysis on Peruvian anchovy landing scenarios and Chinese catalog update frequencies shapes the projection framework across the analysis window. Segmentation dimensions include product type, species application, distribution channel, and regulatory jurisdiction cluster. CAGRs derive from additive intensity coefficients applied to aquaculture production forecasts, with marine lipid price volatility and probiotic adoption curves as key inputs.
Material uncertainties — El Niño disruption severity, unscheduled Chinese additive catalog revisions, and EU Green Deal implementation timing — sit outside the modeled envelope. Forecasts reflect documented assumptions on residue limit convergence patterns and integrated farming system scaling trajectories. Practitioners should keep alternative scenarios live as regulatory divergence and climate-driven raw material availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Salmon Feed Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Kuwait Fisheries and Aquaculture Market
Aquaculture Innovations
South Korea Aquaculture Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Global Ornamental Fish Feed Market
Aquaculture Innovations
Vietnam Aquafeed Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
Aquaculture Water Quality and Biomass Monitoring Test Equipment Market
Aquaculture Innovations
Ornamental Fish Market