
 Aquaculture Cage Market | 2026-2036
Aquaculture Cage Market Size, Share, and Industry Trends Forecast 2026-2036
Aquaculture Cage Market Analysis
Consolidation among commercial salmon farming operators is repositioning procurement power toward fewer, larger buyers across North Atlantic markets. AKVA Group leverages its integrated software-hardware platform to anchor long-term service contracts with these consolidated operators. Selstad AS sustains manufacturing scale across its Norwegian production base, competing on delivery speed for high-volume cage orders. Badinotti Group S.p.A. specializes in netting material engineering, differentiating through polymer formulations that extend service life in high-biofouling waters.
An aquaculture cage is a contained enclosure system, typically constructed from high-density polyethylene frames and synthetic fiber netting with anti-fouling coatings, designed to hold fish in open-water environments while permitting water exchange. These structures enable controlled feeding, health monitoring, and harvest in marine or freshwater settings where land-based pond construction is impractical. Floating cage technology dominates installed base across sheltered coastal sites, though submersible cages are gaining structural momentum in exposed high-energy locations where surface storms damage conventional systems. Fish farming application generates the largest margin pool, while shellfish farming operates on thinner equipment economics due to lower per-unit cage complexity.
Norwegian Food Safety Authority standards, Chilean SUBPESCA aquaculture concessions, and ISO 21600 aquaculture equipment specifications collectively shape cage design mandates, material traceability, and site licensing timelines across major production zones. These frameworks elevate capital requirements for new entrants while rewarding incumbents with certified supply chains and documented environmental compliance. Stakeholders must monitor regulatory divergence between North Atlantic and South Pacific jurisdictions when configuring product portfolios and service networks.
Market Dynamics
Consolidation among Atlantic salmon producers is compressing procurement timelines and elevating technical compliance requirements for cage system vendors. Norwegian Food Safety Authority mandates on escape prevention and sea lice management now dictate material specifications and inspection protocols that smaller fabricators cannot satisfy.
Growth Catalysts
- Chilean SUBPESCA concession expansion:New aquaculture zone allocations in Los Lagos and Aysén regions are triggering fleet renewal cycles among established operators seeking larger-scale cage systems.
- High-density polyethylene formulation advances:UV-stabilized polymer compounds are extending structural service intervals in high-latitude waters, reducing replacement frequency for floating collar systems.
- Shellfish farming mechanization:Automated feeding and monitoring integration is expanding addressable equipment spend beyond finfish into oyster and mussel production clusters.
Market Restraints
- Petrochemical input volatility:HDPE and synthetic fiber netting remain tethered to crude oil derivative pricing, compressing fabrication margins during energy price spikes.
- Norwegian supplier concentration:Three domestic equipment groups control certified supply chains for North Atlantic salmon producers, limiting price negotiation leverage for buyers.
- Submersible cage technical immaturity:Depth-adjustment mechanisms and biofouling management on submerged structures remain operationally unproven at commercial scale.
Strategic Opportunities
- Scottish west coast licensing:Pending Crown Estate Scotland site allocations could unlock greenfield cage demand among mid-tier operators excluded from Norwegian concessions.
- Integrated sensor platforms:Convergence of underwater cameras, dissolved oxygen probes, and AI-driven feeding algorithms is creating bundled hardware-software contract opportunities.
- EU Green Deal aquaculture funding:Carbon footprint reduction incentives are steering public capital toward energy-efficient cage designs and shore-based monitoring infrastructure.
Industry Challenges
- Marine polymer welding certification:Qualified technicians for HDPE joint fabrication remain scarce relative to installation demand, elongating project timelines.
- ISO 21600 compliance documentation:Traceability requirements for netting origin and coating chemistry are extending pre-delivery administrative cycles by four to eight weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquaculture Cage Market |
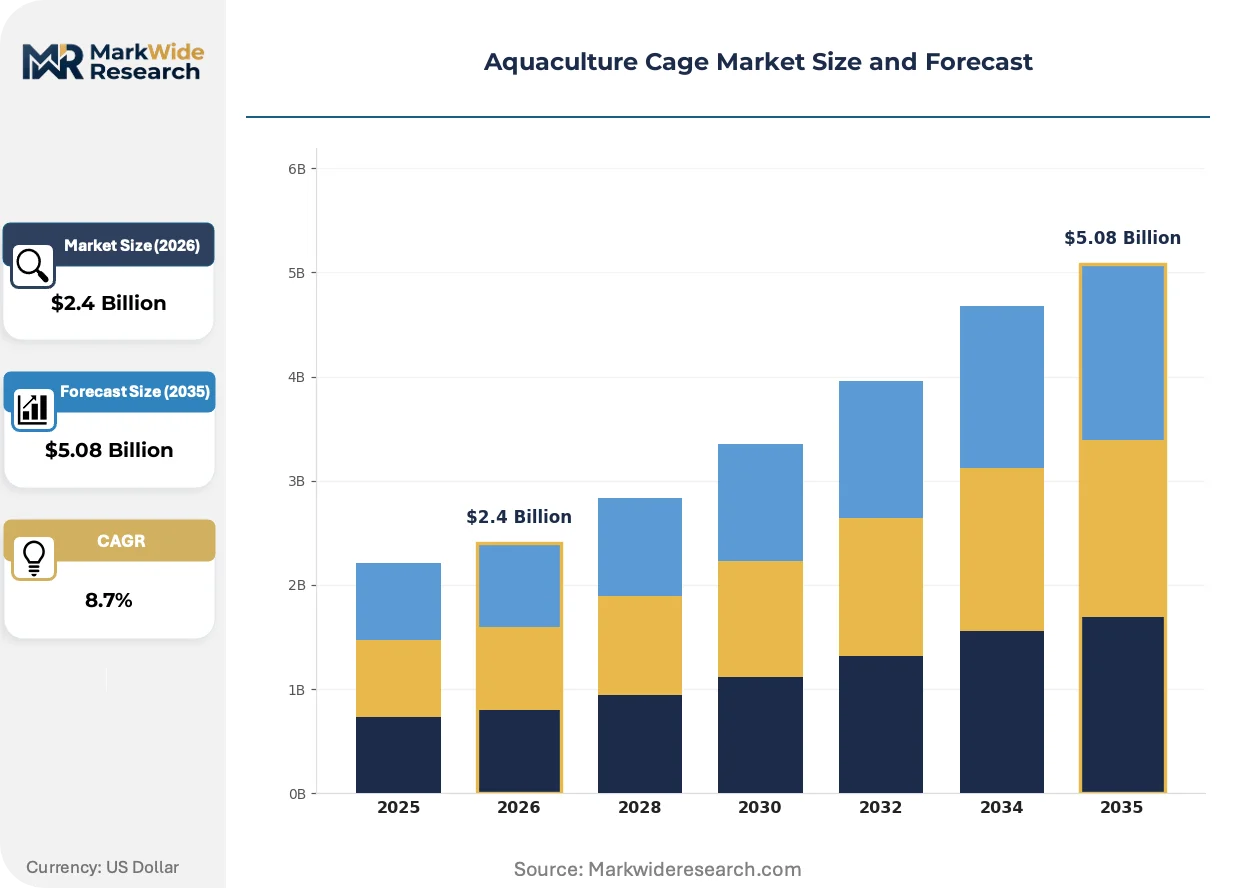
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Floating Cages, Submersible Cages, Fixed Cages, Pen Systems End User: Commercial Farms, Research Institutions, Government Agencies, Academic Organizations Material: Netting Materials, Frame Materials, Coatings, Floats Application: Fish Farming, Shellfish Farming, Larval Rearing, Aquatic Plant Cultivation |
| Companies Covered | AKVA Group, Selstad AS, Badinotti Group S.p.A., Garware Technical Fibres, Qingdao Qihang Fishing Cage Co., Ltd., AquaMaof, Aqualine AS, Fusion Marine Ltd., Gesikat Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquaculture Cage Market Emerging Trajectories
Digital monitoring integration and structural material evolution are redefining performance benchmarks for open-water containment systems. Vendors now compete on data capture density and predictive maintenance capability rather than physical durability alone.
Submersible cage technology is decentralizing site selection constraints for salmon producers. These systems descend below surface turbulence during storm events, enabling farming in exposed North Sea locations previously classified as unsuitable. Mowi and Lerøy are piloting units off Frøya and Hitra, with initial results indicating 40% lower storm damage incidence versus floating equivalents. This capability is compressing the premium commanded by sheltered fjord sites.
EU REACH chemical authorization restrictions are phasing out copper-based anti-fouling coatings on netting materials. The industrial consequence is accelerated R&D into silicone-based and biocide-free surface treatments that satisfy environmental release standards. Norwegian producers are most affected, with Norsk Industri reporting reformulation costs absorbed through equipment lease rate adjustments rather than capital price increases.
Buyer consolidation is compressing vendor negotiation cycles and unbundling service components. Large salmon groups now separate cage procurement from installation and maintenance contracts, pitting specialized service providers against integrated suppliers. This pattern is most visible in Norway, where Grieg Seafood and SalMar have adopted multi-source equipment strategies with single-source software platforms for feed optimization and mortality tracking.
Aquaculture Cage Market Segmentation
Aquaculture cage procurement patterns diverge sharply across technology platforms and end-use contexts. Material specifications and regulatory compliance requirements create distinct buyer profiles that reshape vendor positioning strategies.
Technology:
Site exposure and storm risk tolerance separate buyers into fundamentally different equipment categories.
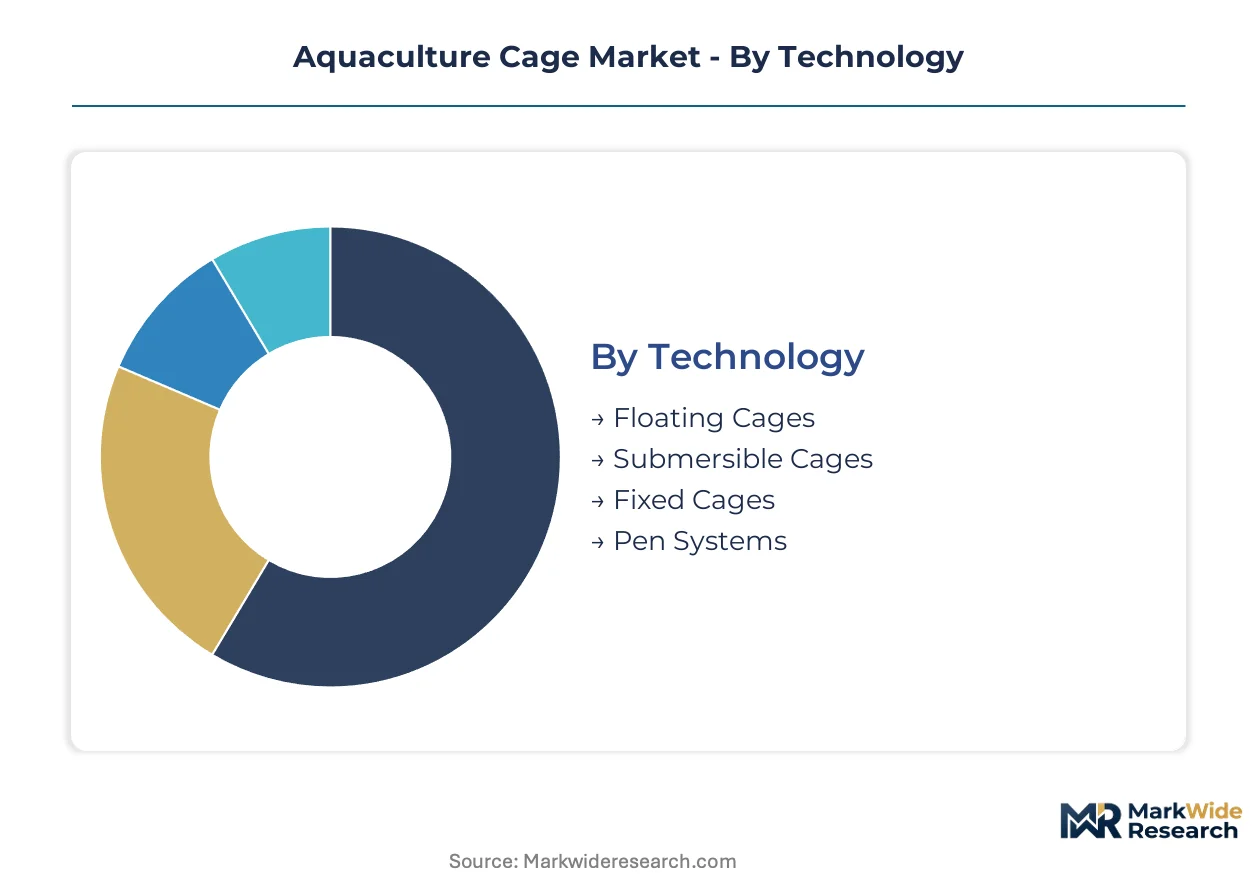
- Floating Cages:Surface-suspended systems with HDPE collar assemblies and synthetic fiber netting dominate sheltered coastal installations. Norwegian fjord operators and Chilean Los Lagos farms concentrate procurement here, driven by established supply chains and lower capital thresholds.
- Submersible Cages:Depth-adjustable structures descend below wave action during storm events, enabling farming in exposed North Sea locations. Mowi and Lerøy pilot programs off Frøya and Hitra validate 40% lower storm damage incidence, compressing premiums for sheltered sites.
- Fixed Cages:Bottom-anchored systems in shallow protected waters serve shellfish and larval applications with minimal capital outlay.
- Pen Systems:Rigid enclosure configurations with metal or composite framing suit research and controlled-environment farming.
Volume sits with Floating Cages; growth tilts toward Submersible Cages.
End User:
Scale and procurement authority fragment cage demand across institutional and commercial buyers.
- Commercial Farms:Consolidated salmon operators in Norway and Chile command multi-unit fleet orders with integrated service contracts. AKVA Group and Selstad AS anchor supply relationships through software-hardware bundling and certified installation capacity.
- Research Institutions:Experimental breeding and stress-testing applications require customized pen configurations with sensor integration.
- Government Agencies:Stock enhancement and public fishery programs in Scotland and Canada specify traceable netting origin per ISO 21600 mandates.
- Academic Organizations:University marine stations prioritize modular, reconfigurable systems for teaching and small-scale trials.
Commercial Farms absorb the majority of unit volume; Research Institutions show the steepest expansion trajectory for sensor-integrated configurations.
Material:
Component-level specifications determine service intervals and regulatory compliance pathways.
- Netting Materials:Synthetic fiber meshes with anti-fouling coatings constitute the largest material spend category. EU REACH restrictions on copper-based treatments accelerate silicone-based and biocide-free formulation R&D, with Norwegian producers absorbing reformulation costs through lease rate adjustments.
- Frame Materials:UV-stabilized HDPE compounds extend structural service intervals in high-latitude waters, reducing replacement frequency for floating collar systems.
- Coatings:Surface treatments for biofouling resistance face tightening environmental release standards across North Atlantic jurisdictions.
- Floats:Buoyancy elements in foam-filled or air-pressurized configurations complete collar assembly systems.
Netting Materials command the highest replacement frequency; Frame Materials are gaining share fastest as HDPE formulation advances extend service life.
Application:
Biological complexity and harvest value shape equipment specification intensity.
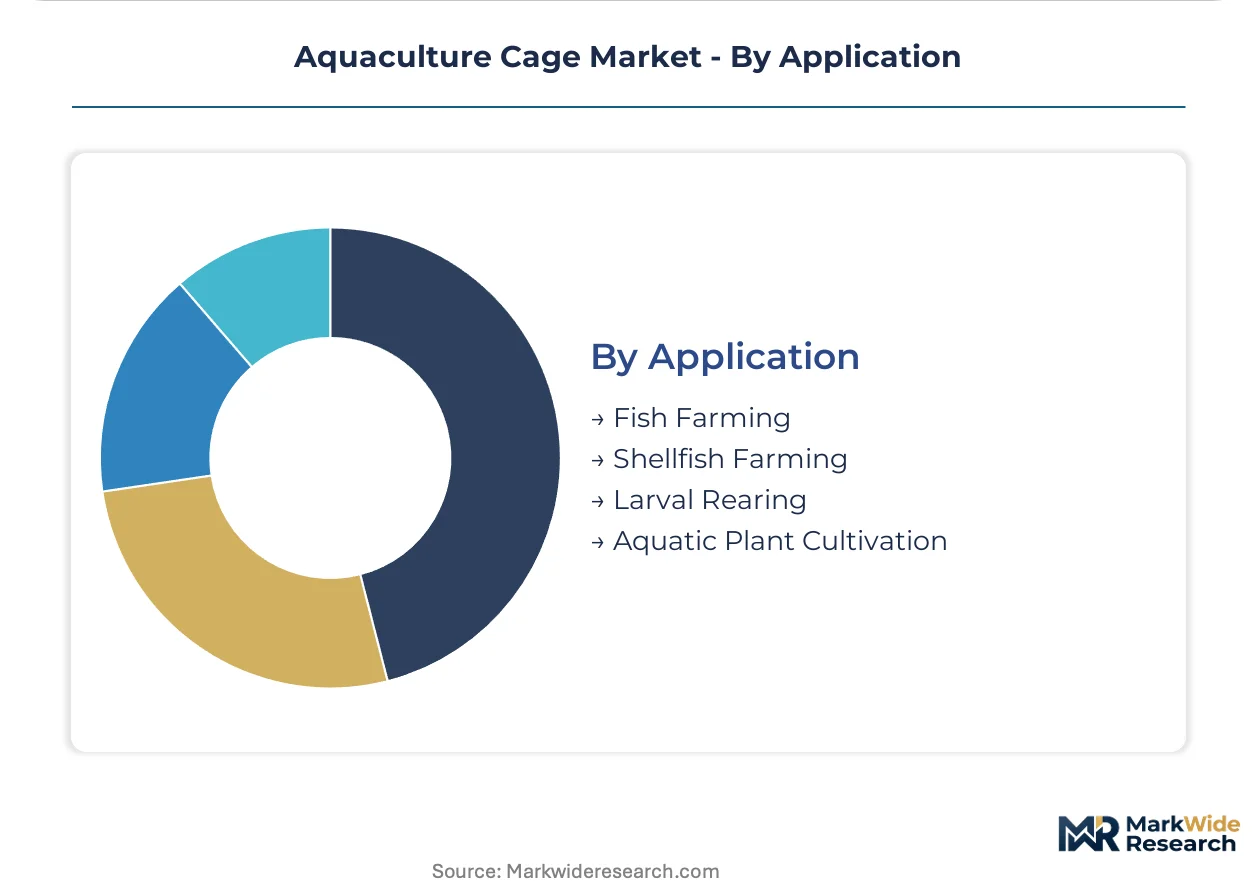
- Fish Farming:Finfish containment generates the largest margin pool, with automated feeding and mortality tracking systems elevating per-cage equipment spend. Salmon dominates, though trout and sea bass operations in the Mediterranean and Turkey expand addressable demand.
- Shellfish Farming:Oyster and mussel production operates on thinner equipment economics due to lower per-unit cage complexity, though mechanization is expanding addressable spend.
- Larval Rearing:Fine-mesh enclosures for juvenile stock require specialized netting specifications and intensive monitoring.
- Aquatic Plant Cultivation:Seaweed farming applications utilize simplified frame structures with minimal netting requirements.
Fish Farming concentrates revenue; Shellfish Farming is expanding most quickly as automation penetrates traditional manual operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial salmon farming concentrates procurement power across North Atlantic and South Pacific coastal zones. Norwegian fjord systems and Chilean fjord networks absorb the majority of high-specification cage orders. Regulatory divergence between these jurisdictions reshapes vendor certification requirements and service network deployment.
Norway
Consolidated salmon operators command multi-unit fleet renewals with integrated software contracts. Norwegian Food Safety Authority mandates on escape prevention and sea lice management dictate material specifications and inspection protocols. The Frøya-Hitra cluster off Trøndelag hosts submersible cage pilot programs validating storm damage reduction.
Chile
SUBPESCA concession expansion in Los Lagos and Aysén regions triggers fleet renewal cycles among established operators. Aquaculture environmental licensing requirements tighten water column monitoring and fallowing period enforcement. Puerto Montt anchors fabrication capacity serving southern zone concession holders.
Scotland
Crown Estate Scotland licensing allocations could unlock greenfield demand among mid-tier operators excluded from Norwegian concessions. Marine Scotland regulatory frameworks impose containment integrity standards and sea lice management plans. The Shetland Islands cluster concentrates exposed-site farming operations requiring reinforced collar specifications.
Canada
Health Canada and Fisheries and Oceans Canada oversight shapes netting material approval pathways for British Columbia salmon farms. Indigenous consultation requirements extend site licensing timelines for new entrants. The Campbell River area on Vancouver Island hosts service infrastructure supporting Pacific coast operations.
China
Offshore aquaculture development plans under MIIT guidance steer capital toward deep-water cage systems in the Yellow Sea and East China Sea. GB standards for aquaculture equipment establish baseline material specifications for domestic fabricators. The Shandong Peninsula cluster concentrates HDPE processing capacity for collar assembly production.
Aquaculture Cage Market Vendor Landscape
Norwegian producers anchor one tier; Chinese fabricators hold cost-competitive positioning for standardized floating systems. The vendor base separates into integrated platform providers, specialized netting engineers, and regional fabrication specialists. Three strategic archetypes dominate: software-hardware bundlers, material science specialists, and scale-driven manufacturers. Consolidation among Atlantic salmon producers compresses procurement timelines, while concession expansion in Chile triggers geographic diversification moves.
Within the integrated platform tier, AKVA Group represents the software-hardware bundling archetype anchoring long-term service relationships. Selstad AS exemplifies scale-driven manufacturing capacity competing on delivery velocity for high-volume orders. Badinotti Group S.p.A. occupies a position as the material science specialist differentiating through polymer formulation expertise for high-biofouling environments.
| Leading Market Players |
|---|
| AKVA Group |
| Selstad AS |
| Badinotti Group S.p.A. |
| Garware Technical Fibres |
| Qingdao Qihang Fishing Cage Co., Ltd. |
| AquaMaof |
| Aqualine AS |
| Fusion Marine Ltd. |
| Gesikat Ltd. |
| Others |
Supply Flow & Price Mechanics
Polyethylene resin price indices cascade through aquaculture cage fabrication into three distinct procurement tiers. HDPE collar assemblies and synthetic fiber netting absorb petrochemical volatility, compressing margins for mid-tier fabricators while integrated Norwegian suppliers pass cost adjustments through lease rate structures.
Pricing Analysis
Volume concentrates in standardized floating cage systems with thinner margins, while submersible configurations and sensor-integrated platforms capture premium positioning. Three-tier pricing structure across certified premium, standard compliance, and economy-grade equipment separates buyers by Norwegian Food Safety Authority certification status and ISO 21600 traceability documentation. Pricing pressure stems from Chilean SUBPESCA concession expansion triggering fleet renewal demand that outstrips certified installation capacity. Consolidated salmon operators in Norway exhibit lowest price sensitivity due to bundled software-hardware contracts, while mid-tier Scottish operators excluded from Norwegian concessions face acute budget constraints.
Supply Chain Analysis
Refurbishment flows for HDPE collar assemblies and netting recapture extend service intervals and compress replacement demand cycles. Raw material concentration centers on Norwegian petrochemical processing for UV-stabilized HDPE compounds, Chinese synthetic fiber production for mesh substrates, and Italian polymer formulation for anti-fouling coatings. Supply chain risk manifests in single-source vulnerability for marine polymer welding technicians qualified to Norwegian certification standards. Distribution runs through direct vendor relationships with consolidated salmon operators, supplemented by regional fabrication specialists serving government stock enhancement programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine polymer welding technician scarcity constrains installation capacity, propping pricing power for certified Norwegian suppliers despite concession expansion in competing jurisdictions.
For Market Incumbents: Deploy backward integration into HDPE compounding capacity to secure raw material cost control against petrochemical volatility. AKVA Group and Selstad AS should expand certified technician training pipelines to capture installation bottleneck premiums, while Badinotti Group S.p.A. accelerates silicone-based anti-fouling formulation R&D ahead of EU REACH copper phase-out deadlines. For New Entrants and Emerging Players: Regional fabrication specialists in Scotland and Canada represent the most penetrable channel partner type for mid-tier operators excluded from Norwegian supply relationships. White-space targets include sensor-integrated submersible cage servicing for exposed-site salmon farms and automated shellfish farming equipment for Mediterranean oyster producers. Go-to-market positioning should emphasize rapid installation velocity against Norwegian incumbent delivery backlogs. For Investors and Strategic Acquirers: Distressed-cycle entries favor material science specialists with polymer formulation IP in Italian and Spanish coastal zones facing EU environmental compliance upgrades. Long-term viability favors vendors with software-hardware bundling capability and documented ISO 21600 certification pathways. Monitor Chilean SUBPESCA licensing adjudication timelines as inflection indicator for southern hemisphere demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Polymer Welding Certification Program | Addresses technician scarcity elongating Norwegian installation timelines. |
| Silicone-Based Anti-Fouling Formulation Launch | Preempts EU REACH copper restrictions affecting netting replacement economics. |
| Submersible Cage Platform Integration | Enables exposed North Sea farming previously classified as unsuitable. |
| Sensor-Hardware Bundling Expansion | Captures consolidated salmon operator procurement for mortality tracking systems. |
| Scottish West Coast Service Network Buildout | Positions for Crown Estate Scotland licensing allocations among mid-tier operators. |
Methodological Framework
Multi-period observation of HDPE resin pricing, Norwegian installation capacity utilization, and Chilean concession adjudication timelines anchored the trend analysis, supplemented by interviews with aquaculture equipment procurement directors at consolidated salmon operators, marine polymer welding technicians, SUBPESCA licensing officials, and synthetic fiber netting manufacturers. Secondary validation drew from Norwegian Food Safety Authority inspection protocols, EU REACH chemical authorization databases, ISO 21600 equipment specifications, and trade flow data for aquaculture machinery. Bottom-up unit demand modeling triangulated against top-down market value estimates.
Input-output matrices mapped cage unit demand across technology platforms, material specifications, and end-user categories over the projection horizon. Segmentation dimensions included floating versus submersible versus fixed cage architectures, commercial farm versus research institution versus government agency procurement authority, and HDPE frame versus synthetic netting versus coating material spend. CAGRs derived from regression analysis of historical installation volumes against concession expansion schedules and fleet renewal cycles. Industry-specific inputs incorporated storm damage incidence rates from Frøya-Hitra pilot programs and biofouling service interval data from high-latitude deployments.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to Norwegian sea lice management protocols, breakthrough advances in biocide-free surface treatments, and geopolitical disruption to petrochemical supply chains. Forecasts reflect documented assumptions regarding concession allocation timelines and certification pathway stability. Practitioners should monitor SUBPESCA environmental licensing enforcement intensity and EU Green Deal aquaculture funding disbursement rates for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
Ecuador Shrimp Feed Market
Aquaculture Innovations
Vietnam Aquaculture Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
Crab Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
North America Aqua Feed Market
Aquaculture Innovations
Saudi Arabia Aquaculture Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
Egypt Aquafeed Market
Aquaculture Innovations
Norway Aquaculture Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
United States Ornamental Fish Market
Aquaculture Innovations
Fish Breeding Tank Market