
 Aquaponics Market | 2026-2036
Aquaponics Market Size, Share, and Industry Trends Forecast 2026-2036
Aquaponics Market Intelligence
The gap between premium turnkey aquaponics systems and commodity component kits is broadening in ways that reshape supplier economics. Nelson and Pade, Inc. dominates the high-end commercial segment with integrated system designs that command sustained margin pools. ECF Farmsystems GmbH competes through urban vertical installations that anchor its position in European metropolitan food production. Hydrofarm Holdings Group, Inc. leverages its distribution scale to supply hobbyist-grade components across multiple channels.
Aquaponics denotes a closed-loop cultivation method where fish waste metabolizes into plant nutrients through nitrifying bacteria, typically operating at water temperatures between 18-30°C and pH ranges of 6.8-7.2 for optimal biological conversion. The technique eliminates synthetic fertilizer inputs while yielding both protein and vegetable outputs from a single water reservoir. Media-based systems occupy the largest installed base due to lower technical barriers and familiar operational parallels to soil gardening. Vertical aquaponics configurations represent the fastest-expanding category as urban real estate constraints force production into three-dimensional footprints. Deep water culture segments concentrate margin pools in commercial lettuce and leafy green operations where harvest cycles compress to six-week intervals.
The EPA's Clean Water Act provisions and state-level agricultural water quality standards in California, Arizona, and Texas shape system design requirements for commercial operators discharging into municipal treatment networks. FDA's Food Safety Modernization Act traceability rules are pressing commercial farms toward automated monitoring platforms that document water chemistry and harvest chain-of-custody. Stakeholders must weigh capital intensity against regulatory compliance automation as the primary strategic fork determining competitive survival.
Market Dynamics
Water scarcity mandates across arid southwestern United States states are compressing adoption timelines for soilless cultivation systems, forcing municipal water restrictions to function as de facto regulatory accelerators for commercial aquaponics deployment.
Growth Catalysts
- EU Green Deal sustainable agriculture mandates:Certification requirements for closed-loop food production are accelerating commercial system installations across European metropolitan zones.
- Deep water culture technology:Compressed six-week harvest cycles for lettuce and leafy greens are pulling commercial operators toward higher-output configurations.
- California agricultural water quality standards:Discharge regulations into municipal treatment networks are mandating automated monitoring platforms that document chain-of-custody.
Market Restraints
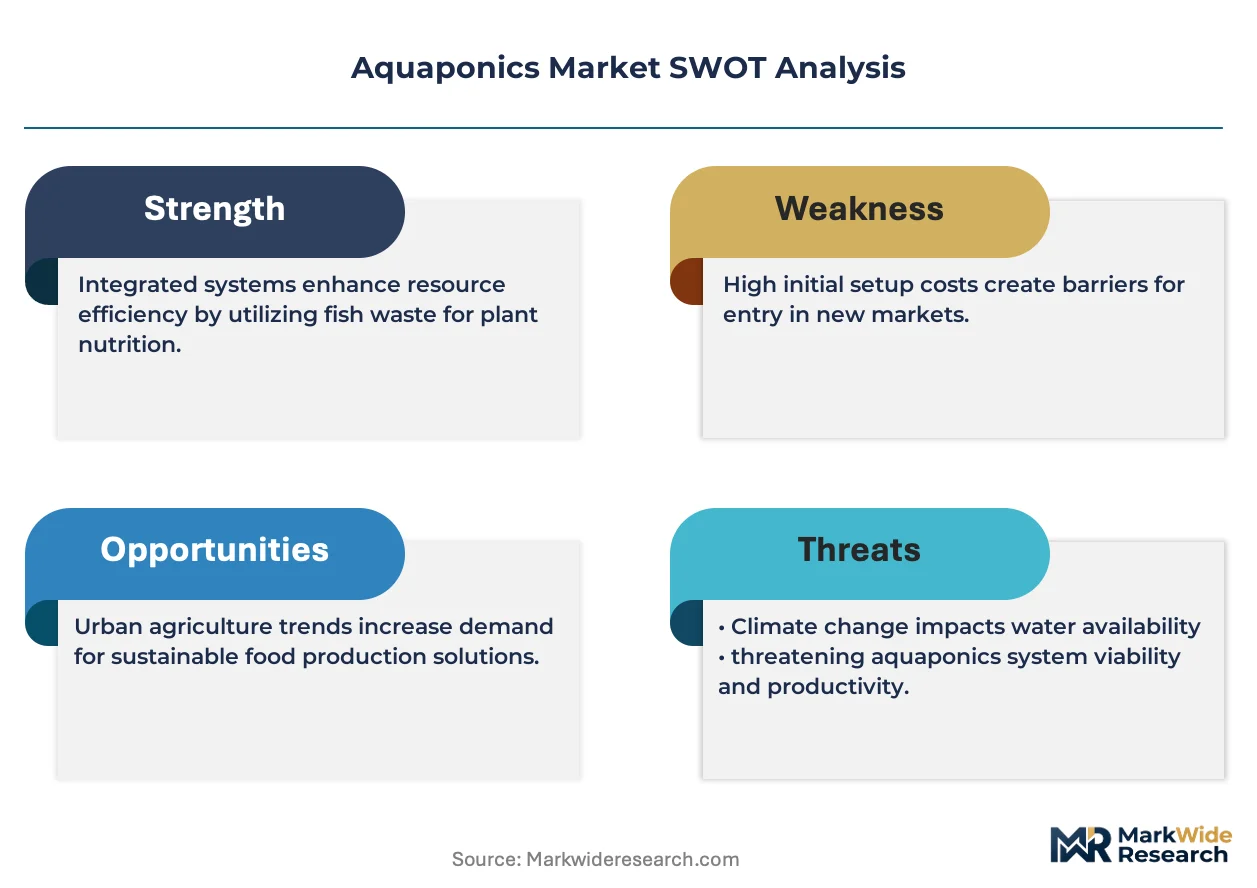
- Capital intensity barrier:Integrated system designs require substantial upfront investment in biofiltration infrastructure and climate-controlled housing.
- Technical limitation in nitrifying bacteria stability:pH maintenance between 6.8-7.2 demands continuous chemistry monitoring that elevates operational complexity.
- Substitution threat from hydroponics:Soilless growing methods without fish protein output compete for identical urban real estate and water-scarce growing regions.
Strategic Opportunities
- Vertical aquaponics configurations:Three-dimensional production footprints address urban real estate constraints in densely populated metropolitan food production zones.
- FDA Food Safety Modernization Act traceability rules:Automated monitoring platform mandates create white space for compliance-integrated system suppliers.
- Media-based system hobbyist expansion:Lower technical barriers and soil-gardening familiarity are opening residential and educational installation channels.
Industry Challenges
- Biological systems management skill gap:Simultaneous fish husbandry and horticulture expertise requirements exceed available trained workforce pools.
- Temperature control capex burden:Sustained 18-30°C water temperature maintenance demands energy-intensive climate infrastructure in variable ambient conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquaponics Market |
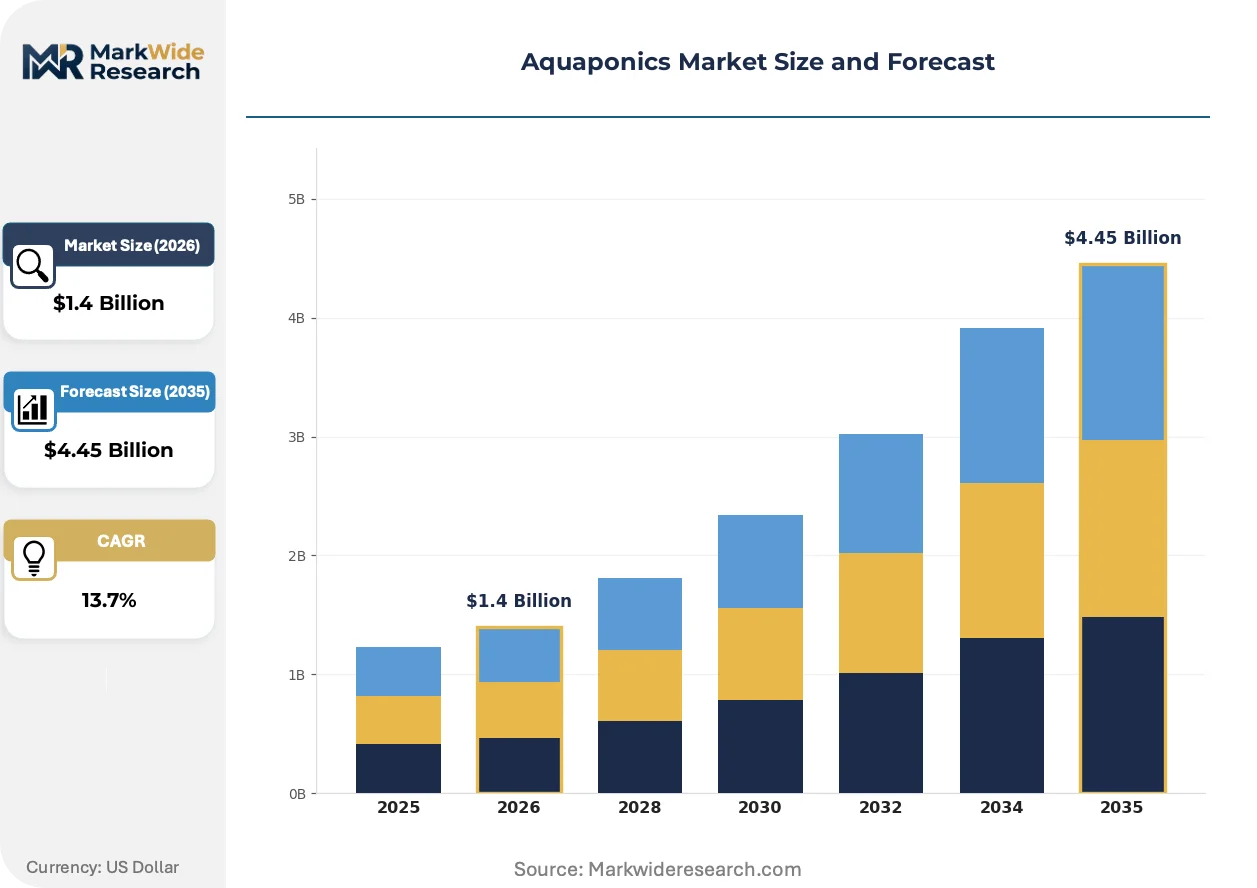
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Media-Based, Nutrient Film Technique, Deep Water Culture, Vertical Aquaponics Component: Fish Tank, Grow Bed, Water Pump, Biofilter, Aeration System Application: Commercial Farming, Residential Gardening, Research, Educational Purposes End User: Farmers, Hobbyists, Academic Institutions, Agribusiness Companies |
| Companies Covered | Nelson and Pade, Inc., The Aquaponic Source, Inc., Pentair Aquatic Eco-System, Inc., Practical Aquaponics (Pty)Ltd., Green Life Aquaponics, ECF Farmsystems GmbH, Superior Fresh LLC, Hydrofarm Holdings Group, Inc., Springworks Farm Maine, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquaponics Market Strategic Shifts & Innovations
Automation layers are penetrating biological system management, converting artisanal aquaponics operations into data-driven production facilities where sensor networks govern feeding schedules and harvest timing.
Internet-of-Things sensor arrays are expanding into commercial aquaponics facilities as core infrastructure rather than optional upgrades. Mid-scale operators in Texas and Arizona are deploying networked water chemistry monitors that transmit pH, ammonia, and nitrite readings to cloud dashboards in real time. This connectivity is expanding into predictive harvest scheduling and automated fish feeding systems that compress labor inputs per unit output.
EPA Clean Water Act provisions are tightening discharge standards for commercial operators releasing into municipal treatment networks. California, Arizona, and Texas state-level agricultural water quality standards now mandate documented filtration performance and effluent testing protocols. Commercial lettuce and leafy green operations with deep water culture segments are responding by integrating third-party certified biofiltration systems that preempt regulatory inspection failures.
Direct-to-restaurant procurement contracts are displacing traditional wholesale distribution channels for urban aquaponics producers. Metropolitan vertical farms in European and North American city centers are bypassing regional produce distributors to supply chefs with harvest-to-table intervals under 24 hours. This channel compression is most visible in arid southwestern United States cities where water-scarce growing credentials command menu premium positioning.
Aquaponics Market Segmentation
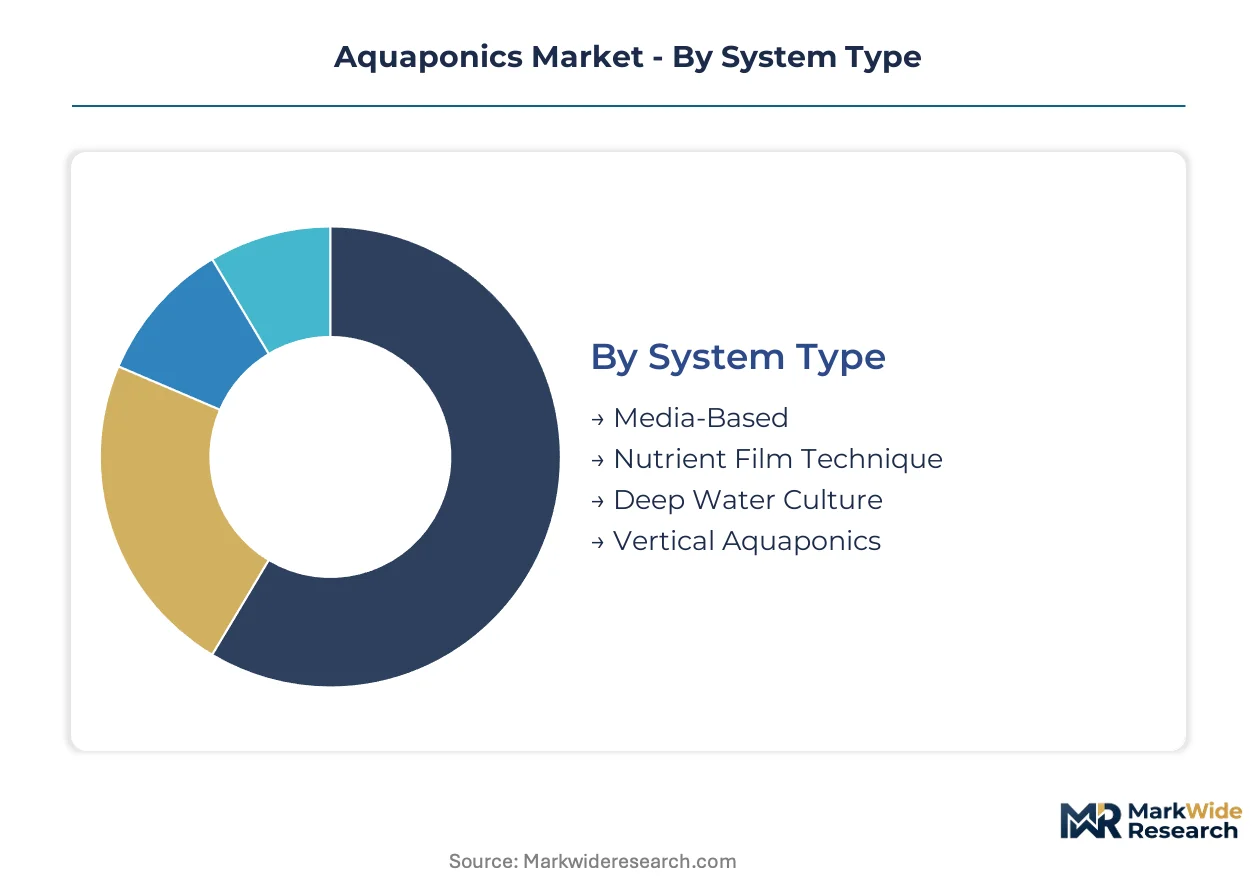
Aquaponics system architectures diverge sharply in capital requirements and operational complexity. Component integration depth determines whether installations function as standalone turnkey operations or embedded subsystems within larger agricultural facilities.
System Type:
Integration depth varies from fully self-contained units requiring minimal external infrastructure to modular subsystems designed for embedding within climate-controlled greenhouses or warehouse environments.
- Media-Based:Clay pebble or gravel substrates anchor root structures while housing nitrifying bacteria colonies in fixed-film biofiltration. Demand concentrates in residential and educational installations across Arizona and Texas where familiar soil-gardening parallels reduce operator training burdens.
- Deep Water Culture:Rafts suspend lettuce and leafy green roots directly in nutrient-rich reservoirs with dissolved oxygen maintained through aeration. Commercial operators in California's Central Valley deploy these configurations for six-week harvest cycles that maximize output per water volume.
- Nutrient Film Technique:Thin film streams cascade through angled channels delivering continuous nutrient flow to exposed roots. Greenhouse producers in Spain and the Netherlands favor this method for strawberry and herb production.
- Vertical Aquaponics:Stacked growing towers or wall-mounted columns compress production into three-dimensional footprints. Metropolitan installations in Singapore and Berlin exploit this architecture where urban real estate premiums prohibit horizontal expansion.
Volume placements concentrate in Media-Based systems; the faster expansion belongs to Vertical Aquaponics.
Component:
Cost tier stratification separates premium integrated subsystems from commodity replacement parts, with pricing spreads widest in biological filtration and climate control elements.
- Fish Tank:Reinforced polymer or concrete reservoirs range from 1,000-liter hobbyist units to 50,000-liter commercial vessels. Institutional buyers at universities and research stations specify food-grade materials with integrated viewing panels.
- Grow Bed:Container structures support media substrates or raft systems with drainage integration. Commercial farms in arid southwestern United States prioritize insulated designs that buffer against extreme ambient temperature swings.
- Water Pump:Circulation systems rated for continuous operation at 18-30°C water temperatures. Replacement demand concentrates in existing installations where pump failure triggers immediate crop risk.
- Biofilter:Nitrifying bacteria colonization surfaces convert ammonia to plant-available nitrates. EPA discharge compliance in California mandates certified biofiltration performance that elevates specification requirements.
- Aeration System:Diffuser networks and air pumps maintain dissolved oxygen levels for fish health and root respiration. Deep water culture segments drive specification toward high-efficiency blower systems.
Margin concentration sits with Biofilter assemblies; Aeration Systems gain share fastest as deep water culture expands.
Application:
Customer maturity separates artisanal operations from data-driven production facilities, with automation penetration deepest where regulatory traceability mandates apply.
- Commercial Farming:Profit-oriented operations selling into wholesale produce channels or direct restaurant contracts. FDA Food Safety Modernization Act traceability rules are pressing these operators toward automated monitoring platforms.
- Residential Gardening:Hobbyist-scale installations emphasizing household food production and educational engagement. Media-based systems dominate this tier due to lower technical barriers.
- Research:Controlled experiments examining nutrient cycling, fish growth rates, or plant yield optimization. Academic institutions in Germany and the Netherlands maintain dedicated aquaponics research stations.
- Educational Purposes:K-12 and university programs teaching sustainable agriculture principles. School districts in Texas and California specify turnkey systems with curriculum integration.
Revenue concentration aligns with Commercial Farming; Educational Purposes demonstrate steepest expansion trajectory as sustainability curricula proliferate.
End User:
Procurement authority separates centralized agribusiness purchasing from distributed hobbyist acquisition, with contract structures varying from single-unit retail to multi-installation enterprise agreements.
- Farmers:Professional agricultural producers integrating aquaponics into existing operations or establishing dedicated facilities. Water scarcity mandates across Arizona and Texas accelerate their adoption timelines.
- Hobbyists:Individual enthusiasts purchasing through retail channels and online marketplaces. Component kit suppliers target this segment with modular expansion paths.
- Academic Institutions:Universities and research centers requiring publication-grade data reproducibility. These buyers specify sensor-integrated systems with data logging capabilities.
- Agribusiness Companies:Corporate entities deploying aquaponics at scale for branded produce lines. EU Green Deal certification requirements shape their system selection toward closed-loop documentation.
Contract value peaks with Agribusiness Companies; Academic Institutions are expanding procurement fastest as research funding for sustainable agriculture climbs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phoenix anchors commercial aquaponics deployment in the southwestern United States, where municipal water restrictions and extreme heat stress conventional agriculture. Water-scarce metropolitan clusters across four continents are accelerating closed-loop system installations as climate adaptation infrastructure.
United States
Arid southwestern states concentrate commercial adoption, with Arizona and Texas operators deploying automated monitoring platforms under EPA Clean Water Act discharge mandates. California agricultural water quality standards now require documented filtration performance for effluent release into municipal networks. Phoenix and Tucson host the densest clusters of deep water culture lettuce operations serving direct-to-restaurant channels.
Germany
Metropolitan vertical installations in Berlin and Hamburg exploit EU Green Deal certification requirements for closed-loop food production. ECF Farmsystems GmbH anchors European urban production with three-dimensional footprint configurations addressing real estate constraints. Research stations at technical universities in Stuttgart and Munich advance nitrifying bacteria optimization protocols for temperate climate operations.
Singapore
Vertical aquaponics configurations dominate this city-state where land scarcity prohibits horizontal expansion. Government food security initiatives subsidize rooftop and warehouse installations producing leafy greens and tilapia for domestic consumption. The Lim Chu Kang agricultural zone hosts integrated demonstration facilities combining deep water culture with automated nutrient monitoring.
Australia
Murray-Darling Basin water allocation restrictions push horticultural producers toward soilless methods with dual protein-vegetable output. Research institutions in Queensland and New South Wales develop heat-tolerant system designs for ambient temperature extremes. Perth metropolitan operators leverage desalination co-location for reliable water supply independent of rainfall variability.
Netherlands
Greenhouse horticulture expertise in Westland and Aalsmeer clusters transfers into aquaponics integration within existing climate-controlled infrastructure. Wageningen University research stations examine nutrient film technique optimization for strawberry and herb production. Dutch equipment fabricators supply biofiltration and aeration components to operators across northwestern Europe.
Aquaponics Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a bifurcated structure separating integrated system architects from component suppliers. The vendor base stratifies into three tiers: premium turnkey commercial installations, mid-scale urban vertical configurations, and commodity hobbyist-grade kits. Strategic archetypes include full-stack system integrators, specialized biofiltration engineers, and distribution-scale component aggregators. Competitive moves concentrate on geographic expansion into water-scarce regions and technology licensing partnerships with agricultural equipment manufacturers.
Within the premium commercial tier, Nelson and Pade, Inc. and ECF Farmsystems GmbH occupy positions exemplifying integrated design depth and metropolitan vertical specialization respectively. Hydrofarm Holdings Group, Inc. anchors the component supply archetype through multi-channel distribution scale. These three entities represent distinct strategic vectors: sustained margin pools through turnkey complexity, urban real estate optimization, and hobbyist market accessibility through modular expansion paths.
| Leading Market Players |
|---|
| Nelson and Pade, Inc. |
| The Aquaponic Source, Inc. |
| Pentair Aquatic Eco-System, Inc. |
| Practical Aquaponics (Pty)Ltd. |
| Green Life Aquaponics |
| ECF Farmsystems GmbH |
| Superior Fresh LLC |
| Hydrofarm Holdings Group, Inc. |
| Springworks Farm Maine, Inc. |
| Others |
Cost & Logistics Intelligence
Biological systems management expertise concentrated in Germany and the Netherlands generates labor-cost differentials that widen pricing-tier spreads between artisanal installations and automated commercial facilities. European metropolitan operators absorb premium pricing for integrated monitoring platforms, while southwestern United States buyers prioritize capital-efficient component kits that minimize upfront expenditure.
Pricing Analysis
Value-based pricing anchored to harvest throughput and water-use efficiency separates commercial tiers in this market. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation depth and biofiltration certification grade. Price differentiation runs through EPA discharge compliance tiers in California and Texas, where certified systems command sustained premiums. Cost compression in hobbyist-grade component kits is intensifying because Asian fabrication scale erodes margin pools for basic circulation and aeration hardware. Academic institutions demonstrate lowest price sensitivity given grant-funded procurement authority; residential hobbyists exhibit highest elasticity to component cost fluctuations.
Supply Chain Analysis
Reinforced polymer resin for tank fabrication rests on petrochemical supply networks concentrated in China, Germany, and the United States. Nitrifying bacteria colonization media and sensor-integrated monitoring hardware draw from Dutch greenhouse technology clusters and Taiwanese electronics manufacturing. Single-source vulnerability concentrates in specialized biofiltration membranes where European fabricators dominate specification-grade production. Distribution runs through agricultural equipment dealers in rural markets and direct-to-farm e-commerce platforms serving metropolitan vertical operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aquaponics is transitioning from artisanal craft to data-driven production as Internet-of-Things sensor networks displace manual water chemistry monitoring. This technology replacement phase rewards operators who automate biological system management ahead of regulatory traceability mandates.
For Market Incumbents: Deepen backward integration into biofiltration membrane production to defend margin pools against commodity substitution from hydroponics suppliers. Incumbents should consolidate channel control through exclusive dealer networks in Arizona and Texas while accelerating FDA-compliant automated monitoring platform development before traceability rules harden.
For New Entrants and Emerging Players: Restaurant supply distributors represent the most accessible channel partners for metropolitan vertical aquaponics producers seeking white-space entry. New entrants should target educational procurement channels in Texas and California where sustainability curriculum mandates drive institutional demand with lower technical barriers. A curriculum-integrated turnkey positioning offers the clearest go-to-market angle against established component suppliers.
For Investors and Strategic Acquirers: Re-rating potential sits with automated monitoring platform specialists given FDA Food Safety Modernization Act traceability catalysts. Long-term viability favors acquisition targets with captive biofiltration technology and established direct-to-restaurant channel relationships in water-scarce metropolitan clusters. Watch for EPA discharge standard tightening in southwestern states as the inflection signal for compliance-integrated system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Monitoring Platform Development | FDA traceability mandates in commercial farming operations drive specification requirements for sensor-integrated systems. |
| Backward Integration into Biofiltration | Captive membrane production insulates margin pools from European specialty fabricator supply constraints. |
| Direct-to-Restaurant Channel Expansion | Phoenix and Tucson operators bypass wholesale distributors to capture harvest-to-table premium positioning. |
| Educational Curriculum Integration | Texas and California school district sustainability mandates create institutional procurement pull for turnkey systems. |
| Vertical Configuration Patent Portfolio | Singapore and Berlin metropolitan real estate constraints reward three-dimensional footprint intellectual property control. |
Research Approach
Multi-period observation of water discharge permit filings, municipal water restriction enactments, and commercial system installation permits anchored the trend analysis, supplemented by interviews with aquaponics facility operators, agricultural equipment distributors, EPA regional compliance officers, university sustainability program directors, and restaurant procurement managers. Secondary validation drew from FDA Food Safety Modernization Act guidance documents, EPA Clean Water Act enforcement data, state-level agricultural water quality standards, and customs records for aquaponics component imports. Bottom-up triangulation across facility-scale capacity estimates and top-down reconciliation against regional water scarcity policy impacts ensured analytical robustness.
Input-output matrices modeled system architecture adoption by integration depth, application maturity, and metropolitan real estate constraint severity across the projection horizon. Segmentation dimensions included system type, component tier, customer automation readiness, and regional regulatory framework cluster. CAGRs were derived from installed base expansion trajectories calibrated against water scarcity policy acceleration curves and biological systems management labor availability constraints.
Caveats apply where nitrifying bacteria stability breakthroughs or hydroponics protein-fortification advances could materially shift the outlook. Forecasts reflect assumptions about EPA discharge enforcement continuity and EU Green Deal certification timeline adherence. A small set of triggers—FDA traceability rule finalization, southwestern United States drought severity indices, and automated feeding system cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
China Aquafeed Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
North America Shrimp Feed Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
Shrimp Feed Market
Aquaculture Innovations
Clams, Cockles, Ark Shells Market
Aquaculture Innovations
Kuwait Fisheries and Aquaculture Market
Aquaculture Innovations
Ornamental Fish Market
Aquaculture Innovations
China Shrimp Market
Aquaculture Innovations
Brazil Fisheries and Aquaculture Market
Aquaculture Innovations
Smart Aquaculture Systems Market
Aquaculture Innovations
Aquaculture Additives Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market
Aquaculture Innovations
Global Plant Based Fish Feed Market
Aquaculture Innovations
Microalgae-Based Aquafeed Market
Aquaculture Innovations
Aquaculture Cage Market