
 Global Ornamental Fish Feed Market | 2026-2036
Global Ornamental Fish Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ornamental Fish Feed Market Foresight
Plant-based protein is pivoting away from fishmeal dependence in ornamental feed economics. Tetra GmbH leverages captive R&D facilities in Germany to sustain formulation leadership across European distribution channels. Zeigler Bros., Inc. anchors its position through backward integration into specialized ingredient sourcing for color-enhancing applications. Hikari Co., Ltd. dominates premium flake and pellet categories across Asian hobbyist markets through manufacturing scale in Japan.
Ornamental fish feed comprises formulated diets engineered to deliver precise protein profiles, typically between 35% and 50% crude protein, alongside carotenoid additives for pigmentation enhancement in captive species. These feeds serve commercial breeders, public aquariums, and hobbyist aquarists by supporting immune function, growth rates, and visual phenotype expression in non-food fish species. Flake formulations occupy the highest volume tier due to universal compatibility with community tanks and extended shelf stability, while frozen feeds command premium positioning among specialist breeders prioritizing palatability. Color-enhancing formulations represent the fastest-expanding margin pool as consumer willingness to pay for phenotype intensity rises among premium aquarists.
FDA oversight of animal feed safety standards in the United States shapes import requirements and ingredient traceability obligations for foreign manufacturers. EFSA and REACH frameworks in Europe restrict synthetic additive portfolios and mandate comprehensive labeling disclosures, directly influencing formulation R&D allocation. The EU F-Gas Regulation indirectly pressures cold-chain logistics for frozen feed distribution, altering regional supply configurations. Stakeholders must monitor divergence between regional contaminant thresholds and emerging restrictions on marine-derived ingredients to preempt compliance-driven product redesign cycles.
Market Dynamics
The ornamental fish feed sector is restructuring around protein source substitution as breeders and aquarists reject marine-derived inputs amid traceability mandates and cost volatility. Formulation houses now face simultaneous pressure from EFSA disclosure rules and Southeast Asian procurement consolidation.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain efficiency mandates for frozen feed distribution are accelerating logistics modernization across European importers, compressing spoilage rates and extending shelf-life claims.
- Thailand-Indonesia breeding clusters:Export-oriented ornamental aquaculture expansion in these countries is concentrating demand for high-protein flake and pellet formulations at commercial scale.
- Carotenoid microencapsulation:This delivery technology is enabling precise pigmentation control in captive species, unlocking premium pricing among specialist breeders and public aquarium curators.
Market Restraints
- Fishmeal price volatility:Peruvian anchovy quota fluctuations and competing aquafeed demand are compressing margin stability for marine-protein-dependent formulations.
- REACH additive restrictions:ECHA's tightening synthetic pigment approvals are forcing costly reformulation cycles and reducing available color-enhancement chemistries.
- Single-source krill dependence:Antarctic supply concentration creates vulnerability for premium frozen feed producers reliant on astaxanthin-rich inputs.
Strategic Opportunities
- India's nascent ornamental aquaculture:Underdeveloped breeder infrastructure and rising middle-class hobbyism create whitespace for packaged feed penetration against live-food traditions.
- Plant-protein fermentation:Single-cell protein from agricultural waste streams offers cost-advantaged amino acid profiles that align with EU Green Deal circularity incentives.
- Direct-to-breeder e-commerce:Specialized platforms are disintermediating traditional distributor networks, enabling formulation houses to capture margin and capture usage data.
Industry Challenges
- Formulation chemist scarcity:Cross-disciplinary expertise spanning aquatic nutrition, pigment chemistry, and regulatory compliance remains concentrated among a handful of European and Japanese specialists.
- Multi-jurisdiction labeling synchronization:Divergent FDA, EFSA, and Japan's Ministry of Agriculture disclosure timelines force parallel SKU maintenance and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ornamental Fish Feed Market |
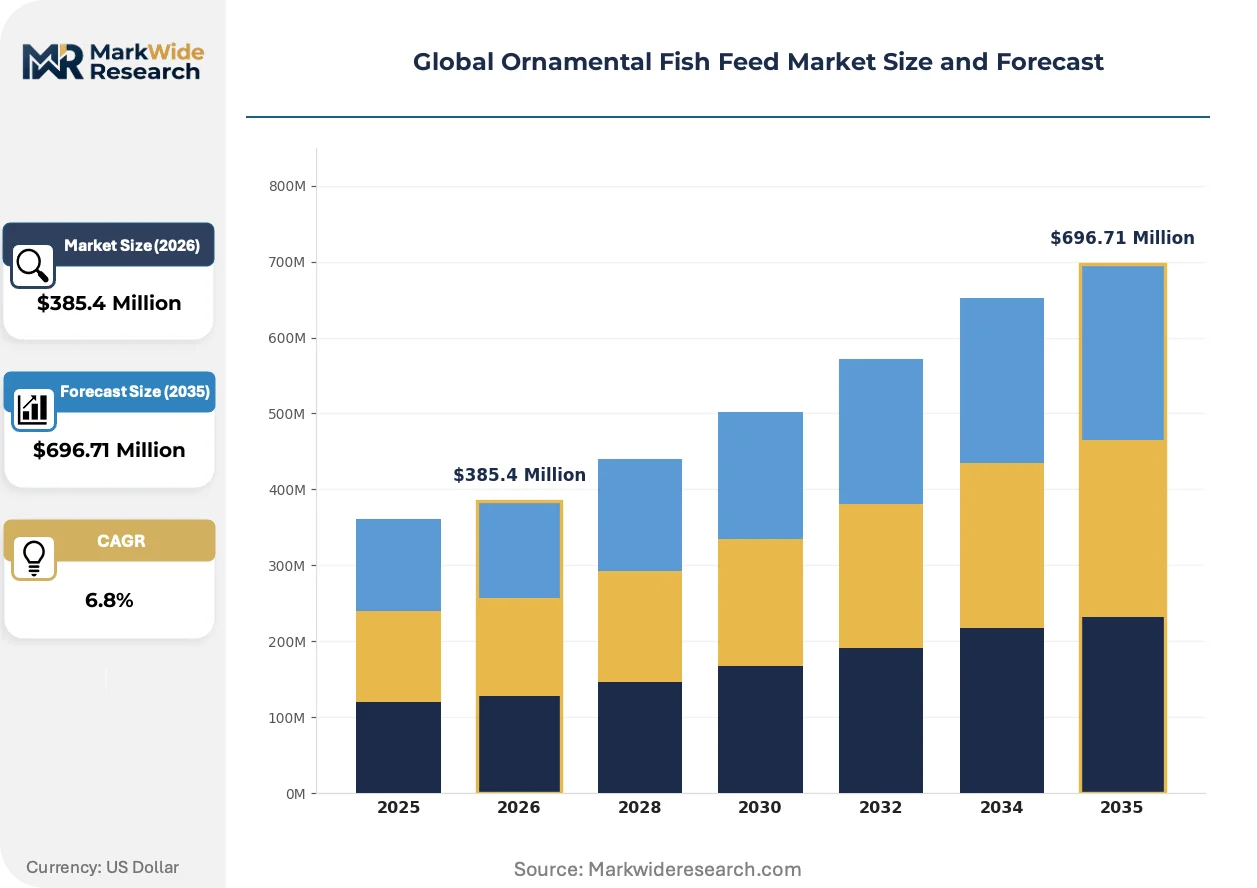
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Flakes, Granules, Frozen, Tablets, Gel Feed Ingredient: Fishmeal, Spirulina, Krill Oil, Wheat Gluten, Soy Protein, Algae Feed Formulation: High Protein, Color Enhancing, Growth Promoting, Disease Resistant, Balanced Nutrition, Organic End User: Aquarists, Public Aquariums, Pet Stores, Research Institutions, Hobbyists, Aquaculture Farms |
| Companies Covered | Tetra GmbH, JBL GmbH & Co. KG, Cargill Incorporated, Zeigler Bros., Inc., Aller Aqua A/S, Skretting AS, Hikari Co., Ltd., Rangen, Inc., BioMar Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ornamental Fish Feed Market Shifts & Advancements
Active substitution of marine ingredients with precision-fermented alternatives is compressing traditional supply hierarchies while digital traceability tools reshape procurement verification standards.
Precision fermentation of microbial proteins is rewriting the economics of high-performance ornamental feeds. Specialist breeders in Germany and Japan are piloting these formulations for discus and marine reef species. The technology is compressing the premium attached to wild-caught krill and fishmeal by delivering consistent amino acid ratios at lower input cost volatility.
REACH framework amendments on microplastic-free labeling are forcing frozen feed producers to reformulate binding agents and packaging coatings. Industrial consequence includes accelerated R&D allocation toward alginate and starch-based alternatives. Premium flake manufacturers serving Dutch and German distribution channels are responding fastest due to retailer sustainability scorecard requirements.
Certification-driven purchasing is consolidating buyer preference around third-party audited sustainability claims. Public aquariums and high-volume commercial breeders are displacing unverified suppliers with feed lines carrying ASC or Friend of the Sea chain-of-custody documentation. This shift is most visible in Nordic and Australian procurement offices where institutional procurement policies mandate disclosed provenance.
Global Ornamental Fish Feed Market Segmentation
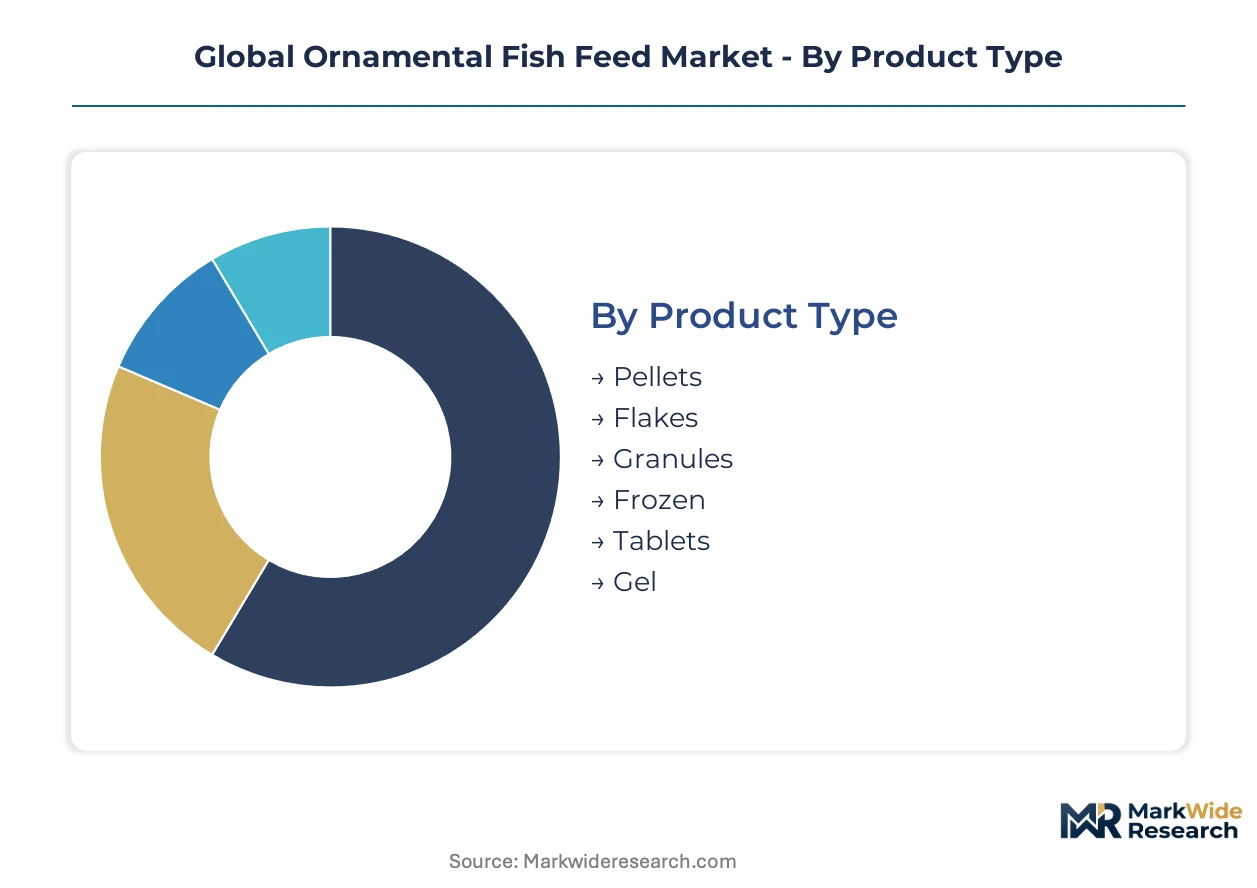
Segmentation in ornamental fish feed reflects divergent supply chain configurations across formulation technologies and procurement channels. Breeders in Thailand and Indonesia drive volume concentration in specific product formats, while European regulatory pressures fragment ingredient sourcing strategies.
Product Type:
Supply concentration for finished feed formats clusters around flake and pellet manufacturing infrastructure in Japan and Germany.
- Flakes:Thin-layer dried formulations deliver 35-50% crude protein with extended shelf stability. Demand concentrates among community tank aquarists in Germany and the Netherlands where retailer sustainability scorecards favor packaged convenience over live alternatives.
- Pellets:Compressed extruded diets enable precise nutrient density control for commercial breeding operations. Procurement from Thailand-Indonesia export clusters is accelerating as large-scale discus and cichlid producers standardize on sinking and floating variants.
- Granules:Mid-size particulates target medium-bodied ornamental species with moderate feeding aggression.
- Frozen:Cold-chain dependent formats retain palatability for specialist marine breeders. EU F-Gas Regulation compliance costs are compressing importer margins.
- Tablets:Slow-dissolving compressed feeds adhere to tank surfaces for bottom-feeding species.
- Gel:Moisture-rich preparations suit finicky feeders and juvenile conditioning protocols.
Flakes absorb the bulk of installed capacity; color-enhancing pellet variants are expanding most quickly.
Feed Ingredient:
Cost tier stratification separates marine-derived inputs from fermentation-based alternatives as price volatility reshapes procurement.
- Fishmeal:Peruvian anchovy supply fluctuations and competing aquafeed demand are forcing European formulators toward reduced inclusion rates. REACH traceability mandates accelerate substitution timelines.
- Spirulina:Arthrospira platensis biomass delivers complete protein with natural carotenoid content. Premium flake producers in Japan leverage domestic cultivation infrastructure for pigment consistency.
- Krill Oil:Antarctic supply concentration creates astaxanthin access vulnerability for frozen feed specialists.
- Wheat Gluten:Plant-based binder functionality supports extrusion stability at lower cost tiers.
- Soy Protein:Fermented soy concentrate offers amino acid completeness for vegetarian formulation lines.
- Algae:Schizochytrium and Isochrysis strains provide DHA without marine fishmeal dependence.
Fishmeal retains the largest share of ingredient spend; precision-fermented single-cell proteins are climbing the fastest.
Feed Formulation:
Application-specific performance claims determine margin capture across breeder versus hobbyist channels.
- High Protein:Formulations exceeding 45% crude protein support rapid growth phases in juvenile ornamental species. Commercial farms in Indonesia prioritize these for export-grade guppy and betta production cycles.
- Color Enhancing:Carotenoid microencapsulation enables precise astaxanthin and canthaxanthin delivery. Public aquarium curators in Australia and Singapore pay premiums for phenotype intensity in display collections.
- Growth Promoting:Optimized amino acid ratios accelerate time-to-market for breeding operations.
- Disease Resistant:Immunostimulant additives target stress reduction in high-density holding systems.
- Balanced Nutrition:General-purpose formulations serve multi-species community tanks.
- Organic:Certified ingredient chains appeal to sustainability-mandated institutional procurement.
Balanced nutrition lines dominate volume throughput; color-enhancing formulations command the steepest expansion trajectory.
End User:
Customer type segmentation separates institutional procurement discipline from discretionary hobbyist purchasing patterns.
- Public Aquariums:Institutional buyers mandate ASC or Friend of the Sea chain-of-custody documentation. Nordic and Australian procurement offices exclude unverified suppliers through formal sustainability policies.
- Aquaculture Farms:Export-oriented breeding operations in Thailand concentrate demand for high-protein flake and pellet at commercial scale. FDA import requirements shape supplier qualification for US-bound shipments.
- Aquarists:Serious hobbyists with multiple tank systems drive premium category penetration.
- Pet Stores:Retail intermediaries prioritize margin and shelf-life over formulation sophistication.
- Research Institutions:Controlled study requirements demand batch consistency and full ingredient disclosure.
- Hobbyists:Casual consumers exhibit price sensitivity and brand loyalty to established flake lines.
Aquaculture farms absorb the bulk of installed capacity; public aquariums are gaining share fastest through certification-driven purchasing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand and Indonesia concentrate commercial breeding demand for high-protein flake and pellet formulations, while Germany and Japan anchor premium formulation R&D. The United States shapes import compliance standards that cascade through supplier qualification protocols.
Thailand
Export-oriented ornamental aquaculture in Bangkok and surrounding provinces drives concentrated procurement of growth-promoting pellets for discus and cichlid breeding cycles. The Department of Fisheries enforces Good Aquaculture Practices certification for feed suppliers serving EU-bound shipments. Pathum Thani and Nakhon Pathom host dense clusters of commercial hatcheries standardizing on sinking pellet variants.
Indonesia
Java-based betta and guppy producers generate scaled demand for color-enhancing flake formulations targeting export-grade phenotype intensity. The Ministry of Marine Affairs and Fisheries implements traceability requirements for marine-derived feed ingredients under national quality standards. Bandung and Yogyakarta concentrate specialist breeder operations upgrading from live-food traditions to packaged diets.
Germany
Premium home aquarists and public aquariums in Berlin, Hamburg, and Munich sustain demand for spirulina-enriched flake and precision-formulated frozen feeds. EFSA disclosure mandates and EU F-Gas Regulation compliance reshape cold-chain logistics for importers. Melle anchors Tetra GmbH's captive R&D facilities sustaining European formulation leadership.
Japan
Disciplined hobbyist markets in Tokyo, Osaka, and Nagoya absorb premium pellet and flake categories with exacting quality specifications. METI standards on feed safety and ingredient labeling exceed baseline international requirements. Hino and Kasugai concentrate Hikari Co., Ltd.'s manufacturing infrastructure serving Asian distribution channels.
United States
Public aquariums in California, Florida, and Illinois mandate ASC or Friend of the Sea chain-of-custody documentation for institutional procurement. FDA import requirements on animal feed safety enforce ingredient traceability obligations for foreign manufacturers. Orlando and San Diego anchor major public aquarium complexes driving certification-driven purchasing consolidation.
Global Ornamental Fish Feed Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation houses commanding premium positioning while volume producers serve commercial breeding operations. The vendor base clusters around three archetypes: integrated aquafeed conglomerates with ornamental divisions, dedicated ornamental specialists with captive R&D infrastructure, and regional contract manufacturers serving private-label demand. Dominant competitive moves include backward integration into specialized ingredient sourcing and direct-to-breeder e-commerce platform development.
Among German formulation specialists, Tetra GmbH and JBL GmbH & Co. KG exemplify the R&D-intensive archetype with European distribution anchoring. Zeigler Bros., Inc. and Hikari Co., Ltd. represent geographically concentrated specialists with manufacturing scale in Pennsylvania and Japan respectively. Cargill Incorporated and BioMar Group occupy positions as diversified aquafeed conglomerates leveraging ornamental divisions within broader protein supply architectures.
| Leading Market Players |
|---|
| Tetra GmbH |
| JBL GmbH & Co. KG |
| Cargill Incorporated |
| Zeigler Bros., Inc. |
| Aller Aqua A/S |
| Skretting AS |
| Hikari Co., Ltd. |
| Rangen, Inc. |
| BioMar Group |
| Others |
Supply & Pricing Matrix
Formulation chemist scarcity in Germany and Japan concentrates R&D labor costs, widening spreads between premium precision-formulated feeds and economy flake lines sourced from Southeast Asian contract manufacturers. REACH compliance investments and EFSA disclosure mandates in Europe inflate fixed cost bases that Thai and Indonesian volume producers avoid, stratifying global pricing tiers by regulatory exposure rather than ingredient quality alone.
Pricing Analysis
Volume capture concentrates in standard flake and pellet tiers where Thai and Indonesian breeders drive procurement scale, while margin accrual clusters in color-enhancing formulations and precision-fermented alternatives commanding certification premiums. Price differentiation hinges on carotenoid microencapsulation technology and ASC chain-of-custody documentation, with public aquariums least sensitive and casual hobbyists most responsive to shelf-price positioning. Cost compression in marine-protein-dependent lines intensifies as Peruvian anchovy quota volatility feeds through to fishmeal input costs.
Supply Chain Analysis
Cold-chain logistics costs for frozen feed distribution are accelerating under EU F-Gas Regulation compliance requirements, compressing importer margins across German and Dutch distribution channels. Manufacturing gravity centers on Japan for premium flake and pellet infrastructure, Germany for spirulina-enriched formulation R&D, and Thailand-Indonesia for high-volume extrusion serving export-oriented breeding clusters. Raw material sourcing draws from Antarctic krill concentrations for astaxanthin, Peruvian anchovy fisheries for fishmeal, and domestic Japanese cultivation for spirulina biomass. Single-source krill dependence creates astaxanthin access vulnerability for premium frozen feed specialists. Distribution runs through specialized aquarist retailers in Europe, direct-to-breeder e-commerce platforms in Japan, and consolidated distributor networks serving Southeast Asian commercial hatcheries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as REACH additive restrictions and EFSA disclosure mandates force costly reformulation cycles that smaller regional manufacturers cannot absorb, eliminating unverified suppliers from public aquarium and institutional procurement channels.
For Market Incumbents: Deepen backward integration into precision-fermented single-cell protein production to insulate margin from fishmeal price volatility and Antarctic krill supply concentration. Secure ASC or Friend of the Sea certification across full product lines to defend institutional procurement relationships against emerging sustainability-audited competitors. For New Entrants and Emerging Players: Direct-to-breeder e-commerce platforms offer disintermediation pathways into specialist discus and marine reef segments where formulation sophistication commands premium positioning. Target India's nascent ornamental aquaculture infrastructure with packaged feed solutions displacing live-food traditions among rising middle-class hobbyists in Bandung and Yogyakarta upgrade cycles. For Investors and Strategic Acquirers: Re-rating potential sits with precision-fermentation technology specialists given EU Green Deal circularity incentives accelerating substitution away from marine-derived inputs. Long-term viability favors acquisition targets with captive R&D infrastructure spanning aquatic nutrition, pigment chemistry, and multi-jurisdiction regulatory compliance expertise. Monitor divergence between ECHA synthetic pigment approvals and FDA import requirements as inflection indicators forcing parallel SKU maintenance investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Single-Cell Protein | Captive fermentation capacity insulates margin from Peruvian anchovy quota volatility and krill supply concentration. |
| ASC Chain-of-Custody Certification | Third-party audited sustainability documentation unlocks public aquarium procurement in Nordic and Australian institutional channels. |
| Direct-to-Breeder E-Commerce Platform | Disintermediation captures margin and usage data from specialist discus and marine reef breeding operations. |
| Carotenoid Microencapsulation R&D | Precise astaxanthin delivery technology commands premium pricing from phenotype-focused public aquarium curators. |
| Multi-Jurisdiction Labeling Synchronization | Parallel SKU maintenance for FDA, EFSA, and METI compliance reduces inventory segmentation costs across export markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with formulation R&D directors, commercial breeding operation managers, public aquarium procurement officers, and specialized aquarist retail buyers. EFSA additive approval databases, FDA import refusal records, Japanese METI feed safety standards, and Thai Department of Fisheries certification registries provided cross-referenced validation points. Bottom-up demand modeling across breeder facility counts and top-down supply verification through manufacturing capacity assessments were triangulated for convergence.
Granularity-level modeling operated at product type, feed ingredient, formulation technology, and end-user archetype dimensions across the analysis window. CAGRs were derived from segment-level volume and value trajectories incorporating protein source substitution rates, certification penetration curves, and regional regulatory implementation timelines. Forecast inputs included precision-fermentation technology adoption curves in German and Japanese specialist markets and cold-chain logistics cost inflation under EU F-Gas Regulation compliance requirements.
The model holds under stable regulatory implementation schedules and continued REACH framework enforcement; deviation in ECHA synthetic pigment approval timelines or Antarctic krill fishery quota reductions would shift ingredient substitution trajectories and margin pool distributions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Japan Aquafeed Market
Aquaculture Innovations
Sandfish Market
Aquaculture Innovations
Perch Market
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Seaweed Cultivation Market
Aquaculture Innovations
Bahrain Fisheries and Aquaculture Market
Aquaculture Innovations
Mariculture Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
Fish Oil for Aquafeed Market
Aquaculture Innovations
China Aquafeed Market
Aquaculture Innovations
Vietnam Aquafeed Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
Aquaculture Therapeutics Market
Aquaculture Innovations
Saudi Arabia Aquaculture Market
Aquaculture Innovations
United States Ornamental Fish Market