
 North America Self-Contained Breathing Apparatus Market | 2026-2036
North America Self-Contained Breathing Apparatus Market Size, Share, and Industry Trends Forecast 2026-2036
North America Self-Contained Breathing Apparatus Market Intelligence
The National Fire Protection Association (NFPA) 1981 standard is restructuring market entry requirements for SCBA manufacturers. This mandate for enhanced performance and safety features elevates R&D costs. MSA Safety leverages its strong brand and distribution network in the fire service sector. Honeywell International Inc. competes through technological innovation in its open-circuit systems, while 3M differentiates with a broad portfolio covering multiple industrial end-uses.
A self-contained breathing apparatus is a respiratory device that supplies breathable air from its own compressed air cylinder, completely isolating the user from contaminated atmospheres. These systems typically provide 30 to 60 minutes of air supply. Open-circuit SCBA models represent the largest product segment, driven by extensive use in firefighting. The closed-circuit product type, while a smaller segment, is critical for long-duration missions in mining and specialized rescue operations.
In the United States, both the National Institute for Occupational Safety and Health (NIOSH) and the Occupational Safety and Health Administration (OSHA) govern SCBA certification and use. These regulations create non-negotiable product specifications and drive replacement cycles in industrial and first-responder markets. Future competitive advantage will depend on integrating real-time physiological monitoring and wireless data transmission capabilities into next-generation apparatus.
Market Dynamics
The North America self-contained breathing apparatus market is defined by stringent regulatory mandates. The National Fire Protection Association's evolving standards, enforced by NIOSH and OSHA, create non-negotiable replacement cycles and elevate the baseline for product performance and safety features.
Growth Catalysts
- Stricter Regulations:The NFPA 1981 standard's requirements for enhanced communication systems and thermal durability compel municipal fire departments and industrial users to upgrade their existing SCBA fleets to remain compliant.
- Industrial Safety Culture:A heightened focus on worker safety within the US and Canadian oil and gas, chemical manufacturing, and hazardous material handling sectors drives consistent demand for certified respiratory protection.
- Technological Upgrades:The integration of telemetry for real-time monitoring and improved ergonomics in new SCBA models creates a clear performance advantage, incentivizing replacement of older, less capable equipment.
Market Restraints
- High R&D and Certification Costs:Meeting the demanding specifications of NFPA and NIOSH requires significant upfront investment in research and testing, creating a high barrier to entry for new manufacturers.
- Component Price Volatility:The cost of specialized materials, such as carbon fiber for compressed air cylinders and specific electronic components for telemetry systems, is subject to supply chain fluctuations.
- Limited Air Supply Duration:Standard open-circuit SCBA units offer a finite air supply, typically 30 to 60 minutes, which limits their use in extended duration incidents compared to closed-circuit alternatives.
Strategic Opportunities
- Data Integration and Connectivity:Developing SCBA systems that seamlessly integrate wireless data transmission with incident command software offers a significant opportunity to enhance firefighter safety and operational oversight.
- Expansion in Specialized Industrial Niches:Targeting underpenetrated applications, such as pharmaceutical cleanroom emergency response or semiconductor fabrication plant safety teams, provides avenues for market growth beyond traditional firefighting.
- Physiological Monitoring:Incorporating sensors to monitor user vitals like heart rate and body temperature can transform the SCBA into a critical life-monitoring tool, creating a new layer of value.
Industry Challenges
- Complex Certification Pathways:Navigating the multi-stage approval process with both NIOSH and the NFPA for new product introductions can lead to extended development timelines and delayed market entry.
- Interoperability with Legacy Systems:Ensuring new, data-enabled SCBA units can communicate effectively with older radio systems and command platforms used by many fire departments presents a significant technical hurdle.
- Advanced Training Requirements:The shift from simple breathing apparatus to complex electronic safety systems necessitates more intensive and costly training programs for end-users to ensure proper use and maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Self-Contained Breathing Apparatus Market |
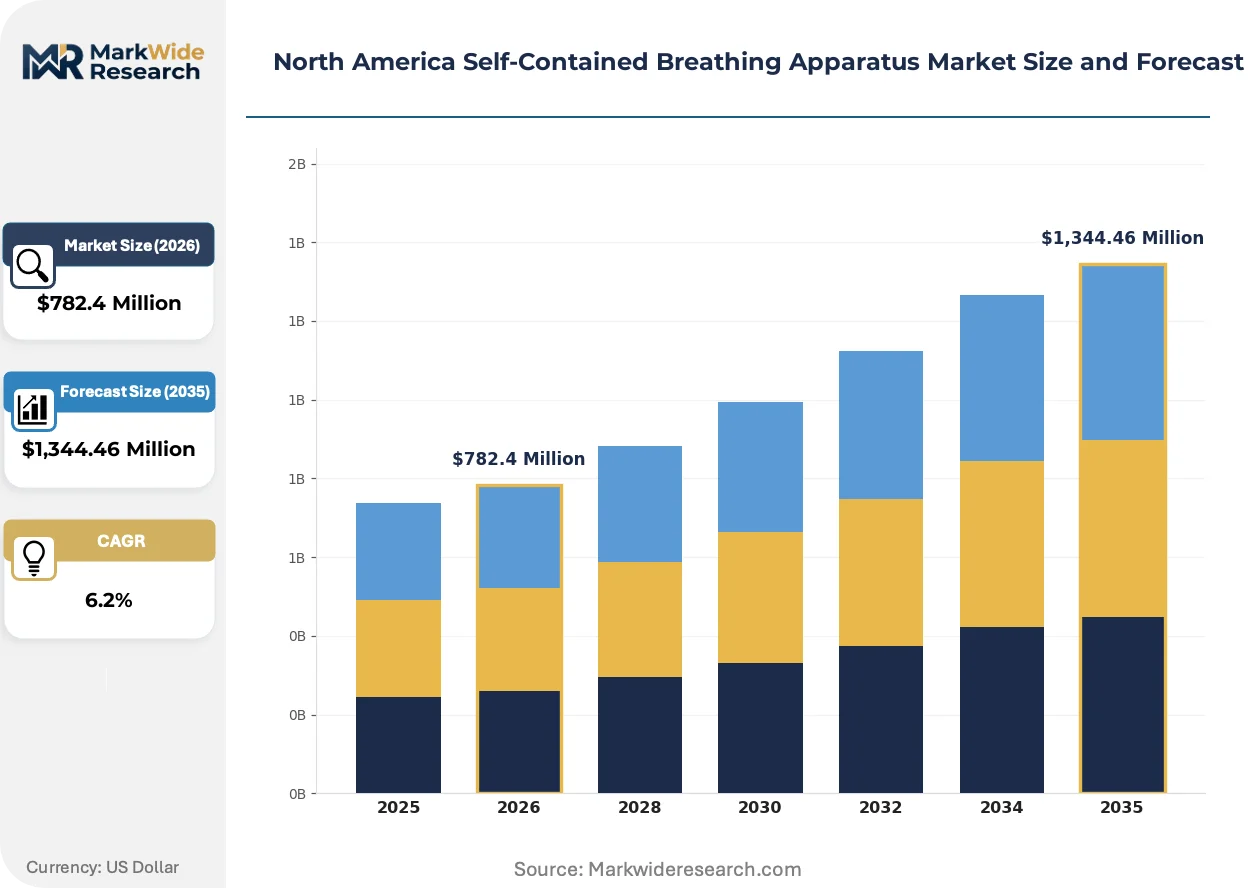
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,344.46 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open-Circuit, Closed-Circuit, Supplied-Air, Self-Contained Industry Vertical: Firefighting, Mining, Chemical, Construction Application: Rescue Operations, Industrial Hazards, Hazardous Waste, Military Use Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | MSA Safety, 3M, Drägerwerk AG & Co. KGaA, Honeywell International Inc., Avon Protection, Scott Safety, Interspiro, 3M Scott Fire & Safety, Levitt-Safety Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Self-Contained Breathing Apparatus Market Strategic Shifts & Innovations
The evolution of SCBA technology centers on integrating digital capabilities to enhance user safety and situational awareness. This shift transforms the apparatus from a standalone life-support device into a connected node within a broader incident management ecosystem.
Advanced composite materials and ergonomic redesigns are reducing the physical burden on users. Lighter carbon-composite cylinders and more balanced weight distribution are being adopted by fire departments across North America to combat fatigue. This focus on human factors is modularizing the SCBA platform, allowing components like harnesses and backplates to be tailored for different body types and applications.
Regulatory updates from the National Fire Protection Association continue to drive product innovation cycles. The NFPA 1981 standard's latest revisions, for example, impose stricter requirements for voice communication clarity and device durability in high-heat environments. The fire service sector in the United States and Canada is most impacted, forcing equipment upgrades to meet the new compliance benchmarks.
A notable shift in purchasing behavior involves a greater emphasis on the total cost of ownership over initial acquisition price. This change disrupts traditional, transactional sales models, favoring suppliers that offer bundled packages including multi-year warranties, on-site maintenance, and certified training programs. This trend is most prominent among large metropolitan fire departments in the US managing extensive equipment inventories.
North America Self-Contained Breathing Apparatus Market Segmentation
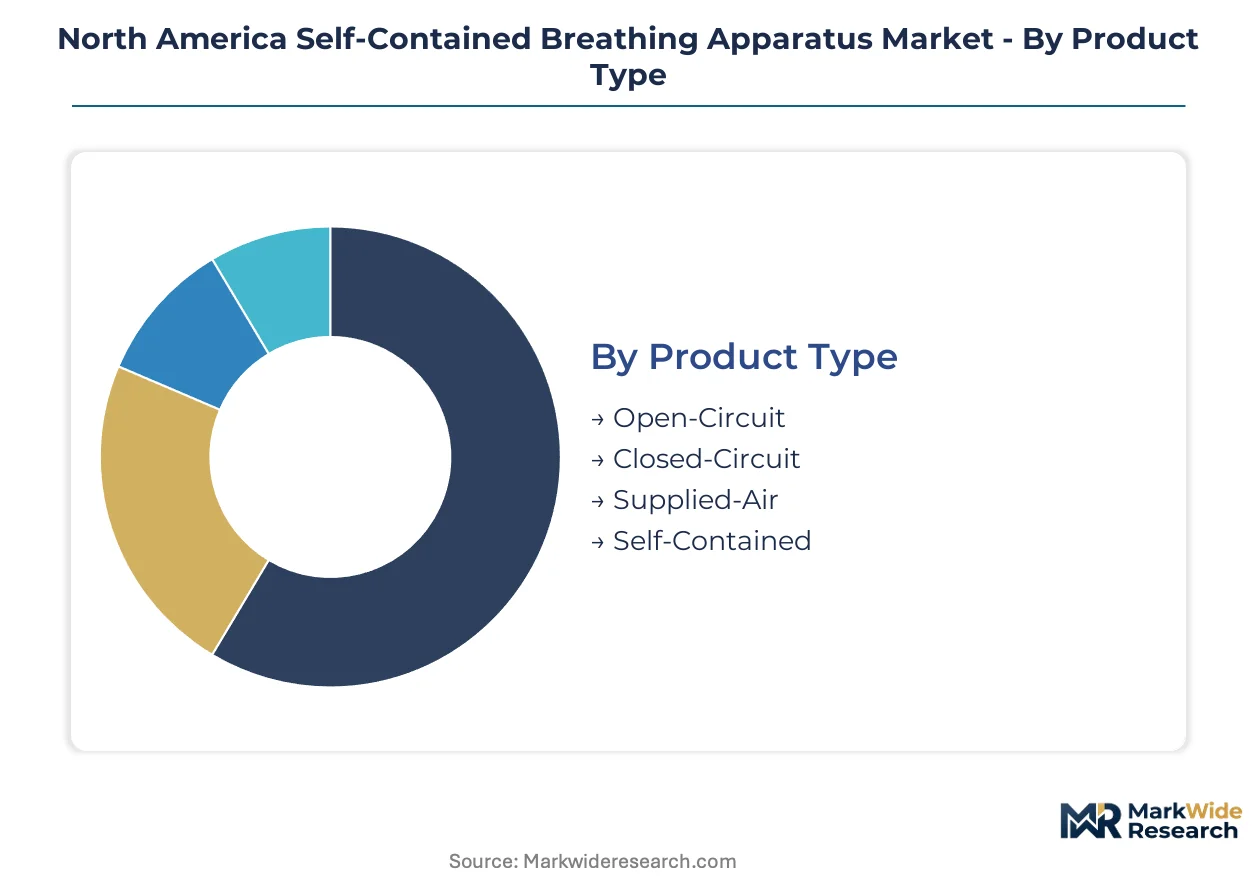
The North America self-contained breathing apparatus market delineates into several core segments, reflecting diverse operational demands and regulatory compliance needs. These classifications highlight distinct product specifications and end-user requirements across various industries.
Product Type:
The market for self-contained breathing apparatus is fundamentally defined by the technical specifications of its air delivery systems, catering to varied duration and environmental challenges.
- Open-Circuit:These systems release exhaled air into the atmosphere, providing a continuous flow of fresh air from a compressed cylinder. Demand concentrates in municipal firefighting services across the US, driven by NFPA 1981 standards for rapid deployment.
- Closed-Circuit:These units recirculate exhaled air after removing carbon dioxide and replenishing oxygen, significantly extending operational duration. Mining operations in Canada utilize these for extended underground missions, where long air supply is critical for safety.
- Supplied-Air:This equipment delivers breathable air from a remote source via a hose, suitable for situations requiring prolonged stationary work. Chemical processing plants in North America deploy these for tasks within confined spaces, ensuring continuous air supply.
- Self-Contained:This term broadly encompasses all units carrying their own air supply, isolating users from contaminated environments. Industrial safety protocols in the US mandate their use in hazardous material response, protecting workers from immediate threats.
Open-Circuit systems lead on scale; Closed-Circuit systems lead on momentum.
Industry Vertical:
Demand for respiratory protection varies significantly across industrial and public service sectors, each presenting unique operational hazards and regulatory requirements.
- Firefighting:This sector represents the largest end-user segment, relying on SCBA for structural fires, wildland incidents, and hazardous material responses. Municipal fire departments in the US consistently upgrade equipment to meet NFPA 1981 standards, driving replacement cycles.
- Chemical:Facilities handling toxic gases and volatile substances require SCBA for routine maintenance, emergency response, and confined space entry. Canadian petrochemical plants invest in high-performance units to protect workers from airborne contaminants.
- Mining:Underground mining operations use SCBA for escape and rescue, particularly closed-circuit types, to navigate oxygen-deficient or toxic atmospheres. Mines in the US often integrate SCBA with other safety systems for enhanced worker protection.
- Construction:Workers in demolition, abatement, or hazardous site remediation utilize SCBA to protect against dust, fumes, and chemical exposures. OSHA regulations in North America mandate respiratory protection on sites with airborne hazards.
Firefighting remains the dominant end-use, while Chemical applications show consistent expansion.
Application:
The specific operational context dictates the type and duration of self-contained breathing apparatus required, addressing distinct safety imperatives.
- Rescue Operations:This segment encompasses emergency services deploying SCBA for victim extrication from collapsed structures, confined spaces, or toxic environments. Urban search and rescue teams in the US depend on SCBA for critical life-saving missions.
- Industrial Hazards:SCBA protects workers engaged in tasks involving exposure to toxic gases, oxygen deficiency, or airborne particulates within industrial settings. Oil and gas facilities in Alberta, Canada, mandate SCBA for maintenance in processing units.
- Hazardous Waste:Personnel involved in the cleanup, transport, or disposal of dangerous materials use SCBA to prevent inhalation of harmful substances. Environmental protection agencies in North America enforce strict safety protocols for waste site workers.
- Military Use:Specialized military units employ SCBA for chemical, biological, radiological, and nuclear (CBRN) defense, as well as confined space entry during operations. US military forces integrate SCBA into their standard equipment for personnel protection.
Rescue Operations drive significant volume, with Industrial Hazards representing a vital safety requirement.
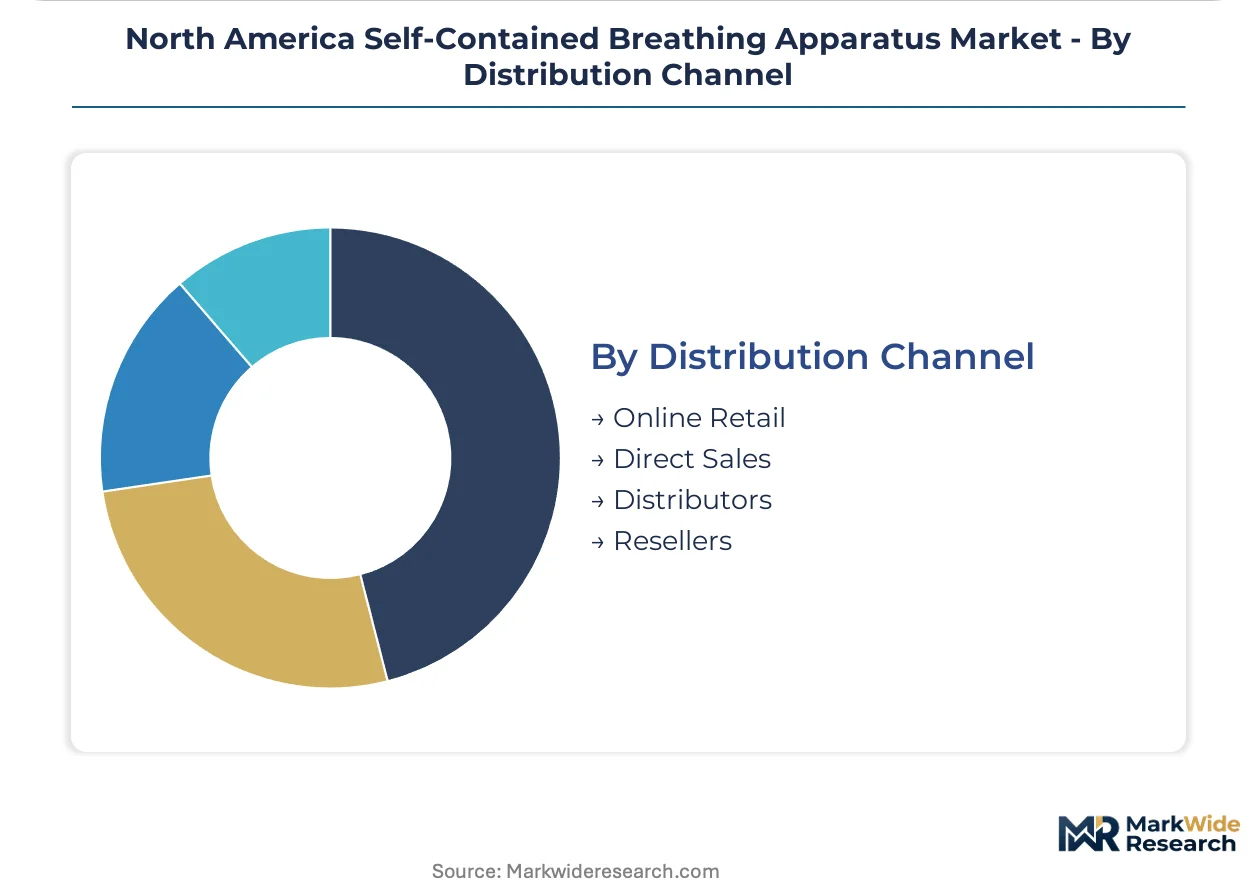
Distribution Channel:
The procurement and delivery of self-contained breathing apparatus occur through various channels, each optimizing for reach, service, or cost efficiency.
- Direct Sales:Manufacturers engage directly with large institutional buyers, such as major fire departments or government agencies, offering customized solutions and comprehensive service contracts. MSA Safety often employs direct sales for large fleet procurement by US metropolitan fire services.
- Distributors:Independent companies purchase SCBA from manufacturers and resell them to a broader customer base, often providing local support, training, and maintenance. Regional distributors serve a wide network of smaller fire departments and industrial clients across Canada.
- Online Retail:This channel facilitates convenient purchasing for smaller industrial users or individual contractors, offering a range of standard SCBA models and accessories. Specialized safety equipment websites in North America provide product specifications and delivery services.
- Resellers:These entities often integrate SCBA into larger safety equipment packages or offer them as part of a broader product portfolio to niche markets. Safety solution providers in the US bundle SCBA with other PPE for hazardous material teams.
Direct Sales secures major contracts, while Distributors ensure broad market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American self-contained breathing apparatus market traces its origins to early industrial safety needs and firefighting advancements in the 20th century. Early innovations in respiratory protection in the United States and Canada laid the groundwork for modern SCBA systems. This foundational period established initial demand for reliable air supply in hazardous environments.
United States
Demand for SCBA in the United States stems from rigorous industrial safety mandates and municipal firefighting needs. OSHA regulations and NFPA 1981 standards compel regular equipment upgrades across various sectors. Major metropolitan fire departments, such as those in New York and Los Angeles, consistently invest in advanced SCBA systems for first responders.
Canada
Canadian industrial safety protocols, particularly in oil and gas, drive significant SCBA procurement. Health Canada guidelines and provincial OHS acts enforce stringent respiratory protection requirements for workers. Alberta's energy sector, centered around Calgary, represents a major hub for specialized SCBA solutions in hazardous environments.
Mexico
Mexico's expanding manufacturing sector and growing focus on worker safety generate demand for SCBA. STPS regulations and specific NOMs dictate the use of certified respiratory protection in high-risk industrial settings. Industrial parks in Monterrey and Ciudad Juárez frequently procure SCBA for emergency response teams and hazardous material handling.
North America Self-Contained Breathing Apparatus Market Key Industry Players
The competitive structure tilts toward established safety equipment manufacturers with deep distribution networks. This market features a mix of large diversified conglomerates and specialized breathing apparatus providers. Strategic archetypes include full-spectrum solution providers, technology innovators, and niche industrial specialists. Dominant competitive moves involve portfolio diversification and strategic partnerships to meet evolving regulatory demands.
On the premium-tier vector, MSA Safety and Honeywell International Inc. exemplify companies with broad product portfolios and extensive reach across North America. Both companies anchor significant market share through their established brand recognition and long-standing relationships with fire services and industrial clients. 3M, a diversified technology company, represents another prominent player, leveraging its material science expertise to differentiate its respiratory protection offerings. These entities maintain strong positions by continually adapting their SCBA systems to meet stringent safety standards.
| Leading Market Players |
|---|
| MSA Safety |
| 3M |
| Drägerwerk AG & Co. KGaA |
| Honeywell International Inc. |
| Avon Protection |
| Scott Safety |
| Interspiro |
| 3M Scott Fire & Safety |
| Levitt-Safety Limited |
| Others |
Cost & Logistics Intelligence
Carbon fiber for compressed air cylinders represents a significant cost component, tracing its path from specialized material suppliers through manufacturing to the final SCBA unit. This material cost directly influences the pricing structures across various product tiers and end-user segments in North America.
Pricing Analysis
Tiered transactional pricing structures dominate the North America self-contained breathing apparatus market, reflecting product complexity and performance. Price differentiation arises from NFPA 1981 certification levels and the integration of advanced data telemetry capabilities. Pricing pressure stems from stringent regulatory updates compelling frequent equipment upgrades, which manufacturers absorb through R&D investment. Smaller industrial users exhibit the most price sensitivity, while large metropolitan fire departments prioritize advanced features and comprehensive service packages.
Supply Chain Analysis
Logistics and freight costs influence the final delivered price of SCBA units, particularly for specialized components sourced internationally. Geographic supply concentration for critical components rests in the United States, Germany, and select Asian countries for specialized electronics. Raw material dependencies include advanced composite materials, high-pressure valve assemblies, and sensor technologies. Component price volatility represents a structural risk due to reliance on specialized suppliers. Distribution runs through a dual model of direct sales to major buyers and a network of regional distributors for broader market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the premiumization of SCBA systems through advanced digital integration and enhanced safety features.
For Market Incumbents:Acquire specialized software firms with expertise in real-time data analytics and wireless communication protocols. Enhance internal R&D capabilities to integrate physiological monitoring sensors, addressing the threat of new entrants with niche technological advantages. Invest in advanced materials science to reduce product weight and improve ergonomics, securing long-term contracts with major fire service clients. Leverage existing distribution networks to offer bundled service and training packages, reinforcing brand loyalty against competitive pressures.
For New Entrants and Emerging Players:Enter via strategic partnerships with established safety equipment distributors to overcome high market entry barriers. Target underpenetrated applications, such as pharmaceutical cleanroom emergency response or specialized hazardous material handling teams, for initial market penetration. Focus on developing cost-effective, modular SCBA systems that meet specific industrial safety requirements without extensive customization. Offer a clear value proposition centered on ease of maintenance and rapid deployment for smaller industrial buyers.
For Investors and Strategic Acquirers:Consolidation pressure builds where regulatory compliance costs are high and technological innovation cycles accelerate. The North America SCBA market offers sustained long-term viability due to non-negotiable safety mandates and continuous equipment replacement cycles. Identify acquisition targets that possess strong intellectual property in connectivity solutions or advanced material composites for cylinders. A successful integration of AI-driven predictive maintenance features into SCBA systems represents a key signal to watch for future market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in IoT Integration | Enhances firefighter safety by providing real-time data to incident commanders. |
| Develop Advanced Composite Materials | Reduces SCBA weight, improving user ergonomics for North American fire departments. |
| Form Strategic Partnerships | Expands market reach into specialized industrial niches like chemical processing plants. |
| Pursue NIOSH/NFPA Certification | Ensures compliance with evolving safety standards for all North American users. |
| Offer Bundled Service Contracts | Secures long-term revenue streams from large metropolitan fire departments. |
Research Approach
Direct dialogue with fire chiefs, industrial safety managers, SCBA design engineers, and regulatory compliance officers provided critical qualitative insights. This primary research was rigorously validated through secondary data sources, including NFPA standards documents, OSHA enforcement reports, company annual reports, and industry association publications. A combination of bottom-up and top-down triangulation ensured comprehensive market coverage and accuracy.
A bottom-up approach quantified demand from end-user segments, while a top-down analysis validated overall market size across the analysis window. Segmentation dimensions modeled included product type, industry vertical, application, distribution channel, and regulatory compliance cycles. Compound annual growth rates were derived from historical growth trends and projected regulatory impacts, with NFPA standard revision schedules and industrial safety investment trends serving as key forecast inputs.
Inputs from regulatory body publications and manufacturer product disclosures were available through the study window; gaps in granular regional spending data introduce uncertainty bands around specific sub-segment projections. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Stakeholders should weight assumptions against their own operating context, considering potential impacts from unforeseen supply chain disruptions or rapid shifts in material science.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Gowns Market
Safety Equipment and Personal Protective Equipment (PPE)
Crash Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Radar Speed Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Barrier Systems Market