
 US Industrial Barrier Systems Market | 2026-2036
US Industrial Barrier Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US Industrial Barrier Systems Market Insights
The gap between premium polymer-composite systems and commodity steel guardrails is expanding across US distribution centers and heavy manufacturing floors. Rite-Hite leverages its captive installation network to dominate turnkey loading dock barrier programs. A-Safe sustains technology leadership in flexible polymer impact absorption for food-grade and cleanroom environments. BOPLAN competes aggressively on modular reconfiguration speed, targeting automotive assembly lines with frequent layout changes.
Industrial barrier systems encompass physical protective structures engineered to absorb or deflect vehicle impact, pedestrian separation, and equipment collision in commercial and industrial facilities. Typical specifications include ASTM F2656 crash-test ratings for vehicle barriers, OSHA 1910.176 compliance for material handling zones, and deflection tolerances measured in inches at defined impact velocities. Fixed barriers anchor permanent perimeter protection in manufacturing plants, while modular installations capture the fastest expansion as warehouses adopt reconfigurable zone management. Composite materials command premium positioning due to corrosion immunity and color customization, whereas steel retains volume dominance in outdoor and heavy-vehicle applications.
OSHA, the Federal Highway Administration, and state DOTs collectively shape barrier system demand through workplace safety mandates, roadway work zone specifications, and procurement qualification requirements. NHTSA guidelines for off-road industrial vehicles indirectly influence barrier impact rating thresholds adopted by end users. Stakeholders must monitor evolving MASH crash-test standards and state-level Buy America provisions that could reroute material sourcing and certification strategies.
Market Dynamics
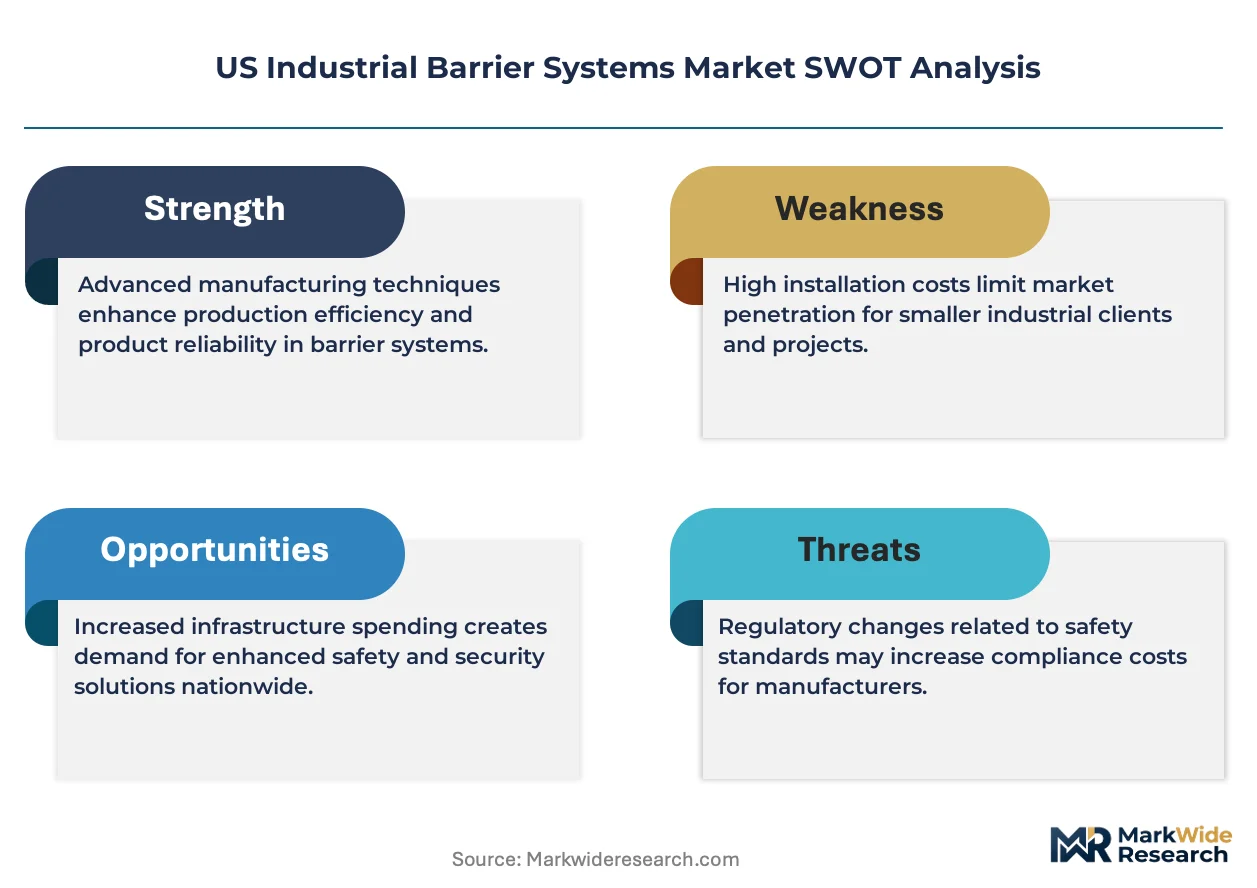
Polymer composite materials are compressing the traditional steel-dominant supply base as Texas Gulf Coast petrochemical operators and national distribution networks rewrite material specifications around corrosion immunity and color-coded zone management.
Growth Catalysts
- OSHA 1910.176 mandates:Warehouse material handling zones face intensified pedestrian-vehicle separation requirements, forcing retrofit installations across existing facilities.
- Texas Gulf Coast concentration:Petrochemical corridor expansion drives specialized barrier procurement for high-corrosion, high-impact environments.
- Flexible polymer impact absorption:Food-grade and cleanroom facilities adopt deflection-tolerant systems that reduce floor damage and maintenance cycles.
Market Restraints
- Steel input cost volatility:Hot-rolled coil price swings compress margin stability for commodity guardrail producers serving outdoor applications.
- Composite material supply concentration:Domestic polymer resin production clusters along the Gulf Coast expose buyers to hurricane disruption risk.
- MASH crash-test certification timelines:Extended Federal Highway Administration approval cycles delay product launches for roadway-adjacent industrial sites.
Strategic Opportunities
- Automotive assembly line reconfiguration:Michigan and Ohio plants demand modular barrier systems enabling rapid layout shifts for model changeovers.
- Buy America provisions:Infrastructure Investment and Jobs Act domestic content rules create preference for US-manufactured barrier systems in federally funded projects.
- Smart facility integration:Convergence of polymer barriers with IoT-enabled impact sensors opens predictive maintenance contracts.
Industry Challenges
- Polymer welding technician scarcity:Composite installation requires specialized thermal bonding skills absent from traditional steel fabrication workforces.
- Legacy concrete anchoring incompatibility:Retrofit projects face structural assessment delays when existing floor slabs cannot support dynamic load specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Industrial Barrier Systems Market |
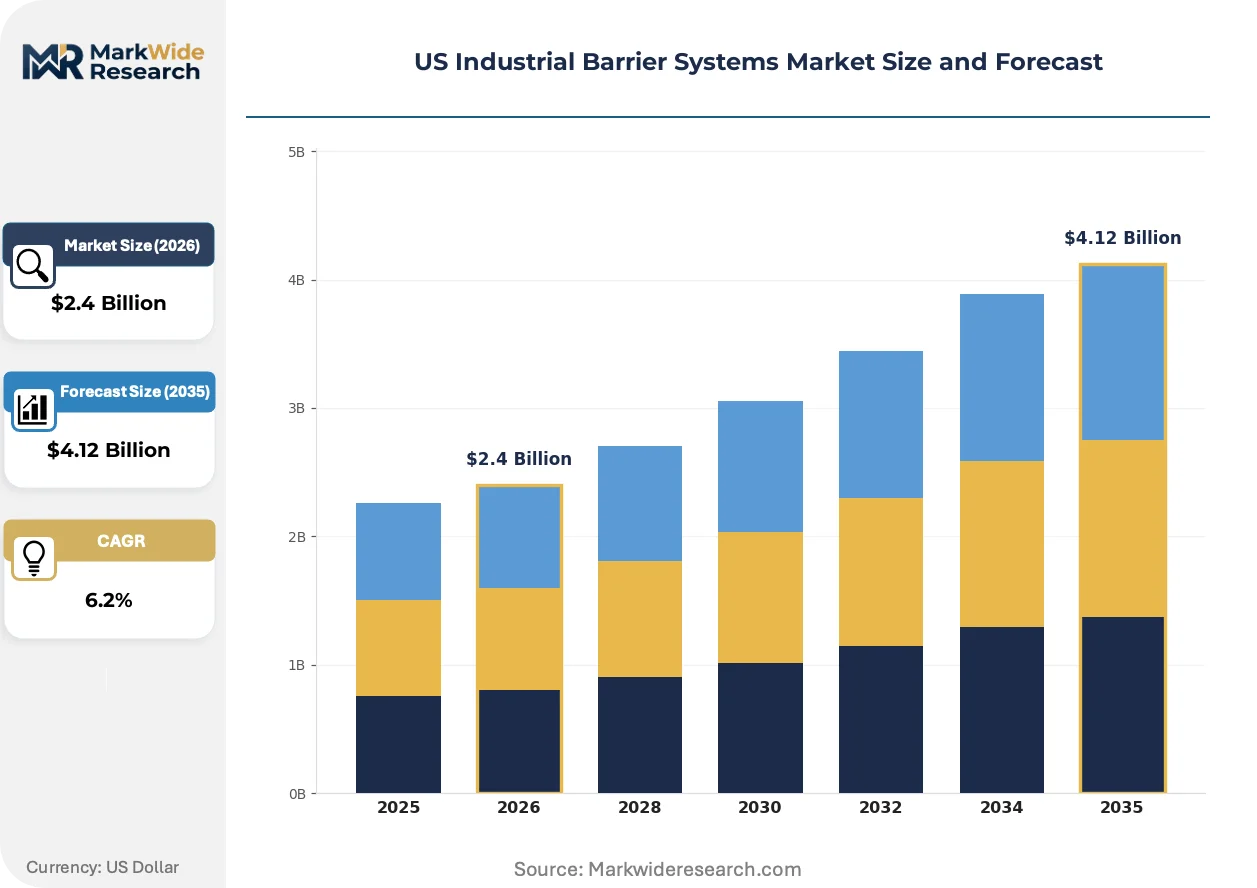
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Barriers, Mobile Barriers, Crash Barriers, Safety Fences Material: Steel, Concrete, Plastic, Composite Application: Manufacturing, Warehousing, Transportation, Construction Installation: Permanent, Temporary, Modular, Custom |
| Companies Covered | A-Safe, BOPLAN, Rite-Hite, Fabenco by Tractel, Barrier1, CAI Safety Systems, Inc., Wildeck, McCue, TrafFix Devices, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Industrial Barrier Systems Market Trends and Innovations
Active reshaping of this market centers on material substitution dynamics, regulatory recalibration of impact standards, and procurement model compression toward integrated safety-as-service offerings.
Polymer composite barrier systems are consolidating specification authority across food processing and pharmaceutical manufacturing floors. Cleanroom operators in North Carolina and New Jersey biotechnology clusters specify color-coded polymer railings to eliminate corrosion particle contamination. This material shift is consolidating vendor relationships around single-source polymer specialists capable of custom formulation and rapid prototyping.
OSHA workplace safety enforcement patterns are tightening documentation requirements for material handling zone risk assessments. Facility safety managers must now maintain impact-test certificates and maintenance logs for all vehicle barriers. Distribution centers in California and Illinois respond by centralizing procurement through specialized safety distributors rather than general construction suppliers.
Integrated service contracts now bundle barrier installation, inspection, and replacement into multi-year agreements. Third-party logistics operators in the Southeast and Midwest abandon capital purchase models for per-linear-foot subscription pricing. This restructuring concentrates vendor selection criteria on nationwide service network density rather than unit manufacturing cost alone.
US Industrial Barrier Systems Market Segmentation
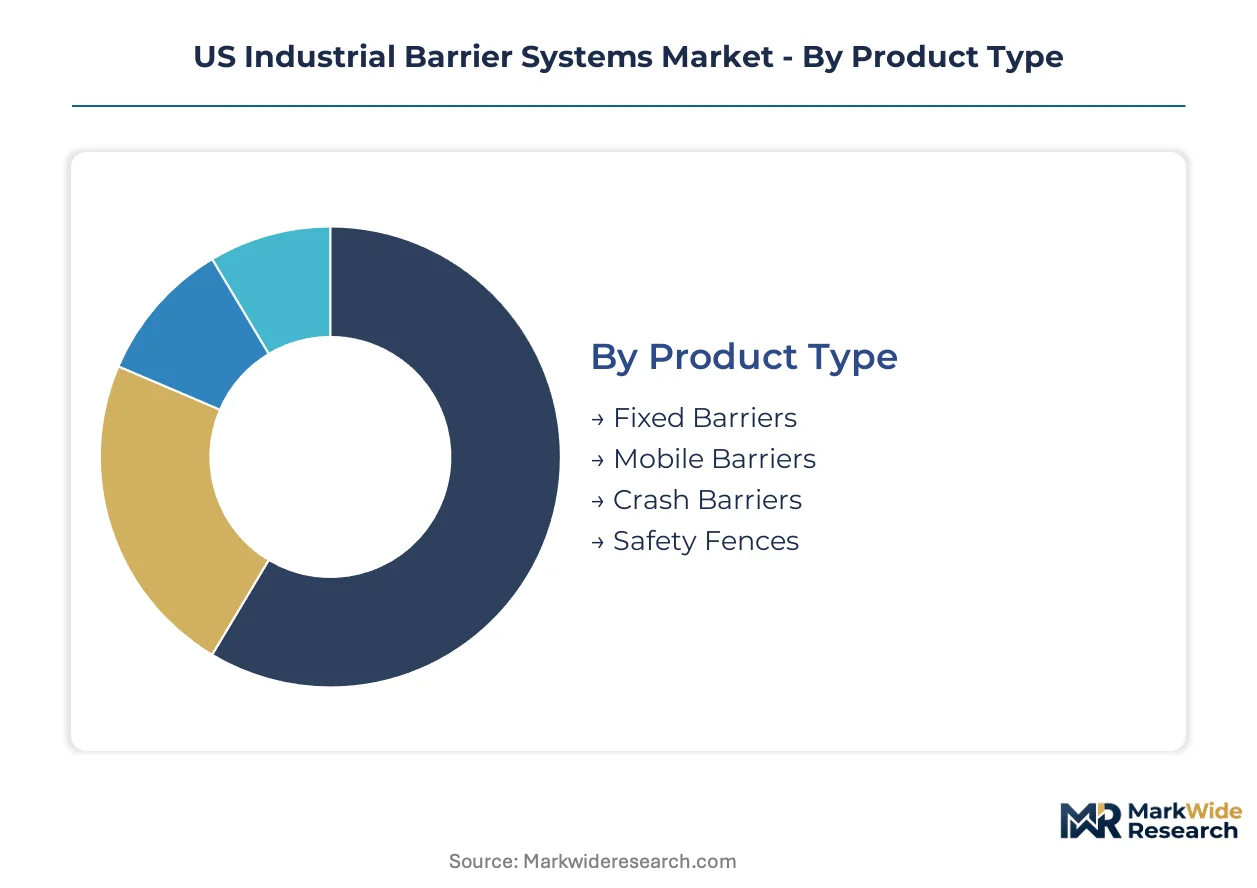
Barrier system procurement in the United States fragments across four critical dimensions that reshape vendor selection criteria and margin structures. Certification burdens vary sharply by segment, with crash-test ratings and OSHA compliance creating tiered qualification barriers that favor specialized suppliers over generalist fabricators.
Product Type:
ASTM F2656 crash-test certification separates vehicle-rated systems from pedestrian-only barriers, while OSHA 1910.176 compliance applies universally across material handling zones.
- Fixed Barriers:Permanent anchor systems bolted to concrete slabs provide perimeter protection for manufacturing plants and loading docks. Texas Gulf Coast petrochemical operators specify fixed barriers with corrosion-resistant coatings for high-humidity, chemical-exposure environments where replacement cycles must extend beyond fifteen years.
- Mobile Barriers:Castor-mounted or forklift-transportable units enable rapid zone reconfiguration without structural modification. Automotive assembly plants in Michigan and Ohio deploy mobile barriers to accommodate model changeovers, with procurement concentrated among Tier 1 suppliers requiring same-day layout flexibility.
- Crash Barriers:Impact-rated systems tested to MASH or ASTM standards for vehicle containment.
- Safety Fences:Light-duty pedestrian separation for low-velocity zones.
Leading the category by volume: Fixed Barriers. Growing fastest: Mobile Barriers.
Material:
Cost tiers stratify sharply, with polymer composites commanding 2-3x steel pricing but eliminating lifecycle maintenance expenditures.
- Steel:Hot-rolled and galvanized configurations dominate outdoor and heavy-vehicle applications. Distribution centers in California and Illinois specify steel guardrails for loading dock perimeters where upfront capital constraints outweigh long-term maintenance considerations.
- Composite:Fiber-reinforced polymer systems absorb impact through material deflection rather than structural deformation. Food-grade facilities in North Carolina and New Jersey biotechnology clusters mandate composite railings to eliminate corrosion particle contamination in cleanroom environments.
- Concrete:Precast or poured-in-place systems for maximum impact resistance.
- Plastic:Lightweight polyethylene barriers for temporary pedestrian channeling.
Highest volume share: Steel. Steepest expansion trajectory: Composite.
Application:
End-use concentration determines specification authority, with warehousing operators consolidating procurement through specialized safety distributors.
- Warehousing:Third-party logistics operators and e-commerce fulfillment centers drive the largest absolute demand volume. OSHA pedestrian-vehicle separation mandates force retrofit installations across existing facilities in the Southeast and Midwest, with specification authority shifting from facility managers to corporate safety directors.
- Manufacturing:Heavy industrial floors require impact-rated systems for forklift and AGV traffic. Petrochemical processors along the Texas Gulf Coast specify corrosion-immune barriers for outdoor tank farms and process unit perimeters.
- Transportation:Airport cargo facilities and intermodal terminals.
- Construction:Temporary work zone protection for roadway-adjacent industrial sites.
Dominant by revenue: Warehousing. Gaining share fastest: Manufacturing.
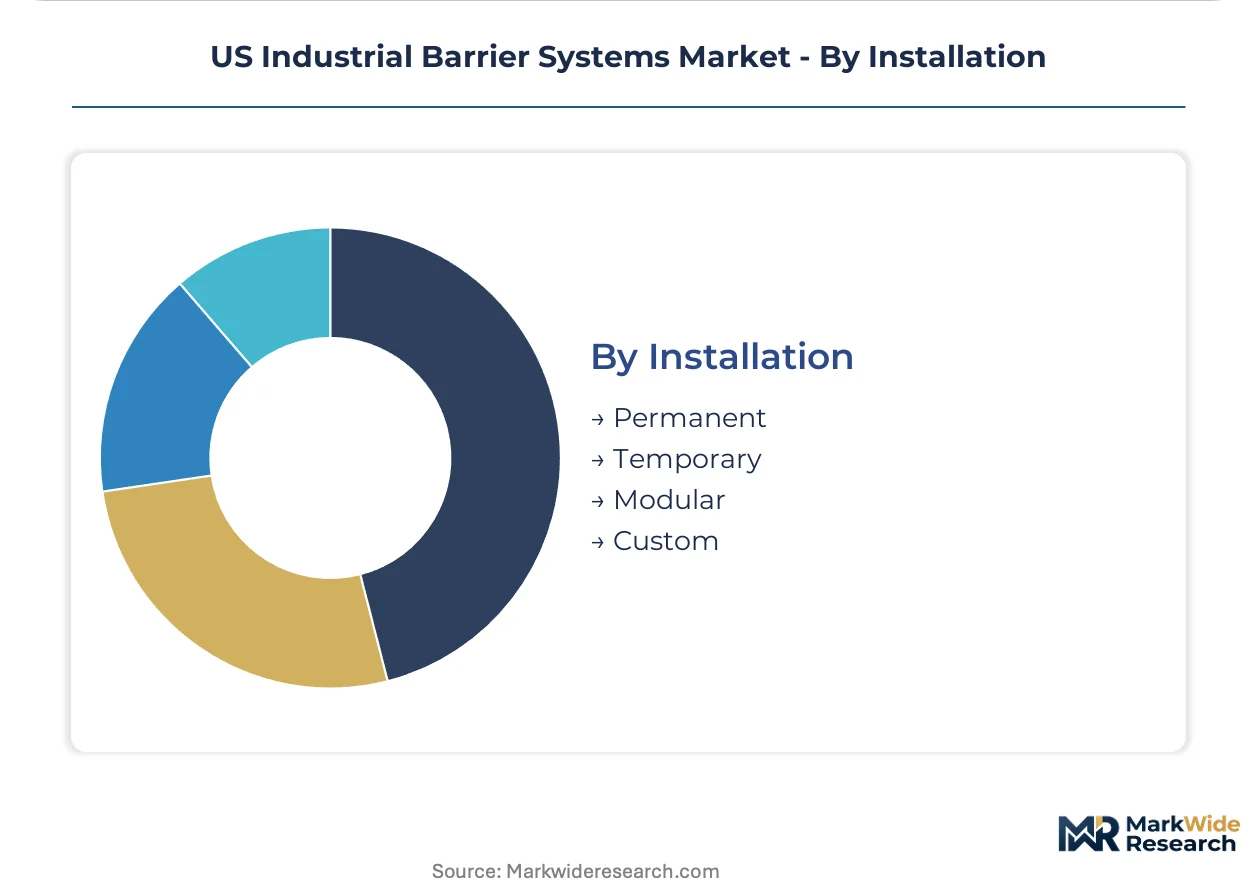
Installation:
Customer type splits between capital-purchase facilities and subscription-model operators seeking to convert fixed costs to variable expenditures.
- Modular:Component-based systems enable rapid reconfiguration without specialized labor. Southeast and Midwest distribution networks adopt modular barriers to support seasonal volume fluctuations, with vendors offering per-linear-foot subscription pricing that bundles installation and replacement.
- Permanent:Cast-in-place or heavy-anchor systems for structural integration.
- Temporary:Rapid-deploy barriers for short-duration projects.
- Custom:Engineered-to-order systems for non-standard facility geometries.
Largest installed base: Permanent. Expanding most quickly: Modular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Gulf Coast petrochemical corridor concentrates the nation's highest barrier system deployment intensity. Houston-Beaumont-Port Arthur industrial zones drive specialized procurement for corrosion-immune protection in high-humidity chemical processing environments.
Texas Gulf Coast
Petrochemical expansion along the Houston Ship Channel and Beaumont-Port Arthur complex demands specialized barrier systems for tank farm perimeters and process unit protection. OSHA Process Safety Management standards and EPA Risk Management Plan requirements mandate robust vehicle containment infrastructure. Corpus Christi LNG export terminals add incremental demand for marine-grade composite barriers in salt-air environments.
Southeast Distribution Belt
Third-party logistics operators in Georgia and South Carolina retrofit existing warehouses under intensified OSHA 1910.176 enforcement. The Savannah-Charlotte-Atlanta freight corridor concentrates e-commerce fulfillment center construction requiring modular pedestrian-vehicle separation systems. State workforce safety agencies in Georgia and South Carolina coordinate inspection protocols with federal OSHA regional offices.
Midwest Manufacturing Core
Automotive assembly plants in Michigan and Ohio deploy mobile barrier systems for production line reconfiguration flexibility. Michigan OSHA workplace safety inspections focus on forklift traffic management in Tier 1 supplier facilities. Detroit-Warren-Flint metropolitan statistical area leads national demand for rapid-reconfiguration modular installations.
California Logistics Hubs
Inland Empire distribution centers face Cal/OSHA pedestrian protection mandates exceeding federal baseline requirements. Los Angeles-Long Beach port complex cargo facilities specify ASTM F2656-rated crash barriers for intermodal terminal security. California Air Resources Board indirect source rules influence warehouse construction standards affecting barrier placement protocols.
Northeast Biotechnology Clusters
Cleanroom facilities in New Jersey and North Carolina pharmaceutical manufacturing zones specify color-coded polymer barriers to eliminate corrosion particle contamination. FDA Current Good Manufacturing Practice guidelines implicitly shape facility design standards affecting barrier material selection. Research Triangle Park and New Brunswick-Piscataway corridors concentrate food-grade barrier demand.
US Industrial Barrier Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across installation service models and material technology tiers. The vendor base stratifies between turnkey solution providers capturing long-term service contracts and component specialists selling through distribution channels. Three archetypes dominate: captive installation networks bundling design-to-maintenance programs, polymer formulation specialists commanding premium specification authority, and steel fabricators competing on upfront capital cost. Consolidation pressure intensifies through strategic partnerships linking regional installers with national material suppliers, while technology licensing agreements accelerate composite barrier penetration into conventional steel-dominated accounts.
Among captive installation network operators, Rite-Hite anchors the turnkey service tier with integrated loading dock and barrier system programs. A-Safe and BOPLAN occupy positions within the polymer specialist archetype, with A-Safe exemplifying technology leadership in flexible impact absorption and BOPLAN representing modular reconfiguration speed for automotive applications. These three companies illustrate the competitive divergence between service-integrated and product-centric market positions.
| Leading Market Players |
|---|
| A-Safe |
| BOPLAN |
| Rite-Hite |
| Fabenco by Tractel |
| Barrier1 |
| CAI Safety Systems, Inc. |
| Wildeck |
| McCue |
| TrafFix Devices, Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive installation networks anchor both supply positioning and pricing power for turnkey barrier system providers, creating separation between service-integrated vendors competing on outcome-based contracts and component specialists locked into transactional pricing. Rite-Hite's vertically controlled deployment infrastructure enables subscription-model premiums that commodity fabricators cannot match, while polymer specialists like A-Safe leverage formulation IP to sustain margin tiers above steel alternatives.
Pricing Analysis
Outcome-based pricing tied to facility uptime and safety incident reduction anchors premium tiers for integrated service providers. Three-tier pricing structure across premium polymer composite, mid-grade steel, and economy galvanized configurations reflects certification grade and after-sales bundling intensity. Pricing pressure stems from hot-rolled coil volatility compressing margins for outdoor steel guardrail producers. Warehousing operators exhibit highest price sensitivity due to capital purchase constraints, while petrochemical facilities prioritize lifecycle cost over upfront expenditure.
Supply Chain Analysis
Dual-sourcing requirements from federal contractors and large distribution networks mandate multi-supplier qualification for polymer resin and steel coil inputs. Domestic production clusters along the Texas Gulf Coast and Midwest steel belt draw from concentrated petrochemical feedstock and regional hot-rolled coil capacity. Supply chain risk centers on hurricane exposure disrupting Gulf Coast resin production during peak season. Distribution runs through specialized safety distributors consolidating procurement authority away from general construction supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where OSHA 1910.176 enforcement intensity creates a barrier-to-entry moat for certified incumbents capable of sustaining documentation and testing investments that generalist fabricators cannot match.
For Market Incumbents: Anchor market position through captive control of polymer welding technician pipelines and MASH certification capabilities that emerging competitors lack. Defensive consolidation should prioritize acquiring regional installation networks in the Southeast Distribution Belt to preempt subscription-model competitors. Threat of modular reconfiguration specialists like BOPLAN capturing automotive assembly line share demands counterinvestment in rapid-deployment service infrastructure. For New Entrants and Emerging Players: Begin with white-space targeting of secondary logistics markets in Tennessee and Kentucky where OSHA enforcement intensity lags coastal states but warehouse construction accelerates. The most penetrable segment lies in temporary barrier rental for construction-adjacent industrial sites facing MASH approval delays. Go-to-market execution should emphasize per-linear-foot subscription pricing to bypass capital purchase committee resistance. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by building products conglomerates seeking safety system diversification. Long-term viability favors vendors with demonstrated polymer formulation capabilities and nationwide service network density over pure-play steel fabricators. Watch for inflection in federal infrastructure spending execution triggering Buy America procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Formulation IP Acquisition | Captures corrosion-immune specification authority in Gulf Coast petrochemical corridors. |
| MASH Certification Fast-Track Investment | Accelerates product launch timelines for roadway-adjacent industrial site penetration. |
| IoT Sensor Integration Partnership | Enables predictive maintenance contracts converting capital expenditure to recurring revenue. |
| Welding Technician Training Pipeline | Resolves composite installation scarcity constraining polymer barrier deployment velocity. |
| Regional Installer Network Consolidation | Builds density required for per-linear-foot subscription model viability in Midwest markets. |
Research Methodology
Independent corroboration across facility safety directors, polymer formulation engineers, and OSHA compliance officers underwrites the qualitative findings in this analysis. Primary fieldwork engaged plant engineers at Texas Gulf Coast petrochemical operators, procurement leads at third-party logistics providers, and aftermarket service heads at barrier system distributors. Secondary validation drew from OSHA enforcement databases, FHWA MASH certification records, and SEC filings of publicly traded safety equipment manufacturers. Bottom-up demand modeling triangulated against top-down industrial construction expenditure tracking.
Comparable-period anchoring to historical facility retrofit cycles and petrochemical expansion waves structured the forecast window. Segmentation modeling spanned product type, material composition, installation modality, and regional regulatory cluster dimensions. CAGRs derived from regression analysis of barrier system procurement against industrial construction permits and OSHA inspection intensity indices. Forecast inputs incorporated polymer resin price trajectory assumptions and federal infrastructure appropriation execution rates.
Underlying measurement precision varies by segment; warehousing and manufacturing application data carry tighter precision than emerging smart facility integration categories. Forecasts reflect documented assumptions regarding OSHA enforcement continuity and Gulf Coast hurricane frequency. Deviation in federal Buy America procurement implementation or MASH standard revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
China Premium Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Snowmobile Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Technologies Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Hazard and Safety Indicator Control Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Public Address and Voice Alarm Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market