
 Strobe Beacon Market | 2026-2036
Strobe Beacon Market Size, Share, and Industry Trends Forecast 2026-2036
Strobe Beacon Market Insights
A capital-intensity divergence between in-house LED driver production and outsourced assembly is rotating competitive advantage toward vertically integrated manufacturers. Federal Signal leverages captive semiconductor sourcing to sustain margin resilience across North American industrial accounts. PATLITE Corporation anchors its position through dedicated R&D facilities in Osaka that specialize in multi-color programmable strobes for semiconductor fabs.
A strobe beacon is a high-intensity visual warning device that generates rapid flashes of light through gas discharge or solid-state emission, typically operating between 1 and 5 joules per flash with IP66 or higher enclosure ratings for harsh environments. Its primary industrial purpose is to alert personnel to hazardous conditions, equipment status changes, or emergency evacuations in high-noise settings where audible signals prove ineffective. LED-based product types now dominate value capture due to their 50,000-hour operational lifespan and compatibility with low-voltage DC systems, while xenon sources retain niche dominance in explosive-atmosphere applications requiring intrinsically safe certification. Emergency response applications command premium pricing through NFPA and EN 54 compliance requirements, whereas construction sector demand concentrates in magnetic-mount portable units for rental fleet deployment.
OSHA workplace safety standards and the EU Machinery Directive collectively mandate visible warning devices on mobile industrial equipment, forcing OEMs to spec integrated strobe systems at the factory level rather than retrofit. The FCC regulates electromagnetic emissions from battery-powered wireless beacon systems, creating compliance barriers for unlicensed spectrum designs in US logistics hubs. Stakeholders must monitor evolving IEC 60079 explosion-protection standards as hydrogen economy infrastructure expands, since revised gas group classifications will recertify existing product lines.
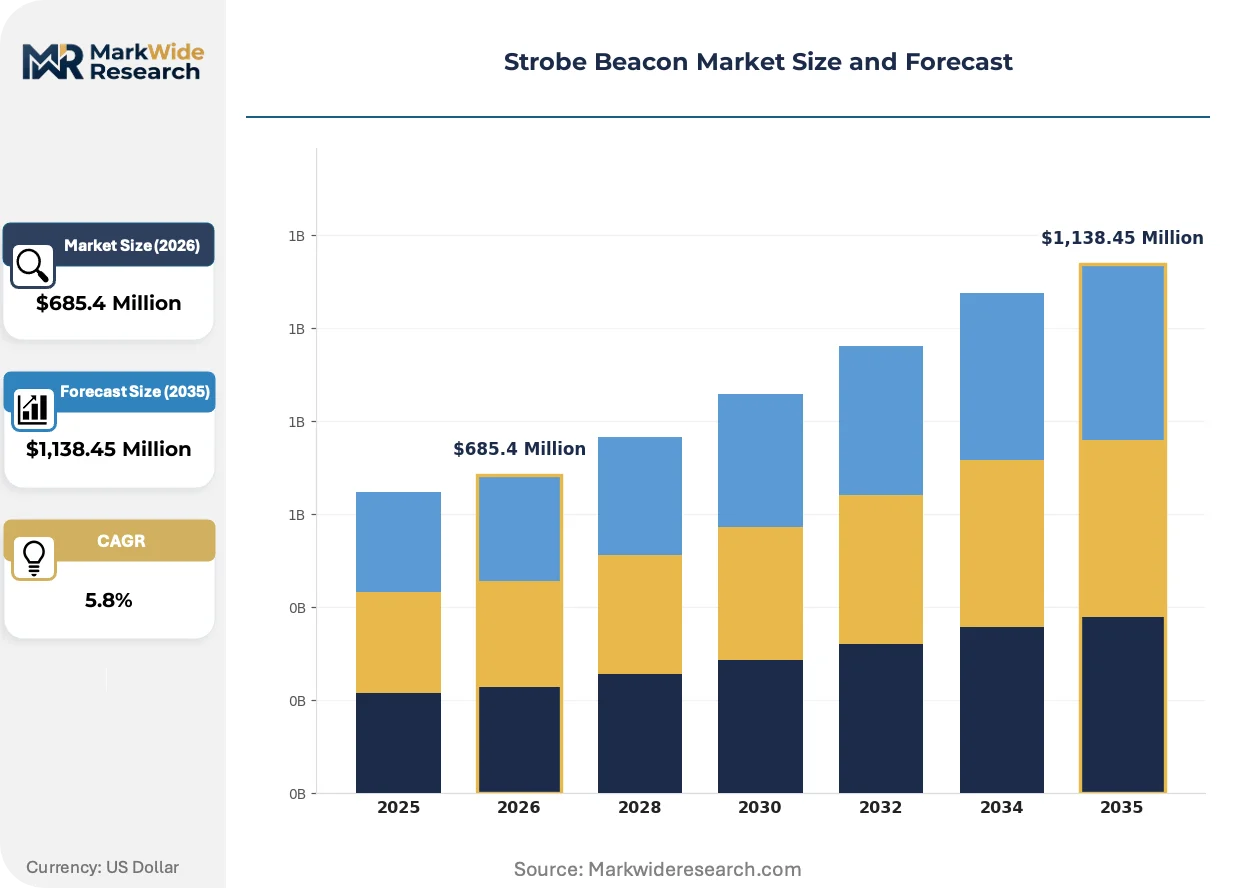
Market Dynamics
LED solid-state emission is decomposing the incumbent xenon gas-discharge architecture across industrial safety applications, compressing maintenance cycles and recalibrating supplier qualification criteria for mining and semiconductor fabrication end-users.
Growth Catalysts
- EU Machinery Directive mandates:Factory-level integration of visible warning devices on mobile equipment now eliminates retrofit channels and locks OEM specification relationships.
- Hydrogen economy infrastructure:IEC 60079 explosion-protection recertification requirements for revised gas group classifications are generating replacement demand across chemical processing and energy storage installations.
- Australian mining fleet expansion:Surface and underground operators are mandating redundant visual alert systems for autonomous haulage corridors in Western Australia's Pilbara region.
Market Restraints
- Semiconductor input volatility:LED driver IC lead times and pricing instability constrain production planning for manufacturers without captive foundry arrangements.
- Xenon lamp supply concentration:Specialty glass envelope and electrode sourcing remains concentrated among a limited set of European and Japanese component suppliers.
- FCC electromagnetic compliance:Unlicensed spectrum restrictions for battery-powered wireless beacon systems create certification barriers for logistics hub deployments in the United States.
Strategic Opportunities
- German industrial corridor concentration:Machinery OEM specification teams in Baden-Württemberg and Bavaria are consolidating vendor panels for integrated safety systems.
- NFPA 72 emergency communication systems:Mass notification integration requirements for educational and healthcare facilities are expanding addressable product configurations.
- Silicon carbide driver convergence:Wide-bandgap semiconductor integration with programmable multi-color LED arrays enables higher flash rates with reduced thermal management overhead.
Industry Challenges
- IECEx/ATEX certification timelines:Intrinsically safe product qualification for Zone 0 hydrogen atmospheres extends development cycles by 12-18 months.
- Legacy system integration friction:Hardwired 24VDC control architectures in established manufacturing plants resist migration to networked beacon management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strobe Beacon Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Xenon, Halogen, Incandescent Application: Emergency Response, Construction, Marine, Industrial Mounting Type: Fixed, Magnetic, Portable, Vehicle-Mounted Power Source: Battery-Powered, AC, DC, Solar |
| Companies Covered | Federal Signal, Banner Engineering, SIRENA S.p.A., Auer Signal, PATLITE Corporation, WERMA Signaltechnik GmbH + Co. KG, E2S Warning Signals, CAPTRON Electronic, Tomar Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strobe Beacon Market Trends and Innovations
Programmable multi-spectral emission and embedded diagnostic intelligence are redefining product value propositions beyond basic alerting, shifting competitive differentiation toward predictive maintenance integration and seamless building automation connectivity.
Solid-state LED strobe technology is decomposing the historical xenon dominance in high-intensity industrial signaling. Semiconductor fabrication facilities in Taiwan and South Korea are specifying RGB-programmable units for equipment status hierarchies. The technology is compressing maintenance intervals from 5,000 to 50,000 hours while enabling centralized color-scheme management through facility SCADA networks.
OSHA workplace safety enforcement is intensifying inspection protocols for mobile equipment visibility systems in construction and warehousing operations. Citation patterns are elevating factory-integrated strobe specifications over aftermarket retrofit installations. North American rental fleet operators are now mandating magnetic-mount portable units with integrated battery monitoring as standard equipment.
Specification authority is migrating from maintenance procurement teams to corporate safety engineering functions with centralized vendor qualification programs. Approved manufacturer lists are narrowing to three-to-five suppliers with documented NFPA, UL, and IEC compliance portfolios. This concentration is most visible in United States distribution center buildouts where fire-alarm and equipment-safety beacon specifications are being unified under single-source contracts.
Strobe Beacon Market Segmentation
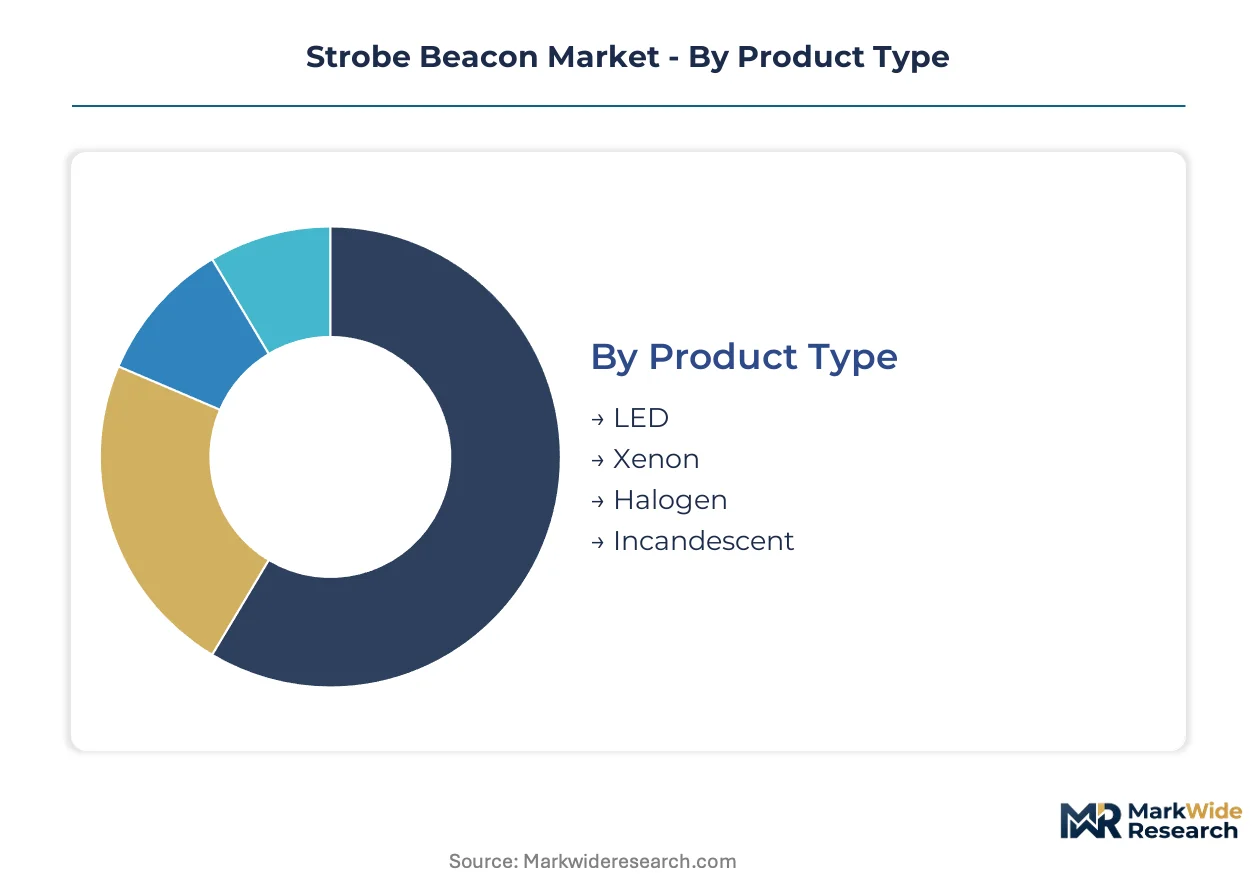
Strobe beacon segmentation reveals divergent margin structures across light source technologies and mounting configurations. Specification authority concentrates in segments where NFPA, IECEx, and OSHA compliance create certification moats that filter low-cost competitors.
Product Type:
LED-based configurations command premium positioning through 50,000-hour operational lifespans and programmable multi-spectral emission, while legacy gas-discharge architectures defend niche applications in explosive atmospheres.
- LED:Solid-state diode arrays with silicon carbide drivers enable flash rates exceeding 10Hz with minimal thermal overhead. Semiconductor fabrication facilities in Taiwan and South Korea specify RGB-programmable units for equipment status hierarchies, compressing maintenance cycles from 5,000 to 50,000 hours.
- Xenon:Gas-discharge tubes operating at 1-5 joules per flash deliver peak luminous intensity exceeding 200 candela. Intrinsically safe certification for Zone 0 hydrogen atmospheres under IEC 60079 sustains demand across chemical processing installations despite shorter lamp life.
- Halogen:Tungsten-halogen filament technology persists in marine applications requiring warm color temperature and minimal electromagnetic interference.
- Incandescent:Legacy bulb architecture retains minimal share in budget-constrained retrofit scenarios where existing 24VDC control infrastructure resists upgrade.
LED holds installed capacity across industrial and semiconductor end-uses. Xenon is rotating up the share rankings in hydrogen economy infrastructure deployments.
Application:
Emergency response specifications extract margin through NFPA 72 and EN 54 compliance requirements that extend development timelines, while construction demand concentrates in rental fleet channels with standardized portable configurations.
- Emergency Response:Mass notification integration for educational and healthcare facilities mandates synchronized strobe activation with voice evacuation systems. NFPA 72 compliance requirements for candela output and flash synchronization create specification barriers that narrow approved vendor lists to three-to-five suppliers.
- Construction:Magnetic-mount portable units dominate rental fleet procurement for temporary hazard demarcation. OSHA inspection intensification in warehousing and mobile equipment operations is elevating factory-integrated specifications over aftermarket retrofit installations.
- Marine:SOLAS-compliant visible signaling for vessel navigation and man-overboard alerting operates in salt-spray environments demanding IP67+ enclosure ratings.
- Industrial:Equipment status indication and process alarm annunciation in high-noise manufacturing environments where audible signals prove ineffective.
Emergency Response concentrates specification authority through centralized safety engineering functions. Construction is climbing the fastest as rental fleet standardization expands addressable volume.
Mounting Type:
Fixed installations capture recurring revenue through building automation integration, while magnetic configurations serve temporary deployment economics in construction and logistics.
- Fixed:Permanent bracket mounting with conduit entry for hardwired 24VDC or AC control integration in manufacturing plants and distribution centers.
- Magnetic:High-strength rare-earth magnet bases enable rapid repositioning on rental fleet equipment and temporary work zones without drilling or wiring modification.
- Portable:Self-contained battery-powered units with integrated monitoring for standalone deployment in remote or confined space operations.
- Vehicle-Mounted:Vibration-resistant enclosures for OEM integration on autonomous haulage trucks and mobile industrial equipment under EU Machinery Directive mandates.
Fixed mounting holds installed capacity in permanent industrial infrastructure. Magnetic is gaining share fastest through rental fleet standardization and temporary deployment economics.
Power Source:
DC low-voltage architectures align with industrial control system conventions, while battery-powered configurations expand addressable applications beyond wired infrastructure constraints.
- Battery-Powered:Lithium-ion cell integration with wireless control enables deployment in remote mining operations and logistics hubs where FCC unlicensed spectrum compliance creates certification barriers.
- AC:Mains-powered units for permanent installation in facilities with established electrical infrastructure and centralized emergency power backup.
- DC:12VDC and 24VDC compatibility with industrial control architectures and vehicle electrical systems dominates OEM specification.
- Solar:Photovoltaic panel integration with supercapacitor storage for off-grid applications in perimeter security and remote pipeline monitoring.
DC holds installed capacity across industrial and vehicle OEM specifications. Battery-Powered is expanding most quickly through wireless beacon deployment in logistics and mining automation corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German machinery OEM specification channels while Australian mining operators absorb premium markups for Zone 0 hydrogen-rated units. Regulatory divergence between OSHA workplace safety enforcement and EU Machinery Directive mandates fragments procurement authority across Atlantic supply chains.
United States
OSHA inspection intensification in warehousing and construction mobile equipment elevates factory-integrated strobe specifications over aftermarket retrofits. FCC electromagnetic emissions regulations constrain battery-powered wireless beacon deployments in logistics hubs. Distribution center buildouts in the Midwest and Southeast corridors consolidate vendor panels under single-source fire-alarm and safety beacon contracts.
Germany
Machinery OEM specification teams in Baden-Württemberg and Bavaria narrow approved vendor lists to three-to-five suppliers with documented NFPA, UL, and IEC compliance portfolios. EU Machinery Directive mandates lock factory-level integration of visible warning devices on mobile equipment. Industrial automation clusters around Stuttgart and Munich drive demand for programmable multi-color LED arrays with SCADA network compatibility.
Australia
Surface and underground mining operators in Western Australia's Pilbara region mandate redundant visual alert systems for autonomous haulage corridors. TGA-equivalent state mining safety regulators enforce stricter visibility device standards for fleet expansion projects. Perth-based procurement teams for BHP and Rio Tinto operations specify IP66+ enclosures with 50,000-hour LED lifespans for harsh desert environments.
China
Semiconductor fabrication facilities in the Yangtze River Delta and Pearl River Delta specify RGB-programmable strobe units for equipment status hierarchies. GB standards for industrial safety equipment align with IEC 60079 explosion-protection frameworks for chemical processing infrastructure. Shenzhen and Shanghai automation integrators compress maintenance cycles through centralized color-scheme management platforms.
Japan
METI-supported manufacturing safety initiatives accelerate LED strobe adoption in automotive and electronics assembly plants. JIS standards for industrial signaling equipment create certification barriers for imported competitors. Osaka-based R&D facilities specialize in multi-color programmable strobes for semiconductor fabs, anchoring domestic supply chain control.
Strobe Beacon Market Competitive Landscape
Concentration sits with vertically integrated manufacturers possessing captive semiconductor sourcing and dedicated explosion-protection certification capabilities. The vendor base stratifies across three tiers: multinational industrial conglomerates with broad safety portfolios, mid-cap specialists with regional specification authority, and component assemblers serving price-sensitive retrofit channels. Dominant competitive moves include backward integration into LED driver IC supply and strategic partnerships with machinery OEMs for factory-level specification capture.
Among North American industrial safety providers, Federal Signal exemplifies the conglomerate archetype with diversified warning systems portfolios. PATLITE Corporation occupies a specialist position representing Japanese precision manufacturing in programmable visual signaling. WERMA Signaltechnik GmbH + Co. KG anchors the German Mittelstand tier, reflecting Baden-Württemberg's machinery supply chain density.
| Leading Market Players |
|---|
| Federal Signal |
| Banner Engineering |
| SIRENA S.p.A. |
| Auer Signal |
| PATLITE Corporation |
| WERMA Signaltechnik GmbH + Co. KG |
| E2S Warning Signals |
| CAPTRON Electronic |
| Tomar Electronics |
| Others |
Pricing and Supply Chain Analysis
Captive LED driver production at scale anchors margin resilience for manufacturers with in-house semiconductor sourcing, compressing price floors for outsourced assemblers while elevating premiums for explosion-certified configurations. Factory-level specification capture under EU Machinery Directive mandates locks pricing power with vertically integrated suppliers, whereas retrofit channels face commoditization from unbranded imports.
Pricing Analysis
Configured-to-order pricing for Zone 0 hydrogen-rated units commands substantial premiums over standard LED configurations due to IECEx/ATEX certification timelines and specialized glass envelope sourcing. Three-tier pricing structure across premium explosion-certified, standard industrial-grade, and economy retrofit levels segments buyer archetypes, with mining fleet operators in Western Australia showing lowest price sensitivity for redundant autonomous haulage systems. Pricing pressure stems from semiconductor input volatility constraining production planning for manufacturers without captive foundry arrangements. Rental fleet procurement in construction exhibits highest price sensitivity, driving magnetic-mount portable standardization.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for LED driver ICs and silicon carbide components sourced from Taiwan and South Korea. Manufacturing concentration centers on China for PCB assembly, Japan for specialty glass electrodes, and Germany for precision optical enclosures, with xenon lamp glass envelope sourcing remaining tethered to limited European and Japanese component suppliers. Single-source vulnerability in specialty gas-discharge tube electrodes creates qualification bottlenecks for hydrogen economy infrastructure deployments. Distribution runs through machinery OEM specification teams in Baden-Württemberg and direct procurement channels for Australian mining operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from networked building automation platforms integrating visual alerting into unified safety systems, requiring defensive repositioning around predictive maintenance interfaces.
For Market Incumbents: Shield specification relationships by embedding diagnostic intelligence into programmable multi-color arrays, countering displacement from SCADA-integrated competitors. Deepen backward integration into silicon carbide driver supply to offset semiconductor volatility, while accelerating IEC 60079 Zone 0 certification investment ahead of hydrogen infrastructure expansion.
For New Entrants and Emerging Players: Aftermarket service gaps in legacy 24VDC hardwired installations present white-space opportunity for wireless retrofit modules with minimal infrastructure modification. Target temporary deployment economics in construction rental fleets through battery-powered magnetic units with integrated monitoring, leveraging FCC compliance as a barrier against unlicensed spectrum competitors.
For Investors and Strategic Acquirers: Specialist manufacturers with captive explosion-protection certification capabilities and dedicated R&D facilities represent the most defensible acquisition profile for long-term positioning. Monitor IEC 60079 gas group recertification timelines as the critical inflection signal for replacement demand acceleration across chemical processing and energy storage installations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Driver IC Supply | Captive semiconductor sourcing insulates margin resilience against foundry allocation volatility. |
| Zone 0 Hydrogen Certification Investment | IEC 60079 recertification ahead of hydrogen economy infrastructure captures replacement cycles. |
| SCADA Network Compatibility Development | Programmable multi-color integration with facility automation platforms elevates specification authority. |
| Machinery OEM Specification Partnership | EU Machinery Directive factory-level integration locks out retrofit channel competitors. |
| Predictive Maintenance Interface Development | Embedded diagnostic intelligence shifts value proposition beyond basic alerting functionality. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across safety engineering functions with secondary validation against SEC filings, customs trade data, IEC certification registries, and machinery OEM specification documentation. Bottom-up unit economics triangulated against top-down sector spending patterns to establish market sizing boundaries.
Sensitivity analysis tested forecast outputs across variable assumptions for semiconductor input pricing, hydrogen infrastructure deployment pace, and regulatory enforcement intensity over the projection horizon. Segmentation modeling captured light source technology, mounting configuration, application vertical, power source architecture, and regional regulatory cluster dimensions. CAGRs derived from installed base turnover rates, fleet expansion trajectories, and compliance-driven replacement cycles specific to mining automation and semiconductor fabrication end-uses.
Forecasts assume regulatory continuity in OSHA workplace safety enforcement, EU Machinery Directive implementation, and IEC 60079 explosion-protection frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Digital Camlock Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Protection Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Guards Market