
 APAC Safety Instrumented Systems Market | 2026-2036
APAC Safety Instrumented Systems Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Safety Instrumented Systems Market Outlook
South Korea's semiconductor fabrication cluster is tilting toward redundant safety architectures as process node shrinkage intensifies hazard severity. Yokogawa Electric Corporation anchors its regional position through deep calibration expertise in burner management systems. Honeywell International Inc. leverages its distributed control platform to compete across LNG regasification terminals. ABB Ltd dominates high-availability configurations for subsea production control.
APAC Safety Instrumented Systems comprise engineered control layers—sensors, logic solvers, and final control elements—configured to achieve specified Safety Integrity Levels per IEC 61511, typically SIL 2 or SIL 3 for hydrocarbon processing. These systems execute automatic protective responses when process deviations exceed safe thresholds, preventing catastrophic releases or equipment damage. Emergency Shutdown Systems occupy the largest installed base across mature refinery infrastructure, while Safety Instrumented Functions gain share as greenfield projects embed programmable safety logic from commissioning. Fire & Gas Systems command premium pricing in offshore platforms where detection speed directly determines evacuation viability.
China's SAMR enforces GB standard alignments with IEC 61508 that compel domestic integrators to recertify imported safety devices. Australia's TGA-equivalent functional safety regime for process industries, administered through state-level occupational safety authorities, creates dual compliance obligations for multinational operators. Japan's METI industrial safety directives mandate periodic proof testing intervals that sustain aftermarket service demand. Stakeholders must monitor how India's CEA grid code revisions for thermal power plants will expand Safety Instrumented Systems scope beyond traditional hydrocarbon boundaries.
Market Dynamics
China's SAMR enforcement of GB standard alignments with IEC 61508 is forcing wholesale recertification of imported safety devices, compressing supplier margins while elevating domestic integrators who can navigate dual compliance architectures faster than multinational competitors.
Growth Catalysts
- Refinery corridor expansion:India's western coast petrochemical complexes are embedding SIL 3 programmable logic from commissioning, bypassing the retrofit cycle that constrains mature markets.
- Semiconductor node shrinkage:South Korea's fabrication clusters are mandating redundant safety architectures as hazard severity intensifies below 7nm process thresholds.
- Offshore platform electrification:Australia's Browse Basin and Scarborough developments are specifying integrated Fire & Gas Systems with sub-100ms detection response times.
Market Restraints
- Specialized sensor supply concentration:High-integrity pressure transmitters for SIL 3 applications concentrate among German and Japanese component suppliers, exposing integrators to 16-24 week lead times.
- Proof testing labor intensity:Japan's METI-mandated periodic proof testing intervals sustain recurring service demand but constrain operator flexibility during turnaround windows.
- Legacy system interoperability friction:Brownfield installations running proprietary DCS protocols from the 1990s resist seamless integration with modern safety PLCs without expensive gateway architectures.
Strategic Opportunities
- CEA grid code expansion:India's Central Electricity Authority revisions for thermal power plants will extend Safety Instrumented Systems scope into generator protection and grid synchronization.
- Remote proof testing protocols:Cloud-connected diagnostic platforms enable predictive maintenance models that reduce offshore platform manning requirements in Malaysia's Sarawak fields.
- Subsea production control:High-availability safety configurations for subsea trees and manifolds represent underpenetrated territory as Vietnam and Indonesia advance deepwater frontier developments.
Industry Challenges
- Functional safety engineer scarcity:TÜV-certified SIL practitioners remain concentrated in Yokohama, Singapore, and Shanghai, creating recruitment bottlenecks for Jakarta and Bangkok project offices.
- Dual compliance documentation burden:Australia's state-level occupational safety authorities impose parallel certification requirements that extend project engineering schedules by 4-8 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Safety Instrumented Systems Market |
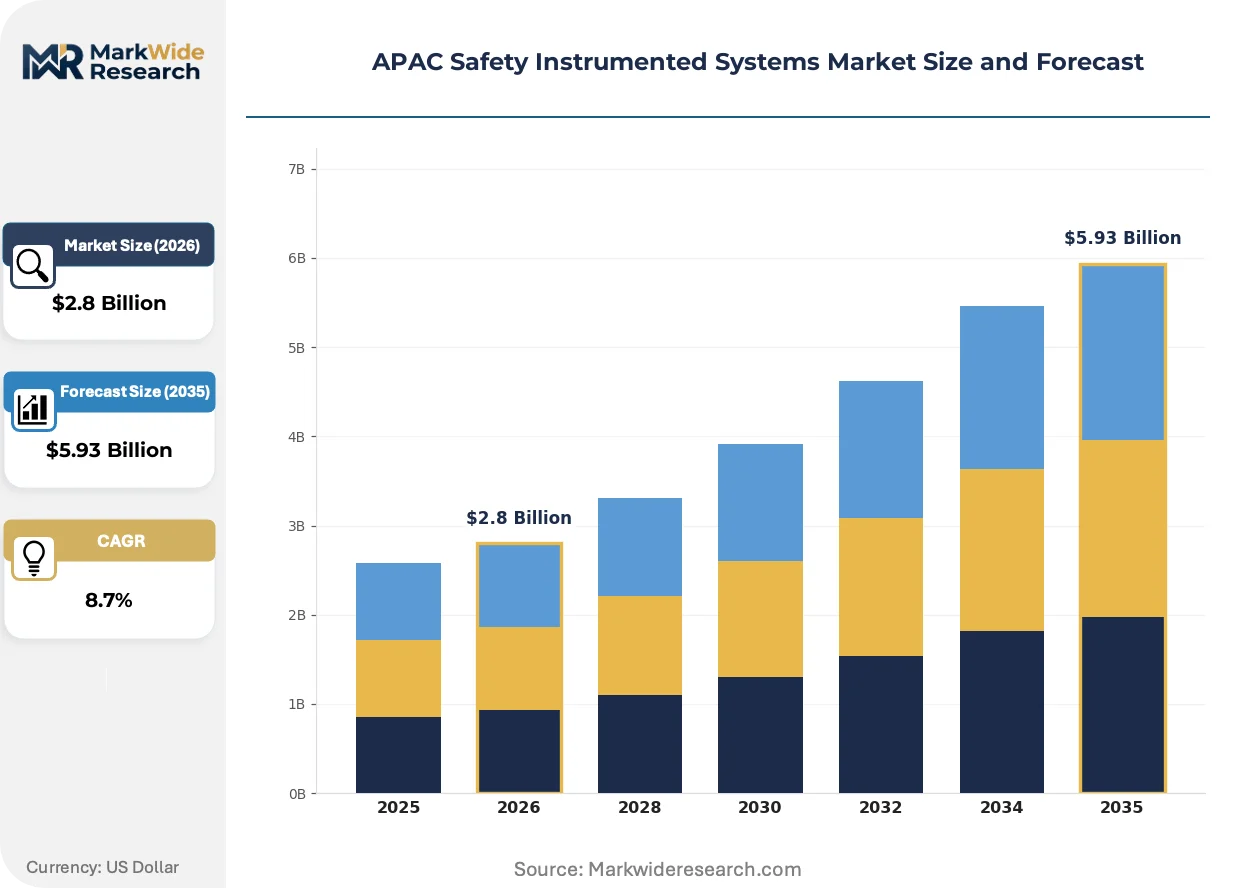
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emergency Shutdown Systems, Fire & Gas Systems, Safety Sensors, Control Systems End User: Oil & Gas, Chemical, Pharmaceutical, Power Generation Technology: Programmable Logic Controllers, Distributed Control Systems, Fieldbus Technology, Safety Instrumented Functions Installation: Onshore, Offshore, Industrial Facilities, Remote Locations |
| Companies Covered | Rockwell Automation Inc., Emerson Electric Company, Honeywell International Inc., Yokogawa Electric Corporation, ABB Ltd, Schneider Electric SE, Siemens AG, HIMA Paul Hildebrandt GmbH, SIS-TECH Solutions LP, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Safety Instrumented Systems Market Strategic Shifts
Safety system architectures are converging with process control networks, dissolving the traditional air-gapped separation between operational technology and safety instrumented functions while introducing new cybersecurity qualification requirements.
Integrated safety-PLC platforms are hybridizing formerly discrete Emergency Shutdown System and Fire & Gas System architectures into unified logic solver configurations. LNG regasification terminals in Singapore and Tianjin are adopting these consolidated platforms to reduce cabinet footprint and wiring complexity. This consolidation is hybridizing supplier competitive dynamics, privileging vendors with distributed control heritage over pure-play safety specialists.
China's GB/T 21109 implementation rules are tightening proof testing documentation requirements for imported safety devices. Domestic integrators must now submit SAMR-recognized third-party validation reports before commissioning, adding 6-10 weeks to project schedules. Petrochemical complexes in Zhejiang and Shandong provinces are responding by pre-qualifying safety device suppliers during FEED phases rather than post-tender.
Asset owner engineering teams are unbundling after-sales service contracts from initial system procurement, creating standalone multi-year calibration and proof testing agreements. This unbundling is compressing upfront equipment margins while expanding recurring revenue pools for service-capable vendors. The shift is most pronounced among Japanese chemical majors and Australian LNG operators with mature installed bases requiring sustained functional safety verification.
APAC Safety Instrumented Systems Market Segmentation
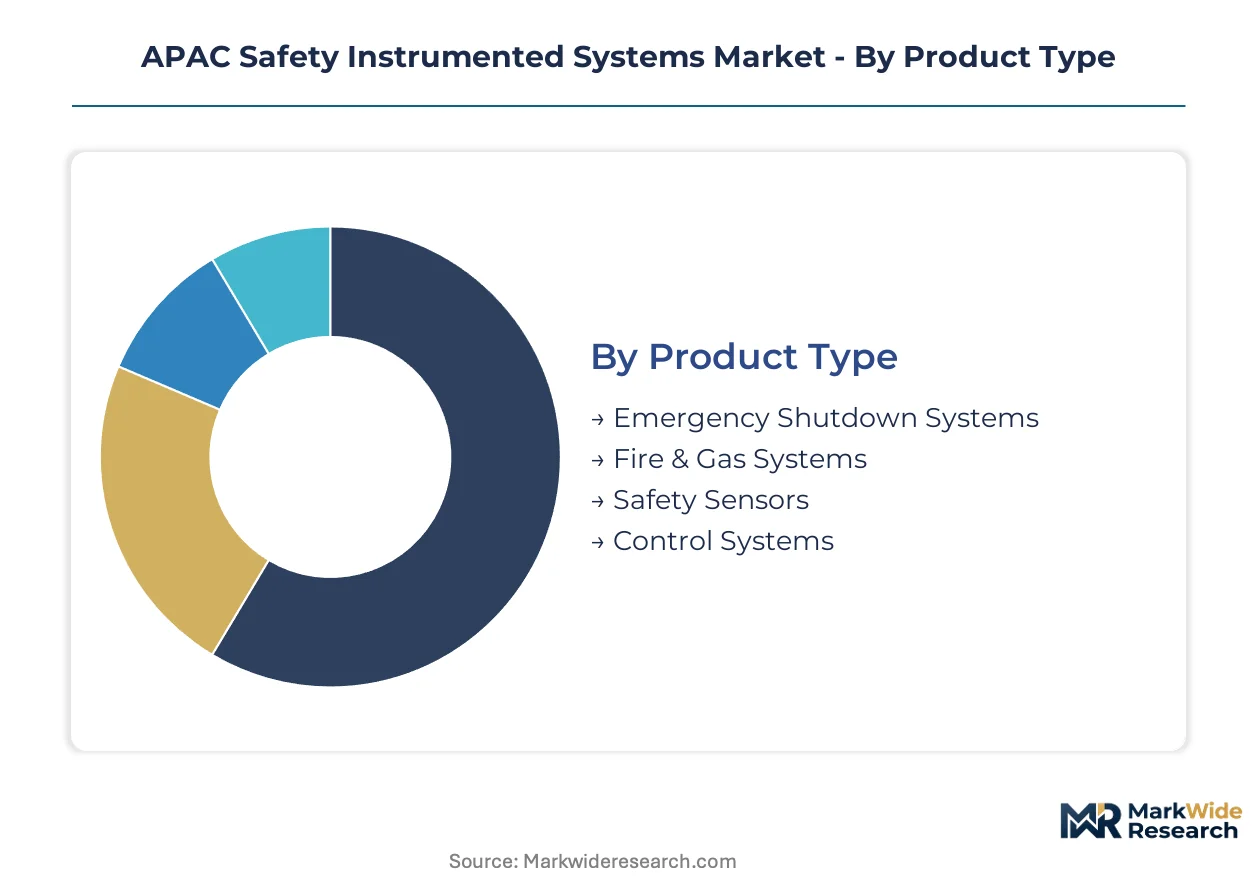
APAC Safety Instrumented Systems demand fragments across four structural axes. Product configurations range from mature hardwired architectures to emerging programmable platforms. End-user concentration in hydrocarbon processing contrasts with nascent pharmaceutical adoption. Technology choices reflect the tension between legacy DCS integration and standalone SIL-certified logic.
Product Type:
Mature hardwired systems dominate installed bases across established refinery corridors, while programmable architectures gain ground in greenfield semiconductor and LNG facilities.
- Emergency Shutdown Systems:Hardwired relay-logic configurations remain prevalent across brownfield refinery infrastructure in Japan and Australia. India's western coast petrochemical complexes specify SIL 3 programmable ESD architectures from commissioning, bypassing the retrofit constraints that limit mature markets.
- Fire & Gas Systems:Integrated detection and suppression platforms command premium positioning in Australia's Browse Basin offshore developments. Sub-100ms response specifications for toxic gas detection drive sensor redundancy requirements that elevate system complexity and certification burden.
- Safety Sensors:Pressure transmitters and temperature switches form the detection layer for SIL-rated loops.
- Control Systems:Safety PLCs and dedicated logic solvers execute final element commands per IEC 61511.
Emergency Shutdown Systems handle the majority of throughput; Fire & Gas Systems is the fastest mover on share.
End User:
Cost tier stratification separates capital-intensive hydrocarbon processors from regulated pharmaceutical manufacturers with distinct compliance architectures.
- Oil & Gas:Upstream exploration, midstream transportation, and downstream refining operations constitute the foundational demand pool. Southeast Asian petrochemical complexes in Singapore and Thailand embed layered protection architectures that cascade from process control through safety instrumented functions to mechanical relief.
- Chemical:Chlor-alkali and specialty chemical producers in China's Zhejiang province face SAMR-mandated GB/T 21109 compliance that extends proof testing documentation requirements.
- Pharmaceutical:Active pharmaceutical ingredient manufacturing in India and South Korea adopts safety instrumented systems for reactor temperature emergency control.
- Power Generation:India's Central Electricity Authority grid code revisions are expanding safety system scope into generator protection and synchronization logic.
Oil & Gas commands the dominant share of procurement volume; Power Generation is expanding most quickly as regulatory scope broadens.
Technology:
Application criticality determines architecture selection, with integrated control-safety platforms displacing standalone configurations in high-availability environments.
- Programmable Logic Controllers:SIL-certified safety PLCs from major automation vendors execute discrete logic functions with deterministic response times. South Korea's semiconductor fabrication clusters specify redundant PLC architectures as process node shrinkage below 7nm intensifies thermal runaway hazards.
- Distributed Control Systems:Integrated safety-process control platforms reduce cabinet footprint and wiring complexity at LNG regasification terminals in Singapore and Tianjin.
- Fieldbus Technology:Digital communication protocols enable remote diagnostics and reduce marshalling hardware.
- Safety Instrumented Functions:Discrete safety loops configured to specific SIL targets per IEC 61511.
Programmable Logic Controllers anchor the technology mix; Distributed Control Systems are climbing the fastest as consolidation preferences intensify.
Installation:
Geography and accessibility shape specification requirements, with offshore environments imposing the most stringent availability and response time demands.
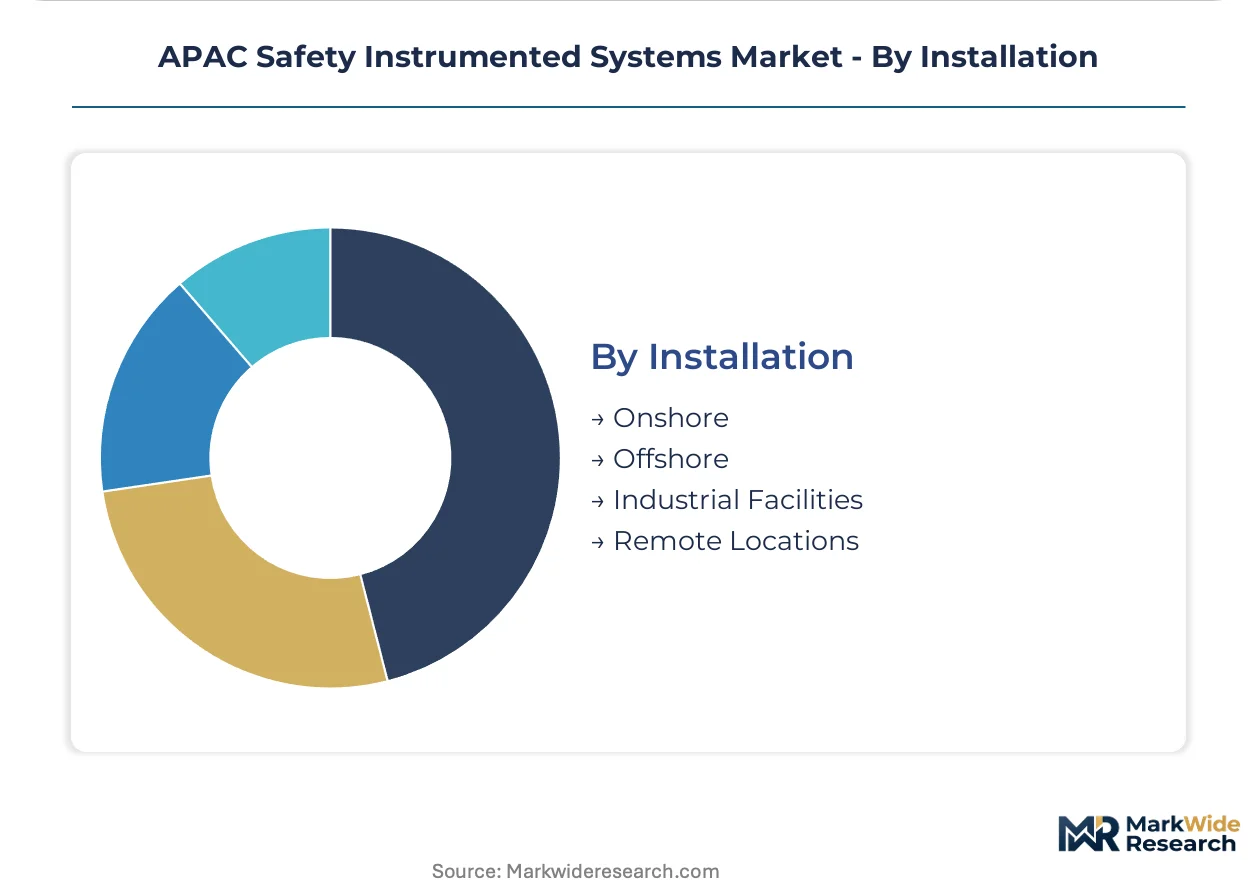
- Onshore:Refinery and petrochemical complex installations benefit from established maintenance infrastructure and shorter proof testing mobilization times. China's Shandong province refineries are pre-qualifying safety device suppliers during FEED phases to accommodate SAMR documentation timelines.
- Offshore:Platform and subsea production control systems require high-availability configurations with automated diagnostic capabilities. Malaysia's Sarawak fields are piloting cloud-connected remote proof testing protocols to reduce manning requirements.
- Industrial Facilities:Integrated manufacturing sites with combined process and utility operations.
- Remote Locations:Pipeline compressor stations and isolated processing units with limited technical support access.
Onshore installations comprise the bulk of deployed assets; Offshore configurations are gaining share fastest as deepwater frontier developments advance in Vietnam and Indonesia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Malacca Strait refining corridor anchors Southeast Asian demand for layered protection architectures. Subsea pipeline networks linking Australian offshore gas fields to Asian markets sustain high-availability safety system procurement.
China
Zhejiang and Shandong province petrochemical complexes are pre-qualifying safety device suppliers during FEED phases. SAMR enforcement of GB/T 21109 alignment with IEC 61508 compels domestic integrators to recertify imported devices. The Yangtze River Delta chemical corridor is absorbing extended documentation timelines through earlier supplier engagement.
India
Western coast refinery expansions in Gujarat and Maharashtra are embedding SIL 3 programmable logic from commissioning. CEA grid code revisions for thermal power plants are extending safety system scope into generator protection. The Jamnagar refining complex is specifying integrated safety architectures that bypass retrofit constraints.
Japan
Kansai region chemical producers face METI-mandated periodic proof testing intervals that sustain aftermarket service demand. Osaka Bay industrial clusters are unbundling after-sales contracts from initial procurement to expand recurring revenue pools. Chubu region automotive chemical suppliers are adopting redundant safety architectures for battery material processing.
South Korea
Seoul Capital Area semiconductor fabrication clusters are mandating redundant safety architectures as process nodes shrink below 7nm. Busan-Ulsan heavy industrial zones are specifying deterministic response times for thermal runaway protection. Daegu-Gyeongbuk region display material producers are layering safety instrumented functions over existing process control.
Australia
Browse Basin and Scarborough offshore developments are specifying integrated Fire & Gas Systems with sub-100ms detection response times. State-level occupational safety authorities impose dual compliance obligations that extend project engineering schedules. Western Australia LNG export terminals are piloting cloud-connected remote proof testing protocols to reduce platform manning.
APAC Safety Instrumented Systems Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with concentrated sensor supply. The supplier base organizes around three archetypes: distributed control heritage vendors, pure-play safety specialists, and domestic integrators with regulatory navigation capabilities. Consolidation pressures favor vendors with calibration service networks over equipment-only suppliers. Vertical integration into safety logic solver manufacturing and backward integration into high-integrity sensor production represent the dominant competitive vectors.
Among Japan-based automation vendors, Yokogawa Electric Corporation occupies a position exemplifying deep calibration expertise in burner management systems. Honeywell International Inc. and ABB Ltd represent the distributed control heritage archetype, with the former leveraging platform integration across LNG regasification terminals and the latter anchoring high-availability configurations for subsea production control. These three companies illustrate how service capability and sector specialization determine competitive positioning more than hardware specifications alone.
| Leading Market Players |
|---|
| Rockwell Automation Inc. |
| Emerson Electric Company |
| Honeywell International Inc. |
| Yokogawa Electric Corporation |
| ABB Ltd |
| Schneider Electric SE |
| Siemens AG |
| HIMA Paul Hildebrandt GmbH |
| SIS-TECH Solutions LP |
| Others |
Value Chain & Pricing Dynamics
Yokohama's calibration service cluster concentrates aftermarket capability for SIL-certified proof testing, granting Japanese integrators pricing leverage over equipment-only suppliers in Southeast Asian tender processes. This geographic concentration of technical labor reshapes how safety system vendors structure bundled versus unbundled service contracts across the region.
Pricing Analysis
Volume-discount tiering separates turnkey ESD installations from component-only procurement, with after-sales service unbundling compressing upfront equipment margins while expanding recurring calibration revenue pools. Price differentiation hinges on SIL certification grade and geographic service coverage density, with remote offshore platforms commanding substantial premiums over onshore refinery corridors. Cost compression in standard programmable safety PLCs is intensifying as Chinese domestic integrators achieve GB/T 21109 compliance parity. National oil companies exhibit highest price sensitivity due to capital budget cyclicality, while semiconductor fabricators prioritize deterministic response specifications over procurement cost.
Supply Chain Analysis
Contract manufacturing for safety logic solvers concentrates among German and Japanese automation foundries with captive SIL certification facilities. Component supply draws from precision sensor specialists in Japan and Germany, safety PLC assembly in China and Singapore, and final system integration across Australia and South Korea. Single-source vulnerability pervades high-integrity pressure transmitter supply for SIL 3 loops. Distribution runs through certified system integrators with SAMR or METI regulatory navigation capabilities rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against integrated process-safety platform vendors eroding pure-play safety specialist territory. Cloud-connected diagnostic platforms threaten traditional proof testing service incumbents with predictive maintenance displacement.
For Market Incumbents: Entrench calibration service density in Yokohama, Singapore, and Shanghai clusters to defend against remote proof testing protocols. Deepen backward integration into high-integrity sensor production to reduce exposure to German and Japanese component supplier lead time volatility. Prioritize SAMR pre-qualification workflows during FEED phases to compress documentation timelines versus multinational competitors. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Indonesia deepwater frontier developments where high-availability subsea safety configurations remain underpenetrated. Target India's CEA grid code expansion corridor for thermal power generator protection as regulatory scope broadens beyond hydrocarbon boundaries. Lead with cloud-connected diagnostic platforms to capture remote proof testing contracts in Malaysia's Sarawak fields. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with distributed control heritage integrating safety-process control platforms over pure-play safety specialists facing consolidation pressure. Long-term viability rests on service network density and regulatory navigation capabilities rather than hardware differentiation alone. Monitor India's western coast refinery commissioning timelines and China's SAMR enforcement intensity as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of SIL 3 pressure transmitters reduces exposure to 16-24 week lead time volatility from German and Japanese component suppliers. |
| Cloud-Connected Diagnostic Platform Launch | Remote proof testing protocols reduce offshore platform manning requirements in Malaysia's Sarawak fields and Australia's Browse Basin. |
| SAMR Pre-Qualification Program | Early supplier engagement during FEED phases compresses GB/T 21109 documentation timelines that currently extend project schedules by 6-10 weeks. |
| CEA Grid Code Compliance Investment | Generator protection and synchronization logic expansion in India's thermal power plants opens non-hydrocarbon demand pools. |
| Subsea High-Availability Configuration Development | Vietnam and Indonesia deepwater frontier developments require safety architectures for trees and manifolds with limited incumbent penetration. |
Study Parameters
The analysis maps Emergency Shutdown Systems, Fire & Gas Systems, Safety Instrumented Functions, and Safety Sensors, each validated through functional safety engineers, petrochemical procurement directors, offshore platform engineering managers, and automation system integrators. Primary interview intelligence triangulates against SAMR regulatory filings, METI industrial safety directives, IEC 61508/61511 certification databases, and customs import records for safety device trade flows. Bottom-up project pipeline assessment across refinery, LNG, and semiconductor fabrication developments reconciles with top-down regional automation spending forecasts.
Assumptions hold China's GB standard enforcement trajectory, India's CEA grid code revision implementation pace, and Japan's METI proof testing interval mandates as fixed regulatory conditions across the modeling period. Segmentation dimensions include product architecture, end-use industry vertical, technology platform type, and installation environment. CAGRs derive from installed base expansion rates plus replacement cycle timing for brownfield safety system upgrades. Industry-specific inputs incorporate SIL certification tier penetration by application criticality and offshore versus onshore project mix shifts.
Sensitivities concentrate around SAMR documentation timeline compression, semiconductor node shrinkage acceleration below 5nm, and subsea project sanctioning delays in Vietnam and Indonesia. Forecasts reflect these assumptions without incorporating unannounced regulatory overhauls or breakthrough non-programmable safety architectures. Quarterly review of refinery FEED phase safety device pre-qualification rates and cloud-connected diagnostic platform adoption in Malaysia's Sarawak fields is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Earmuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Fluid Market