
 Radar Speed Gun Market | 2026-2036
Radar Speed Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Radar Speed Gun Market Insights
Doppler-to-LIDAR sensor convergence is fragmenting the traditional hardware stack into modular, software-defined platforms. Stalker Radar leverages in-house semiconductor fabrication to sustain margin control across its in-vehicle lineup. Uniden America Corporation competes through consumer-channel density, while Decatur Electronics anchors municipal procurement with permanent-installation expertise calibrated to FCC emission standards.
A radar speed gun emits radio or laser pulses to calculate object velocity via frequency shift or time-of-flight measurement, with Doppler variants operating in X, K, or Ka bands and LIDAR units achieving sub-kilometer precision at millisecond refresh rates. Handheld units dominate traffic enforcement procurement volumes, though integrated fixed-station deployments command superior lifetime value through automated citation workflows. Doppler technology retains cost advantages in emerging markets, while GPS-augmented systems are displacing legacy RF architectures in precision sports timing.
FCC Part 90 governs radio emission parameters for US law enforcement radar, while EU CE marking under the Radio Equipment Directive mandates interoperability testing for cross-border traffic corridors. The US National Highway Traffic Safety Administration coordinates with state departments of transportation to certify speed measurement accuracy for judicial admissibility. Stakeholders must monitor whether emerging V2X communication standards will subsede standalone speed detection hardware or create hybrid sensor fusion requirements.
Market Dynamics
Sensor fusion architectures are compressing the traditional radar speed gun value chain by collapsing discrete RF, laser, and positioning modules into unified system-on-chip platforms. This consolidation is redistributing margin pools from discrete component suppliers toward firmware-integrated OEMs.
Growth Catalysts
- FCC Part 90 emission standards:US law enforcement procurement mandates are accelerating replacement cycles for legacy X-band units that fail to meet updated interference protocols. Municipal agencies face judicial admissibility risks with non-compliant hardware.
- Precision sports timing:Track and field federations in Germany and Japan are specifying GPS-augmented LIDAR for sub-millisecond finish-line accuracy, creating certified equipment refresh demand independent of traffic enforcement cycles.
- Industrial calibration workflows:Manufacturing quality control departments in automotive and aerospace sectors are adopting handheld Doppler units for non-contact velocity verification of conveyor systems and rotating machinery.
Market Restraints
- Gallium arsenide substrate costs:RF front-end fabrication depends on specialized semiconductor materials subject to supply concentration in East Asian foundries, creating input cost volatility for Ka-band Doppler units.
- Judicial calibration requirements:US state courts mandate NHTSA-traceable certification intervals that impose recurring compliance burdens on agency fleets, extending replacement timelines beyond technical obsolescence.
- Smartphone speed detection apps:Consumer-grade acoustic and camera-based velocity estimation tools are capturing price-sensitive recreational segments, compressing entry-level hardware margins.
Strategic Opportunities
- V2X infrastructure integration:Connected vehicle deployment in South Korea and the United States is creating demand for roadside speed verification nodes that feed into cooperative intelligent transport systems rather than issuing citations.
- EU AI Act compliance services:Automated speed enforcement systems with machine learning-based target classification face new algorithmic transparency requirements, opening consulting and retrofit markets for compliance engineering.
- Drone-mounted LIDAR:Aerial traffic monitoring units are penetrating highway patrol applications where ground-based positioning is hazardous or impractical, particularly across mountainous corridors in Austria and Switzerland.
Industry Challenges
- Firmware security certification:Connected speed guns require cyber resilience validation against GPS spoofing and data manipulation attacks, extending product development timelines by 8-14 months for agencies requiring FedRAMP-aligned assurance.
- Cross-platform integration:Municipal procurement increasingly demands API compatibility with existing citation management and evidence storage systems, forcing hardware vendors to maintain fragmented software development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radar Speed Gun Market |
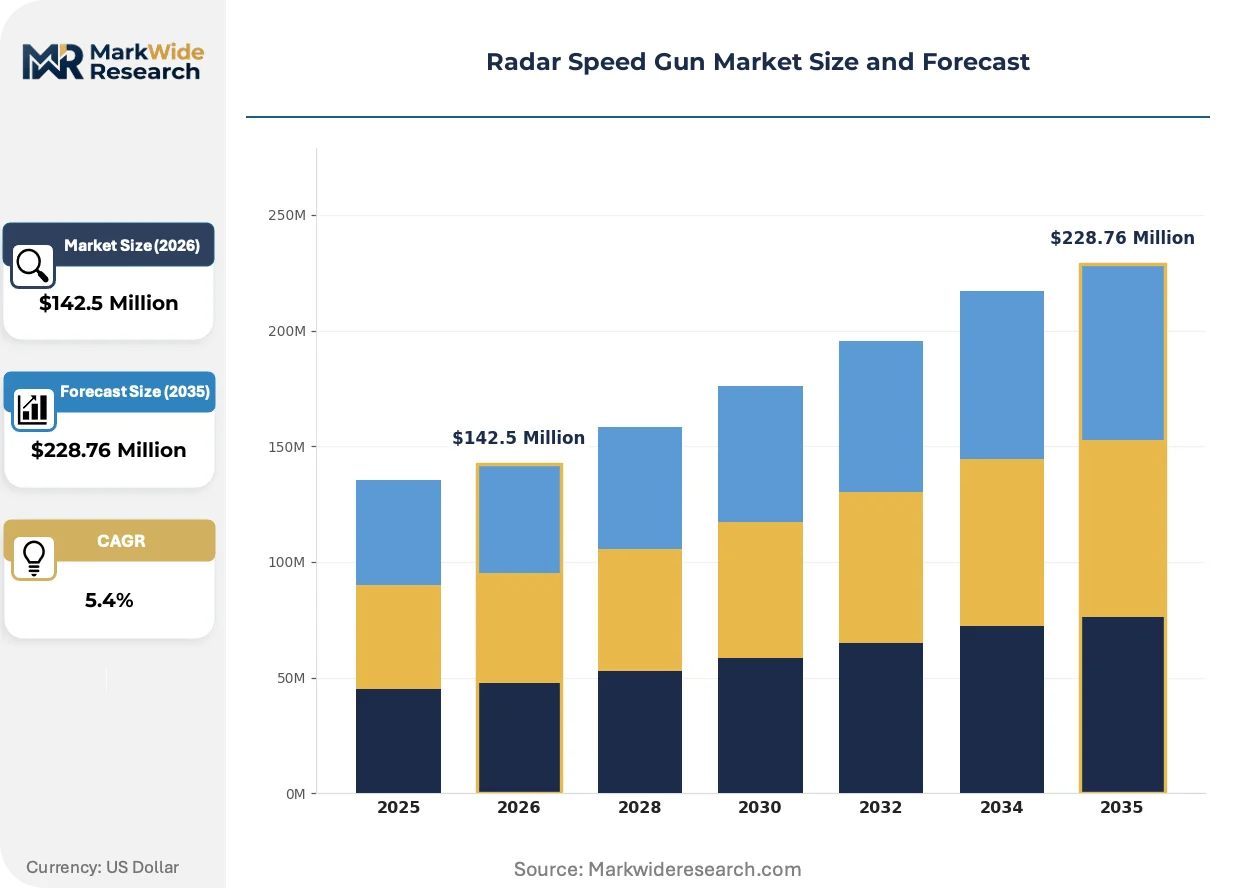
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $228.76 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, In-Vehicle, Tripod Mounted, Fixed Station Technology: Laser, Doppler, RF, GPS End User: Law Enforcement, Sports, Industrial, Traffic Management Installation: Permanent, Temporary, Portable, Integrated |
| Companies Covered | Pocket Radar, Escort, Stalker Radar, Sports Radar, Valentine Research, Uniden America Corporation, Radenso, Bushnell, Decatur Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radar Speed Gun Market Trends and Innovations
Computational photonics and edge AI are converging to redefine speed detection hardware as software-defined sensor platforms rather than fixed-function RF instruments. This transformation is compressing product lifecycles and redrawing competitive boundaries.
Solid-state beam-steering LIDAR arrays are rendering obsolete mechanical scanning mechanisms in precision enforcement applications. German traffic authorities are specifying MEMS-based units for multi-lane monitoring, eliminating moving parts that degrade calibration stability. The structural consequence is collapsing maintenance revenue streams that historically sustained municipal service contracts.
The EU Radio Equipment Directive's 2024 cybersecurity amendments are mandating firmware signing and secure boot protocols for all CE-marked speed measurement devices. Manufacturers must now maintain hardware security module integration through production, raising barriers for low-volume assemblers. Handheld unit suppliers serving cross-border traffic corridors face the steepest compliance cost escalation.
Subscription-based device-as-a-service models are displacing capital purchase frameworks among North American sheriff departments with constrained equipment budgets. Vendors retain ownership and calibration responsibility while agencies pay per-citation or per-device-month fees. This shift is most pronounced in Texas and Florida counties with volatile tax revenue streams.
Radar Speed Gun Market Segmentation
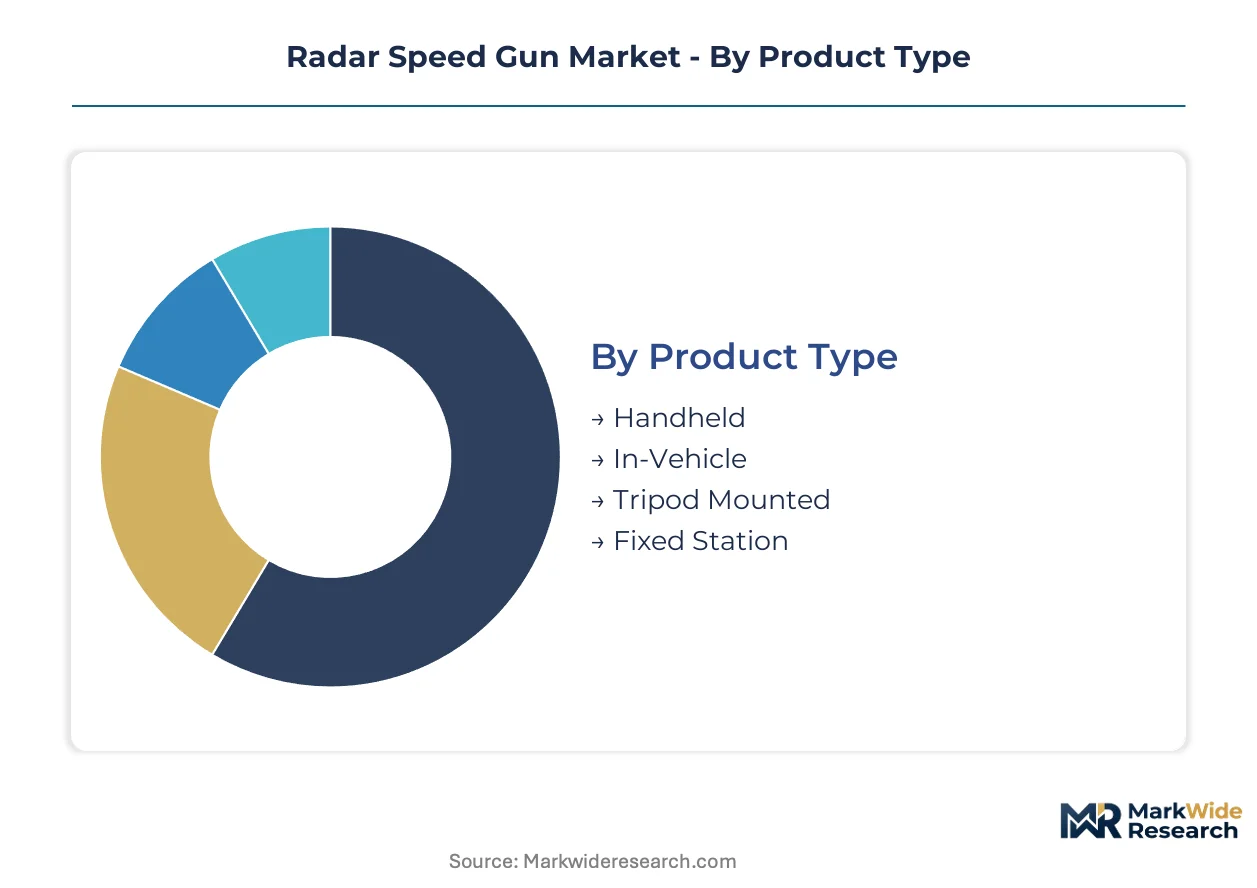
Radar speed gun procurement fragments across four distinct dimensions, each governing margin structure and replacement cadence. Product type determines capital intensity and calibration burden, while technology choice shapes regulatory compliance pathways and evidentiary admissibility.
Product Type:
Mature form factors dominate municipal procurement cycles, though emerging configurations are capturing specialized enforcement niches.
- Handheld:Battery-powered Doppler or LIDAR units with pistol-grip ergonomics and integrated displays for immediate velocity readout. Traffic patrol divisions in the United States and Germany specify these for roadside deployment where vehicle positioning flexibility outweighs stationary accuracy requirements.
- In-Vehicle:Dashboard-integrated systems with through-windshield LIDAR targeting and heads-up display projection. Highway patrol agencies across Texas and Florida favor these for rolling enforcement scenarios where officer safety demands minimal roadside exposure.
- Tripod Mounted:Stabilized platforms for temporary speed zone monitoring with extended battery packs. Construction zone contractors deploy these for short-duration traffic calming where permanent infrastructure is uneconomical.
- Fixed Station:Pole-mounted installations with automated license plate recognition and citation generation. German autobahn authorities and Japanese expressway operators specify these for high-volume enforcement corridors.
Handheld units retain volume leadership; fixed station deployments hold the steepest expansion curve.
Technology:
Cost tiers separate legacy RF architectures from precision photonic systems, with hybrid configurations emerging at the premium boundary.
- Laser:Time-of-flight LIDAR emitters achieving sub-meter target resolution at ranges exceeding one kilometer. German KBA certification requirements and Japanese expressway standards specify these for multi-lane discrimination where Doppler beam spread creates evidentiary ambiguity.
- Doppler:Frequency-shift radar operating in X, K, or Ka bands with mature semiconductor supply chains. Emerging market traffic departments and industrial calibration workflows favor these for unit economics despite FCC Part 90 emission compliance burdens.
- RF:Dedicated radio frequency systems with directional antenna arrays for moving-mode enforcement. Rural sheriff departments in the United States deploy these where terrain masking reduces LIDAR effectiveness.
- GPS:Satellite-augmented positioning for mobile platform velocity reference and synchronization. Precision sports timing federations in Germany and Japan mandate these for finish-line coordination across distributed sensor networks.
Doppler retains installed base dominance; LIDAR configurations are climbing the fastest on replacement demand.
End User:
Customer type dictates procurement authority structure and specification complexity, from federal grant-funded fleets to discretionary club purchases.
- Law Enforcement:Municipal, county, and state agencies with judicial admissibility requirements and NHTSA-traceable calibration protocols. These buyers command premium pricing for evidentiary-grade documentation.
- Sports:Track and field federations, motorsport sanctioning bodies, and training facilities requiring sub-millisecond timing precision. German athletics associations specify certified LIDAR for championship events.
- Industrial:Manufacturing quality control departments and conveyor system operators using non-contact velocity verification. Aerospace component suppliers in Japan deploy handheld units for rotating machinery diagnostics.
- Traffic Management:Transportation departments and tollway authorities integrating speed data into intelligent transport systems. South Korean V2X pilot programs source these for cooperative infrastructure nodes.
Law enforcement commands revenue concentration; traffic management applications are expanding most quickly on connected vehicle deployment.
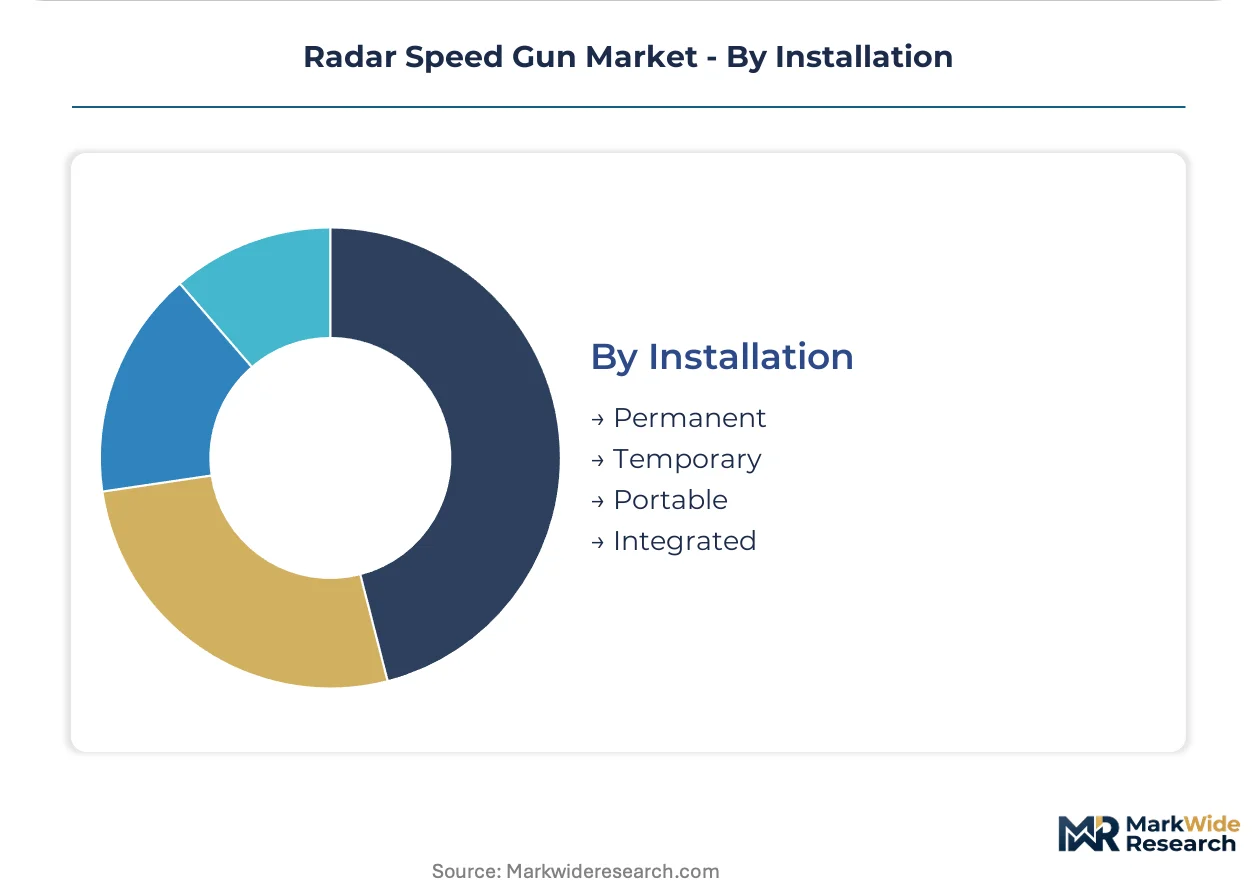
Installation:
Deployment permanence shapes total cost of ownership calculations and vendor service contract structures.
- Permanent:Hardwired installations with utility grid connection and fiber backhaul for real-time data transmission. German autobahn segments and Japanese expressway tunnels specify these for continuous monitoring.
- Temporary:Battery or solar-powered units for construction zones and special event traffic management. Rental service providers in the United States maintain fleets for seasonal demand spikes.
- Portable:Rapid-deployment cases with self-leveling mounts for incident response and emergency speed limit reductions. State patrol agencies favor these for wildfire evacuation route management.
- Integrated:Sensor fusion platforms combining speed detection with V2X communication, weather monitoring, or air quality sensing. South Korean smart highway pilots specify these for multi-function roadside units.
Portable installations retain procurement volume leadership; integrated systems are gaining share fastest on infrastructure modernization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Law enforcement agencies and precision sports federations concentrate procurement across five national markets with distinct regulatory pathways and infrastructure investment cycles. Each geography presents unique specification requirements and certification protocols.
United States
Municipal police departments and state highway patrol agencies drive replacement demand for FCC Part 90-compliant Doppler and LIDAR units. The National Highway Traffic Safety Administration coordinates calibration certification for judicial admissibility. Texas and Florida counties lead adoption of subscription-based device-as-a-service procurement models.
Germany
The Kraftfahrt-Bundesamt enforces stringent multi-lane discrimination standards that specify MEMS-based LIDAR for autobahn enforcement corridors. German athletics associations mandate GPS-augmented systems for championship track and field timing. Bavarian traffic authorities are piloting drone-mounted LIDAR for mountainous highway monitoring.
Japan
Expressway operators and industrial calibration laboratories anchor demand for sub-millisecond precision systems. METI standards govern RF emission parameters for traffic enforcement hardware. The Nagoya-Osaka industrial corridor deploys handheld Doppler units for aerospace component velocity verification.
South Korea
Smart highway infrastructure programs are integrating speed detection nodes into cooperative intelligent transport systems. National V2X pilot deployments specify roadside verification sensors rather than standalone citation devices. Seoul Capital Area transportation authorities lead procurement for multi-function integrated installations.
United Kingdom
Police forces and traffic management contractors balance procurement between handheld units for flexible deployment and fixed-station systems for automated enforcement. CE marking under the Radio Equipment Directive mandates cybersecurity protocols including firmware signing. London and Southeast England concentrate demand for construction zone temporary monitoring solutions.
Radar Speed Gun Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels with divergent margin structures. The vendor base separates into three tiers: semiconductor-integrated OEMs sustaining margin control through captive fabrication, consumer-channel distributors competing on volume density, and municipal specialists anchoring permanent-installation expertise. Consolidation pressure is intensifying as firmware-integrated platforms displace discrete component suppliers. Competitive moves center on sensor fusion architecture development and API compatibility investments for citation management system integration.
Among North American specialists, Stalker Radar and Decatur Electronics occupy positions at opposite ends of the procurement spectrum. Stalker Radar exemplifies the vertically integrated archetype through in-house semiconductor fabrication capabilities. Decatur Electronics anchors the municipal permanent-installation segment with FCC emission standard calibration expertise. Uniden America Corporation represents the consumer-channel density model, competing through retail distribution reach rather than direct agency contracting.
| Leading Market Players |
|---|
| Pocket Radar |
| Escort |
| Stalker Radar |
| Sports Radar |
| Valentine Research |
| Uniden America Corporation |
| Radenso |
| Bushnell |
| Decatur Electronics |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Ka-band semiconductor foundries across Taiwan and South Korea is compressing component pricing while forcing suppliers toward long-term municipal contracting to secure volume commitments. This utilization dynamic rewards vendors with captive fabrication like Stalker Radar, while squeezing margin for assembly-dependent competitors serving price-sensitive consumer channels.
Pricing Analysis
Cost-plus contracts with gallium arsenide wafer price indexation dominate procurement between RF front-end suppliers and Doppler unit assemblers. Three-tier pricing structure across evidentiary-grade, commercial-calibration, and recreational tiers separates law enforcement agencies willing to pay certification premiums from industrial buyers prioritizing unit economics over NHTSA traceability. Pricing pressure stems from smartphone speed detection apps capturing recreational segments, eroding entry-level hardware margins. Municipal fleets exhibit lowest price sensitivity due to judicial admissibility requirements, while construction zone contractors and sports clubs demonstrate highest elasticity.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for RF semiconductor sourcing. Gallium arsenide substrate fabrication concentrates in Taiwan, South Korea, and Japan, while MEMS-based LIDAR arrays source from German and Austrian precision optics clusters. Raw material dependencies span specialized semiconductor substrates, rare-earth laser emitters, and GPS receiver modules. Single-source vulnerability in East Asian foundries threatens Ka-band Doppler production continuity. Distribution runs through direct municipal procurement channels for law enforcement, industrial distributors for calibration workflows, and retail networks for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent radar speed gun manufacturers face substitution defense imperatives as V2X infrastructure and smartphone-based detection erode standalone hardware utility. Smartphone speed apps and connected vehicle verification nodes threaten to commoditize recreational and traffic management applications.
For Market Incumbents: Pre-empt V2X displacement by embedding speed verification modules into cooperative intelligent transport system architectures. Secure firmware-integrated platform dominance through API compatibility investments with citation management systems. Defend municipal relationships by absorbing NHTSA calibration burden under subscription-based device-as-a-service contracts.
For New Entrants and Emerging Players: Build out drone-mounted LIDAR capabilities for mountainous highway patrol applications where ground positioning is hazardous. Target Austrian and Swiss corridor authorities with aerial monitoring solutions. Penetrate precision sports timing through GPS-augmented certification partnerships with German athletics federations.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across handheld Doppler assembly as semiconductor consolidation compresses component costs. Long-term viability favors firmware-integrated OEMs over discrete component suppliers. Acquisition targets should demonstrate municipal procurement anchoring or captive semiconductor fabrication. Watch for V2X deployment acceleration in South Korea and Texas as inflection signal for hybrid sensor fusion demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Development | Unifies RF, LIDAR, and GPS modules into software-defined architectures for municipal procurement. |
| Firmware Security Certification Investment | Addresses EU Radio Equipment Directive cybersecurity mandates and FedRAMP-aligned agency requirements. |
| Device-as-a-Service Model Expansion | Captures Texas and Florida county demand amid volatile tax revenue streams. |
| V2X Infrastructure Integration Partnership | Positions speed verification nodes within South Korean cooperative intelligent transport pilots. |
| Drone-Mounted LIDAR Capability Buildout | Penetrates Austrian and Swiss mountainous corridor monitoring where ground access is limited. |
Research Methodology
Operator-level perspectives from traffic patrol commanders, municipal procurement officers, precision sports timing officials, and industrial calibration supervisors anchored the qualitative base. Primary interviews combined with secondary validation against FCC Part 90 emission filings, NHTSA calibration certification databases, EU CE marking registries, and municipal equipment procurement records. Bottom-up unit economics across handheld, in-vehicle, and fixed-station configurations triangulated with top-down market sizing.
Scenario-bracketing framed volume projections across conservative, baseline, and aggressive V2X adoption pathways. Segmentation modeling spanned product type, technology architecture, end-user category, and installation permanence. CAGRs derived from replacement cycle analysis of legacy X-band units, precision sports equipment refresh demand, and infrastructure modernization budgets. Industry-specific inputs incorporated judicial admissibility certification intervals and gallium arsenide supply concentration risk.
The forecast holds incumbent behavior within observed patterns; aggressive moves by smartphone app developers or V2X infrastructure vendors would shift outcomes beyond projected ranges. Forecasts reflect assumptions regarding FCC emission standard continuity, EU cybersecurity amendment implementation timelines, and municipal budget allocation stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Biodegradable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Steel Smart Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market