
 Body Armor Accessories Market | 2026-2036
Body Armor Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Body Armor Accessories Market Outlook
Aftermarket plate carrier customization is reconfiguring margin pools away from standardized kit sales toward modular upgrade ecosystems. Safariland leverages its holster and pouch integration expertise to dominate law enforcement channel relationships. Point Blank Enterprises anchors military contract execution through vertically controlled domestic manufacturing. DuPont competes at the materials tier, sustaining Kevlar fiber supply advantages against emerging UHMWPE alternatives.
Body armor accessories comprise supplementary components—plate carriers, retention systems, ballistic inserts, and load-bearing attachments—engineered to enhance protection, mobility, and equipment accessibility for armed personnel. These items integrate with base armor platforms through MOLLE-compatible webbing, quick-release mechanisms, and NIJ-certified ballistic materials rated against specific threat levels. The accessory type dimension shows plates and pouches capturing the fastest expansion as operators prioritize scalable protection and ammunition carriage. Material selection reveals Kydex outpacing leather in holster fabrication due to moisture resistance and reproducible molding precision, while Kevlar retains premium positioning in soft armor covers despite weight penalties against newer composites.
The U.S. NIJ Standard-0101.06 and its forthcoming successor govern ballistic performance certification, directly determining product eligibility for federal procurement channels. European defense buyers reference ECHA REACH compliance for chemical constituent disclosure in textile treatments and polymer finishes. The EU AI Act and emerging autonomous threat-detection integrations signal future compliance layers for smart accessory platforms. Stakeholders must monitor standard revision timelines and cross-border certification reciprocity to preserve market access across NATO supply chains.
Market Dynamics
The aftermarket plate carrier ecosystem is pulling procurement decisions away from standardized military tenders toward modular, operator-configurable systems that prioritize mission-specific adaptability over bulk volume contracts.
Growth Catalysts
- NIJ Standard-0101.06 Revision:The forthcoming update to U.S. ballistic resistance protocols is forcing law enforcement agencies to refresh soft armor inventories, creating replacement demand for MOLLE-compatible carriers and certified inserts.
- Modular Load-Bearing Equipment:Military units across NATO-aligned forces are adopting scalable plate systems that allow rapid reconfiguration between direct action and sustainment roles without platform replacement.
- Kydex Holster Fabrication:Moisture-resistant, precision-molded retention systems are displacing leather in duty gear procurement channels due to reproducible fit and reduced maintenance cycles.
Market Restraints
- Aramid Fiber Supply Concentration:Kevlar production capacity remains concentrated among a limited set of domestic suppliers, exposing procurement timelines to raw material allocation constraints.
- REACH Chemical Disclosure:ECHA compliance requirements for textile treatments and polymer finishes add documentation burden and reformulation costs for European distribution.
- UHMWPE Weight Advantage:Ultra-high molecular weight polyethylene composites are substituting traditional aramids in soft armor applications, compressing margins for legacy material suppliers.
Strategic Opportunities
- EU AI Act Integration:Autonomous threat-detection modules embedded in smart plate carriers will require compliance certification, creating first-mover advantage for accessory platforms with embedded sensor architectures.
- Civilian Tactical Channel:Direct-to-consumer sales of NIJ-certified civilian armor are bypassing traditional law enforcement distributor networks, opening margin capture for digitally native brands.
- Quick-Release Mechanism Standardization:Cross-manufacturer compatibility protocols for emergency doffing systems present white space for component suppliers to capture platform-agnostic retrofit demand.
Industry Challenges
- Ballistic Certification Backlogs:NIJ testing facility capacity constraints are extending time-to-market for new insert designs, compressing product development windows against contract award deadlines.
- Multi-Material Integration Complexity:Combining ceramic, polyethylene, and aramid layers in hybrid plates requires specialized laminating expertise that outstrips available technical workforce supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Armor Accessories Market |
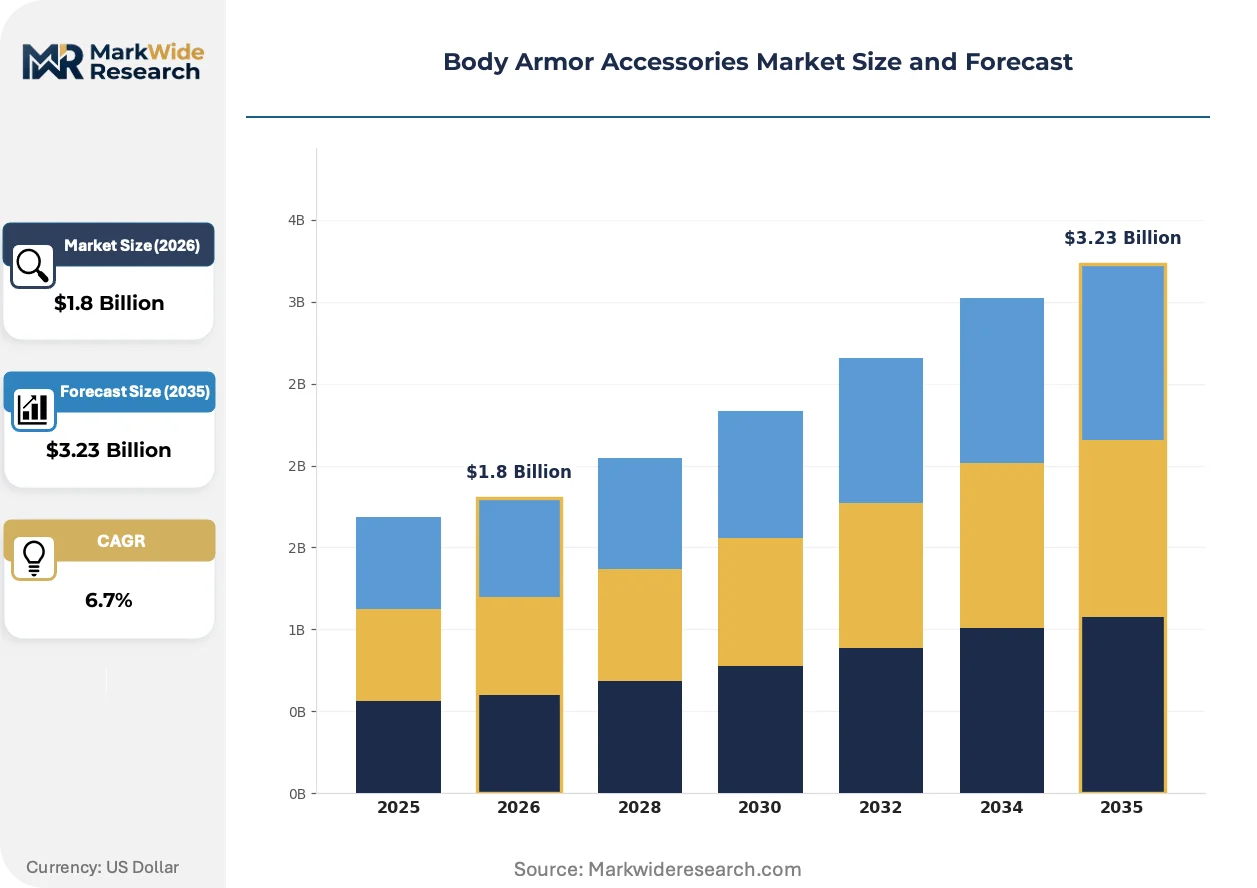
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accessory Type: Holsters, Plates, Pouches, Covers Material: Kydex, Nylon, Leather, Kevlar End User: Military, Law Enforcement, Security, Civilians Functionality: Storage, Protection, Customization, Comfort |
| Companies Covered | Point Blank Enterprises, Safariland, BAE Systems, DuPont, Honeywell International, 3M, Elmon, AR500 Armor, Armored Republic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Armor Accessories Market Strategic Shifts
Accessory platforms are converging with digital infrastructure, biometric monitoring, and autonomous threat response systems that transform passive protection into active operational tools.
UHMWPE composite inserts are collapsing the weight-performance tradeoff that previously favored ceramic plates in military procurement specifications. Special operations units are fielding all-polyethylene systems at accelerated procurement cycles. This collapse is compressing the addressable market for traditional ceramic strike face suppliers and reallocating R&D budgets toward fiber-matrix optimization.
ECHA REACH enforcement on per- and polyfluoroalkyl substances is forcing reformulation of water-repellent textile treatments used in plate carrier covers. European defense contractors are sourcing alternative C6 fluorocarbon chemistries or silicone-based finishes to maintain supply continuity. The regulation is most acute in German and French procurement channels, where chemical disclosure documentation now gates contract eligibility.
Law enforcement agencies are unbundling armor procurement from integrated duty gear packages, issuing separate solicitations for plates, carriers, and retention systems. This fragmentation is elevating specialized accessory vendors over full-system suppliers in municipal bidding processes. The pattern is most visible in U.S. state-level procurement, where sheriff departments and municipal police forces are consolidating purchasing authority while diversifying vendor pools.
Body Armor Accessories Market Segmentation
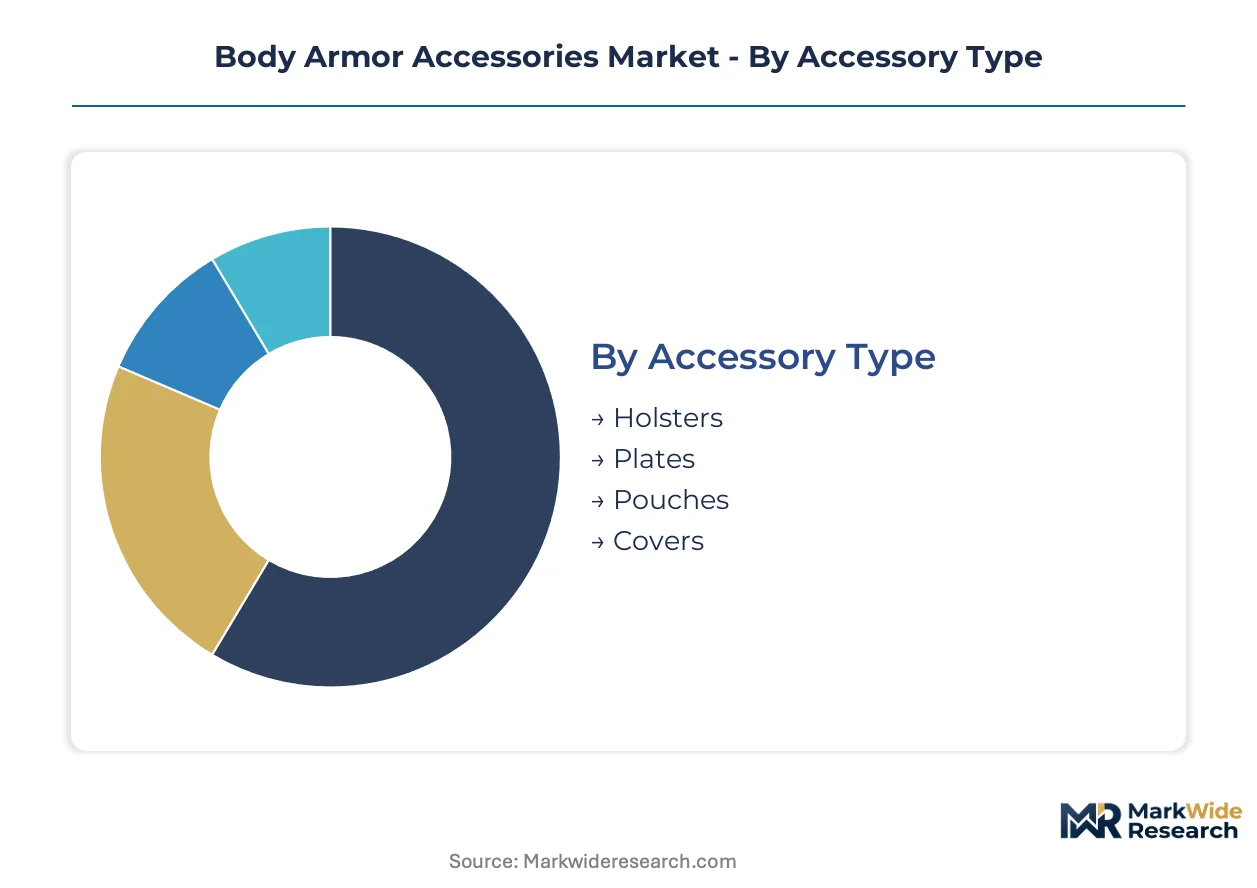
Accessory configuration determines procurement cadence across defense channels, with ballistic components requiring multi-year certification cycles while retention systems turn over faster through modular upgrade paths. Understanding segment-level replacement dynamics clarifies inventory planning for military quartermasters and law enforcement supply officers managing mixed-vendor ecosystems.
Accessory Type:
Plates and pouches compress replacement cycles through battlefield wear and ammunition capacity reconfiguration, while holsters and covers extend service life through material durability advances.
- Plates:Ceramic and polyethylene composite strike faces rated to NIJ Level III/IV specifications dominate military procurement. Special operations units in the United States are accelerating polyethylene adoption for weight reduction in multi-day patrol configurations.
- Pouches:MOLLE-compatible ammunition and medical carriage systems enable rapid mission reconfiguration without platform replacement. Law enforcement agencies in Texas and California are standardizing pouch modularity across patrol and tactical response units.
- Holsters:Level II and Level III retention systems integrate weapon-mounted light channels.
- Covers:Ballistic fabric enclosures protect plate edges from moisture degradation.
Plates anchor the volume base while pouches gain share at the steepest rate.
Material:
Cost stratification separates premium fiber composites from commodity polymers, with procurement budgets determining acceptable weight-performance tradeoffs across agency tiers.
- Kydex:Thermoplastic acrylic-polyvinyl chloride alloy enables precision-molded holster fabrication with reproducible retention geometry. Sheriff departments across Florida and Arizona are specifying Kydex for duty gear standardization programs.
- Kevlar:Para-aramid fiber maintains premium positioning in soft armor covers despite density penalties against UHMWPE alternatives. Military procurement channels continue specifying Kevlar for fragmentation protection in vest backing layers.
- Nylon:Ballistic-grade Cordura dominates pouch and carrier construction for abrasion resistance.
- Leather:Traditional holster material persists in ceremonial and plainclothes assignments.
Nylon constitutes the volume foundation while Kydex climbs the fastest through law enforcement channel conversion.
End User:
Customer type dictates specification stringency, with military contracts requiring full NIJ certification trails while civilian purchases operate under lighter compliance burdens.
- Military:Scalable plate carrier systems supporting direct action through sustainment mission profiles. Department of Defense modernization programs are driving multi-year procurement cycles for modular load-bearing equipment.
- Law Enforcement:Municipal and state agency purchases of duty-rated soft armor and retention systems. Police departments in Illinois and Ohio are unbundling carrier and plate acquisitions to diversify vendor pools.
- Security:Private sector guard services operating under variable threat assessments.
- Civilians:Direct-to-consumer NIJ-certified armor bypassing traditional distributor networks.
Law Enforcement anchors the volume base while Civilians expand most quickly through digital channel penetration.
Functionality:
Application priority shifts between protection-centric military specifications and mobility-focused law enforcement configurations, with comfort emerging as a competitive differentiator in extended-wear scenarios.
- Protection:Ballistic threat mitigation through hard and soft armor integration. Military procurement specifications prioritize protection hierarchy above all other functional attributes.
- Storage:Equipment accessibility and ammunition carriage capacity. Tactical response teams in Virginia and Washington are driving demand for expandable medical and breaching tool pouches.
- Customization:Operator-specific configuration of MOLLE attachment patterns.
- Comfort:Load distribution and thermal management in extended patrol contexts.
Protection anchors the volume base while Comfort gains share at the steepest rate through special operations feedback loops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Law enforcement agencies in the United States demonstrate the lowest price elasticity, absorbing premium costs for NIJ-certified modular systems, while civilian buyers in emerging markets exhibit acute sensitivity to unit economics in direct-to-consumer channels.
United States
Department of Defense modernization programs and municipal police unbundling of carrier-plate acquisitions drive procurement volume. The NIJ Standard-0101.06 revision mandates inventory refresh cycles across federal and state agencies. Manufacturing clusters in Florida and Arizona concentrate Kydex holster fabrication for sheriff department standardization programs.
Germany
Bundeswehr scalable plate carrier adoption and federal police equipment modernization sustain defense-channel demand. ECHA REACH enforcement on per- and polyfluoroalkyl substances forces reformulation of water-repellent textile treatments. Industrial concentration in Bavaria and North Rhine-Westphalia hosts specialized laminating operations for hybrid plate production.
United Kingdom
Ministry of Defence special operations units accelerate polyethylene plate procurement for weight-critical patrol configurations. UK Defence Standardization compliance requirements govern ballistic performance certification for NATO interoperability. Greater Manchester and West Midlands police forces drive municipal unbundling trends in duty gear acquisition.
France
Gendarmerie Nationale and Police Nationale modular equipment upgrades prioritize mission-reconfigurable load-bearing systems. ANSM chemical disclosure protocols align with ECHA REACH for textile treatment documentation. The Île-de-France region anchors domestic manufacturing for fragmentation protection vest backing layers.
Australia
Australian Defence Force special operations command drives lightweight polyethylene insert evaluation for regional deployment profiles. TGA alignment with ISO ballistic standards facilitates equipment interoperability with Five Eyes partners. Victoria and New South Wales state police services standardize MOLLE-compatible pouch modularity across tactical response units.
Body Armor Accessories Market Competitive Environment
Vertically integrated defense contractors and specialized accessory fabricators split the market along certification-depth versus agility vectors. Tier concentration remains moderate, with incumbent military suppliers defending long-cycle contract relationships against nimble law enforcement channel specialists. Two dominant archetypes emerge: domestic manufacturing anchors controlling military procurement execution, and modular integration specialists capturing municipal unbundling opportunities. Competitive moves center on backward integration into fiber-matrix production and rapid-response manufacturing for shortened law enforcement replacement cycles.
Within the domestic manufacturing anchor tier, Point Blank Enterprises exemplifies vertically controlled execution through captive supply chain management, while Safariland occupies the modular integration specialist position leveraging holster and pouch integration expertise. DuPont sits within the materials tier, sustaining para-aramid fiber supply positioning against emerging composite alternatives. These three entities represent the strategic archetype distribution without exhausting the competitive field.
| Leading Market Players |
|---|
| Point Blank Enterprises |
| Safariland |
| BAE Systems |
| DuPont |
| Honeywell International |
| 3M |
| Elmon |
| AR500 Armor |
| Armored Republic |
| Others |
Value Chain & Pricing Dynamics
The Port of Savannah corridor cost dynamics amplify price differentiation between domestic Kydex fabricators and import-dependent nylon weavers, concentrating margin capture among vertically integrated plate carriers while squeezing modular pouch specialists dependent on Asian textile inputs.
Pricing Analysis
Aftermarket plate carrier customization drives lifetime value through recurring pouch and retention system purchases rather than single-transaction kit sales. Three-tier pricing structure across NIJ-certified premium, duty-rated standard, and training-grade economy levels separates military contract holders from municipal procurement channels. Cost compression in soft armor inserts intensifies as UHMWPE suppliers erode Kevlar premiums through weight-performance advantages. Law enforcement agencies demonstrate lowest price sensitivity, absorbing certification premiums, while civilian direct-to-consumer buyers exhibit acute unit economics focus.
Supply Chain Analysis
Para-aramid fiber feedstock draws from domestic DuPont facilities and Teijin operations in Japan, with UHMWPE resin concentrated among DSM in the Netherlands and Honeywell in the United States. Ballistic-grade ceramics source from CoorsTek in Colorado and Morgan Advanced Materials in the United Kingdom, while Cordura nylon weavers cluster in Taiwan and South Korea. Single-source vulnerability in NIJ-certified testing facility capacity extends lead times for new insert designs. Distribution runs through defense contractor prime channels for military contracts and law enforcement distributor networks for municipal agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized laminating expertise for hybrid plate production represents the critical capability gap, with qualified technical workforce scarcity constraining expansion timelines for multi-material integration programs.
For Market Incumbents: Harden ballistic certification pipelines through captive NIJ testing relationships or accredited in-house laboratories to compress time-to-market against contract deadlines. Deepen upstream control over para-aramid fiber supply through long-term offtake agreements with domestic producers, insulating procurement timelines from raw material allocation constraints imposed by UHMWPE substitution trends. For New Entrants and Emerging Players: Pursue civilian direct-to-consumer channels where NIJ certification bypasses traditional law enforcement distributor markups, capturing margin through digitally native brand positioning. Target quick-release mechanism standardization protocols as platform-agnostic retrofit demand emerges, exploiting white space in cross-manufacturer compatibility specifications. For Investors and Strategic Acquirers: Modular integration specialists with established law enforcement channel relationships and MOLLE-compatible design libraries represent priority acquisition archetypes for defense contractor portfolio expansion. Watch NIJ Standard-0101.06 revision implementation timelines as inflection indicators for replacement cycle acceleration across federal and state agency inventories.| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Certification Pipeline Investment | Captive testing capacity compresses product development windows against municipal contract award deadlines. |
| Backward Integration into Fiber-Matrix Production | In-house UHMWPE composite manufacturing insulates margins from DSM and Honeywell supply allocation constraints. |
| Quick-Release Mechanism Standardization | Cross-platform compatibility protocols capture retrofit demand from mixed-vendor carrier ecosystems. |
| Civilian Direct-to-Consumer Channel Launch | Digital-native NIJ-certified brands bypass traditional law enforcement distributor networks and markups. |
| EU AI Act Compliance Architecture | Embedded sensor platforms in smart plate carriers secure first-mover advantage in autonomous threat-detection integration. |
Study Parameters
The analysis maps plate carrier, pouch, holster, and ballistic insert sub-sectors, each validated through procurement officers at municipal police departments, military quartermasters, defense contractor program managers, and NIJ testing facility directors. Primary interview intelligence triangulates against secondary sources including NIJ Standard-0101.06 documentation, ECHA REACH substance databases, SEC 10-K filings from listed defense contractors, and Department of Defense modernization program announcements. Bottom-up vendor shipment data reconciles with top-down military and law enforcement budget appropriations.
Assumptions hold NIJ certification reciprocity stable across NATO procurement channels while varying UHMWPE substitution rates and civilian channel penetration scenarios across the projection horizon. Segmentation models disaggregate by accessory type, material grade, end-user category, and functional priority, with CAGRs derived from replacement cycle analysis and procurement budget trajectories. Forecast inputs incorporate special operations fielding timelines for polyethylene plates and ECHA enforcement intensity on perfluorinated textile treatments.
Sensitivities concentrate around NIJ testing facility capacity expansion, REACH chemical disclosure scope revisions, and UHMWPE fiber-matrix performance breakthroughs. Cross-checking against Department of Defense budget justification documents and state-level law enforcement procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Scuba Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Blast Monitoring Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Face Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Alarm Management System Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market