
 US Industrial Hearing Protection Market | 2026-2036
US Industrial Hearing Protection Market Size, Share, and Industry Trends Forecast 2026-2036
US Industrial Hearing Protection Market Analysis
Multi-source procurement among defense and aviation contractors is hardening as sole-source dependencies on legacy suppliers face scrutiny. 3M leverages its dual strength in disposable foam earplugs and electronic earmuffs to sustain dominance across both commodity and premium tiers. Honeywell International Inc. anchors its position through integrated safety portfolios that bundle respiratory and hearing products for integrated distributor relationships. David Clark Company competes narrowly in aviation-ground-support and cockpit communication headsets where noise-canceling precision commands technical loyalty.
Industrial hearing protection encompasses personal protective equipment engineered to attenuate occupational noise exposure through passive absorption, active electronic cancellation, or structural blocking mechanisms, typically rated by Noise Reduction Rating values tested under ANSI S3.19-1974 protocols to verify decibel reduction across octave-band frequencies. These devices serve the fundamental commercial purpose of preventing noise-induced hearing loss in environments where engineering controls cannot reduce sound below damaging thresholds. Earmuffs with moderate and high NRR ratings capture the largest volume share due to their reusability, visual compliance verification, and compatibility with hard-hat mounting systems in construction and mining. Earplugs represent the fastest-expanding product category as silicone and thermoplastic custom-molded variants displace commodity foam in manufacturing settings where long-duration comfort and consistent fit testing matter. Distribution through industrial safety distributors and direct sales channels controls the majority of margin pools, while online retail grows fastest among small and mid-sized contractors seeking price transparency and rapid replenishment.
OSHA's Hearing Conservation Amendment mandates baseline audiometric testing and hearing protection provision for workers exposed to time-weighted average noise levels exceeding 85 decibels, directly compelling employer expenditure and product certification to ANSI standards. EPA's labeling requirements under 40 CFR Part 211 standardize NRR disclosure and prohibit inflated claims, shaping product development and marketing boundaries for all market participants. NIOSH's recommended exposure limits, though non-mandatory, influence corporate safety policies and insurance underwriting criteria, particularly among self-insured manufacturers with elevated workers' compensation exposure. Stakeholders must monitor the divergence between OSHA's current permissible exposure limit and NIOSH's stricter recommended threshold, as any regulatory harmonization would force accelerated replacement of marginal-protection inventory and reshape competitive positioning across the NRR segmentation ladder.
Market Dynamics
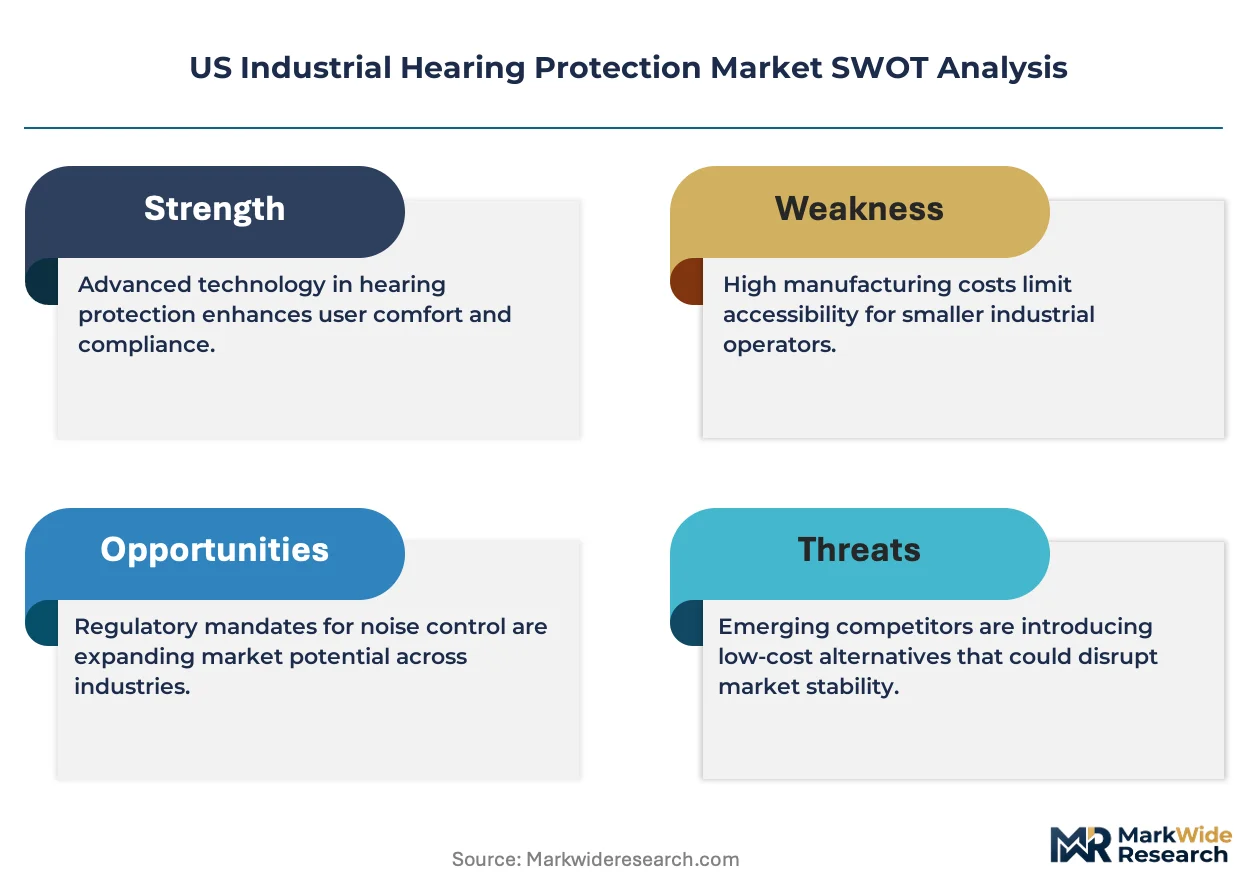
The US Industrial Hearing Protection Market is being structurally reshaped by the divergence between OSHA's current 85-decibel action level and NIOSH's stricter 85-decibel recommended exposure limit, creating regulatory uncertainty that compresses replacement cycles and forces employers toward higher-NRR inventory.
Growth Catalysts
- OSHA Hearing Conservation Amendment:Mandatory baseline audiometric testing and hearing protection provision for workers exposed to time-weighted average noise levels exceeding 85 decibels compels consistent employer expenditure on certified devices.
- Smart earmuffs with Bluetooth communication:Construction and oilfield contractors in Texas and the Gulf Coast are adopting electronic hearing protection that integrates environmental monitoring and two-way radio functionality.
- Manufacturing facility expansion:Heavy industry clusters across Ohio and the Midwest are driving procurement of custom-molded earplugs as long-duration comfort requirements displace commodity foam alternatives.
Market Restraints
- Raw material concentration:Silicone and thermoplastic elastomer supply chains for custom-molded earplugs face input cost volatility tied to petrochemical feedstock pricing.
- Technical fit-testing burden:Individualized earplug fitting under ANSI S3.19-1974 protocols requires specialized equipment and trained personnel, limiting adoption among smaller contractors.
- Substitution by engineering controls:Noise-dampening machinery enclosures and automated remote operation systems reduce headcount in high-decibel zones, compressing addressable PPE demand.
Strategic Opportunities
- California enforcement leadership:The state's Division of Occupational Safety and Health maintains inspection intensity above national averages, accelerating compliance-driven upgrade spending among Los Angeles and Bay Area manufacturers.
- Online retail channel expansion:Direct-to-contractor e-commerce platforms are capturing small and mid-sized construction firms seeking price transparency and rapid replenishment cycles.
- Dual carbon goals convergence:Rechargeable lithium-ion batteries in electronic earmuffs align with corporate sustainability mandates while eliminating disposable battery waste streams.
Industry Challenges
- Audiometric technician shortage:Baseline and annual hearing testing requirements under OSHA standards face execution bottlenecks due to limited certified occupational health professionals in rural industrial corridors.
- Legacy system integration:Smart hearing protection with environmental data logging must interface with existing safety management software, creating IT compatibility friction for multi-site employers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Industrial Hearing Protection Market |
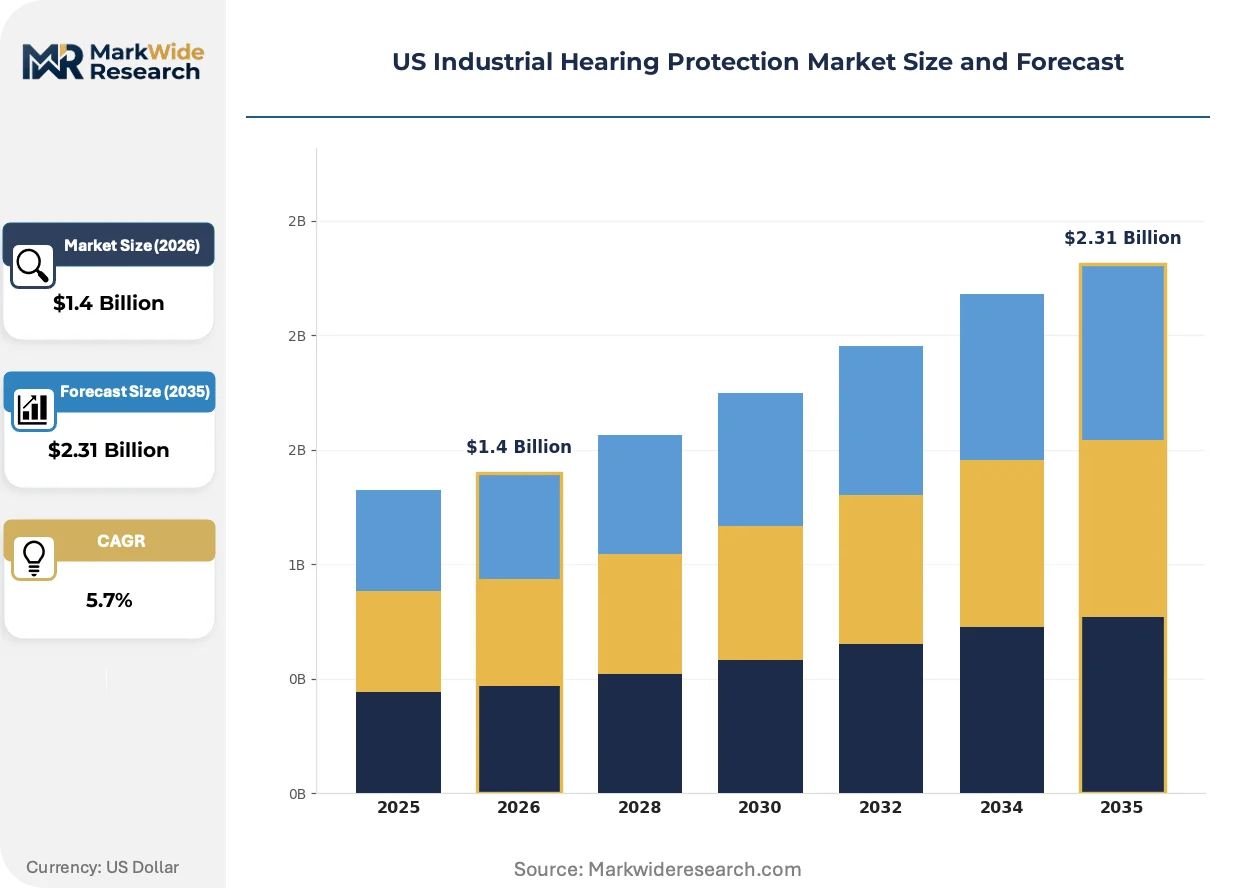
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.31 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Earplugs, Earmuffs, Semi-insert Earplugs, Sound-Dampening Helmets End User: Manufacturing, Construction, Mining, Transportation Noise Reduction Rating: Low NRR, Moderate NRR, High NRR, Maximum NRR Distribution Channel: Online Retail, Direct Sales, Retail Stores, Distributors |
| Companies Covered | 3M, Honeywell International Inc., MSA Safety, David Clark Company, Moldex-Metric, Elvex, Starkey, PROTECH USA, ProtectEar USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Industrial Hearing Protection Market Emerging Trajectories
Active noise-canceling circuitry and biometric sensing are converging in next-generation industrial earmuffs, transforming hearing protection from passive compliance equipment into connected safety infrastructure that feeds real-time data to site supervisors.
Bluetooth-enabled communication earmuffs with environmental dosimetry are rewriting how construction and oilfield contractors manage worker safety. These devices continuously monitor cumulative noise exposure and transmit alerts to supervisors when thresholds approach. Major infrastructure projects in Texas and Louisiana are standardizing on these systems. The technology is compressing demand for standalone noise dosimeters and basic passive earmuffs.
EPA labeling requirements under 40 CFR Part 211 are tightening enforcement against inflated NRR claims, forcing manufacturers to retest legacy product lines under stricter protocols. The regulation is compressing margin on marginal-protection inventory and accelerating phase-out of products that cannot meet revised certification standards. California and Ohio state procurement offices are now requiring third-party ANSI verification for all bulk purchases.
Industrial safety distributors are unbundling after-sales service from product margins, shifting toward subscription-based fit-testing and inventory management programs. Small contractors in the Midwest are bypassing traditional distributor relationships entirely through manufacturer-direct e-commerce portals. This channel compression is most visible among roofing and framing subcontractors seeking same-week delivery on high-NRR disposable earplug cases.
US Industrial Hearing Protection Market Segmentation
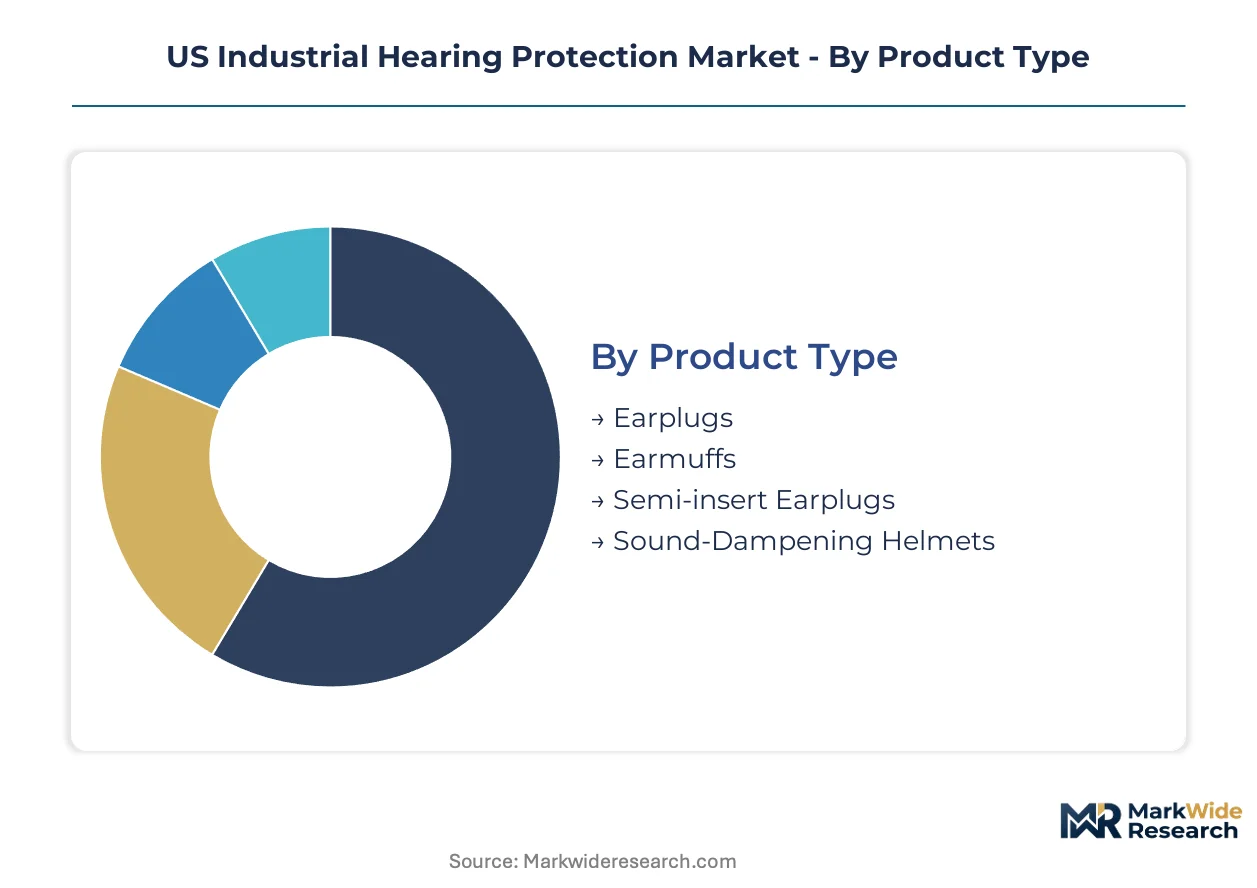
Industrial hearing protection procurement varies sharply by operational environment, regulatory exposure, and workforce mobility. Buyers select across product architectures, noise attenuation specifications, and fulfillment channels based on fit-testing capabilities, replacement frequency, and integration with existing PPE systems.
Product Type:
Noise attenuation technology determines reusability, comfort duration, and compatibility with hard-hat systems across construction and manufacturing workflows.
- Earplugs:Silicone and thermoplastic custom-molded variants displace commodity foam in Ohio and Midwest manufacturing facilities where long-duration wear and consistent fit testing drive specification. This segment is climbing the fastest as ANSI-verified custom molding replaces disposable alternatives in high-compliance environments.
- Earmuffs:Reusable cup-and-seal designs with moderate to high NRR ratings dominate procurement volumes due to visual compliance verification and hard-hat mounting compatibility in Texas oilfield and Gulf Coast construction. Demand concentrates where supervisor spot-checks replace individualized fit protocols.
- Semi-insert Earplugs:Banded designs with replaceable pods offer intermediate protection for intermittent noise exposure in transportation maintenance yards.
- Sound-Dampening Helmets:Integrated headgear combining impact protection with acoustic attenuation serves specialized mining and heavy machinery applications in Appalachia.
Mature deployment sits with Earmuffs. Newer deployment is concentrated in Earplugs.
End User:
Industry verticals impose distinct noise exposure profiles, shift patterns, and regulatory inspection intensities that shape product selection and replacement cycles.
- Manufacturing:Continuous-process facilities across Ohio and the Midwest specify custom-molded earplugs for eight-hour wear cycles, driven by OSHA Hearing Conservation Amendment compliance and state-level enforcement in California. Procurement runs through integrated safety distributors bundling respiratory and hearing products.
- Construction:Project-based contractors in Texas and Louisiana prioritize Bluetooth-enabled electronic earmuffs with environmental dosimetry for site-wide communication and threshold alerting. Channel compression is visible as mid-sized firms bypass distributors for manufacturer-direct e-commerce.
- Mining:Underground and surface extraction operations in Appalachia and the Mountain West require maximum NRR ratings and helmet-integrated systems for dual hazard protection.
- Transportation:Rail yards and aviation ground support in California and the Northeast specify semi-insert designs for intermittent protection during equipment coupling and engine maintenance.
Volume concentration rests with Manufacturing. Technology upgrade intensity peaks in Construction.
Noise Reduction Rating:
Attenuation performance tiers align with decibel exposure mapping, regulatory threshold proximity, and corporate risk management policies.
- Low NRR:Sub-20 decibel reduction ratings serve marginal exposure zones where engineering controls approach compliance thresholds, primarily in automated manufacturing settings.
- Moderate NRR:Mid-range attenuation dominates general industrial procurement where 85-decibel action levels trigger mandatory protection provision under OSHA standards.
- High NRR:Upper-tier passive and electronic systems capture specification in heavy fabrication and oilfield services across Texas and the Gulf Coast where time-weighted averages exceed 90 decibels.
- Maximum NRR:Peak attenuation ratings address mining, forging, and shooting-range environments with sustained exposure above 100 decibels.
Procurement gravity centers on High NRR. Upgrade pressure is intensifying in Maximum NRR.
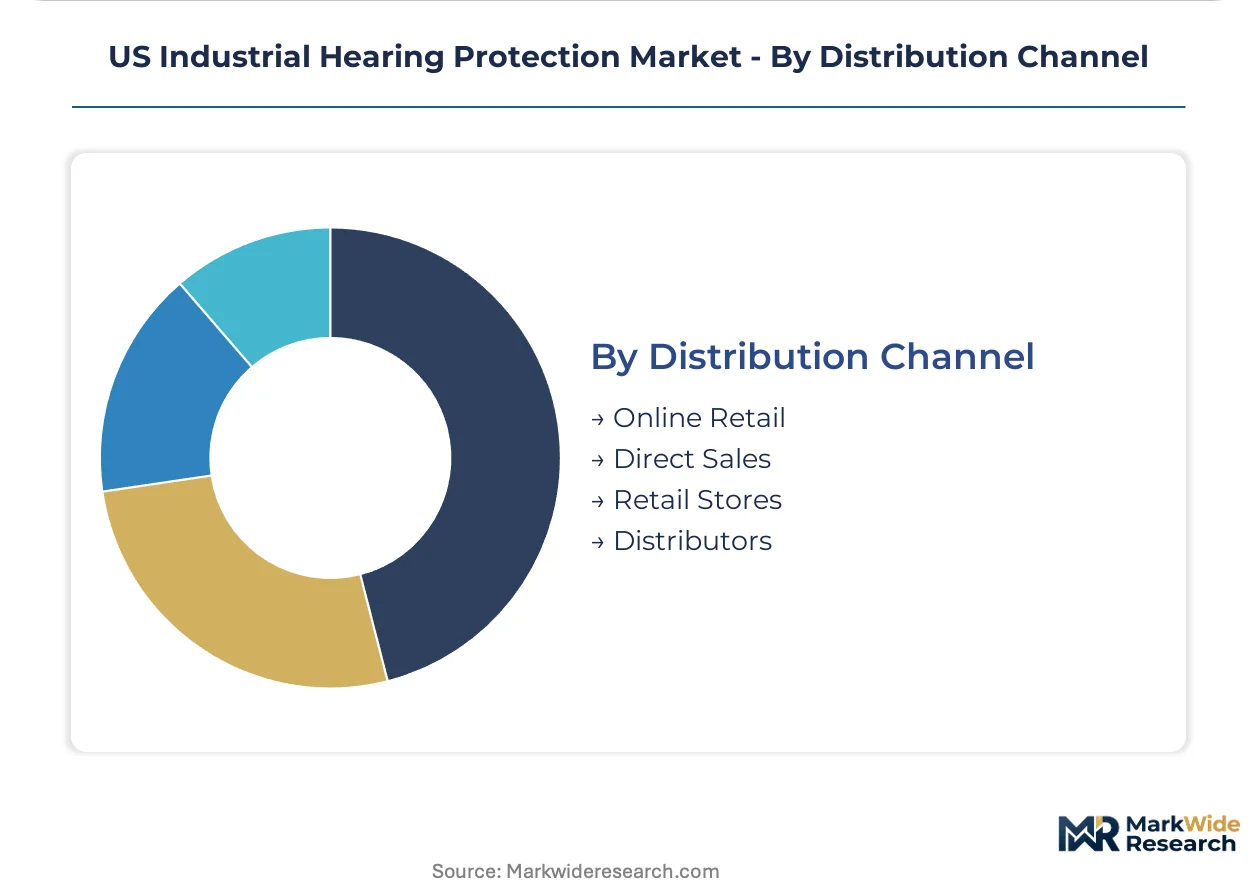
Distribution Channel:
Fulfillment pathway selection reflects order scale, technical service requirements, and replenishment velocity needs.
- Online Retail:Direct-to-contractor platforms capture small and mid-sized roofing and framing subcontractors in the Midwest seeking price transparency and same-week delivery on disposable earplug cases.
- Direct Sales:Manufacturer relationships with self-insured manufacturers enable customized fit-testing programs and volume pricing for multi-site employers.
- Retail Stores:Big-box and specialty safety outlets serve walk-in procurement for immediate replacement needs among independent contractors.
- Distributors:Industrial safety distributors control margin pools through bundled respiratory-hearing portfolios and subscription-based inventory management for large manufacturing accounts.
Margin retention favors Distributors. Channel expansion is fastest in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement intensity concentrates in Texas, California, and Ohio, where heavy industry clusters and state-level workplace safety enforcement drive replacement cycles and upgrade spending across manufacturing, construction, and oilfield operations.
Texas
Oilfield services and Gulf Coast petrochemical expansion are accelerating demand for Bluetooth-enabled electronic earmuffs with environmental dosimetry. OSHA's Permissible Exposure Limit standards apply rigorously to offshore platform and refinery maintenance crews. Houston and Beaumont industrial corridors are standardizing on smart hearing protection that integrates two-way radio functionality for site-wide communication.
California
The state's Division of Occupational Safety and Health maintains inspection intensity above national averages, compelling Los Angeles and Bay Area manufacturers toward higher-NRR inventory and third-party ANSI verification. Cal/OSHA's enforcement posture accelerates compliance-driven upgrade spending. Sacramento Valley food processing and Central Valley agriculture equipment manufacturing are displacing commodity foam with custom-molded silicone earplugs for eight-hour wear cycles.
Ohio
Continuous-process automotive and steel fabrication facilities across the Midwest specify custom-molded thermoplastic earplugs driven by long-duration comfort requirements and consistent fit-testing protocols. Ohio's alignment with federal OSHA standards is supplemented by state-level workers' compensation incentives for audiometric program compliance. Cleveland-Akron and Youngstown-Warren industrial clusters are expanding procurement of high-NRR reusable systems.
Louisiana
Downstream chemical manufacturing and offshore construction in the Gulf Coast corridor are adopting electronic hearing protection with environmental monitoring capabilities. Louisiana Workforce Commission safety initiatives reinforce federal hearing conservation mandates for time-weighted average exposures exceeding 85 decibels. Lake Charles and Baton Rouge petrochemical complexes are driving specification of helmet-integrated systems for dual hazard protection.
Pennsylvania
Appalachian mining operations and Pittsburgh-region heavy machinery fabrication require maximum NRR ratings for sustained exposure above 100 decibels. Pennsylvania Department of Labor and Industry enforcement of mine safety standards shapes procurement toward peak attenuation systems. Erie and Scranton-Wilkes-Barre manufacturing centers are upgrading from marginal-protection inventory to ANSI-verified high-NRR earmuffs.
US Industrial Hearing Protection Market Vendor Landscape
Portfolio diversification dominates the current landscape as incumbents extend across disposable foam, electronic earmuffs, and custom-molded silicone tiers to capture margin at multiple price points. The vendor base organizes around three strategic archetypes: diversified safety conglomerates with integrated respiratory-hearing bundles, specialized hearing protection pure-plays with audiologist channel relationships, and communication headset specialists serving aviation-ground-support niches. M&A activity and technology licensing agreements are the primary competitive moves, with electronic feature integration representing the critical capability gap for legacy passive protection manufacturers.
Within the diversified safety conglomerate tier, 3M and Honeywell International Inc. exemplify portfolio breadth spanning commodity disposables through premium electronic systems. MSA Safety occupies a position anchored in integrated safety equipment for fire service and industrial applications. David Clark Company sits within the communication specialist archetype, serving aviation and ground-support segments where noise-canceling precision commands technical specification loyalty.
| Leading Market Players |
|---|
| 3M |
| Honeywell International Inc. |
| MSA Safety |
| David Clark Company |
| Moldex-Metric |
| Elvex |
| Starkey |
| PROTECH USA |
| ProtectEar USA |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock indices for silicone and thermoplastic elastomers cascade directly into three-tier pricing stratification across premium electronic earmuffs, standard reusable cup-and-seal designs, and economy disposable foam earplugs. Raw material volatility compresses margins on custom-molded earplugs while reinforcing pricing power for integrated safety conglomerates with captive polymer sourcing.
Pricing Analysis
Volume concentration in moderate-NRR reusable earmuffs generates thin margins, while premium electronic systems with Bluetooth and environmental dosimetry capture disproportionate returns. Price differentiation separates ANSI-verified high-NRR products from marginal-protection inventory facing EPA enforcement pressure. Cost compression in commodity foam earplugs intensifies as online retail channels force price transparency. Small roofing and framing subcontractors exhibit highest price sensitivity, whereas self-insured manufacturers prioritize fit-testing service bundling over unit cost.
Supply Chain Analysis
Silicone elastomer supply rests on German and Japanese specialty chemical producers, with thermoplastic feedstock anchored in US Gulf Coast petrochemical complexes. Critical inputs include noise-canceling circuitry from Taiwanese semiconductor fabricators, lithium-ion cells from South Korean battery manufacturers, and acoustic foam from domestic converters. Single-source vulnerability concentrates in active noise-canceling chipsets. Distribution runs through industrial safety distributors controlling bundled respiratory-hearing portfolios, though manufacturer-direct e-commerce bypasses traditional channels for mid-sized contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone and thermoplastic elastomer capacity constraints prop pricing across custom-molded earplug tiers, creating durable margin structures for suppliers with backward-integrated polymer sourcing.
For Market Incumbents: To counter channel compression from manufacturer-direct e-commerce, deepen distributor relationships through subscription-based fit-testing programs and inventory management services. Anchor position by acquiring audiologist-network capabilities in Ohio and California manufacturing corridors where ANSI-verified custom molding displaces commodity foam. For New Entrants and Emerging Players: Direct-to-contractor digital platforms offer the most penetrable route for mid-sized construction firms in Texas and Louisiana seeking rapid replenishment cycles. Target Bluetooth-enabled electronic earmuffs with environmental dosimetry for oilfield contractors standardizing on site-wide communication systems. Pursue white-label manufacturing partnerships with established acoustic engineering houses to bypass R&D capital requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor hearing protection pure-plays with audiologist channel relationships in Midwest manufacturing belts. Long-term viability hinges on regulatory harmonization between OSHA and NIOSH exposure limits forcing accelerated replacement of marginal-protection inventory. Watch EPA enforcement intensity against inflated NRR claims as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Sourcing | Captive silicone supply insulates margin from petrochemical volatility in custom-molded tiers. |
| Bluetooth Communication Platform Development | Electronic earmuff differentiation captures Texas oilfield contractor specification loyalty. |
| Audiologist Network Acquisition | Fit-testing service control locks in Ohio and California manufacturing accounts. |
| Direct-to-Contractor E-Commerce Launch | Channel compression captures Midwest roofing and framing subcontractor procurement. |
| Rechargeable Lithium-Ion Battery Transition | Sustainability alignment eliminates disposable battery waste for corporate ESG mandates. |
Methodological Framework
Independent corroboration across safety equipment distributors, audiometric testing service providers, and industrial procurement managers underwrites the qualitative findings. Primary fieldwork encompassed interviews with plant engineers at Ohio automotive facilities, OSHA compliance officers in California, and channel partners serving Texas oilfield contractors. Secondary validation drew from EPA 40 CFR Part 211 enforcement records, ANSI S3.19-1974 certification databases, and customs data on silicone elastomer imports. Bottom-up demand modeling triangulated against top-down industrial PPE expenditure estimates.
Comparable-period anchoring referenced historical replacement cycles and upgrade spending patterns across the projection horizon. The analytical framework modeled segmentation across product architecture, noise attenuation tier, end-use vertical, and distribution channel. CAGRs derived from fitted growth curves incorporating OSHA enforcement intensity indices, state-level workers' compensation incentive programs, and petrochemical feedstock price trajectories. Industry-specific inputs included NRR verification compliance rates and smart earmuff adoption curves in construction and oilfield applications.
The model holds under steady regulatory divergence between OSHA and NIOSH exposure limits; deviation toward harmonization would shift replacement cycle velocity and inventory valuation. Forecasts reflect assumptions on inspection intensity persistence in California and Texas, custom-molded earplug displacement rates, and electronic feature integration cost curves. A small set of triggers—EPA NRR claim enforcement actions, lithium-ion cell supply disruptions, and audiometric technician labor availability—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Gowns Market
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
Steel Smart Locker Market