
 Electronic Siren Systems Market | 2026-2036
Electronic Siren Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Siren Systems Market Analytics
Project finance for municipal emergency infrastructure is fragmenting the competitive landscape, allowing mid-tier suppliers to bid alongside established defense contractors. Federal Signal Corporation leverages its vertical integration in warning system components to sustain margin control across North American installations. Whelen Engineering Company anchors its position through R&D intensity in LED-array acoustic platforms. Hörmann Warnsysteme competes on geographic dominance in German-speaking European markets for civil protection networks.
Electronic siren systems encompass electro-acoustic warning devices generating tones between 100 dB and 135 dB through motor-driven or electronic oscillator mechanisms, designed for mass notification during natural disasters, military alerts, and industrial emergencies. Fixed sirens dominate municipal installations due to grid-tied reliability and permanent coverage mapping, while portable sirens represent the fastest-expanding category as wildfire-prone jurisdictions in Australia and California prioritize rapid-deployment assets. Solar-powered configurations capture growing margin pools where remote installations lack grid access.
The EU Green Deal and F-Gas Regulation shape product standards for sustainable power integration, while FCC Part 15 and FAA obstruction lighting mandates govern electromagnetic compatibility and aviation safety in US deployments. India's BIS certification requirements and CDSCO-adjacent emergency device protocols create compliance barriers for non-domestic manufacturers. Stakeholders must monitor how national resilience frameworks redefine procurement specifications before committing to platform development roadmaps.
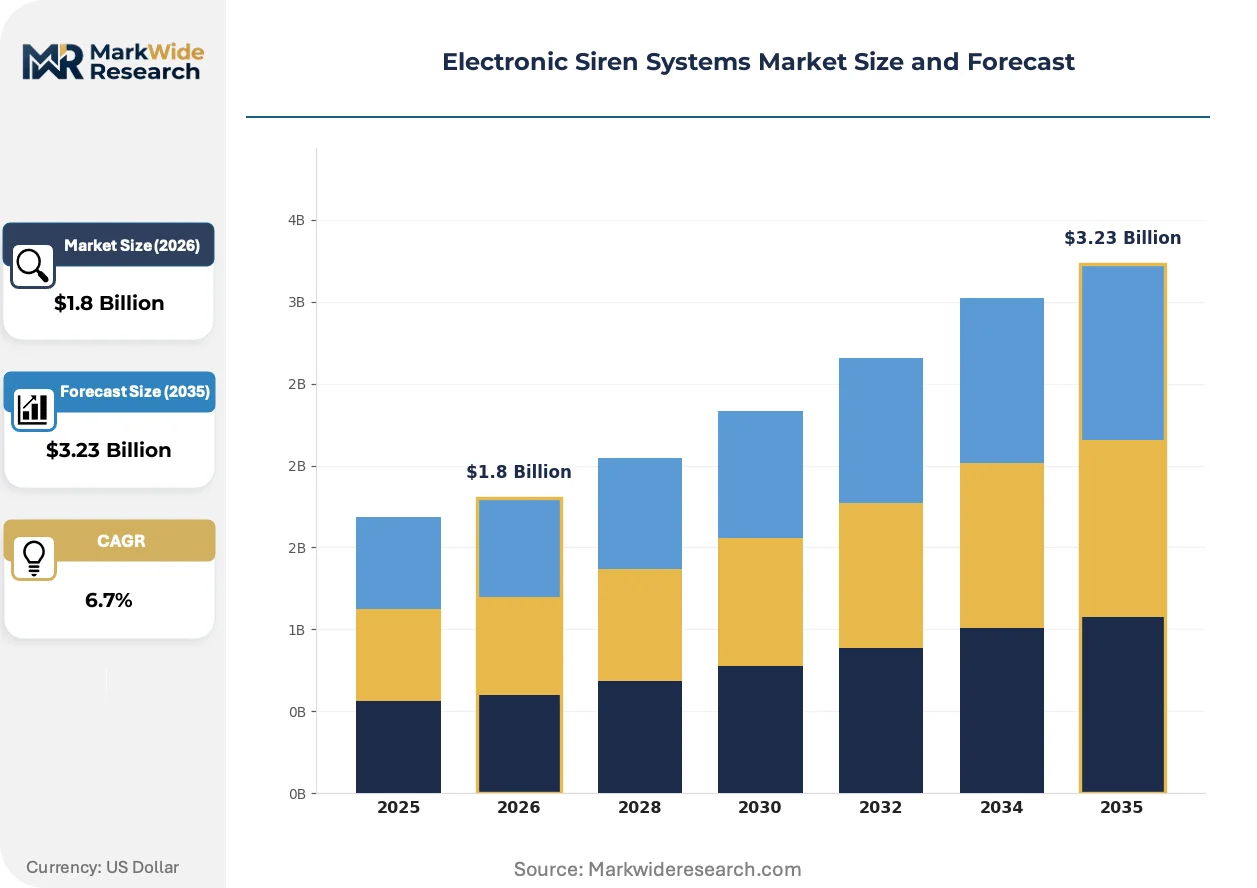
Market Dynamics
Municipal resilience mandates are fragmenting procurement authority away from centralized defense ministries toward city-level emergency management departments, creating bid windows for specialized electro-acoustic suppliers outside traditional contractor networks.
Growth Catalysts
- EU Green Deal resilience mandates:German municipal governments must upgrade civil defense infrastructure under binding climate adaptation frameworks, opening replacement cycles for grid-integrated warning systems.
- Smart city corridor development:India's urban infrastructure programs mandate BIS-certified electronic sirens for disaster preparedness in high-density metropolitan zones.
- Solar-powered remote deployment:Off-grid photovoltaic configurations address coverage gaps in wildfire-prone Australian jurisdictions lacking reliable electrical infrastructure.
Market Restraints
- Neodymium magnet supply concentration:Rare earth dependency on Chinese processing facilities creates input cost volatility for motor-driven siren manufacturers.
- F-Gas Regulation compliance friction:EU restrictions on fluorinated greenhouse gases complicate cooling system designs for high-output electronic oscillator platforms.
- Acoustic masking from urban density:Building height regulations in Mumbai and São Paulo degrade effective coverage radius, forcing denser installation patterns.
Strategic Opportunities
- California wildfire rapid-response contracts:Portable siren procurement for evacuation corridors in fire-prone counties creates demand for battery-backed mobile units.
- FAA obstruction lighting convergence:Dual-function platforms combining aviation safety strobes with mass notification audio reduce infrastructure duplication costs.
- Outcome-based maintenance agreements:Municipal buyers in Nordic countries are piloting performance contracts where suppliers guarantee 99.5% uptime rather than selling hardware outright.
Industry Challenges
- BIS certification timeline compression:Indian domestic testing capacity constraints delay foreign manufacturer market entry by 8-14 months.
- Legacy analog integration complexity:Electromechanical siren networks in Eastern European municipalities resist digital control protocol upgrades without full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Siren Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Sirens, Mobile Sirens, Portable Sirens, Integrated Sirens End User: Public Safety Agencies, Defense Forces, Commercial Vehicles, Emergency Services Installation Type: Roof-Mounted, Bumper-Mounted, Console-Mounted, Wireless Systems Power Source: Battery-Powered, AC-Powered, Solar-Powered, Hybrid Systems |
| Companies Covered | Federal Signal Corporation, Whelen Engineering Company, Sentry Siren Inc., American Signal Corporation, MA Safety Signal, Acoustic Technology Inc., B & M Siren Manufacturing, Hörmann Warnsysteme, E2S Warning Signals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Siren Systems Market Evolving Landscape
Software-defined audio architectures are displacing fixed-tone hardware, enabling municipalities to reprogram warning signals remotely without physical site visits. This shift compresses maintenance labor costs while expanding real-time adaptability during multi-hazard scenarios.
IP-based control platforms are virtualizing siren command hierarchies, replacing dedicated copper-wire activation circuits with encrypted cellular and mesh networks. State emergency management agencies in Texas and Florida are deploying these systems for hurricane-season flexibility. The technology is virtualizing geographic coverage planning by allowing dynamic zone activation rather than fixed district mapping.
FCC Part 15 electromagnetic compatibility mandates are tightening spurious emission limits for networked warning devices, forcing redesigns of power supply filtering and RF shielding. Manufacturers serving US municipal buyers must retest existing product lines against revised Class B digital device standards. Industrial facilities near aviation corridors face overlapping FAA lighting coordination requirements that complicate installation permitting.
Aggregated procurement consortia are consolidating buyer power across county and state boundaries, displacing single-municipality purchasing patterns. Multi-jurisdiction cooperative agreements in the Pacific Northwest and Great Lakes regions bundle siren replacement into unified tender processes. This concentration is most visible in California where Cal OES coordinates wildfire warning system standardization across 58 counties.
Electronic Siren Systems Market Segmentation
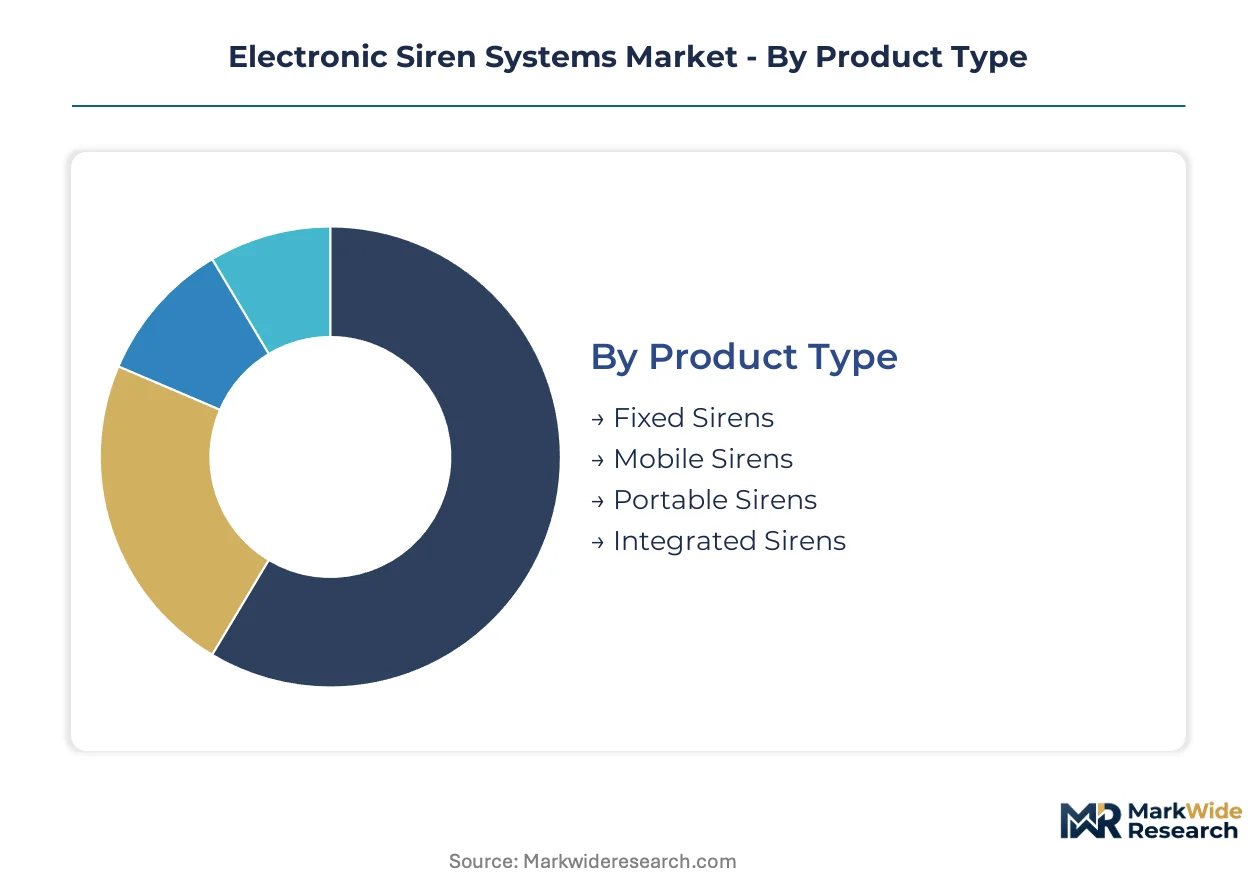
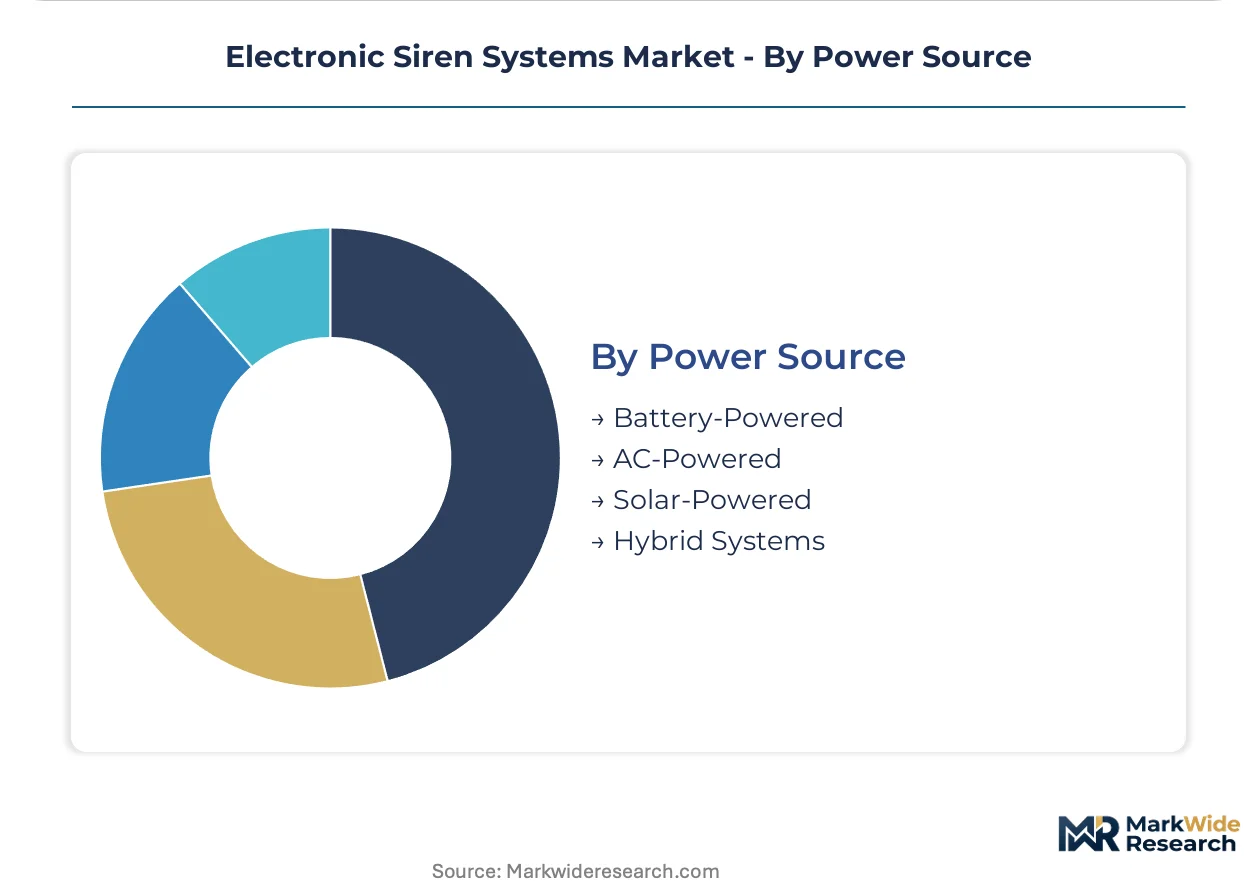
Electronic siren systems fragment across four structural dimensions that reshape procurement patterns and margin architecture. Product configuration determines capital intensity and replacement cycles. End-user identity governs certification requirements and contract structures. Installation topology and power architecture together dictate deployment feasibility across grid-connected versus remote environments.
Product Type:
Cost tier separates permanent infrastructure investments from rapid-deployment assets with divergent depreciation schedules and maintenance obligations.
- Fixed Sirens:Permanent electro-acoustic installations rated for 100-135 dB output through grid-tied motor-driven or electronic oscillator mechanisms. Municipal governments in Germany prioritize these under EU Green Deal resilience mandates for civil defense network upgrades.
- Mobile Sirens:Vehicle-integrated warning systems with rotating or directional acoustic horns for patrol and convoy applications. Defense forces in India specify these for smart city corridor disaster preparedness where BIS certification governs procurement eligibility.
- Portable Sirens:Battery-backed units deployable without fixed infrastructure. Australian wildfire-prone jurisdictions concentrate procurement here for evacuation corridor coverage where grid reliability fails.
- Integrated Sirens:Multi-function platforms combining acoustic warning with visual strobes or data transmission. FAA obstruction lighting convergence creates dual-use demand near aviation corridors.
Fixed sirens command the established base. The steepest expansion runs through portable configurations.
End User:
Customer type determines regulatory jurisdiction and contract structure, from federal defense procurement to municipal emergency management fragmentation.
- Public Safety Agencies:City and county emergency management departments with decentralized procurement authority under resilience frameworks. Cal OES in California coordinates 58-county standardization for wildfire warning procurement.
- Defense Forces:National military and paramilitary organizations with centralized acquisition through defense ministries. FCC Part 15 electromagnetic compatibility mandates govern networked system deployments.
- Commercial Vehicles:Fleet operators requiring compact warning systems for hazard signaling. OSHA workplace safety protocols intersect with state-level commercial vehicle equipment regulations.
- Emergency Services:Fire, ambulance, and search-and-rescue units needing rapid-deployment audio assets. Nordic municipalities pilot outcome-based maintenance agreements guaranteeing 99.5% uptime.
Public safety agencies anchor volume demand. Defense procurement channels are gaining share fastest through resilience mandate funding.
Installation Type:
Mounting topology constrains acoustic coverage geometry and integration complexity with host vehicle or building infrastructure.
- Roof-Mounted:Elevated positioning maximizes acoustic propagation radius in dense urban environments. Mumbai building height regulations force denser installation patterns due to acoustic masking.
- Bumper-Mounted:Forward-facing configurations for traffic clearance and convoy warning. Commercial vehicle fleets specify these for highway hazard signaling compliance.
- Console-Mounted:Interior control integration for operator-activated warning sequences. Emergency services vehicles require these for hands-free activation protocols.
- Wireless Systems:Cellular or mesh-network activation eliminating dedicated control wiring. Texas and Florida state agencies deploy these for hurricane-season geographic flexibility.
Roof-mounted systems dominate municipal infrastructure. Wireless configurations are climbing the fastest through IP-based virtualization of command hierarchies.
Power Source:
Energy architecture determines deployment feasibility across grid-connected, mobile, and off-grid scenarios with divergent total cost of ownership profiles.
- Battery-Powered:Rechargeable storage enabling portable and backup operation without continuous grid access. California counties prioritize these for wildfire rapid-response contracts in evacuation corridors.
- AC-Powered:Grid-tied operation for permanent installations with highest sustained output capability. German municipal upgrades under EU Green Deal specify grid-integrated configurations.
- Solar-Powered:Photovoltaic panels with battery buffering for remote locations lacking electrical infrastructure. Australian jurisdictions lacking reliable grid access capture growing margin pools here.
- Hybrid Systems:Multi-source power management combining AC, battery, and solar inputs. F-Gas Regulation compliance friction shapes cooling system designs for high-output electronic oscillator platforms.
AC-powered systems retain the installed base. Solar-powered configurations are expanding most quickly where remote coverage gaps persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German municipal procurement corridors under EU Green Deal mandates, while Indian smart city programs compress margins through BIS certification barriers and localized sourcing requirements.
Germany
Municipal governments across Bavaria and North Rhine-Westphalia are replacing legacy electromechanical networks with grid-integrated electronic oscillator platforms. The EU Green Deal's binding climate adaptation frameworks mandate civil defense infrastructure resilience upgrades by 2030. Stuttgart and Munich clusters dominate specification-setting for German-speaking European markets.
United States
California counties are consolidating wildfire rapid-response procurement through Cal OES coordination across 58 counties for portable battery-backed units. FCC Part 15 electromagnetic compatibility mandates are tightening spurious emission limits for networked warning devices. Texas and Florida state agencies deploy IP-based control platforms for hurricane-season geographic flexibility.
India
Smart city corridors in Maharashtra and Karnataka mandate BIS-certified electronic sirens for disaster preparedness in high-density metropolitan zones. CDSCO-adjacent emergency device protocols create compliance barriers extending foreign manufacturer market entry by 8-14 months. Mumbai's building height regulations force denser installation patterns due to acoustic masking degradation.
Australia
Wildfire-prone jurisdictions in New South Wales and Victoria prioritize solar-powered portable configurations where grid reliability fails during evacuation corridor coverage. TGA-equivalent state-level emergency equipment standards govern deployment specifications. Queensland remote installations capture growing margin pools through off-grid photovoltaic configurations.
Japan
Metropolitan Tokyo and Osaka prefectures are modernizing tsunami warning networks through METI-coordinated resilience infrastructure programs. JIS standards for electro-acoustic warning devices shape procurement specifications for mass notification systems. Kanto region manufacturers supply LED-array acoustic platforms for municipal disaster preparedness upgrades.
Electronic Siren Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying oscillator mechanisms, acoustic horns, and power management modules. The vendor base organizes around three tiers: defense contractors with centralized ministry relationships, municipal-focused electro-acoustic suppliers with decentralized emergency management access, and component fabricators capturing margin from rare earth magnet and LED array inputs. Consolidation pressure runs through aggregated procurement consortia bundling multi-county replacement cycles. Competitive moves center on geographic expansion into smart city corridors and backward integration into warning system component production.
Among North American platform integrators, Federal Signal Corporation and Whelen Engineering Company occupy positions representing consolidated system-tier capabilities. Federal Signal exemplifies vertical control through in-house production of warning system components. Whelen Engineering sits within the R&D-intensive archetype developing LED-array acoustic platforms. Hörmann Warnsysteme anchors geographic specialization for German-speaking European civil protection networks. These three represent distinct competitive positioning vectors: component-captive manufacturing, technology-intensive product development, and regional market dominance.
| Leading Market Players |
|---|
| Federal Signal Corporation |
| Whelen Engineering Company |
| Sentry Siren Inc. |
| American Signal Corporation |
| MA Safety Signal |
| Acoustic Technology Inc. |
| B & M Siren Manufacturing |
| Hörmann Warnsysteme |
| E2S Warning Signals |
| Others |
Value Network & Pricing Analysis
Rare earth processing concentration in Chinese facilities for neodymium magnets feeds directly into margin compression for motor-driven siren manufacturers, pushing value capture toward solar-powered electronic oscillator platforms with lower magnet dependency.
Pricing Analysis
Configured-to-order pricing for integrated siren platforms commands 40-60% premiums over standard fixed-tone units due to FAA obstruction lighting convergence requirements. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified systems for Indian smart city procurement from basic AC-powered municipal installations. Price erosion runs through portable siren categories as California counties consolidate 58-county procurement through Cal OES coordination. Public safety agencies with aggregated consortium purchasing exhibit highest price sensitivity; defense forces with centralized ministry channels show lowest.
Supply Chain Analysis
Neodymium magnet feedstock draws from Chinese rare earth processing facilities, with LED array components sourced from South Korean and Japanese semiconductor fabs. Raw material dependencies center on rare earth magnet alloys, photovoltaic cells for solar configurations, and copper wiring for grid-tied installations. Single-source vulnerability in Chinese magnet processing creates tariff exposure under evolving trade frameworks. Distribution runs through municipal procurement consortia in North America and defense ministry channels in India and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based maintenance agreements in Nordic municipalities are expanding faster than hardware unit sales, converting capital expenditure into recurring service revenue with 99.5% uptime guarantees.
For Market Incumbents: Build certification moats through accelerated BIS testing investments in India, compressing foreign entrant timelines by 8-14 months. Deepen backward integration into LED-array acoustic platforms to match Whelen Engineering's R&D intensity. Defend against municipal procurement fragmentation by embedding software-defined audio architectures that lock in multi-hazard reprogramming dependencies. For New Entrants and Emerging Players: Build out solar-powered portable configurations for Australian wildfire-prone jurisdictions lacking grid infrastructure, the most penetrable white-space segment. Target California rapid-response contracts through battery-backed mobile units as Cal OES consolidates 58-county procurement. Pursue outcome-based maintenance pilots in Nordic municipalities as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined audio platforms as IP-based virtualization displaces dedicated copper-wire infrastructure. Long-term viability favors component-captive integrators with in-house oscillator production over pure assembly operations. Monitor FAA obstruction lighting convergence mandates as the signal for dual-function platform demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Audio Architecture Development | Enables remote reprogramming for multi-hazard scenarios without physical site visits. |
| BIS Certification Fast-Track Investment | Compresses 8-14 month market entry delays for Indian smart city corridor access. |
| Solar-Powered Platform Expansion | Captures margin pools in Australian and California off-grid wildfire evacuation deployments. |
| Outcome-Based Maintenance Pilot Programs | Converts Nordic municipal hardware sales into recurring 99.5% uptime guarantee contracts. |
| FAA Obstruction Lighting Convergence | Reduces infrastructure duplication costs near aviation corridors through dual-function platforms. |
Research Methodology
The analysis maps fixed, mobile, portable, and integrated siren configurations, each validated through municipal emergency management directors, defense procurement officers, and electro-acoustic component suppliers. Primary interviews with civil protection network engineers, smart city infrastructure planners, and wildfire response coordinators combined with secondary validation from FCC Part 15 filings, EU Green Deal implementation reports, and BIS certification databases. Bottom-up unit shipment estimates and top-down municipal budget allocation analysis provided triangulation across the projection horizon.
Assumptions held EU Green Deal resilience mandates and BIS certification timelines fixed while varying solar cost curves and rare earth magnet pricing volatility. Segmentation modeling incorporated product configuration, end-user identity, installation topology, and power architecture dimensions. CAGRs derived from replacement cycle analysis of legacy electromechanical networks and penetration rates for IP-based control platforms. Industry-specific inputs included Cal OES procurement coordination patterns and F-Gas Regulation compliance friction in cooling system designs.
Stress conditions across neodymium supply disruption severity, Indian domestic testing capacity expansion, and California wildfire frequency acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about municipal resilience mandate adoption curves and defense ministry centralization trends. Cross-checking against aggregated procurement consortium bid volumes and FAA obstruction lighting permit filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
China Premium Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Splash Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Alarm Management System Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Apparel Market