
 Global Power Air Purifying Respirator Market | 2026-2036
Global Power Air Purifying Respirator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Air Purifying Respirator Market Intelligence
The EU Green Deal's industrial emissions framework is rebalancing procurement criteria across European manufacturing facilities toward electrically assisted respiratory protection. 3M Company leverages its filtration science heritage to sustain dominant positions in both battery-operated and hybrid system architectures. Honeywell International Inc. anchors its portfolio through integrated connected-safety platforms that link PAPR units to real-time exposure monitoring networks. Dragerwerk AG & Co. KGaA differentiates via specialized full-facepiece designs that serve chemical processing environments with stringent inward-leakage requirements.
A power air purifying respirator is a motor-driven breathing apparatus that draws ambient air through high-efficiency filters—typically HEPA or P100 cartridges—and delivers cleaned airflow to the wearer's breathing zone under positive pressure, with battery systems generally operating eight to twelve hours on a single charge. Full facepiece configurations command the deepest margin pools due to complex sealing geometries and integrated communications hardware, while helmet and hood variants lead volume growth in pharmaceutical manufacturing where loose-fitting designs accommodate prescription eyewear and facial hair. Compressed air technology retains share in mining operations and oil and gas facilities where intrinsic safety requirements restrict battery-powered equipment in explosive atmospheres.
OSHA's respirable crystalline silica enforcement in the United States, REACH chemical exposure frameworks across Europe, and China's GB standards administered by the Ministry of Emergency Management collectively elevate product certification burdens and accelerate replacement cycles for non-compliant legacy equipment. The FDA's emergency use authorization pathways for pandemic preparedness stockpiles in the United States create parallel demand streams distinct from industrial occupational safety procurement. Stakeholders must monitor divergence between regional certification standards as interoperability becomes a decisive factor for multinational facility operators standardizing fleet procurement across jurisdictions.
Market Dynamics
OSHA's respirable crystalline silica enforcement is compressing replacement cycles for legacy passive respirators across US manufacturing, while China's GB standards administered by the Ministry of Emergency Management accelerate fleet turnover in industrial corridor cities. Battery chemistry improvements and connected-safety platform integration are simultaneously reshaping procurement criteria toward intelligent PAPR architectures.
Growth Catalysts
- Silica Dust Regulations:OSHA's updated respirable crystalline silica standard compels US construction and mining employers to replace disposable masks with powered systems that maintain positive pressure.
- China's Industrial Safety Enforcement:State-level work safety bureaus in corridor cities enforce stricter occupational exposure limits, mandating electrically assisted respiratory protection in heavy manufacturing.
- Battery Energy Density Gains:Lithium-ion cell improvements extend single-charge operation from eight to twelve hours, eliminating shift-change equipment swaps in pharmaceutical cleanrooms.
Market Restraints
- Filter Cartridge Supply Concentration:High-efficiency media production clusters in East Asian manufacturing hubs, exposing buyers to logistics disruptions and input cost volatility.
- Intrinsic Safety Limitations:Battery-powered units face restrictions in ATEX Zone 0 mining environments and oil/gas facilities, preserving demand for compressed airline systems.
- Certification Fragmentation:Divergence between NIOSH approval pathways, CE marking under EU PPE Regulation 2016/425, and China's GB standards creates compliance friction for multinational fleet standardization.
Strategic Opportunities
- Pandemic Preparedness Stockpiles:FDA emergency use authorization pathways for strategic national stockpiles create parallel demand streams distinct from industrial occupational safety procurement in the United States.
- Connected-Safety Convergence:Integration of PAPR units with real-time exposure monitoring networks and industrial IoT platforms opens premium pricing in chemical processing and semiconductor fabrication.
- India's Manufacturing Expansion:Factory construction under the PLI scheme drives first-time PAPR adoption in automotive and electronics assembly where silica and solvent exposures previously went unmonitored.
Industry Challenges
- Technical Service Capacity:Qualified technicians for blower motor maintenance and filter flow testing remain scarce in secondary industrial cities, lengthening equipment downtime.
- Legacy System Integration:Retrofitting connected PAPR fleets into existing SCADA and EHS management platforms demands custom API development and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Air Purifying Respirator Market |
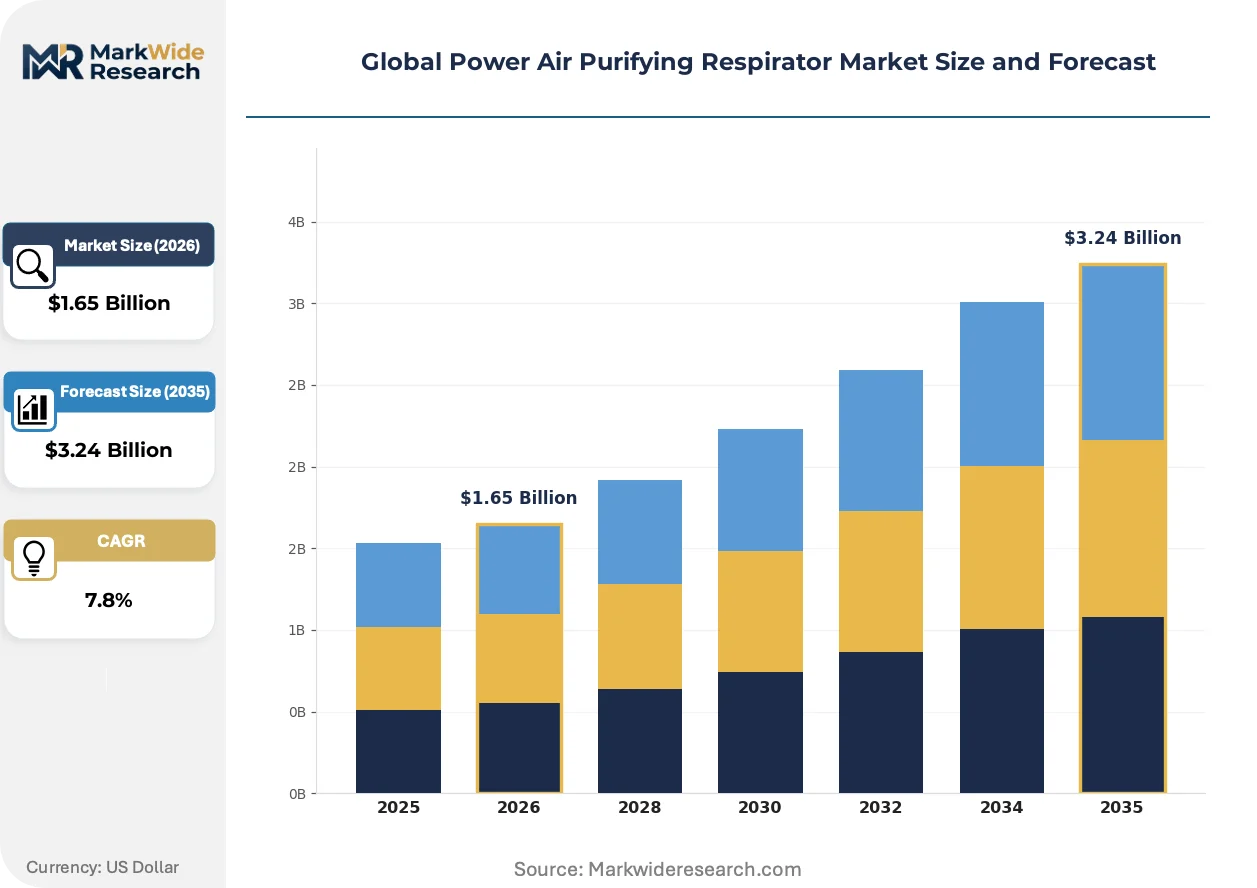
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.24 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose-Fitting, Half Mask, Full Facepiece, Helmet, Hood, Visor Technology: Battery Operated, Compressed Air, Chemical Cartridge, Electrostatic, Hybrid Application: Pharmaceutical Manufacturing, Chemical Processing, Mining Operations, Construction Sites, Metal Fabrication End User Industry: Oil & Gas Facilities, Food Processing Plants, Emergency Response Teams, Laboratories, Fire Services |
| Companies Covered | 3M Company, Honeywell International Inc., Dragerwerk AG & Co. KGaA, Mine Safety Appliances (MSA) Company, Bullard, ILC Dover, Optrel AG, Kimberly-Clark Corporation, Avon Rubber PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Air Purifying Respirator Market Strategic Shifts & Innovations
Electrification of respiratory protection is converging with industrial digitalization, creating intelligent PAPR architectures that transmit exposure data and equipment status in real time. Three developments are reshaping competitive positioning and procurement patterns.
Smart blower units with embedded particulate sensors are overtaking conventional fixed-speed designs in pharmaceutical manufacturing and chemical processing. These systems automatically adjust airflow based on real-time filter loading measurements, extending cartridge life by thirty to fifty percent in high-dust environments. Novartis and BASF facilities in Switzerland and Germany have standardized on these adaptive architectures, compressing demand for passive flow-indicator models.
REACH chemical exposure frameworks across Europe are tightening inward-leakage requirements for full-facepiece designs, accelerating R&D investment in advanced sealing geometries and exhalation valve technologies. The European Chemicals Agency's 2023-2028 work program targets respiratory sensitizers in polyurethane production, forcing manufacturers to recertify legacy products under stricter test protocols. German chemical processors are responding by consolidating procurement around suppliers with integrated testing laboratories.
Buyers in Australia's mining sector are unbundling after-sales service from equipment purchase, contracting independent technical service providers for fit testing and maintenance. This disintermediation of OEM service networks is most visible in Western Australia's Pilbara region, where Rio Tinto and BHP operate centralized respiratory protection programs across multiple mine sites, reducing per-unit lifetime costs through volume-based service agreements.
Global Power Air Purifying Respirator Market Segmentation
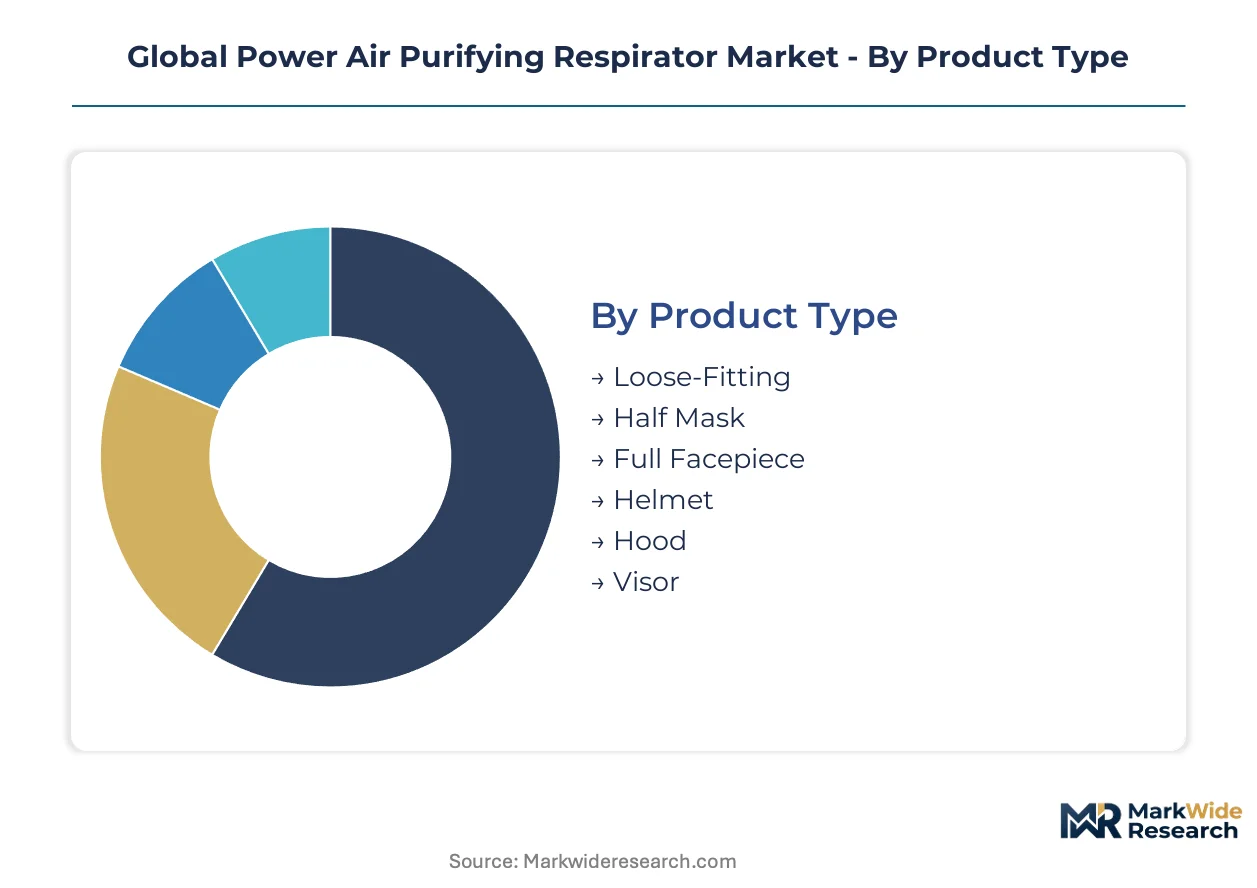
Segmentation in the power air purifying respirator market reveals divergent capital requirements and procurement patterns across protective configurations. Equipment buyers balance upfront acquisition costs against operational constraints including filter replacement schedules, battery maintenance infrastructure, and regulatory compliance burdens.
Product Type:
Capital intensity varies sharply across facepiece architectures, with integrated systems demanding substantially higher initial investment than modular alternatives.
- Full Facepiece:Complex sealing geometries and integrated communications hardware elevate unit costs significantly. Chemical processing facilities in Germany's Ruhr industrial cluster specify these configurations to meet ECHA's tightening inward-leakage requirements for respiratory sensitizers.
- Hood:Loose-fitting designs accommodate prescription eyewear and facial hair without fit testing overhead. Pharmaceutical cleanrooms in Switzerland's Basel region favor hood variants for extended-shift compatibility where battery chemistry improvements eliminate mid-shift equipment swaps.
- Loose-Fitting:Minimal sealing complexity reduces per-unit cost for high-turnover environments.
- Half Mask:Compact form factor suits maintenance operations requiring frequent donning and doffing.
- Helmet:Integrated head protection serves construction and mining sites with falling object hazards.
- Visor:Face shield compatibility addresses grinding and welding applications in metal fabrication.
Full facepiece configurations absorb the bulk of installed capacity; hood variants are expanding most quickly.
Technology:
Power source selection determines operational flexibility, with compressed air systems requiring permanent infrastructure versus battery mobility.
- Battery Operated:Lithium-ion cell improvements extend single-charge operation from eight to twelve hours. China's industrial corridor cities mandate these systems under Ministry of Emergency Management enforcement of stricter occupational exposure limits.
- Compressed Air:Intrinsically safe for ATEX Zone 0 environments where battery ignition risks are prohibitive. Australia's Pilbara mining operations preserve demand for airline systems despite higher lifetime infrastructure costs.
- Chemical Cartridge:Specialized sorbent media target specific vapor contaminants in laboratory settings.
- Electrostatic:Enhanced particle capture efficiency serves semiconductor fabrication cleanrooms.
- Hybrid:Dual-power architectures provide backup redundancy for emergency response applications.
Battery operated technology commands the dominant installed base; compressed air retains irreplaceable share in explosive atmospheres.
Application:
Regulatory enforcement intensity varies by sector, with silica dust rules driving replacement cycles in construction and mining.
- Mining Operations:Silica dust exposure mandates powered systems over passive alternatives. OSHA's updated respirable crystalline silica standard compels US employers toward positive-pressure architectures in underground and surface extraction.
- Pharmaceutical Manufacturing:Containment requirements for potent compound handling drive specification of adaptive blower units with embedded particulate sensors. Novartis facilities in Switzerland have standardized on these intelligent architectures.
- Chemical Processing:Corrosive atmospheres and vapor exposures demand specialized sealing technologies.
- Construction Sites:Fragmented contractor base and project-based procurement create price-sensitive demand.
- Metal Fabrication:Welding fume and grinding dust exposures concentrate demand in automotive supply chains.
Mining operations absorb the bulk of installed capacity; pharmaceutical manufacturing is climbing the fastest.
End User Industry:
Procurement sophistication diverges between safety-critical operations and general industrial applications.
- Oil & Gas Facilities:Intrinsic safety requirements restrict battery-powered equipment in explosive atmospheres. Facilities in the US Gulf Coast and Norway's North Sea operations maintain compressed airline system dominance.
- Emergency Response Teams:FDA emergency use authorization pathways for pandemic preparedness stockpiles create parallel demand streams distinct from industrial occupational safety procurement in the United States.
- Food Processing Plants:Washdown compatibility and contamination prevention drive specification requirements.
- Laboratories:Research-scale operations favor compact half-mask configurations for intermittent use.
- Fire Services:Structural firefighting applications remain dominated by self-contained breathing apparatus rather than powered air purifying alternatives.
Oil and gas facilities absorb the bulk of installed capacity; emergency response teams are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara mining corridor in Western Australia anchors procurement volume for compressed airline systems, while regulatory enforcement across multiple jurisdictions reshapes equipment specifications toward powered alternatives.
United States
Construction and mining operations drive replacement demand as silica dust enforcement intensifies. OSHA's updated respirable crystalline silica standard compels employers toward positive-pressure architectures in surface and underground extraction. The Gulf Coast petrochemical corridor maintains demand for intrinsically safe compressed air systems in explosive atmosphere zones.
Germany
Chemical processing facilities prioritize advanced sealing technologies for respiratory sensitizer protection. REACH frameworks administered by ECHA tighten inward-leakage requirements for full-facepiece designs. The Ruhr industrial cluster consolidates procurement around suppliers with integrated testing laboratories for recertification compliance.
China
Heavy manufacturing in corridor cities mandates electrically assisted respiratory protection under stricter occupational exposure limits. GB standards enforced by the Ministry of Emergency Management accelerate fleet turnover of legacy passive equipment. The Yangtze River Delta manufacturing belt leads adoption of battery-operated systems with extended-shift compatibility.
Australia
Mining expansion in Western Australia drives PAPR procurement as silica dust regulations tighten across surface extraction operations. State-level work safety bureaus enforce compliance deadlines that compress replacement cycles for disposable masks. Rio Tinto and BHP operate centralized respiratory protection programs across multiple Pilbara mine sites.
Switzerland
Pharmaceutical cleanrooms specify adaptive blower units with embedded particulate sensors for potent compound handling. Novartis facilities in the Basel region standardize on intelligent architectures that eliminate mid-shift equipment swaps. The country's precision manufacturing heritage supports premium positioning for connected-safety platform integration.
Global Power Air Purifying Respirator Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with filtration science heritage and integrated safety platform capabilities. Market concentration remains moderate with established players commanding premium positions in full-facepiece architectures while specialized entrants capture niche applications. Three archetypes dominate: diversified technology conglomerates with cross-sector safety portfolios, dedicated respiratory protection specialists with deep regulatory expertise, and regional fabricators serving price-sensitive procurement in emerging manufacturing bases. Capacity expansion in battery system architectures and strategic partnerships for connected-safety convergence represent the dominant competitive vectors reshaping positioning.
Among diversified technology conglomerates, 3M Company and Honeywell International Inc. exemplify archetypes that leverage filtration science heritage and integrated platform capabilities respectively. Dragerwerk AG & Co. KGaA occupies a specialist position anchored in full-facepiece designs for chemical processing environments with stringent inward-leakage requirements. These three entities represent distinct strategic postures: technology breadth, platform integration depth, and application-specific engineering specialization.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| Dragerwerk AG & Co. KGaA |
| Mine Safety Appliances (MSA) Company |
| Bullard |
| ILC Dover |
| Optrel AG |
| Kimberly-Clark Corporation |
| Avon Rubber PLC |
| Others |
Cost & Logistics Intelligence
Backward integration into battery cell production anchors both supply security and margin defense for PAPR manufacturers facing lithium-ion cost volatility. OEMs with captive energy storage capabilities command pricing power against competitors dependent on spot-market cell procurement from East Asian suppliers.
Pricing Analysis
Uptime guarantees and shift-coverage commitments anchor value-based pricing for battery-operated systems in pharmaceutical cleanrooms. Three-tier pricing structure across premium, standard, and economy levels separates connected-safety platforms with real-time monitoring from basic blower units and disposable hood configurations. Cost compression in the economy tier intensifies as Chinese regional fabricators scale production of GB-certified alternatives. Construction contractors exhibit highest price sensitivity due to project-based procurement, while chemical processors prioritize certification grade over unit cost.
Supply Chain Analysis
High-efficiency filtration media supply rests on Japanese and German specialty manufacturers with proprietary electrospinning capabilities. Lithium-ion cells draw from South Korean and Chinese producers, while blower motor assemblies concentrate in Taiwan and Malaysia. Single-source vulnerability in HEPA-grade nanofiber substrates exposes buyers to allocation constraints during industrial demand surges. Distribution runs through authorized safety equipment distributors with fit-testing certification, though Australia's mining sector increasingly contracts independent technical service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is compressing margins for assemblers without upstream control over battery systems or filtration media. Players capturing cell production or sorbent manufacturing capabilities secure cost structures unavailable to pure integrators.
For Market Incumbents: Extend connected-safety platform architectures to lock in pharmaceutical and semiconductor accounts before standardization settles. Deepen backward integration into lithium-ion cell assembly to offset East Asian supplier pricing power. Defend against emerging Chinese regional fabricators by accelerating NIOSH and CE marking recertification timelines that strain competitor compliance budgets.
For New Entrants and Emerging Players: Enter via India's PLI-driven manufacturing expansion where first-time PAPR adoption in automotive assembly outpaces established supplier coverage. Target secondary industrial cities with technical service partnerships that address qualified technician scarcity. Lead with battery rental and maintenance subscription models that reduce capital barriers for price-sensitive construction contractors.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking respiratory protection platform additions. Long-term viability favors targets with integrated testing laboratories and multi-jurisdiction certification portfolios. Watch FDA emergency use authorization stockpile awards as inflection signals for pandemic preparedness revenue durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | Captive lithium-ion supply insulates margins from East Asian spot-market volatility. |
| Connected-Safety Platform Certification | Real-time exposure monitoring integration commands premium positioning in German chemical processing. |
| Multi-Jurisdiction Certification Investment | Simultaneous NIOSH, CE marking, and GB standard approval enables multinational fleet standardization. |
| Independent Technical Service Partnership | Fit-testing and maintenance contracts in Australia's Pilbara mining region reduce customer lifetime costs. |
| Adaptive Blower Unit Development | Embedded particulate sensors extend filter cartridge life by thirty to fifty percent in high-dust environments. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant safety officers, industrial hygienists, OEM procurement managers, and aftermarket service technicians combined with OSHA enforcement databases, NIOSH approval registries, and EU PPE Regulation 2016/425 conformity assessments. Bottom-up equipment shipment tracking and top-down industrial safety spending estimates were triangulated against Ministry of Emergency Management GB standard adoption metrics.
Segment-level modeling addressed facepiece architecture, power source technology, and end-use industry across the analysis window. Pharmaceutical manufacturing adoption patterns, mining sector silica compliance deadlines, and chemical processing inward-leakage requirements informed demand-side assumptions. Supply-side inputs incorporated battery chemistry improvement curves and filtration media production capacity. CAGRs derived from equipment replacement cycle compression and regulatory enforcement intensity trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt battery raw material export restrictions or accelerated harmonization of regional certification standards. Projections reflect documented assumptions regarding OSHA enforcement continuity, China's GB standard implementation timelines, and lithium-ion cell cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market