
 Self-Contained Breathing Apparatus (SCBA) Market | 2026-2036
Self-Contained Breathing Apparatus (SCBA) Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Contained Breathing Apparatus (SCBA) Market Analytics
NFPA 1981-compliant specification tiers is collapsing the gap between premium and mid-market offerings as fire departments prioritize interoperability and shared maintenance protocols. MSA Safety leverages its integrated manufacturing footprint to sustain margin control across cylinder and mask assemblies. Drägerwerk AG & Co. KGaA anchors European demand through its deep specialization in closed-circuit military and industrial systems. Honeywell International Inc. competes aggressively on channel density, particularly within North American municipal procurement frameworks.
A self-contained breathing apparatus is a respiratory protection device comprising a high-pressure compressed air cylinder, pressure regulator, facepiece, and harness assembly, designed to supply breathable air independently of ambient atmosphere for durations typically ranging from thirty to sixty minutes depending on cylinder capacity and user exertion levels. Its primary purpose is to protect personnel from oxygen-deficient, toxic, or otherwise immediately dangerous to life and health atmospheres during emergency response and hazardous operations. Open-circuit systems occupy the dominant share of municipal firefighting procurement due to lower unit cost and simplified training requirements, while electronic monitoring technology represents the fastest-expanding margin pool as departments integrate biometric telemetry and remote accountability features. Confined space entry applications within the industrial sector sustain steady replacement cycles driven by OSHA-mandated fit testing and cylinder hydrostatic inspection intervals.
OSHA respiratory protection standards in the United States, NFPA 1981 performance requirements, and CE marking under the EU Personal Protective Equipment Regulation collectively define product compliance thresholds and market access conditions across major demand centers. These frameworks directly shape R&D priorities, with manufacturers prioritizing reduced breathing resistance, thermal performance, and integrated communications compatibility to satisfy evolving certification benchmarks. Stakeholders must monitor pending updates to cylinder materials standards, particularly around composite fiber wrap technologies, as these specifications will determine next-generation product development roadmaps and capital allocation across manufacturing lines.
Market Dynamics
NFPA 1981 certification upgrades are compressing product lifecycles across municipal fire departments, forcing simultaneous fleet replacement and accelerating inventory turnover for compliant SCBA systems.
Growth Catalysts
- Fleet Modernization Mandates:Municipal fire departments in the United States face accelerated replacement schedules driven by NFPA 1981 certification upgrades, creating sustained procurement pressure for compliant systems.
- OSHA Confined Space Enforcement:Industrial facilities face intensified respiratory protection audits, sustaining replacement cycles for cylinder hydrostatic testing and fit certification programs.
- Composite Cylinder Adoption:Carbon fiber wrap technologies reduce cylinder weight by approximately one-third compared to aluminum alternatives, improving mobility for extended-duration operations.
Market Restraints
- Raw Material Concentration:Carbon fiber supply chains concentrate among Japanese and South Korean producers, exposing manufacturers to input volatility and geopolitical supply disruptions.
- Certification Cost Burden:NFPA 1981 and CE marking under EU Personal Protective Equipment Regulation impose extensive third-party testing expenses that disproportionately constrain smaller regional competitors.
- Extended Asset Lifecycles:Properly maintained SCBA units operate for fifteen to twenty years, limiting replacement frequency outside regulatory-forced turnover events.
Strategic Opportunities
- Biometric Telemetry Integration:Fire departments seek physiological monitoring capabilities that stream heart rate, breathing rate, and temperature data to incident commanders in real time.
- Industrial Emerging Markets:Petrochemical expansion along the US Gulf Coast and Middle Eastern energy corridors generates demand for specialized closed-circuit systems in hydrogen sulfide environments.
- Service Revenue Unbundling:Manufacturers can capture recurring revenue through predictive maintenance contracts, remote diagnostics, and cylinder exchange programs rather than unit sales alone.
Industry Challenges
- Technician Certification Shortage:Qualified SCBA repair technicians require specialized training on electronic monitoring systems, creating bottlenecks for field service expansion.
- Legacy System Interoperability:Departments with mixed-vendor fleets face integration failures when combining new NFPA 1981-compliant units with older communication systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Contained Breathing Apparatus (SCBA) Market |
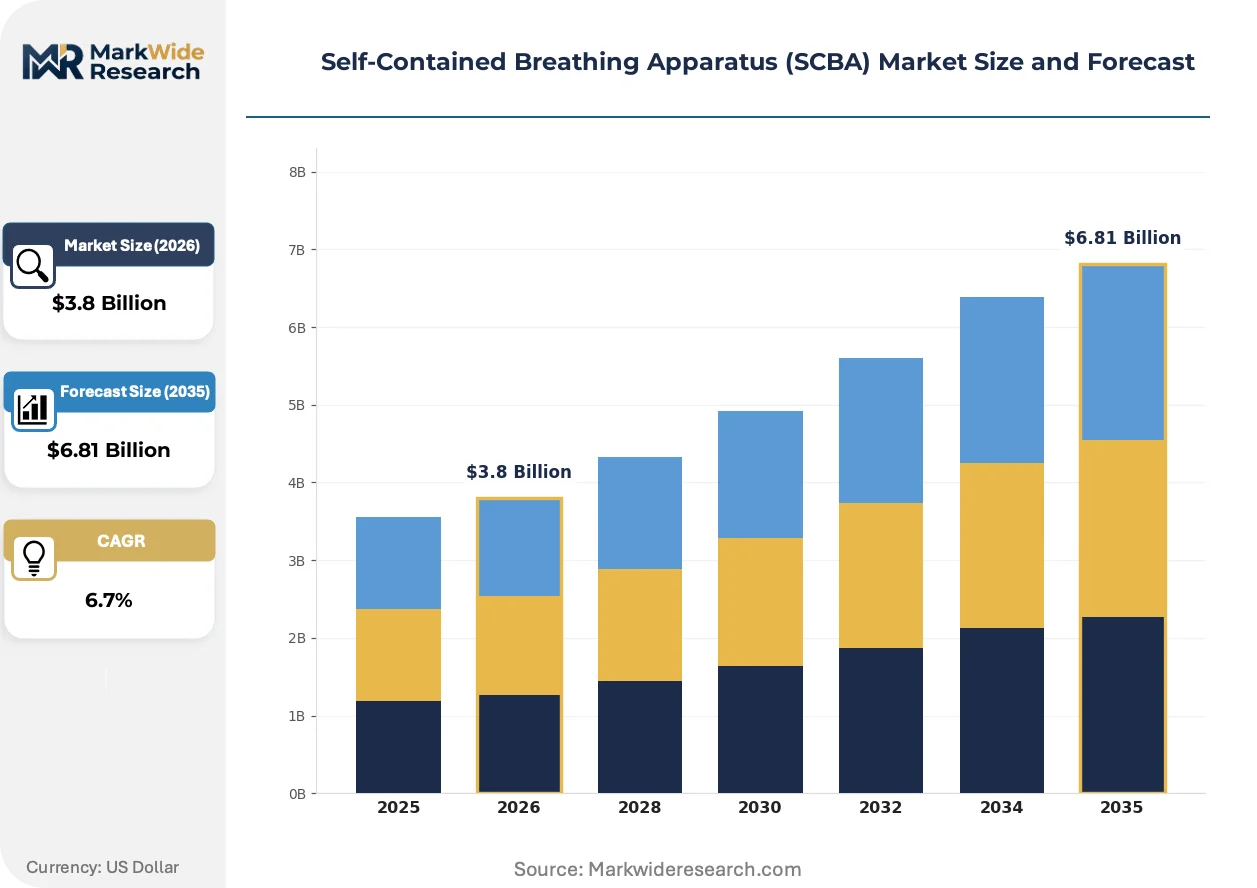
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open-Circuit, Closed-Circuit, Supplied Air, Modular End User: Firefighting Services, Industrial Sector, Emergency Rescuers, Military Application: Hazardous Material Handling, Fire Suppression, Search and Rescue, Confined Space Entry Technology: Composite Cylinders, Electronic Monitoring, Automatic Regulators, Low-Pressure Systems |
| Companies Covered | 3M Scott Fire & Safety, Interspiro, MSA Safety, Shigematsu Works Co., Ltd., Gentex Corporation, Honeywell International Inc., Avon Protection, Survivair, Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Contained Breathing Apparatus (SCBA) Market Evolving Landscape
Electronic monitoring systems are migrating from optional accessories to standard equipment, redefining baseline product specifications and compressing margins for basic open-circuit configurations.
Advanced pressure-demand regulators with reduced breathing resistance are supplanting conventional mechanical designs in premium municipal procurement tiers. Fire departments in California and Texas specify these systems for thermal stress mitigation during extended interior attack operations. The technology is supplanting mid-market offerings as NFPA 1981 performance benchmarks ratchet upward, collapsing price differentiation between historically separate product tiers.
OSHA respiratory protection standards now explicitly reference fit testing documentation requirements, compelling departments to adopt quantitative fit testing protocols over qualitative methods. Industrial end-users face audit exposure if testing records fail to demonstrate annual compliance. Manufacturing facilities in Ohio and Pennsylvania report the steepest compliance investment curves as regional enforcement intensifies.
Departments increasingly specify complete system interoperability rather than best-of-breed component procurement, consolidating vendor relationships and compressing multi-source maintenance complexity. Municipal buyers in Florida and Illinois now require mask-to-regulator compatibility across entire fleets, displacing fragmented supplier strategies. This concentration pattern favors integrated manufacturers with captive cylinder and electronics production over specialized component suppliers.
Self-Contained Breathing Apparatus (SCBA) Market Segmentation
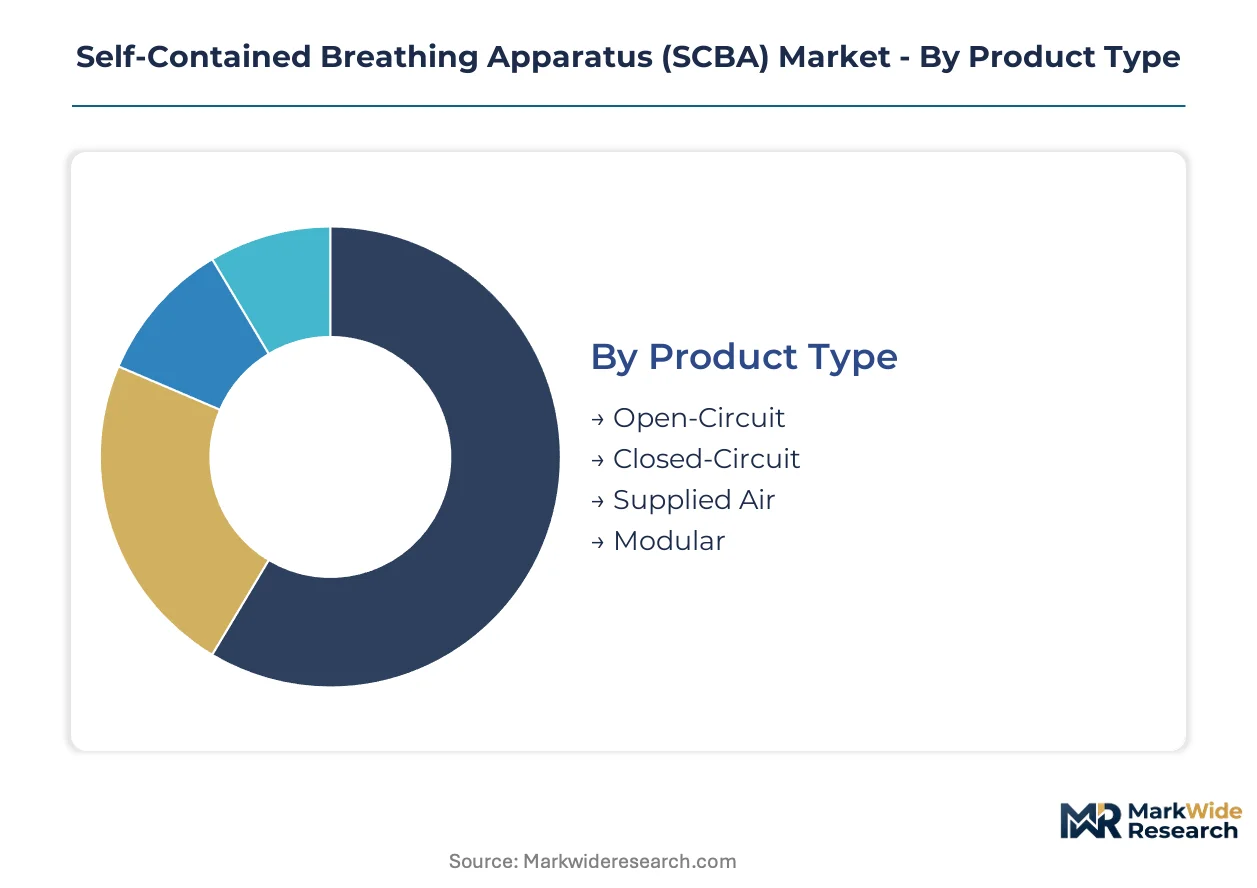
SCBA procurement channels diverge sharply across segment boundaries. Municipal fire departments route through cooperative purchasing agreements, while industrial buyers favor direct manufacturer relationships for confined space compliance programs.
Product Type:
Channel concentration varies by product complexity, with integrated systems flowing through specialized safety distributors and modular components reaching end-users via general industrial supply houses.
- Open-Circuit:Compressed air systems exhaust exhaled breath directly to atmosphere through a demand valve regulator and full-face mask assembly. Fire departments in Texas and California specify these units for interior attack operations where thermal stress and breathing resistance reduction dominate procurement criteria.
- Closed-Circuit:Rebreathing apparatuses recycle exhaled gas through chemical scrubbers, extending duration to four hours for mine rescue and military applications. European defense ministries and Middle Eastern petrochemical corridors generate concentrated demand for these systems in hydrogen sulfide environments.
- Supplied Air:Long-duration hose-fed configurations serve fixed-site industrial applications with established breathing air compressor infrastructure.
- Modular:Component-swappable platforms allow cylinder and mask interchangeability across fleet vintages, appealing to budget-constrained municipal buyers.
By volume, Open-Circuit leads. By growth pace, Closed-Circuit is ahead.
End User:
Cost tier stratification separates specification-grade municipal procurement from price-sensitive industrial maintenance programs.
- Firefighting Services:NFPA 1981-compliant systems with integrated PASS devices and telemetry accountability define the premium tier. Departments in Florida and Illinois now mandate complete fleet interoperability, consolidating vendor relationships around single-source suppliers.
- Industrial Sector:OSHA-mandated fit testing and hydrostatic inspection intervals sustain replacement cycles for petrochemical, pharmaceutical, and wastewater treatment facilities. Ohio and Pennsylvania manufacturing clusters report the steepest compliance investment curves as regional enforcement intensifies.
- Emergency Rescuers:Lightweight rapid-deployment configurations serve technical rescue and urban search and rescue teams requiring extended mobility.
- Military:Specialized closed-circuit systems for chemical, biological, radiological, and nuclear defense operate through dedicated defense procurement channels with extended qualification timelines.
Firefighting Services command the highest unit prices. Industrial Sector volumes expand most rapidly.
Application:
Volume concentration clusters in fire suppression, while margin expansion concentrates in specialized hazardous material operations requiring custom-configured respiratory protection.
- Hazardous Material Handling:Level A encapsulating suits with positive-pressure SCBA integration protect responders during chemical spill containment and clandestine laboratory entry. Gulf Coast petrochemical facilities and Port of Houston operations sustain specialized procurement for hydrogen sulfide and ammonia atmospheres.
- Fire Suppression:Interior structural attack remains the dominant volume application, with departments specifying reduced breathing resistance regulators for extended-duration operations under thermal stress.
- Search and Rescue:Collapsed structure and confined space operations demand lightweight configurations with integrated communication systems for prolonged victim extraction scenarios.
- Confined Space Entry:OSHA 1910.146 compliance drives recurring fit testing and equipment replacement for utility, construction, and maritime maintenance operations.
Fire Suppression dominates unit shipments. Hazardous Material Handling achieves the steepest margin expansion.
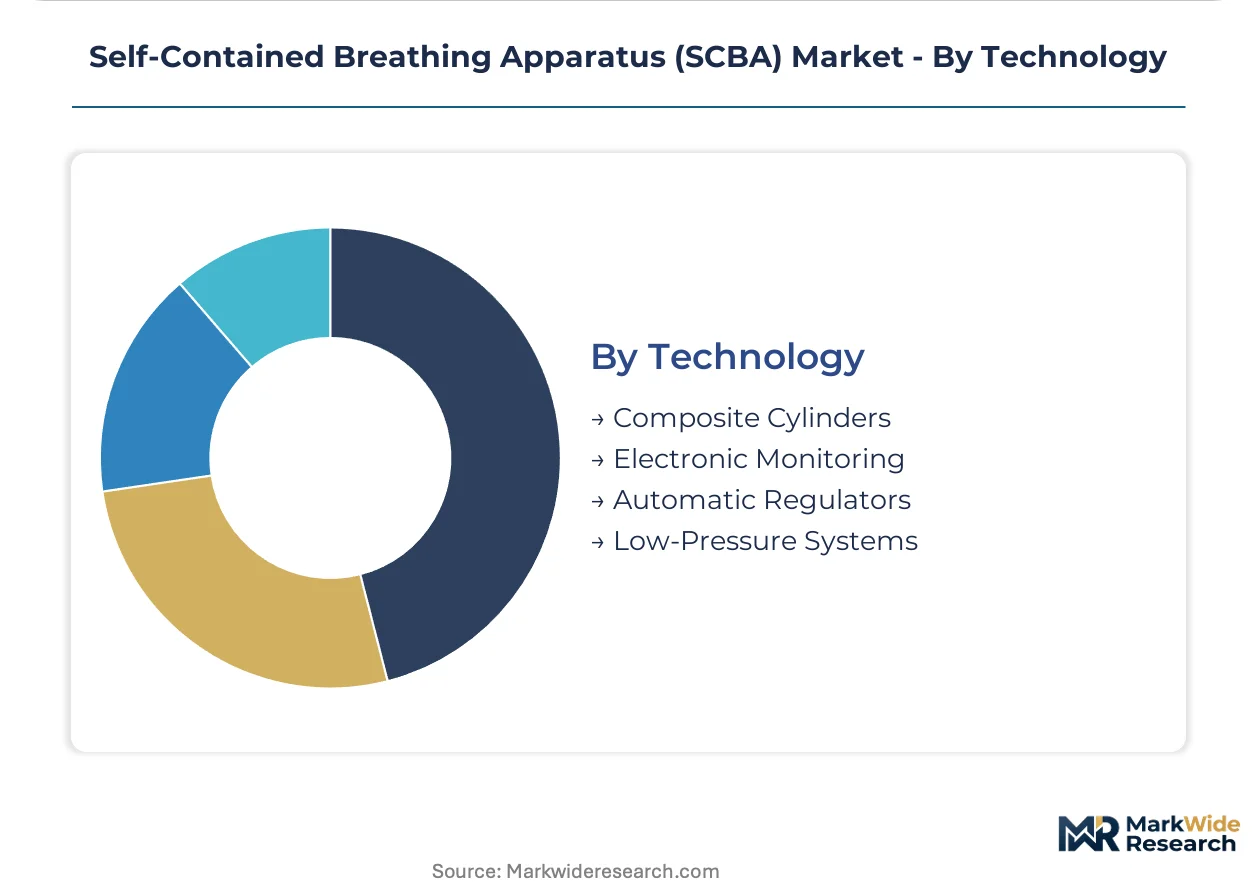
Technology:
Supply concentration in carbon fiber precursor manufacturing shapes cylinder technology adoption curves, while electronics integration redefines baseline product specifications.
- Composite Cylinders:Carbon fiber wrap over aluminum liners reduces weight by approximately one-third versus all-aluminum alternatives, improving mobility for extended operations. Japanese and South Korean precursor suppliers concentrate upstream capacity, exposing manufacturers to input volatility.
- Electronic Monitoring:Biometric telemetry systems stream heart rate, breathing rate, and temperature data to incident commanders, migrating from optional accessories to standard municipal specifications. This technology is compressing margins for basic open-circuit configurations.
- Automatic Regulators:Pressure-demand designs with reduced inhalation resistance supplant conventional mechanical regulators in premium procurement tiers.
- Low-Pressure Systems:Reduced cylinder pressure ratings extend duration through improved air consumption efficiency for specialized industrial applications.
Composite Cylinders lead in unit volume. Electronic Monitoring climbs the fastest as departments modernize aging fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and American SCBA manufacturers dominate export flows to Middle Eastern petrochemical buyers and Asian industrial markets. Supply chains route through Rotterdam and Houston distribution hubs before reaching end-user facilities.
United States
Municipal fire departments in Texas and California drive fleet modernization with NFPA 1981-compliant systems. OSHA enforces confined space respiratory protection standards across manufacturing facilities. Gulf Coast petrochemical clusters near Houston sustain specialized procurement for hydrogen sulfide environments.
Germany
Industrial safety demand concentrates in chemical manufacturing and automotive production corridors. CE marking under the EU Personal Protective Equipment Regulation shapes product compliance thresholds. The Ruhr industrial basin and Bavarian manufacturing zones anchor replacement cycles for cylinder hydrostatic testing programs.
China
Mining operations and petrochemical expansion generate demand for closed-circuit systems in hazardous atmospheres. GB standards and MIIT industrial safety directives define certification requirements. Yangtze River Delta manufacturing clusters invest in respiratory protection for semiconductor fabrication facilities.
Saudi Arabia
State-owned energy operators modernize respiratory protection inventories across downstream refining operations. The country's national industrial safety regulator mandates fit testing documentation for confined space entry. Eastern Province petrochemical cities sustain procurement for specialized closed-circuit configurations.
Japan
Disaster response agencies and nuclear decommissioning operations specify lightweight rapid-deployment configurations. METI industrial safety guidelines influence product specification benchmarks. Osaka-Kobe industrial corridors maintain replacement schedules for pharmaceutical and chemical manufacturing facilities.
Self-Contained Breathing Apparatus (SCBA) Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and geographic coverage. The market structure concentrates around integrated manufacturers with captive cylinder production and electronics capabilities. Three archetypes dominate: diversified industrial conglomerates with safety divisions, pure-play respiratory protection specialists, and defense-focused closed-circuit system providers. Consolidation activity targets regional distributors with municipal procurement relationships, while technology licensing agreements accelerate biometric telemetry adoption.
Within the integrated manufacturing tier, MSA Safety and Honeywell International Inc. exemplify scale-driven positioning through channel density and cooperative purchasing agreement penetration. Drägerwerk AG & Co. KGaA anchors European demand specialization. Japanese fabricators including Shigematsu Works Co., Ltd. occupy positions serving domestic industrial and disaster response procurement frameworks.
| Leading Market Players |
|---|
| 3M Scott Fire & Safety |
| Interspiro |
| MSA Safety |
| Shigematsu Works Co., Ltd. |
| Gentex Corporation |
| Honeywell International Inc. |
| Avon Protection |
| Survivair |
| Drägerwerk AG & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation agreements with Japanese carbon fiber precursor suppliers lock in both raw material access and cost visibility for SCBA manufacturers facing NFPA 1981 compliance deadlines. These contracts insulate integrated producers from spot-market volatility while forcing smaller competitors into higher-cost procurement channels.
Pricing Analysis
Current-generation electronic monitoring systems command a 40-50% premium over prior-generation mechanical configurations, while next-generation biometric telemetry platforms are compressing mid-tier pricing through feature migration. Three-tier pricing structure across NFPA 1981-certified premium, CE-marked standard, and economy industrial tiers separates municipal fire departments from price-sensitive maintenance contractors. Cost compression in basic open-circuit configurations is intensifying because electronic monitoring is becoming standard rather than optional. Industrial confined-space buyers exhibit the highest price sensitivity due to OSHA-mandated replacement cycles, while municipal fire departments prioritize interoperability over unit cost.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Busan and Yokohama to Long Beach have elevated inbound logistics costs for carbon fiber-wrapped cylinder assemblies. Manufacturing concentration in the United States, Germany, and Japan draws from Japanese and South Korean precursor suppliers for composite materials, Italian and German electronics specialists for telemetry modules, and domestic machine shops for regulator components. Single-source vulnerability in Toray and Teijin carbon fiber supply exposes producers to geopolitical disruption. Distribution runs through specialized safety distributors for municipal procurement and direct manufacturer relationships for industrial compliance programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SCBA incumbents face substitution pressure from integrated PPE platforms that bundle respiratory protection with thermal imaging and communications systems into single-vendor contracts.
For Market Incumbents: Secure captive cylinder production through backward integration into carbon fiber winding capabilities, eliminating precursor supply exposure while defending margin position against emerging Asian competitors. Consolidate service networks in Texas and California to capture recurring revenue from NFPA 1981-mandated fleet replacements before regional distributors establish maintenance footholds. For New Entrants and Emerging Players: Predictive maintenance software for legacy SCBA fleets represents an under-served service layer where incumbents prioritize new unit sales over aftermarket retention. Target municipal departments in Florida and Illinois with interoperability retrofit kits that bridge mixed-vendor fleets, using channel partnerships with cooperative purchasing agreements rather than direct sales investment. For Investors and Strategic Acquirers: Capital is best deployed toward regional distributors with established municipal procurement relationships and captive service technician networks, as these assets compound value through recurring inspection and cylinder exchange revenue. Watch for NFPA 1981 certification timeline announcements as the inflection signal determining replacement cycle acceleration or deferral.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cylinder Production | Captive carbon fiber winding capacity insulates margin from Japanese precursor supply volatility. |
| Biometric Telemetry Platform Launch | Electronic monitoring migration from accessory to standard specification redefines baseline product tiers. |
| Service Revenue Unbundling | Predictive maintenance contracts capture recurring revenue beyond unit sales in municipal procurement. |
| Cooperative Purchasing Agreement Penetration | Florida and Illinois consortiums consolidate vendor relationships around single-source suppliers. |
| Closed-Circuit System Certification | Middle Eastern petrochemical corridors demand specialized hydrogen sulfide configurations through extended qualification timelines. |
Research Methodology
Desk research of NFPA technical standards documentation, OSHA enforcement records, and EU PPE Regulation compliance databases preceded structured interviews with municipal fire chiefs, industrial safety directors, and SCBA service technicians. Primary fieldwork with procurement officers at cooperative purchasing agreements and distribution channel partners validated secondary findings from SEC filings of listed safety equipment manufacturers and customs trade data. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, end-user segment, application intensity, and technology generation informed the analytical framework over the projection horizon. Modeled dimensions included open-circuit versus closed-circuit architecture, firefighting versus industrial versus military end-use, fire suppression versus hazardous material handling application, and composite cylinder versus electronic monitoring technology. CAGRs were computed from segment-level growth trajectories with NFPA 1981 replacement cycle timing and OSHA enforcement intensity as primary industry-specific forecast inputs.
Forecasts assume regulatory continuity in NFPA 1981, OSHA 1910.134, and EU PPE Regulation regimes; material policy shifts would require re-modeling of replacement demand timing. Carbon fiber supply disruptions, municipal budget freezes, or accelerated composite cylinder material standard revisions represent specific risk factors that could revise forecast outputs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Emergency Showers Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market
Safety Equipment and Personal Protective Equipment (PPE)
Law Enforcement and Military Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Scuba Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Booster Seat Type Child Safety Seats Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market