
 Traffic Baton Market | 2026-2036
Traffic Baton Market Size, Share, and Industry Trends Forecast 2026-2036
Traffic Baton Market Analytics
Specialty police supply distribution is tilting toward direct manufacturer relationships as agencies consolidate procurement through state cooperative purchasing contracts. Streamlight Inc. leverages its established law enforcement brand recognition to sustain premium positioning in the rechargeable segment. Bayco Products Inc. anchors its competitive stance through specialized traffic safety catalogs that reach municipal buyers. Wenzhou SWIN Traffic Facility Co., Ltd. competes on manufacturing scale, occupying the value tier for conventional baton variants.
A traffic baton is a handheld signaling device, typically constructed from polycarbonate or ABS housing with LED arrays exceeding 200 lumens, designed to direct vehicular and pedestrian flow in low-visibility conditions. The product serves critical safety functions for traffic officers, construction zone flaggers, and emergency scene perimeter control. LED technology leads product type segmentation due to energy efficiency and extended operational lifespan, while solar-powered variants represent the fastest-growing technology segment as agencies pursue off-grid capability. The law enforcement end user category commands the largest volume share, though emergency responder procurement is expanding fastest as fire departments integrate traffic control into incident command protocols.
NHTSA Federal Motor Vehicle Safety Standards influence minimum visibility specifications, while OSHA workplace regulations mandate reflective equipment for construction zone personnel, directly shaping product certification requirements. The EU CE marking framework and REACH substance restrictions affect export-bound manufacturers, particularly those based in Wenzhou's production cluster. Stakeholders must monitor evolving battery transport regulations and state-level sustainable procurement mandates that will determine competitive access across North American and European public sector channels.
Market Dynamics
LED lumen efficiency thresholds mandated by NHTSA Federal Motor Vehicle Safety Standards are forcing municipal procurement departments to retire incandescent baton inventories ahead of normal replacement cycles, compressing demand into a concentrated upgrade window.
Growth Catalysts
- OSHA Construction Zone Mandates:Workplace safety regulations require enhanced reflective signaling equipment for highway work crews, expanding the addressable buyer base beyond law enforcement into infrastructure maintenance sectors.
- Solar Cell Efficiency Gains:Photovoltaic integration into baton housings enables off-grid deployment for rural traffic control and emergency response scenarios without tethered charging infrastructure.
- State Cooperative Purchasing:Consolidated procurement vehicles across municipal police departments aggregate volume demand, reducing per-unit acquisition costs and accelerating replacement timelines.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell manufacturing concentrates in East Asian production clusters, exposing North American and European assemblers to raw material cost volatility and logistics disruption.
- Polycarbonate Resin Pricing:Petroleum-derived housing materials face input cost pressure from upstream chemical feedstock fluctuations, squeezing margin structures for mid-tier manufacturers.
- Incumbent Equipment Longevity:Legacy halogen batons in municipal inventories exhibit extended functional lifespans, delaying replacement cycles despite superior LED performance specifications.
Strategic Opportunities
- Fire Department Integration:Emergency responder agencies are incorporating traffic perimeter control into incident command protocols, opening a procurement channel with distinct specification requirements from police buyers.
- EU Green Deal Procurement:Sustainable purchasing mandates across European public sectors favor rechargeable and solar-powered variants, creating preference premiums for certified low-carbon equipment.
- Connected Baton Development:Convergence of LED arrays with Bluetooth beacon technology enables real-time location tracking and synchronization with smart city traffic management systems.
Industry Challenges
- IP54-to-IP67 Certification Gaps:Achieving full dust and immersion protection ratings requires specialized sealing engineering that extends product development timelines by 8-14 months.
- Multi-Jurisdiction Compliance:Simultaneous satisfaction of NHTSA visibility standards, OSHA workplace rules, and EU CE marking requirements demands redundant testing protocols that inflate certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traffic Baton Market |
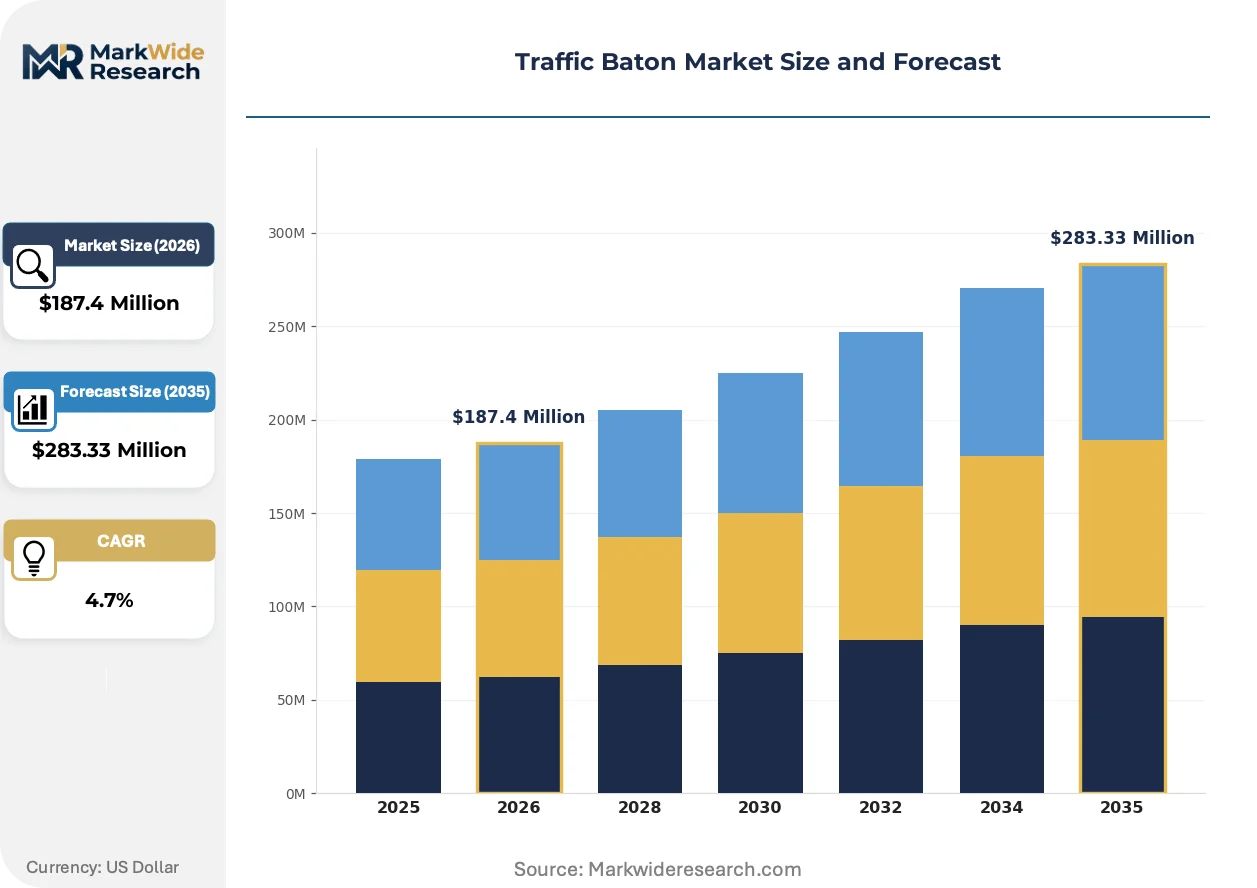
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $283.33 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Lighted, Conventional, Rechargeable End User: Law Enforcement, Traffic Control, Security Services, Emergency Responders Technology: Solar-Powered, Battery-Operated, Manual, Wireless Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Streamlight Inc., Bayco Products Inc., Wenzhou SWIN Traffic Facility Co., Ltd., Pelican Products Inc., Nightstick, Wenzhou Boshi Electric Technology Co., Ltd., EcoGear FX, Nite Ize, Inc., Wenzhou Xiangying Reflective Material Science & Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traffic Baton Market Evolving Landscape
Traffic baton technology is virtualizing around solid-state illumination and embedded connectivity, displacing mechanical switching and passive reflectivity as the dominant design paradigms across public safety procurement.
Programmable LED array controllers are virtualizing the traditional fixed-beam baton architecture. Municipal police departments in the United States are specifying addressable RGB systems that switch between amber warning and red stop signals via software rather than mechanical filters. This virtualization is compressing SKU proliferation by enabling single-hardware platforms to serve multiple traffic control functions through firmware configuration.
REACH substance restrictions enforced by ECHA are eliminating specific flame-retardant additives from polycarbonate housing formulations. European manufacturers must reformulate resin compounds to maintain impact resistance without restricted halogenated compounds. German traffic safety equipment distributors are accelerating supplier qualification audits to ensure batch-level compliance documentation accompanies every shipment.
Direct manufacturer engagement is displacing traditional police supply distributors for volume municipal contracts. State cooperative purchasing agreements aggregate demand from hundreds of departments, enabling buyers to bypass regional distributors and negotiate factory-direct pricing. California and Texas procurement consortia exemplify this channel compression, with specifications written around manufacturer certification rather than distributor stocking requirements.
Traffic Baton Market Segmentation
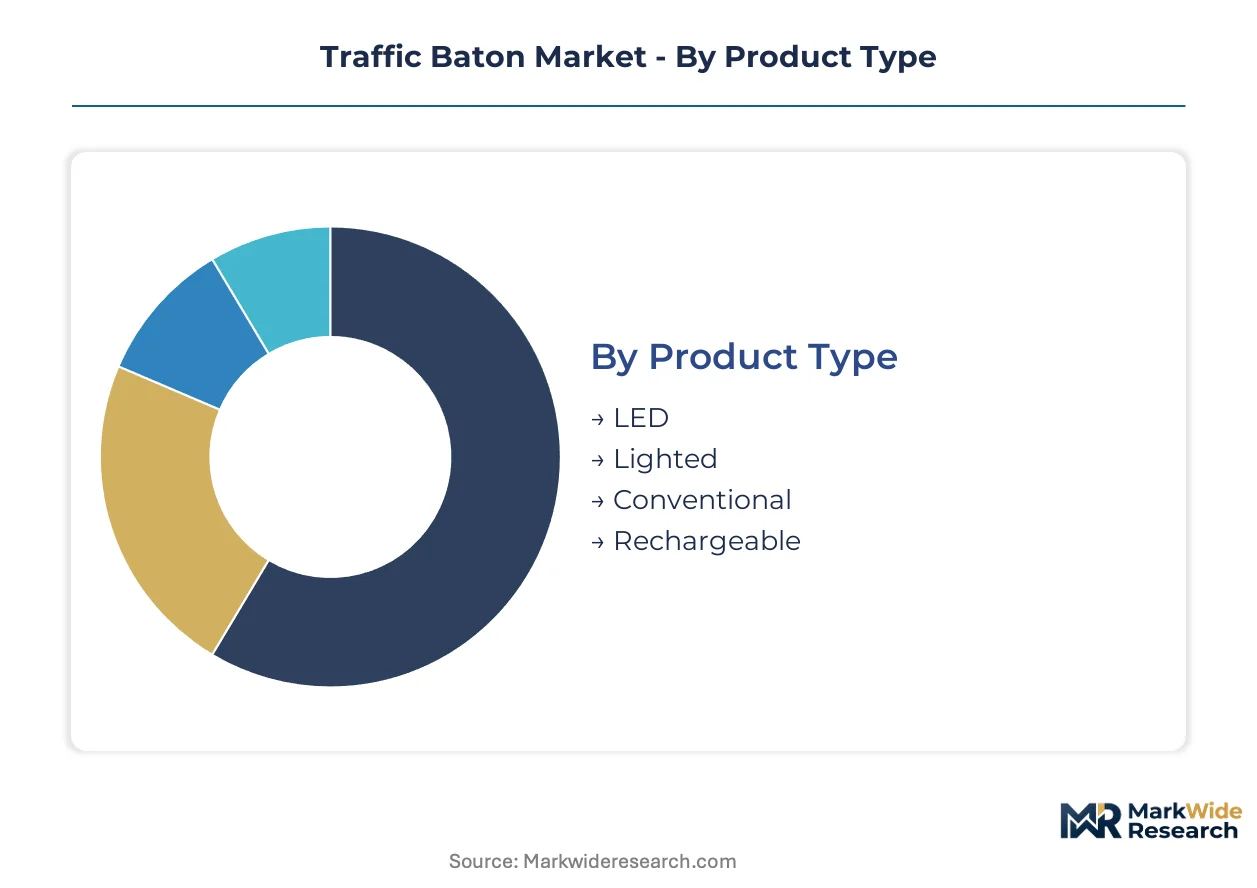
Traffic baton procurement patterns diverge sharply across user workflows and operational environments. Segment boundaries determine specification requirements, certification burdens, and channel economics for manufacturers serving public safety agencies.
Product Type:
LED technology anchors the mature core while rechargeable architectures reshape replacement economics.
- LED:Solid-state illumination arrays exceeding 200 lumens dominate municipal specifications under NHTSA visibility mandates. Police departments in Texas and California aggregate demand through state cooperative contracts, compressing pricing for conventional incandescent alternatives.
- Rechargeable:Lithium-ion cell integration eliminates disposable battery logistics for high-rotation traffic units. German federal police procurement now specifies minimum 500-cycle battery endurance, filtering out nickel-metal hydride legacy designs.
- Lighted:Electroluminescent and chemiluminescent variants serve backup and disaster-kit applications where electrical failure is probable.
- Conventional:Passive reflector and incandescent bulb designs persist in budget-constrained rural jurisdictions with extended equipment amortization horizons.
LED retains volume leadership; rechargeable holds the steepest expansion curve.
End User:
Specification authority concentrates with agencies holding statutory traffic control jurisdiction.
- Law Enforcement:Municipal police departments specify programmable beam patterns, weapon-mount compatibility, and evidence-chain documentation. NHTSA highway safety grants fund equipment modernization across state patrol organizations.
- Emergency Responders:Fire departments integrate traffic perimeter control into incident command protocols, requiring batons with extrication-scene durability and mutual-aid interoperability.
- Traffic Control:Construction zone flaggers operate under OSHA workplace mandates requiring minimum reflective performance and weather-sealed housings.
- Security Services:Private parking enforcement and event security prioritize cost minimization over multi-function capability, accepting simpler mechanical switch designs.
Law enforcement commands procurement volume; emergency responders are expanding most quickly as fire service protocols evolve.
Technology:
Power architecture determines deployment flexibility and total cost of ownership across operating environments.
- Solar-Powered:Photovoltaic integration enables off-grid deployment for rural traffic control and emergency response without tethered charging infrastructure. Australian road maintenance agencies specify solar variants for remote highway segments beyond electrical grid access.
- Battery-Operated:Removable cell designs dominate high-frequency urban applications where rapid field replacement outweighs recharge cycle convenience.
- Manual:Kinetic and unpowered mechanical designs serve disaster preparedness stockpiles and regulatory compliance backup requirements.
- Wireless:Bluetooth beacon integration enables synchronization with smart city traffic management systems, though certification complexity delays commercial rollout.
Battery-operated systems retain installed base dominance; solar-powered configurations gain share fastest in infrastructure-deficient geographies.
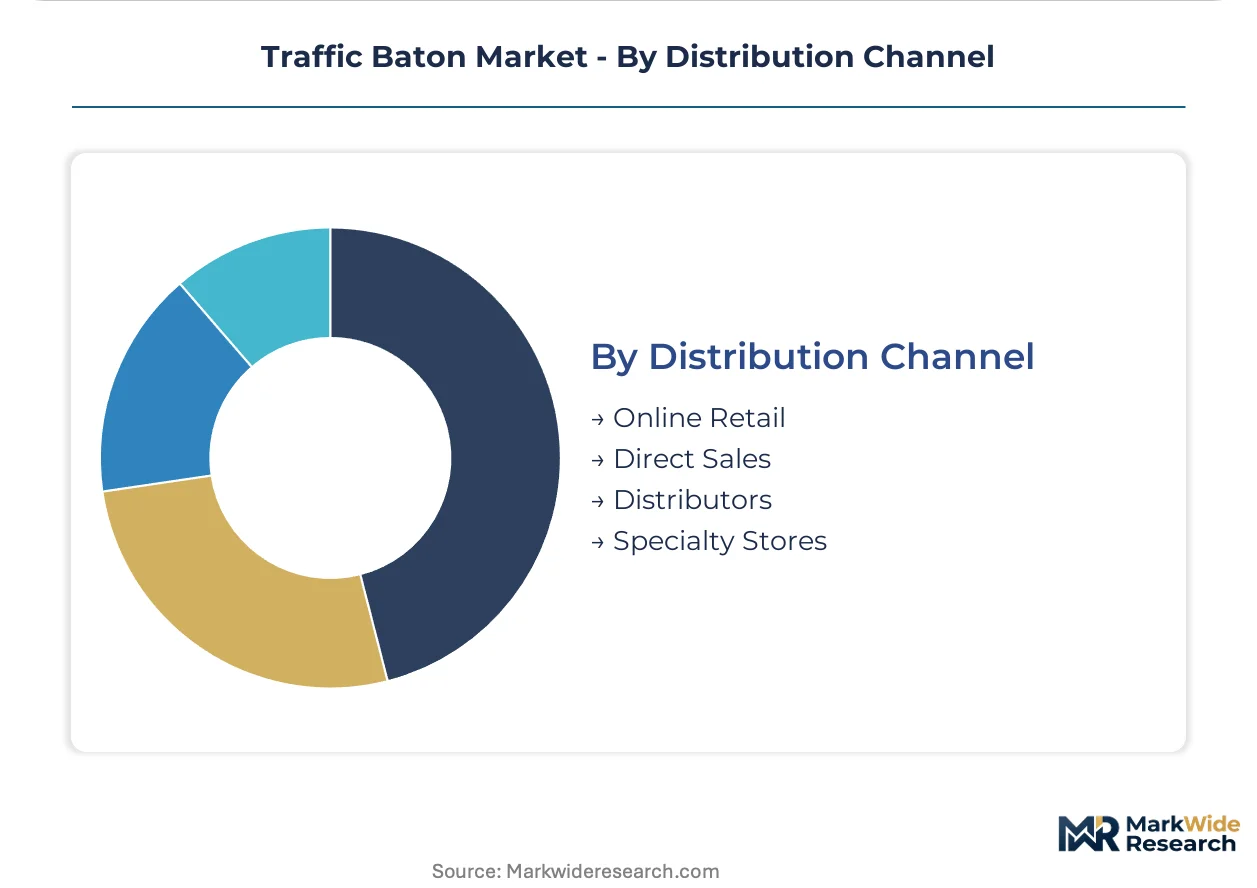
Distribution Channel:
Channel structure is compressing as procurement authority centralizes above the departmental level.
- Direct Sales:State cooperative purchasing agreements aggregate demand from hundreds of departments, enabling factory-direct negotiation bypassing regional distributors. California and Texas consortia write specifications around manufacturer certification rather than distributor stocking.
- Distributors:Specialty police supply houses retain relevance for smaller departments outside cooperative contract coverage and for emergency replacement orders.
- Online Retail:E-commerce penetration concentrates in private security and individual officer purchases below formal procurement thresholds.
- Specialty Stores:Brick-and-mortar public safety equipment retailers serve immediate-need replacement and hands-on specification comparison for smaller agencies.
Direct sales capture volume leadership; online retail climbs fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with North American municipal procurement offices while Chinese manufacturing clusters compete on unit economics. German distributors extract certification premiums for REACH-compliant equipment. Australian road agencies pay freight-adjusted premiums for solar-powered variants suited to remote highway segments.
United States
Municipal police departments in Texas and California drive volume through state cooperative purchasing agreements that aggregate demand from hundreds of agencies. NHTSA Federal Motor Vehicle Safety Standards mandate minimum lumen output, forcing accelerated replacement of incandescent inventories. Streamlight Inc. leverages its law enforcement brand recognition to sustain premium positioning in rechargeable segments.
Germany
Federal police procurement specifies minimum 500-cycle battery endurance, filtering out nickel-metal hydride legacy designs. REACH substance restrictions enforced by ECHA eliminate specific flame-retardant additives from polycarbonate housing formulations. German traffic safety equipment distributors accelerate supplier qualification audits to ensure batch-level compliance documentation accompanies every shipment.
China
Wenzhou's production cluster anchors manufacturing scale for conventional baton variants serving export markets. Domestic demand concentrates with municipal traffic bureaus modernizing equipment under smart city initiatives. Wenzhou SWIN Traffic Facility Co., Ltd. and Wenzhou Boshi Electric Technology Co., Ltd. occupy the value tier through specialized traffic safety catalogs.
Australia
Road maintenance agencies specify solar-powered variants for remote highway segments beyond electrical grid access. State-level sustainable procurement mandates favor rechargeable equipment with documented carbon footprints. Photovoltaic integration enables off-grid deployment for rural traffic control without tethered charging infrastructure.
Canada
Provincial police services modernize equipment through federal highway safety grants administered by Transport Canada. Health Canada and PMRA regulate battery transport and disposal for lithium-ion powered devices. Ontario and Quebec procurement consortia write specifications around manufacturer certification rather than distributor stocking requirements.
Traffic Baton Market Competitive Landscape
Established law enforcement suppliers and specialized traffic safety fabricators split the market along brand-recognition versus manufacturing-scale vectors. The vendor base concentrates into three strategic archetypes: premium-brand incumbents with rechargeable portfolios, value-tier manufacturers exploiting Wenzhou production clusters, and diversified safety equipment conglomerates with cross-category leverage. Competitive moves center on direct manufacturer engagement through state cooperative purchasing and REACH-compliant resin reformulation for European market access.
Within the premium-brand tier, Streamlight Inc. and Pelican Products Inc. exemplify law enforcement-focused positioning built on established agency relationships. Bayco Products Inc. anchors the specialized traffic safety catalog segment reaching municipal buyers outside cooperative contract coverage. Wenzhou SWIN Traffic Facility Co., Ltd. represents the scale-driven manufacturing archetype competing on unit economics for conventional variants. Nightstick and Nite Ize, Inc. occupy mid-market positions between premium certification and value-tier pricing.
| Leading Market Players |
|---|
| Streamlight Inc. |
| Bayco Products Inc. |
| Wenzhou SWIN Traffic Facility Co., Ltd. |
| Pelican Products Inc. |
| Nightstick |
| Wenzhou Boshi Electric Technology Co., Ltd. |
| EcoGear FX |
| Nite Ize, Inc. |
| Wenzhou Xiangying Reflective Material Science & Technology Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Wenzhou's polycarbonate resin and LED component manufacturing cluster anchors upstream supply, concentrating margin capture with North American municipal procurement offices that aggregate volume through state cooperative contracts. Battery cell sourcing from East Asian production hubs exposes assemblers to raw material cost volatility that compresses mid-tier manufacturer margins.
Pricing Analysis
Configured-to-order pricing for programmable RGB batons with NHTSA-certified lumen output commands substantial premiums over standard fixed-beam variants. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and battery cycle endurance. Cost compression in the economy tier is intensifying because petroleum-derived housing materials face upstream chemical feedstock fluctuations. Private security services exhibit highest price sensitivity, while municipal police departments prioritize specification compliance over unit cost.
Supply Chain Analysis
Supplier-financing through extended payment terms has become table stakes for Wenzhou-based manufacturers competing for North American municipal contracts. Production concentrates in China, South Korea, and Taiwan for LED arrays, lithium-ion cells, and polycarbonate resins. The supply chain draws from petroleum-derived housing materials, solid-state illumination components, and rechargeable battery architectures. Single-source vulnerability in East Asian battery cell manufacturing exposes assemblers to logistics disruption. Distribution runs through direct manufacturer engagement for volume contracts and specialty police supply distributors for smaller departmental orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
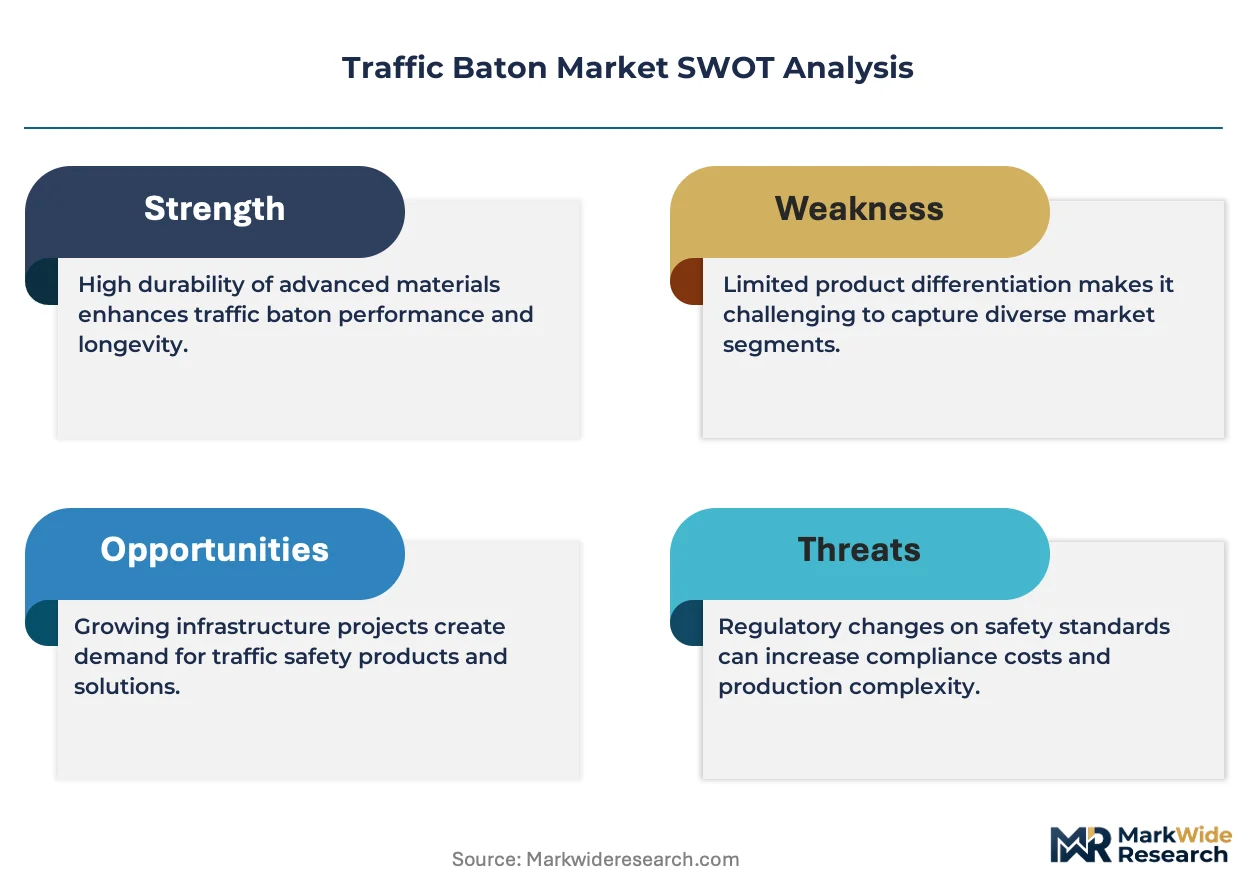
This market operates as a defensive-moat story where NHTSA certification entrenchment creates high switching costs for municipal procurement departments locked into specification-compliant suppliers.
For Market Incumbents: Pre-empt competitive erosion by deepening backward integration into LED driver circuitry and battery management systems to capture margin pools currently flowing to East Asian component suppliers. Secure exclusive supplier status with California and Texas procurement consortia before REACH-compliant European entrants achieve NHTSA certification parity. For New Entrants and Emerging Players: Establish a beachhead in fire department emergency responder procurement, where incident command protocol integration requirements differ from police specifications and incumbent brand loyalty remains weaker. Target solar-powered variants for Australian road maintenance agencies, where off-grid deployment needs and sustainable procurement mandates favor specialized entrants over conventional law enforcement suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier manufacturers with established Wenzhou production scale and pending NHTSA certification completion, positioned to arbitrage the upgrade window as municipal departments retire incandescent inventories. Monitor German federal police procurement specifications for battery endurance thresholds as the inflection indicator for European regulatory convergence with North American visibility standards.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Resin Reformulation | ECHA substance restrictions eliminate halogenated flame retardants, forcing polycarbonate housing reformulation for European market access. |
| State Cooperative Contracting | California and Texas procurement consortia aggregate demand from hundreds of departments, compressing channel margins and favoring direct manufacturer relationships. |
| Solar Cell Integration | Photovoltaic embedding enables off-grid deployment for rural traffic control and emergency response scenarios beyond electrical infrastructure. |
| Bluetooth Beacon Convergence | Connected baton development synchronizes LED arrays with smart city traffic management systems, opening software-recurring revenue streams. |
| IP67 Certification Investment | Full dust and immersion protection ratings extend product development timelines but unlock construction zone procurement under OSHA workplace mandates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal procurement officers, police equipment specialists, and traffic safety distributors; and secondary validation through NHTSA Federal Motor Vehicle Safety Standards documentation, OSHA workplace regulation filings, and state cooperative purchasing contract databases. The research triangulated bottom-up unit demand from departmental replacement cycles with top-down market sizing from public sector equipment budgets.
Forecast inputs considered LED technology adoption curves, rechargeable battery replacement economics, and solar-powered variant penetration across infrastructure-deficient geographies. Segmentation dimensions modeled include product architecture, power source technology, end-user jurisdiction, and distribution channel structure. CAGRs were derived from replacement cycle compression effects and regulatory mandate timing across the projection horizon.
Stress conditions across lithium-ion supply disruption, polycarbonate resin price volatility, and municipal budget contraction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about NHTSA enforcement consistency and state grant funding continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Wearable Airbag Belt Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Protection Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Explosion Proof Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market