
 North America Biometrics in Government Market | 2026-2036
North America Biometrics in Government Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biometrics in Government Market Analytics
Border control and national security deployments is broadening faster than traditional criminal identification systems. IDEMIA leverages its civil and criminal biometric database integration to anchor large-scale federal contracts. Thales Group sustains technology leadership through multimodal platform specialization across face and iris recognition. NEC Corporation competes aggressively on fingerprint matching speed and accuracy benchmarks for law enforcement agencies.
North America biometrics in government encompasses automated identity verification systems that capture, process, and match physiological characteristics against enrolled templates using ISO/IEC 19795-compliant accuracy thresholds, primarily to secure citizen services, border crossings, and criminal justice workflows. Fingerprint recognition retains the largest installed base among technology segments due to decades of FBI IAFIS infrastructure and state motor vehicle agency enrollment, while face recognition represents the fastest-expanding category driven by touchless authentication mandates and NIST FRVT performance improvements. Integration services command the deepest margin pools within service type segments because agencies prioritize vendor accountability for stitching legacy AFIS, new cloud platforms, and mobile capture devices into unified architectures.
The FBI's Criminal Justice Information Services division, NIST, and DHS all enforce biometric performance and interoperability standards that determine vendor eligibility for federal procurement vehicles. State-level REAL ID compliance deadlines and TSA checkpoint modernization timelines create synchronized demand waves across motor vehicle departments and airport authorities. Stakeholders must monitor NIST test protocol evolutions and state procurement consolidation trends to anticipate which technology configurations will dominate the next federal funding cycle.
Market Dynamics
The REAL ID Act modernization is synchronizing demand across motor vehicle departments, airports, and federal facilities, forcing vendors to recalibrate enrollment system architectures for multimodal biometric capture.
Growth Catalysts
- DHS Border Modernization Mandates:Federal agencies are expanding touchless biometric corridors at land, sea, and air ports of entry, requiring iris and facial recognition infrastructure at unprecedented scale.
- California Motor Vehicle Agency Consolidation:State-level REAL ID compliance deadlines are triggering synchronized procurement waves across the largest DMV systems in the United States.
- Contactless Authentication Protocols:Post-pandemic operational requirements have permanently shifted preference toward face and iris modalities over fingerprint capture in high-throughput environments.
Market Restraints
- Silicon Supply Concentration:Specialized image sensors and edge AI processors for biometric terminals face sourcing bottlenecks from concentrated East Asian foundry capacity.
- NIST Certification Timelines:Extended facial recognition vendor test cycles create 18-24 month procurement delays for agencies awaiting FRVT accuracy validation.
- Privacy Litigation Exposure:State biometric privacy statutes, particularly Illinois BIPA, impose uncapped statutory damages that chill deployment enthusiasm among risk-averse municipalities.
Strategic Opportunities
- Texas Border Corridor Expansion:The US-Mexico border region presents concentrated demand for integrated land-port and remote surveillance biometric networks.
- Mobile Enrollment Convergence:Cloud-based biometric platforms paired with hardened tablets are displacing fixed-terminal architectures for field-based law enforcement.
- Interoperability Standards Acceleration:FBI CJIS division mandates for multi-agency template sharing are opening integration service contracts for legacy AFIS modernization.
Industry Challenges
- Cross-Agency Template Harmonization:FBI, DHS, and state criminal repositories operate incompatible biometric data formats, forcing vendors to maintain multiple encoding pipelines.
- Algorithmic Bias Certification:NIST demographic differential testing requirements demand continuous model retraining that strains R&D budgets and extends product cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biometrics in Government Market |
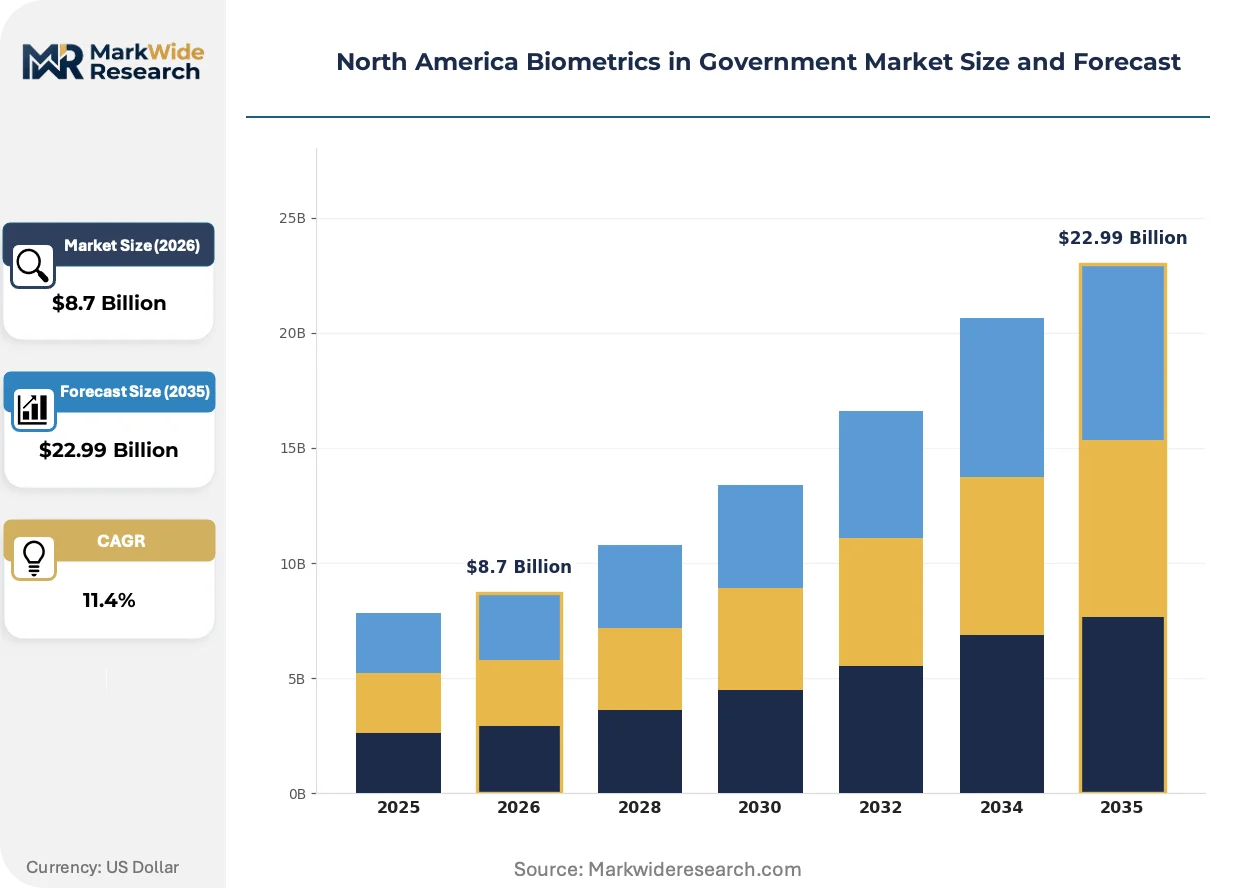
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Border Control, National Security, Criminal Identification, Voter Registration Technology: Face Recognition, Fingerprint Recognition, Iris Recognition, Voice Recognition End User: Federal Agencies, State Governments, Local Authorities, Law Enforcement Service Type: Integration Services, Maintenance Services, Support Services, Consulting Services |
| Companies Covered | IDEMIA, Thales Group, NEC Corporation, Aware Inc., M2SYS Technologies, HID Global Corporation, BIO-key International, Fujitsu, Innovatrics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biometrics in Government Market Evolving Landscape
Touchless multimodal architectures are displacing legacy fingerprint-centric systems across federal and state agencies, with cloud-native platforms compressing deployment timelines and enabling real-time cross-jurisdictional matching.
Edge-based facial recognition with on-device template generation is rewriting procurement specifications for border checkpoints and airport terminals. CBP is field-testing these systems at select land ports to reduce bandwidth dependency and latency. The technology is compressing infrastructure requirements for remote locations lacking fiber connectivity.
NIST FRVT accuracy benchmarks are tightening vendor eligibility for federal procurement vehicles, with performance thresholds now mandatory for DHS and FBI solicitations. Vendors failing demographic parity standards face automatic disqualification regardless of overall accuracy metrics. State motor vehicle departments are adopting these same thresholds to preempt federal compliance audits.
Subscription-based biometric platform licensing is displacing perpetual software purchases across state and local agencies. California and Texas DMVs have shifted to annual consumption models that bundle algorithm updates, cloud storage, and integration support. This reconfiguration is most visible in mid-sized agencies lacking dedicated biometric IT staff.
North America Biometrics in Government Market Segmentation
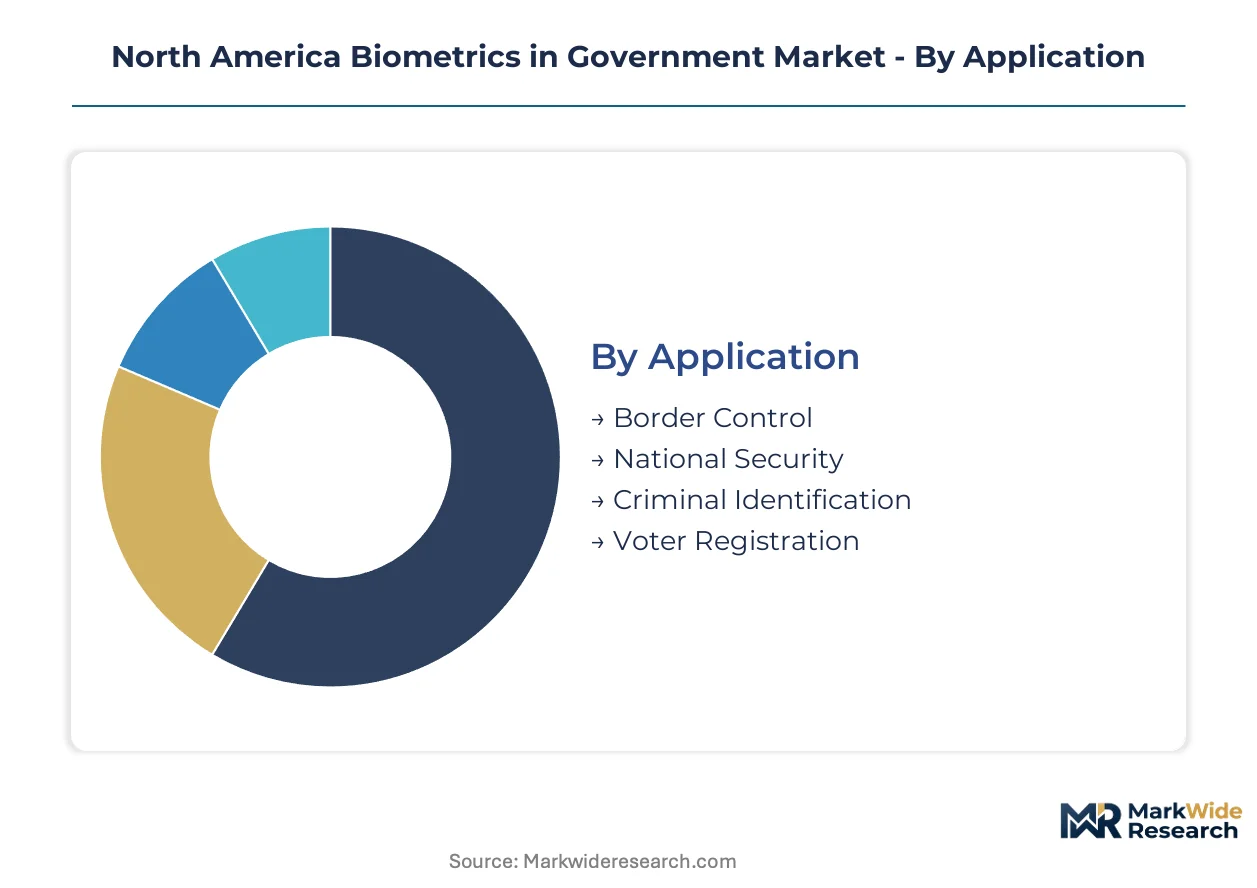
Segmentation in North America biometrics in government reveals how procurement priorities diverge across security mandates, technology readiness, and interagency coordination requirements. Each dimension carries distinct vendor qualification barriers and funding cycle timing.
Application:
Standardized federal mandates dominate high-volume deployments, while customized state-level implementations create fragmentation in system architectures and data formats.
- Border Control:Multimodal biometric corridors at land, sea, and air ports of entry require ISO/IEC 19795-compliant accuracy thresholds. Demand concentrates along the US-Mexico border corridor where CBP modernization timelines synchronize procurement waves across Texas and California land ports.
- National Security:Classified facility access and intelligence community identity management demand higher-assurance biometric modalities with specialized liveness detection. Federal agencies prioritize vendors with existing security clearances and CJIS integration experience.
- Criminal Identification:FBI IAFIS infrastructure and state AFIS networks maintain fingerprint-centric enrollment with gradual multimodal expansion.
- Voter Registration:State motor vehicle department linkages to election systems drive biometric enrollment for REAL ID-compliant identity verification.
Most installed capacity flows through Criminal Identification. Expansion is steepest in Border Control.
Technology:
Cost tiers separate legacy infrastructure investments from next-generation touchless deployments, with price-performance ratios determining replacement velocity.
- Face Recognition:Touchless capture architectures process facial geometry through NIST FRVT-validated algorithms for 1:N identification at distance. Post-pandemic operational requirements in California and Texas DMVs accelerate displacement of fingerprint-centric enrollment terminals.
- Fingerprint Recognition:Decades of FBI IAFIS and state motor vehicle agency infrastructure create the largest installed base of enrolled templates. Legacy AFIS modernization contracts prioritize interoperability with existing ten-print and latent matching systems.
- Iris Recognition:High-accuracy capture at distance supports border corridor applications with harsh environmental conditions.
- Voice Recognition:Telephone-based authentication and remote identity verification expand in federal benefit distribution programs.
Fingerprint Recognition retains the deepest template archives. Face Recognition is gaining share fastest among new procurements.
End User:
Customer type determines procurement vehicle access, with federal indefinite-delivery contracts requiring distinct vendor scale compared to state RFP processes.
- Federal Agencies:DHS, FBI, and State Department operations specify multimodal platforms with classified interoperability protocols. NIST certification and CJIS security compliance create vendor prequalification barriers that consolidate contract awards to established integrators.
- State Governments:Motor vehicle departments and benefit administration agencies drive synchronized demand waves around REAL ID compliance deadlines. California and Texas DMVs issue the largest state-level biometric procurement contracts.
- Local Authorities:County jails and municipal benefit offices deploy smaller-scale biometric enrollment with subscription-based platform licensing.
- Law Enforcement:Mobile biometric capture for field identification prioritizes ruggedized tablets with offline template matching capability.
Federal Agencies command the largest individual contract values. State Governments generate the highest aggregate procurement volume.
Service Type:
Margin concentration follows accountability risk, with integration services bearing full system performance responsibility compared to discrete maintenance transactions.
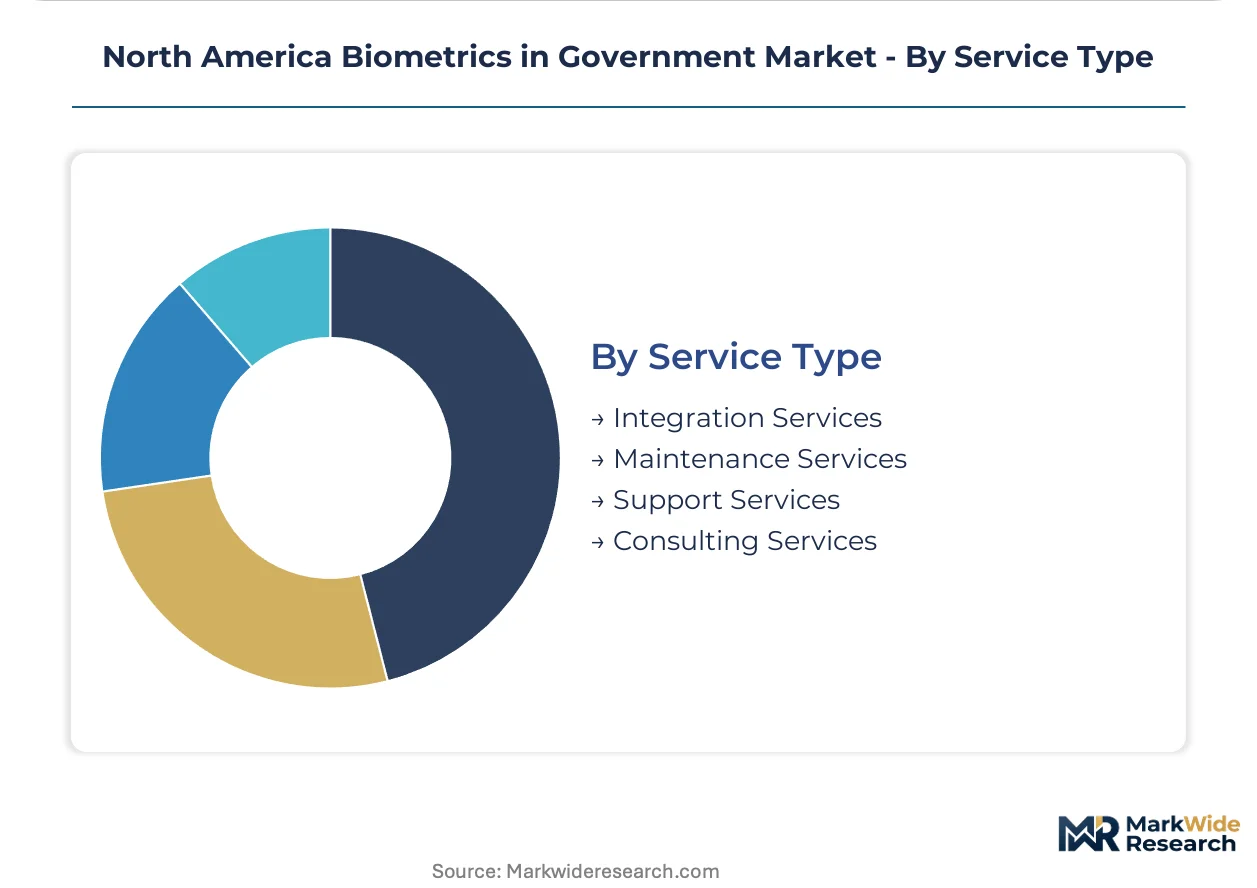
- Integration Services:Vendors stitch legacy AFIS, cloud-native platforms, and mobile capture devices into unified architectures with single-source accountability. FBI CJIS mandates for multi-agency template sharing expand contract scope for legacy system modernization.
- Maintenance Services:Algorithm updates, sensor recalibration, and template database optimization sustain system accuracy over operational lifecycles.
- Support Services:Help desk operations and field technician dispatch address operational disruptions in 24/7 border and law enforcement environments.
- Consulting Services:Biometric policy development and privacy impact assessments guide agencies through Illinois BIPA compliance and state statutory requirements.
Integration Services capture the deepest margin pools. Consulting Services are climbing the fastest as privacy litigation exposure intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US-Mexico border corridor anchors North American biometric procurement, with federal modernization timelines synchronizing demand waves across land ports, airports, and motor vehicle departments. DHS checkpoint expansion and REAL ID compliance deadlines concentrate investment in Texas, California, and Arizona sub-regions.
United States
CBP biometric corridors at land ports of entry drive multimodal infrastructure deployment along the southwestern border. The REAL ID Act modernization mandates synchronize procurement across state motor vehicle departments and TSA checkpoints. California DMV systems and Texas border ports generate the largest concentrated demand volumes.
Canada
Integrated border entry systems with US preclearance facilities expand biometric enrollment at Toronto Pearson and Vancouver International airports. The Canadian Border Services Agency coordinates with DHS on compatible facial recognition standards for cross-border travel corridors. Ontario and British Columbia concentrate federal-provincial procurement for enhanced driver's license programs.
Mexico
Northbound migration management and cargo security priorities expand biometric capture at Tijuana, Ciudad Juárez, and Nuevo Laredo border crossings. Mexican customs administration coordinates infrastructure compatibility with CBP systems under bilateral security frameworks. Baja California and Chihuahua states anchor northern border corridor investment clusters.
California
The state's motor vehicle department consolidation triggers synchronized multimodal enrollment system replacements across DMV field offices. NIST FRVT-validated facial recognition procurement dominates touchless authentication mandates for REAL ID compliance. Los Angeles and San Francisco metropolitan areas concentrate the largest template database migration projects.
Texas
US-Mexico border land ports from El Paso to Brownsville require integrated biometric networks for immigration and customs enforcement. State-level driver's license modernization parallels federal checkpoint expansion timelines. The Rio Grande Valley and El Paso corridors represent the densest concentration of border security biometric procurement.
North America Biometrics in Government Market Competitive Landscape
Multimodal platform specialization dominates the current landscape as vendors recalibrate architectures for touchless capture requirements. The vendor base organizes around three tiers: established federal integrators with CJIS security clearances, mid-scale platform specialists competing on NIST certification speed, and niche mobile enrollment providers serving field law enforcement. Strategic archetypes include legacy AFIS modernizers, cloud-native platform builders, and biometric algorithm pure-plays. Competitive intensity concentrates on NIST FRVT accuracy benchmarks and DHS indefinite-delivery contract vehicles.
Within the federal integrator tier, IDEMIA and Thales Group exemplify vendors anchoring large-scale contracts through civil-criminal database integration and multimodal platform specialization. NEC Corporation occupies a position among algorithm-centric competitors competing on fingerprint matching performance benchmarks. These three represent distinct strategic postures: database consolidation leverage, hardware-software platform breadth, and biometric engine speed optimization.
| Leading Market Players |
|---|
| IDEMIA |
| Thales Group |
| NEC Corporation |
| Aware Inc. |
| M2SYS Technologies |
| HID Global Corporation |
| BIO-key International |
| Fujitsu |
| Innovatrics |
| Others |
Value Network & Pricing Analysis
Captive production of specialized image sensors and edge AI processors anchors vendor pricing power across North American government biometric deployments. This backward integration into semiconductor design insulates established players from foundry cost volatility while locking subscription-based platform licensing at premium tiers for agencies demanding NIST-certified accuracy.
Pricing Analysis
Input-cost pass-through from concentrated East Asian foundry capacity drives algorithm licensing fees upward for facial recognition platforms. Pricing stratifies across NIST FRVT-certified premium tiers, mid-tier state DMV bundles, and economy field-enrollment tablets with offline capability. Cost compression in mid-tier subscriptions intensifies as California and Texas DMVs consolidate procurement volumes. Federal agencies exhibit least price sensitivity due to security clearance requirements, while municipal jails face acute budget constraints.
Supply Chain Analysis
Specialized CMOS image sensor supply rests on Taiwanese and South Korean foundry capacity, with edge AI processor tape-outs concentrated in U.S. fabless design houses. Biometric terminal assembly draws from Mexican contract manufacturers for CBP land-port deployments. Single-source vulnerability in FRVT-validation compute clusters threatens procurement timelines. Distribution runs through federally cleared systems integrators holding CJIS security contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with procurement officers now mandating demographic parity certification that filters out subscale algorithm vendors. The shift toward NIST FRVT-validated multimodal platforms rewards incumbents with sustained R&D investment capacity.
For Market Incumbents: Deepen civil-criminal database integration to defend against cloud-native challengers. Expand NIST certification pipelines ahead of DHS indefinite-delivery vehicle refreshes. Prioritize captive sensor design to offset foundry concentration risk in Taiwanese supply nodes. For New Entrants and Emerging Players: The gap between premium federal integrator pricing and economy state DMV subscriptions offers entry space for mid-tier platform specialists. Target county-level law enforcement mobile enrollment as the most penetrable segment. Lead with rapid NIST certification speed as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for biometric algorithm pure-plays because FBI CJIS interoperability mandates create natural consolidation pressure. Five-to-ten year viability hinges on sustained federal procurement volume. Watch NIST FRVT protocol evolution timing as the critical inflection signal for algorithm obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| NIST FRVT Certification Acceleration | Faster validation cycles unlock DHS and FBI procurement vehicle eligibility before competitors. |
| Multimodal Platform Integration | Unified face-iris-fingerprint architectures displace single-modality vendors in border modernization contracts. |
| Cloud-Native Subscription Licensing | Annual consumption models capture California and Texas DMV consolidation spending with recurring revenue. |
| Edge AI Processor Development | On-device template generation reduces bandwidth dependency for remote CBP land-port deployments. |
| CJIS Security Clearance Expansion | Expanded cleared personnel pools qualify vendors for classified national security facility access contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with biometric procurement officers at DHS and FBI, state DMV IT directors, and CJIS-cleared systems integrators informed deployment timeline assumptions. Secondary validation drew from NIST FRVT test result publications, DHS budget justification documents, and state procurement databases. Bottom-up contract aggregation and top-down federal appropriations triangulation anchored market size estimates.
Segment-weighting across application, technology, end user, and service type dimensions structured the analytical framework. CAGRs derived from deployment velocity curves tied to REAL ID compliance deadlines and CBP modernization appropriations. Modeled inputs included biometric terminal shipment volumes, algorithm licensing transaction counts, and integration service contract values.
Caveats apply where NIST protocol revisions or Illinois BIPA litigation expansion could materially shift the outlook. Forecasts reflect assumptions about federal funding continuity and state procurement consolidation momentum. A small set of named triggers—FRVT accuracy threshold changes, foundry supply disruptions, and biometric privacy statute expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometrics Software Market
Biometrics & Identity Management
Multi-Factor Authentication (MFA) Market
Biometrics & Identity Management
Mobile Devices User Authentication Services Market
Biometrics & Identity Management
Biometrics Banking Market
Biometrics & Identity Management
Latin America Government & Security Biometrics Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Out-Of-Band Authentication Market
Biometrics & Identity Management
Biometric Data Encryption Device Market
Biometrics & Identity Management
Asia Pacific Biometrics in Government Market
Biometrics & Identity Management
Global Behavioral Biometrics Market
Biometrics & Identity Management
Biometric Passport Market
Biometrics & Identity Management
Healthcare Biometrics Market
Biometrics & Identity Management
Biometric Lockers Market
Biometrics & Identity Management
Global Biometrics Middleware Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market
Biometrics & Identity Management
FIDO Authentication Market