
 Protective Gowns Market | 2026-2036
Protective Gowns Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Gowns Market Analysis
China is fragmenting domestic protective gown manufacturing capacity as regional producers expand spunbond-meltblown-spunbond (SMS) fabric lines to serve both local hospitals and export channels. Cardinal Health leverages extensive distribution networks across North American health systems to sustain volume leadership in disposable surgical gowns. DuPont de Nemours anchors premium positioning through Tyvek and Tychem material science, competing on chemical permeation resistance rather than commodity pricing.
Protective gowns are personal protective equipment garments engineered from nonwoven synthetic fabrics such as polypropylene, polyethylene, or multilayer SMS laminates, designed to achieve specific AAMI barrier protection levels against fluid penetration and microbial transmission for healthcare workers and laboratory personnel. Surgical gowns command the largest revenue share among product types due to mandatory use in operating rooms, while isolation gowns experience faster volume acceleration driven by expanded use in emergency departments and contact precaution protocols. Polypropylene dominates material consumption for its cost-efficiency in single-use disposables, though SMS fabric captures margin concentration where hospitals prioritize higher AAMI Level 3 and Level 4 protection.
FDA 510(k) clearance requirements and AAMI PB70 testing standards govern barrier performance claims in the United States, while OSHA bloodborne pathogen regulations mandate employer provision of appropriate protective apparel, directly institutionalizing gown procurement across hospital systems. The EU Medical Device Regulation (MDR) and CE marking requirements create parallel compliance obligations for manufacturers accessing European healthcare markets. Stakeholders must monitor evolving EPA and state-level waste regulations addressing single-use disposable volumes, as sustainability pressures increasingly influence material selection and reusable gown program reinvestment decisions.
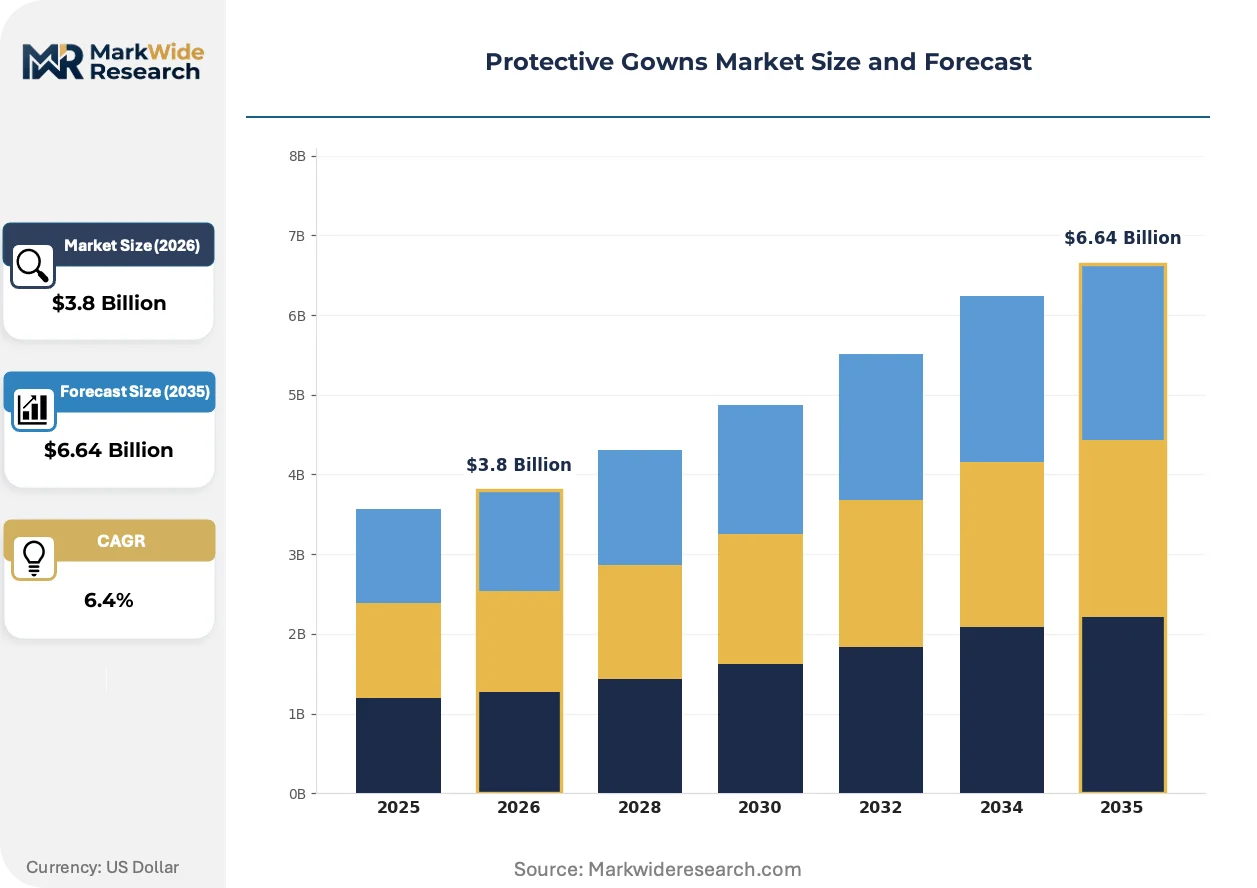
Market Dynamics
FDA and OSHA mandates for fluid-resistant barrier protection are institutionalizing bulk procurement protocols across US hospital systems, compressing vendor selection cycles and elevating AAMI certification requirements from preference to prerequisite.
Growth Catalysts
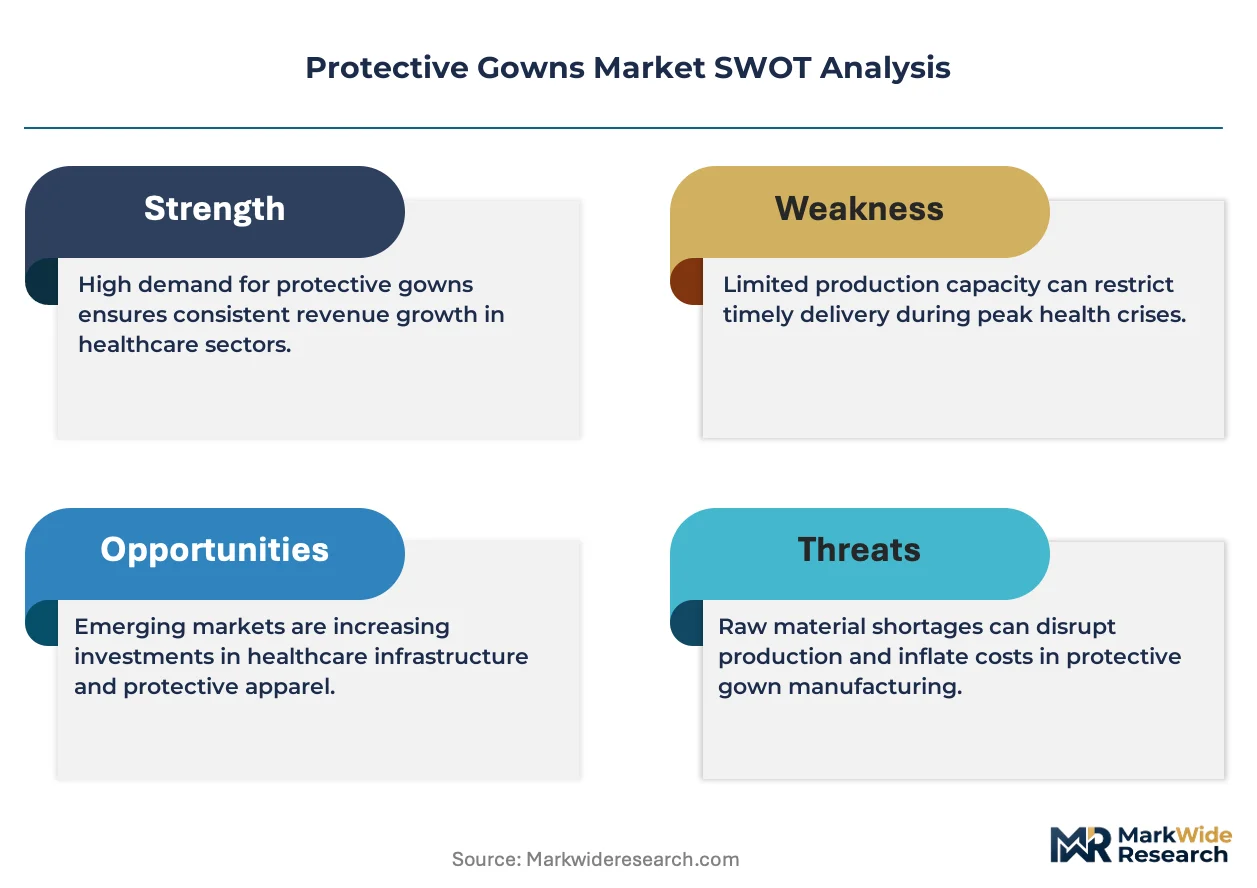
- AAMI Level 3-4 Certification Mandates:US hospital systems now require higher barrier ratings for operating room and emergency department protocols, pulling SMS fabric demand upward.
- China SMS Capacity Expansion:Regional producers are adding spunbond-meltblown-spunbond lines to serve both domestic hospital procurement and export channels.
- OSHA Bloodborne Pathogen Standards:Employer provision requirements directly institutionalize protective gown procurement across acute care employers nationwide.
Market Restraints
- Polypropylene Feedstock Volatility:Crude-linked resin pricing creates margin compression for single-use disposable manufacturers without long-term supply contracts.
- Regional Production Concentration:Domestic Chinese SMS fabric expansion risks oversupply in export markets while import-dependent regions face supply security questions.
- Reusable Gown Substitution:Sustainability pressures and state-level waste regulations are prompting hospital systems to reinvest in laundering infrastructure for multi-use alternatives.
Strategic Opportunities
- EU MDR Compliance Services:CE marking complexity under the Medical Device Regulation creates white space for technical file preparation and notified body liaison services.
- Telehealth-Adjacent Home Care:Post-acute and home health settings are expanding isolation gown use beyond traditional hospital boundaries.
- RFID-Enabled Inventory Tracking:Convergence of smart textile tags with ERP systems enables consignment and auto-replenishment models for large health systems.
Industry Challenges
- FDA 510(k) Timeline Compression:Clearance backlogs for novel barrier materials delay product launches and tie up regulatory capital.
- Legacy Laundering Infrastructure:Hospital systems reintroducing reusable programs face integration friction with existing linen service contracts and infection control workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Gowns Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Gowns, Isolation Gowns, Coveralls, Aprons Material: Polyethylene, Polypropylene, SMS Fabric, PVC End User: Hospitals, Clinics, Laboratories, Long-Term Care Facilities Usage Type: Single-Use, Reusable, Disposable, Sterile |
| Companies Covered | 3M, Cardinal Health, Medline Industries, Inc., DuPont de Nemours, Inc., Kimberly-Clark Corporation, Ansell, Halyard Health, Molnlycke Health Care AB, Owens & Minor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Gowns Market Emerging Trajectories
Material science advances and regulatory digitization are compressing product development cycles while procurement centralization restructures how protective gowns reach end-users. Three forces dominate this evolution.
Smart barrier fabrics incorporating RFID tracking and fluid-indicating dyes are virtualizing inventory management for large health systems. Academic medical centers and integrated delivery networks are piloting these technologies to eliminate stockouts and reduce waste. The technology is virtualizing traditional distributor-held safety stock models into direct-to-consumption data flows.
EU MDR technical documentation requirements and US FDA 510(k) software validation mandates are forcing manufacturers to rebuild quality management systems around electronic submissions. Industrial consequence includes redirected R&D spending toward regulatory technology rather than material innovation. Surgical gown segments with novel barrier claims face the steepest compliance cost escalation.
Health system consolidation is compressing vendor panels and mandating standardized gown protocols across acquired facilities. Group purchasing organizations are displacing individual hospital procurement autonomy with enterprise-level contracts tied to volume commitments. This concentration is most visible in US multi-state hospital systems where supply chain officers now report to C-suite executives rather than materials management departments.
Protective Gowns Market Segmentation
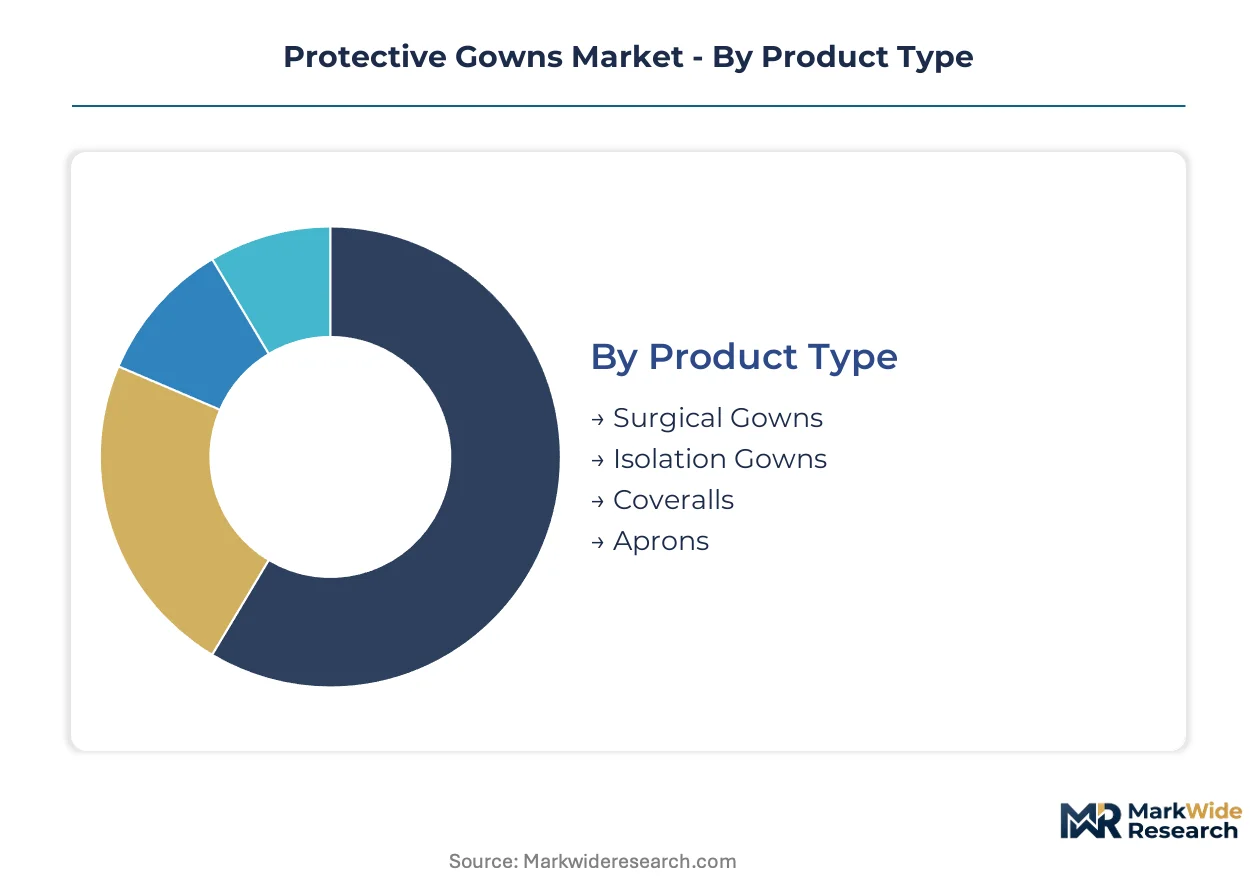
Protective gown procurement varies sharply across clinical settings and usage patterns, with material specifications and barrier ratings driving vendor selection and inventory management protocols. Understanding these segment boundaries clarifies where pricing power concentrates and where commoditization pressures dominate.
Product Type:
After-sales-service intensity differs markedly across gown categories, with surgical gowns requiring specialized fitting support and compliance documentation while isolation gowns flow through standard distribution channels.
- Surgical Gowns:Engineered to AAMI PB70 Level 3-4 standards with reinforced critical zones and sterile packaging, these garments dominate operating room procurement. US hospital systems mandate these for invasive procedures, with Cardinal Health and Owens & Minor controlling distribution through integrated delivery network contracts.
- Isolation Gowns:Designed for contact precaution protocols in emergency departments and isolation wards, these experience volume acceleration driven by expanded infection control mandates. Demand concentrates in bulk purchasing agreements across multi-state health systems seeking standardized barrier protection.
- Coveralls:Full-body protective garments serving laboratory and pharmaceutical manufacturing environments where chemical splash protection exceeds standard gown requirements.
- Aprons:Limited-coverage alternatives for dental and outpatient procedures where fluid exposure risk is localized and lower barrier ratings suffice.
By volume, Surgical Gowns leads. By growth pace, Isolation Gowns is expanding most quickly.
Material:
Cost tier stratification across raw material inputs determines margin structure, with commodity polypropylene facing margin compression while engineered SMS laminates command premium positioning.
- Polypropylene:Spunbond nonwoven fabric dominates single-use disposable production for its cost efficiency and adequate AAMI Level 1-2 performance. Chinese regional producers have expanded capacity aggressively, pressuring export pricing.
- SMS Fabric:Spunbond-meltblown-spunbond multilayer construction delivers superior fluid resistance and microbial barrier for Level 3-4 applications. Hospitals prioritize this material for operating rooms despite 40-60% cost premiums over standard polypropylene.
- Polyethylene:Film-based alternatives offering impermeable chemical protection for specialized laboratory and pharmaceutical manufacturing environments.
- PVC:Legacy material retained in heavy-duty reusable programs where laundering infrastructure supports extended garment lifecycle economics.
By procurement volume, Polypropylene leads. By margin expansion, SMS Fabric is gaining share fastest.
End User:
Customer type segmentation reveals divergent purchasing authority, with centralized hospital procurement contrasting against fragmented clinic decision-making.
- Hospitals:Integrated delivery networks and academic medical centers drive bulk purchasing through group purchasing organizations, standardizing gown protocols across acquired facilities. FDA and OSHA mandates institutionalize protective apparel provision as employer responsibility.
- Clinics:Outpatient and ambulatory surgery centers face procurement constraints from smaller scale and limited storage infrastructure, often relying on distributor consignment models.
- Laboratories:Research and diagnostic facilities require chemical-resistant garments beyond standard medical gown specifications, creating specialized demand for coveralls and enhanced barrier materials.
- Long-Term Care Facilities:Nursing homes and skilled nursing facilities expanded isolation gown use during pandemic protocols, though budget limitations constrain adoption of premium SMS alternatives.
By absolute consumption, Hospitals leads. By volume acceleration, Long-Term Care Facilities shows steepest expansion trajectory.
Usage Type:
Supply concentration varies by lifecycle model, with single-use disposables flowing through distributor networks while reusable programs require regional laundering infrastructure partnerships.
- Single-Use:Disposable gowns dominate acute care settings for infection control assurance and inventory simplicity. Polypropylene and SMS variants constitute the vast majority of hospital procurement volume.
- Reusable:Multi-use garments processed through commercial laundering services are experiencing renewed investment as sustainability pressures mount and state-level waste regulations tighten. Hospital systems face integration friction with existing linen contracts.
- Disposable:Synonymous with single-use in procurement terminology, this category captures all non-reusable garment flows regardless of material specification.
- Sterile:Gamma-irradiated or ethylene oxide-sterilized packaging mandatory for operating room applications, adding 15-25% cost premiums and specialized distribution requirements.
By current procurement volume, Single-Use leads. By reinvestment activity, Reusable is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance requirements and OSHA bloodborne pathogen mandates anchor demand concentration in the United States, while China expands spunbond-meltblown-spunbond fabric capacity to serve both domestic hospital procurement and export channels. Germany and Japan maintain premium positioning through material science specialization, and India scales regional manufacturing to reduce import dependence.
United States
Hospital systems mandate AAMI Level 3-4 surgical gowns for operating rooms, driving bulk procurement through group purchasing organizations. FDA 510(k) clearance and OSHA employer provision requirements institutionalize protective apparel acquisition across acute care employers. Cardinal Health leverages distribution networks across North American health systems from its Dublin, Ohio headquarters.
China
Regional producers expand SMS fabric lines to supply domestic hospitals and export markets simultaneously. NMPA registration requirements and GB standards govern barrier performance claims for medical devices. Yangtze River Delta manufacturing clusters concentrate spunbond-meltblown-spunbond capacity expansion near Shanghai and Jiangsu province textile infrastructure.
Germany
EU MDR compliance obligations reshape quality management systems for manufacturers accessing European healthcare markets. EMA and notified body requirements for CE marking elevate technical documentation burdens. Baden-Württemberg industrial regions host specialized nonwoven engineering firms serving chemical-resistant garment specifications.
Japan
PMDA medical device regulations and JIS standards govern barrier protection claims in acute care settings. METI industrial policy supports domestic manufacturing resilience for critical healthcare supplies. Kanto region medical device clusters around Tokyo maintain premium positioning through material science innovation.
India
CDSCO medical device rules and BIS standards increasingly govern protective gown quality for domestic hospital procurement. PLI scheme incentives attract investment in technical textile manufacturing. Gujarat and Maharashtra textile belts expand spunbond nonwoven capacity to substitute Chinese imports.
Protective Gowns Market Vendor Landscape
Integrated distributors and material science specialists split the market between volume-driven procurement efficiency and premium barrier performance claims. The vendor base concentrates around health system contract consolidation, with group purchasing organizations compressing vendor panels to enterprise-level agreements. Two strategic archetypes dominate: distribution-heavy integrated supply networks and specialty material innovators competing on chemical permeation resistance. Competitive moves center on M&A for distribution footprint expansion and SMS fabric capacity additions to capture AAMI Level 3-4 certification demand.
Within the integrated distribution tier, Cardinal Health and Owens & Minor exemplify health system contract consolidation strategies. DuPont de Nemours anchors the specialty material archetype through Tyvek and Tychem positioning. Among diversified healthcare suppliers, 3M and Kimberly-Clark Corporation occupy positions spanning multiple personal protective equipment categories. Molnlycke Health Care AB represents European-based surgical gown specialization.
| Leading Market Players |
|---|
| 3M |
| Cardinal Health |
| Medline Industries, Inc. |
| DuPont de Nemours, Inc. |
| Kimberly-Clark Corporation |
| Ansell |
| Halyard Health |
| Molnlycke Health Care AB |
| Owens & Minor |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing clusters anchor global SMS fabric capacity, and their expansion velocity directly compresses export pricing for commodity polypropylene gowns while reinforcing premium positioning for AAMI Level 3-4 certified alternatives. Hospital procurement officers leverage this supply bifurcation to extract volume discounts on standard disposables while accepting cost premiums for surgical-grade barrier protection.
Pricing Analysis
Chinese export pricing for standard polypropylene gowns runs 30-40% below North American domestic production, creating geographic arbitrage that US distributors exploit through bulk import contracts. Three-tier pricing structure across premium SMS, standard polypropylene, and economy polyethylene levels separates AAMI certification grades, with FDA 510(k) clearance adding measurable brand premium. Cost compression in the commodity tier is intensifying because Yangtze Delta capacity additions outpace demand absorption, while margins are tightening for import-dependent distributors facing tariff exposure. Long-term care facilities exhibit highest price sensitivity, constrained by Medicaid reimbursement ceilings, whereas academic medical centers prioritize barrier performance over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for distributor relationships with multi-state health systems, with supply-chain finance facilities emerging as working capital bridges for regional manufacturers. Raw material sourcing draws from Saudi Arabian polypropylene resin, South Korean spunbond equipment, and domestic Chinese meltblown fiber production, creating multi-continent dependency chains. Single-source vulnerability concentrates in specialized SMS laminates, where three producers control 70% of certified capacity. Distribution runs through Cardinal Health and Owens & Minor's integrated delivery network contracts, with group purchasing organizations consolidating vendor panels to enterprise-level agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance deadlines and FDA 510(k) software validation mandates are compressing product development timelines, transforming regulatory technology investment from overhead into competitive moat construction.
For Market Incumbents: Build certification moats through vertical integration into SMS fabric production and captive supply of meltblown fiber capacity. Cardinal Health and DuPont de Nemours exemplify divergent paths—distribution scale versus material science specialization—with both requiring reinvestment in electronic quality management systems to defend against emerging Asian producers. Priority levers include backward integration into Yangtze Delta manufacturing partnerships and acquisition of notified body liaison capabilities. For New Entrants and Emerging Players: Establish a beachhead in EU MDR technical file preparation services, where CE marking complexity creates immediate white space. Home health and telehealth-adjacent isolation gown demand represents the most penetrable segment, bypassing entrenched hospital distributor relationships. Go-to-market positioning should emphasize RFID-enabled inventory tracking as a differentiated value proposition for integrated delivery networks seeking auto-replenishment models. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because health system merger activity is compressing vendor panels and mandating standardized protocols across acquired facilities. Acquisition targets should display specialized SMS capacity or regulatory technology capabilities rather than commodity polypropylene scale. Signal to monitor: state-level waste regulations prompting reusable gown program reinvestment, which would redirect capital toward laundering infrastructure providers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR technical documentation requirements elevate compliance costs for surgical gown entrants lacking notified body relationships. |
| Hospital System Partnership | Group purchasing organization contracts consolidate procurement authority, making direct IDN relationships essential for volume access. |
| Backward Integration into SMS Fabric | Captive meltblown capacity insulates margins from Chinese export pricing volatility and secures AAMI Level 3-4 certification supply. |
| RFID-Enabled Inventory Tracking | Smart textile convergence with ERP systems enables consignment models that displace distributor-held safety stock. |
| Reusable Gown Program Development | Sustainability pressures and state waste regulations are prompting hospital reinvestment in laundering infrastructure partnerships. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement officers, GPO contracts managers, biomedical engineers, SMS fabric plant managers, and regulatory affairs specialists at FDA-registered manufacturers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body technical documentation, hospital procurement databases, and customs trade records for polypropylene resin and nonwoven fabric shipments. Bottom-up demand modeling across end-user segments was triangulated against top-down capacity estimates from Yangtze Delta and Gujarat textile belt expansion announcements.
Calibration against historical volume trajectories and regulatory implementation timelines anchored the projection framework across the analysis window. Segmentation dimensions included product type, material specification, AAMI barrier level, end-user facility type, and usage lifecycle model. CAGRs were derived from elasticity-adjusted demand curves incorporating infection control protocol expansion and reusable program substitution effects. Industry-specific inputs encompassed OSHA employer provision mandate enforcement patterns and EU MDR transition deadline compliance rates.
Stress conditions across polypropylene feedstock price volatility, Chinese export tariff regimes, and FDA 510(k) clearance timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding health system consolidation velocity and sustainability regulation diffusion. Macroeconomic contraction, regulatory timeline compression beyond modeled scenarios, or breakthrough reusable fabric technologies would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Anesthetic Gas Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Snowmobile Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Steel Smart Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market