
 Drone Safety Systems Market | 2026-2036
Drone Safety Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Safety Systems Market Insights
FAA Remote ID compliance is expanding the baseline hardware requirement for every commercial drone sold in the United States, reshaping cost structures for OEMs and retrofitters alike. DJI leverages its manufacturing scale to integrate safety modules at the factory level across multiple product tiers. Skydio differentiates through AI-native visual recognition stacks that satisfy emerging detect-and-avoid standards without external sensor payloads. AeroVironment anchors its defense-oriented portfolio with flight termination systems hardened against electronic warfare conditions.
Drone safety systems encompass integrated hardware-software architectures designed to prevent mid-air collisions, enforce geospatial boundaries, and execute controlled emergency landings through parachute deployment or engine cutoff protocols, typically operating with sub-100-millisecond reaction latencies. These systems serve the primary commercial purpose of enabling unmanned aircraft to share airspace with crewed aviation and operate over populated areas without ground-based spotter dependency. Collision avoidance systems currently occupy the largest product category as regulatory minimums harden, while geo-fencing solutions are recording the fastest adoption curve driven by urban air mobility corridor designations. Among technology layers, radar sensors dominate heavy-lift and beyond-visual-line-of-sight applications where all-weather reliability is non-negotiable, whereas visual recognition systems are capturing share in last-mile delivery fleets where weight and power budgets constrain multi-sensor fusion.
The FAA, EASA, and ICAO standards frameworks collectively determine airworthiness certification pathways, with Remote ID in the United States and the Specific category under EU Regulation 2019/947 now functioning as de facto market gatekeepers. China's CAAC and Japan's MLIT are developing parallel conformance regimes that fragment compliance testing for manufacturers serving multiple jurisdictions. Stakeholders must monitor divergence between performance-based standards and prescriptive equipment mandates, as this tension will determine whether modular retrofit solutions or integrated native architectures capture the larger addressable base.
Market Dynamics
Beyond-visual-line-of-sight waivers from the FAA are compressing certification timelines and forcing OEMs to pre-integrate detect-and-avoid modules at the factory level rather than offering aftermarket retrofits.
Growth Catalysts
- FAA Remote ID Mandate:Every commercial drone sold in the United States must now broadcast identification and location data, creating baseline hardware demand across all product tiers.
- Urban Air Mobility Corridors:Designated flight paths in Dallas, Los Angeles, and New York are requiring geo-fencing and collision avoidance systems for operational approval.
- Logistics Network Expansion:Last-mile delivery operators are procuring detect-and-avoid architectures to eliminate ground-based visual observer requirements.
Market Restraints
- Sensor Cost Concentration:Radar modules for all-weather beyond-visual-line-of-sight applications remain priced at premiums that exclude light commercial operators.
- Supply Geographic Concentration:Lithium-polymer battery cells and compact radar chipsets source predominantly from East Asian contract manufacturers, exposing lead time volatility.
- Regulatory Fragmentation:Divergence between FAA performance-based standards and EASA prescriptive equipment mandates forces dual certification investments for multi-jurisdiction vendors.
Strategic Opportunities
- India's Drone Rules 2021:The country's PLI scheme for drone manufacturing is creating localized assembly demand for safety system integration.
- AI-Visual Convergence:Edge-computing inference chips combined with machine vision are enabling single-sensor detect-and-avoid without external radar payloads.
- Defense Channel Expansion:NATO member militaries are hardening flight termination systems against electronic warfare, opening specialized procurement verticals.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineers with real-time operating system experience for sub-100-millisecond reaction latencies command premium compensation.
- Multi-Jurisdiction Certification Overlap:Simultaneous FAA, EASA, and CAAC airworthiness approvals extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Safety Systems Market |
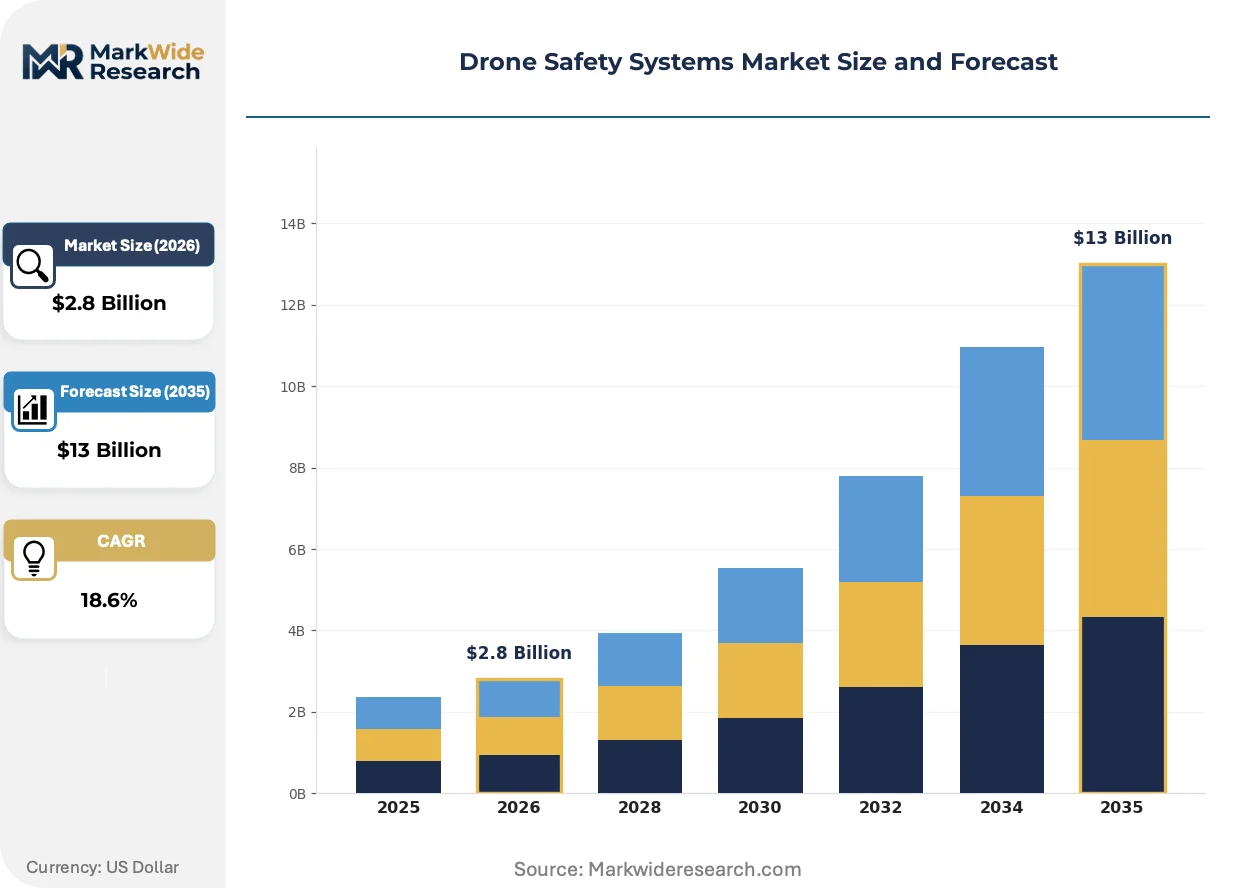
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Collision Avoidance Systems, Geo-Fencing Solutions, Emergency Parachutes, Flight Termination Systems Technology: Radar Sensors, LiDAR, Visual Recognition, Ultrasonic Sensors, Infrared Detection Application: Aerial Photography, Infrastructure Inspection, Agricultural Monitoring, Public Safety, Surveying End User: Commercial Operators, Government Agencies, Film Production Houses, Surveying Firms, Emergency Responders |
| Companies Covered | DJI, Skydio, AeroVironment, Parrot, FLIR Systems, Autel Robotics, Delair, ideaForge, AZUR DRONES SAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Safety Systems Market Trends and Innovations
Software-defined safety architectures are displacing fixed-function hardware, allowing operators to update collision avoidance algorithms through over-the-air patches rather than physical retrofits.
Computer vision inference stacks are absorbing the detect-and-avoid function previously requiring dedicated radar or lidar payloads. Last-mile delivery fleets in the United States are adopting these lighter systems to preserve battery endurance. The weight and power savings are absorbing share from multi-sensor fusion configurations in sub-25-kilogram platforms.
EASA's Specific category under EU Regulation 2019/947 is mandating standardized risk assessments for operations over populated areas. This framework is pushing manufacturers toward pre-certified modular safety kits rather than custom-integrated designs. German and French urban air mobility projects are prioritizing vendors with existing EASA design approvals.
Service-based safety subscriptions are replacing perpetual hardware licenses in commercial operator procurement. Fleet managers now pay annual fees for real-time geofencing updates and remote ID compliance monitoring. This shift is most visible among United States-based logistics networks operating across multiple state jurisdictions with varying local restrictions.
Drone Safety Systems Market Segmentation
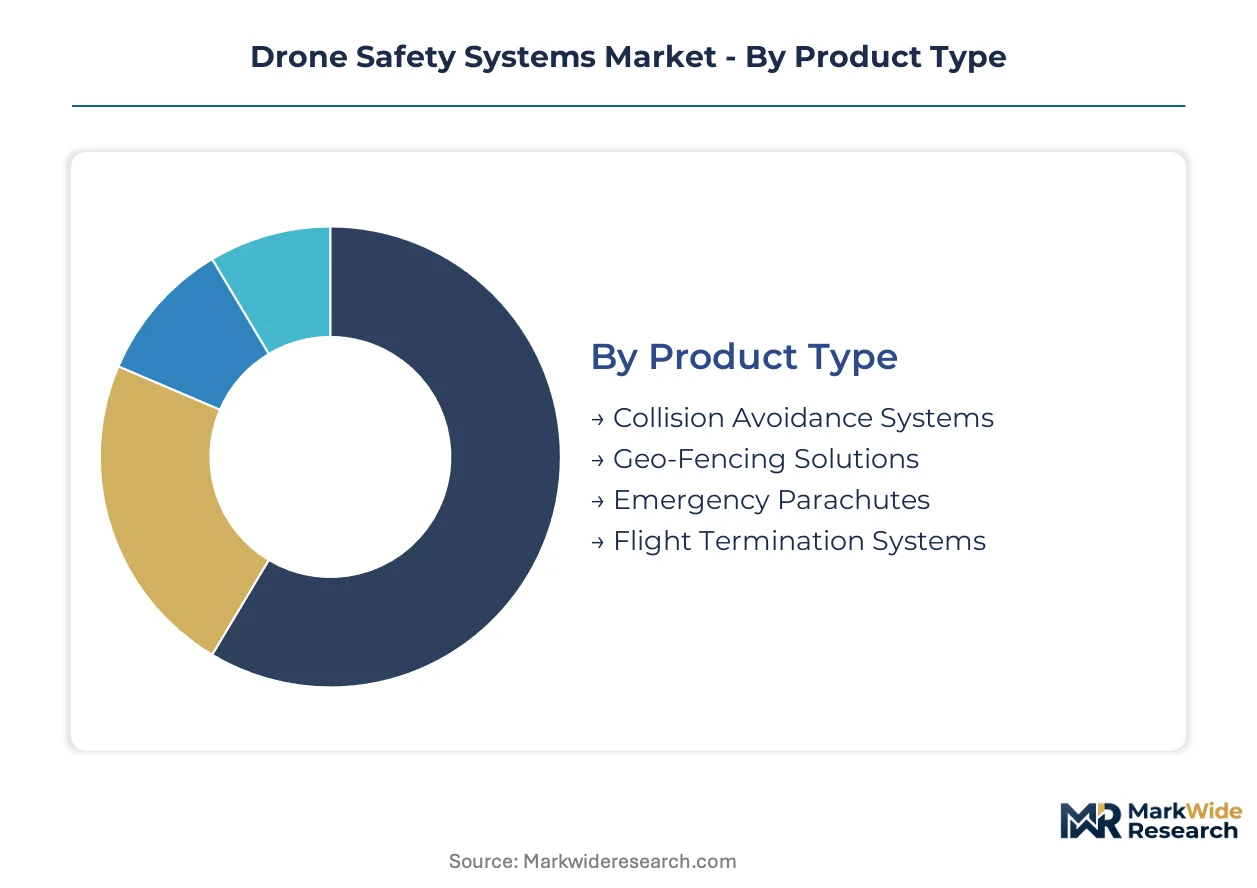
Drone safety systems fragment across hardware configurations, sensing modalities, and operational contexts. Each dimension carries distinct certification pathways and procurement economics that reshape vendor positioning.
Product Type:
Supply concentration in radar and visual computing chipsets funnels manufacturing capacity toward integrated architectures rather than standalone modules.
- Collision Avoidance Systems:Multi-sensor fusion architectures combining radar, camera, and ultrasonic inputs process environmental data with sub-100-millisecond latency. Demand concentrates in United States logistics networks seeking FAA beyond-visual-line-of-sight waivers, where sensor redundancy satisfies operational risk assessments.
- Geo-Fencing Solutions:Software-defined boundary enforcement systems integrate real-time airspace data with flight controller firmware. Urban air mobility corridors in Dallas and Los Angeles are mandating these systems for operational approval, compressing procurement timelines for delivery fleet operators.
- Emergency Parachutes:Pyrotechnic or spring-deployed recovery systems designed for controlled descent over populated areas.
- Flight Termination Systems:Engine cutoff protocols triggered by geofence breach or command link loss, hardened against electronic warfare in defense applications.
Collision Avoidance Systems absorb the bulk of installed capacity; Geo-Fencing Solutions are expanding most quickly.
Technology:
Cost tiering separates premium all-weather radar from lightweight visual stacks that sacrifice range for power efficiency.
- Radar Sensors:Frequency-modulated continuous-wave modules deliver all-weather detection out to 500 meters for heavy-lift platforms. Beyond-visual-line-of-sight cargo operations in the United States and Germany specify these sensors for regulatory compliance.
- Visual Recognition:Convolutional neural networks running on edge-computing inference chips classify obstacles without external sensor payloads. Last-mile delivery fleets in California and Texas are adopting these systems to preserve battery endurance on sub-25-kilogram aircraft.
- LiDAR:Solid-state laser ranging for centimeter-precision mapping in infrastructure inspection.
- Ultrasonic Sensors:Short-range proximity detection for indoor navigation and precision landing.
- Infrared Detection:Thermal signature tracking for night operations and wildlife monitoring.
Radar Sensors dominate heavy-lift procurement; Visual Recognition is climbing the fastest among sub-25-kilogram platforms.
Application:
Volume concentration in commercial logistics is displacing earlier demand centers in photography and surveying.
- Infrastructure Inspection:Automated bridge, power line, and pipeline assessment requires collision avoidance for GPS-denied environments. Texas and California utility operators are procuring detect-and-avoid systems to eliminate ground-based visual observers.
- Agricultural Monitoring:Crop health mapping and precision spraying over varied terrain demands terrain-following safety architectures. Midwest United States farming cooperatives are integrating geo-fencing to prevent drift into neighboring properties.
- Aerial Photography:Cinematography and real estate imaging with geofenced no-fly zone compliance.
- Public Safety:Search-and-rescue and firefighting operations requiring hardened flight termination.
- Surveying:Topographic and cadastral mapping with survey-grade positioning integration.
Infrastructure Inspection absorbs the bulk of current procurement; Agricultural Monitoring is gaining share fastest as cooperatives scale fleet operations.
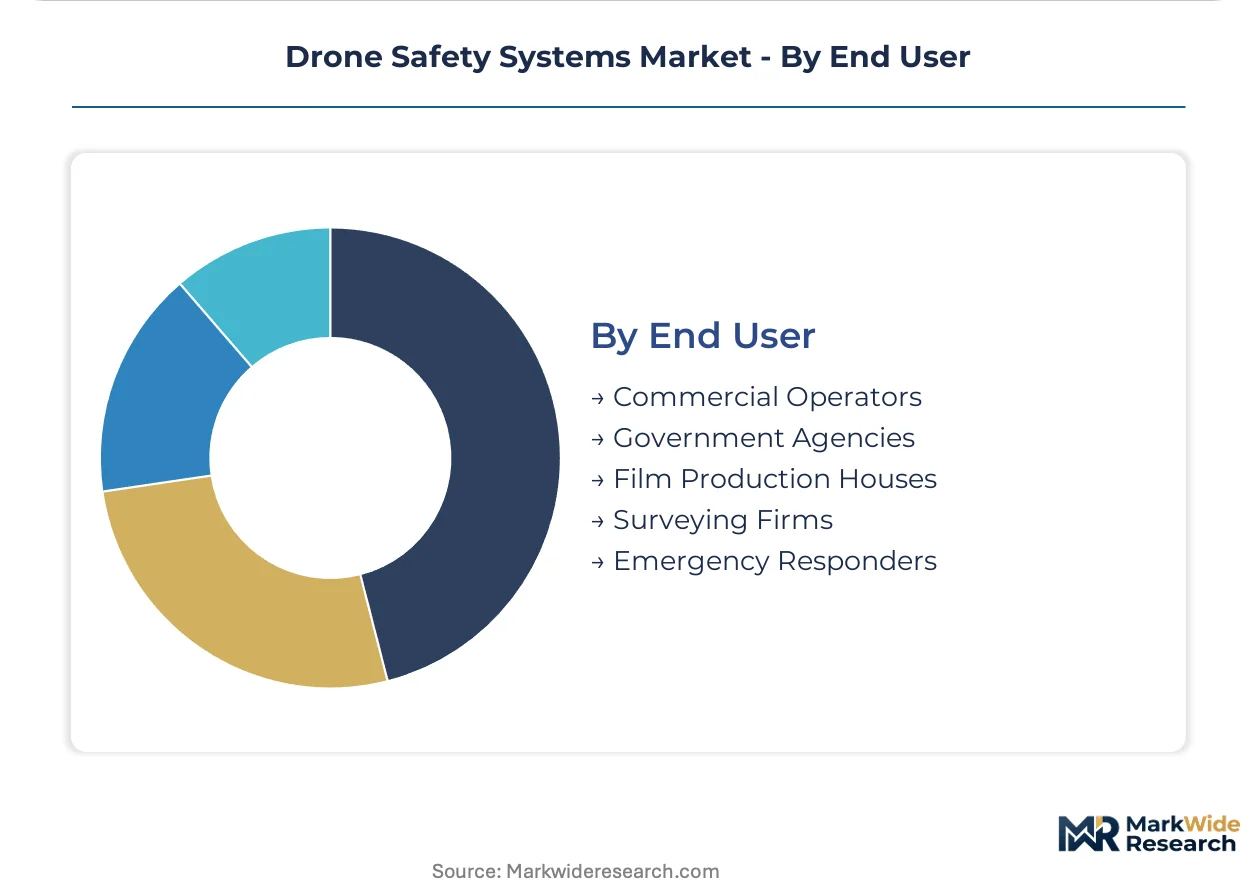
End User:
Customer type determines certification burden and pricing tolerance, with government channels accepting longer lead times for hardened specifications.
- Commercial Operators:Logistics and delivery networks operating under FAA Part 107 with waivers for expanded operations. United States-based last-mile providers are procuring integrated safety stacks at factory level to compress certification timelines.
- Government Agencies:Civil aviation authorities and defense departments specifying electronic-warfare-resistant architectures. NATO member militaries are hardening flight termination systems against signal jamming.
- Film Production Houses:Cinematography fleets requiring geo-fencing for urban location shoots.
- Surveying Firms:Geospatial service providers integrating safety systems with RTK positioning.
- Emergency Responders:Fire departments and search teams operating in degraded communications environments.
Commercial Operators absorb the bulk of unit volume; Government Agencies are expanding most quickly through defense channel procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shenzhen and special economic corridors in Texas concentrate drone safety system manufacturing and testing infrastructure. These zones offer accelerated customs clearance and R&D tax credits that pull component suppliers into tight geographic clusters.
United States
Beyond-visual-line-of-sight cargo networks and urban air mobility corridors in Dallas and Los Angeles drive detect-and-avoid procurement. The FAA's Remote ID mandate and Part 107 waiver pathways tighten compliance timelines for commercial operators. California's Central Valley hosts dense agricultural monitoring fleets integrating geo-fencing for cooperative spraying operations.
Germany
Heavy-lift logistics operators and infrastructure inspection contractors specify radar-based collision avoidance for all-weather reliability. EASA's Specific category under EU Regulation 2019/947 mandates standardized risk assessments for populated-area flights. The Munich-Stuttgart corridor anchors urban air mobility testing with pre-certified modular safety kit requirements.
China
CAAC's evolving unmanned aircraft certification framework and domestic delivery network scale-up compress factory-integration timelines for safety modules. The Yangtze River Delta manufacturing belt supplies compact radar chipsets and lithium-polymer cells to global OEMs. Shenzhen's special economic zone hosts integrated hardware-software architecture development for export markets.
India
The PLI scheme for drone manufacturing and Drone Rules 2021 compliance deadlines pull safety system integrators toward localized assembly. Karnataka and Telangana states designate aerospace parks with simplified certification pathways for component suppliers. Bangalore's hardware startup cluster develops lightweight visual recognition stacks for sub-25-kilogram agricultural platforms.
France
EASA design approval holders and urban air mobility project consortia in Paris prioritize pre-certified modular safety architectures. The Specific category risk assessment framework pushes manufacturers toward standardized kits rather than custom integration. Toulouse's aerospace engineering base supports flight termination system hardening for defense channel specifications.
Drone Safety Systems Market Competitive Landscape
United States producers anchor one tier; Chinese specialists hold manufacturing scale advantages in component supply. The vendor base separates into three distinct tiers: integrated platform OEMs, modular safety kit suppliers, and defense-hardened system specialists. Consolidation pressure concentrates in the middle tier as EASA and FAA certification costs rise. Strategic moves center on backward integration into sensor chipset supply and geographic expansion through local assembly partnerships in India and Southeast Asia.
Within the integrated platform tier, DJI and Skydio exemplify divergent approaches to factory-level safety module integration. AeroVironment occupies a position in defense-hardened flight termination systems. These three companies represent the spectrum from consumer-scale manufacturing to electronic-warfare-resistant specifications.
| Leading Market Players |
|---|
| DJI |
| Skydio |
| AeroVironment |
| Parrot |
| FLIR Systems |
| Autel Robotics |
| Delair |
| ideaForge |
| AZUR DRONES SAS |
| Others |
Pricing and Supply Chain Analysis
Firmware engineers with real-time operating system experience in California and Texas command premium compensation that widens spreads between factory-integrated safety architectures and modular retrofit kits. Labor-cost differentials between embedded systems talent clusters and assembly-line regions feed directly into three-tier pricing structures across premium, standard, and economy certification levels.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with operators paying premiums for safety modules deliverable within compressed FAA waiver timelines while spot inventory of pre-certified kits trades at discounts. Subscription-based SaaS pricing for real-time geofencing updates and Remote ID compliance monitoring is displacing perpetual hardware licenses among United States logistics networks. Price differentiation rests on EASA design approval status and factory-integration depth, with California-based last-mile fleets showing highest price sensitivity and NATO defense channels accepting extended lead times for hardened specifications. Cost compression in visual recognition stacks is intensifying because edge-computing inference chips are absorbing functions previously requiring dedicated radar payloads.
Supply Chain Analysis
India's PLI scheme for drone manufacturing and domestic-content mandates are reshaping sourcing patterns, pulling safety system integrators toward localized assembly in Karnataka and Telangana aerospace parks. Manufacturing gravity centers on China's Yangtze River Delta for compact radar chipsets and lithium-polymer cells, Germany's Munich-Stuttgart corridor for heavy-lift collision avoidance modules, and the United States for defense-hardened flight termination systems. Raw material dependencies include gallium nitride semiconductors, rare-earth magnet assemblies, and high-density battery cells. Single-source vulnerability in East Asian contract manufacturers for radar chipsets exposes lead time volatility. Distribution runs through OEM direct procurement for integrated platforms and specialized distributors for modular retrofit kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone safety systems are transitioning from fixed-function hardware to software-defined architectures, with machine vision inference stacks replacing legacy multi-sensor fusion configurations across sub-25-kilogram platforms.
For Market Incumbents: Hedge against margin erosion in radar-dominated heavy-lift segments by deepening captive supply of edge-computing inference chips for visual recognition stacks. Secure EASA design approvals ahead of EU Regulation 2019/947 risk assessment standardization to lock in modular safety kit procurement channels. Factory-integration partnerships with Indian PLI beneficiaries in Bangalore and Hyderabad compress cost positions for agricultural monitoring platforms.
For New Entrants and Emerging Players: Capture white-space in lightweight visual recognition systems for United States last-mile delivery fleets where battery endurance constraints exclude radar payloads. Penetrate India's sub-25-kilogram agricultural platform segment through localized assembly partnerships in Karnataka aerospace parks. Lead with AI-native software stacks that satisfy emerging detect-and-avoid standards without external sensor hardware.
For Investors and Strategic Acquirers: Re-rating potential sits with modular safety kit suppliers holding existing EASA design approvals given the Specific category risk assessment framework pushing manufacturers toward standardized architectures. Long-term viability favors vendors with backward integration into sensor chipset supply and geographic diversification through Indian local assembly. Watch FAA beyond-visual-line-of-sight waiver issuance velocity as inflection indicator for detect-and-avoid procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Chipsets | Captive supply of edge-computing inference chips secures margin control against visual recognition commoditization. |
| EASA Design Approval Investment | Pre-certified modular safety kits lock in procurement from German and French urban air mobility consortia. |
| Indian Local Assembly Partnership | PLI scheme compliance in Karnataka and Telangana opens agricultural monitoring platform demand. |
| Software-Defined Safety Architecture Launch | Over-the-air algorithm updates displace physical retrofits and create recurring subscription revenue streams. |
| Defense Channel Hardening Program | Electronic-warfare-resistant flight termination systems access NATO procurement verticals with extended contract durations. |
Research Methodology
Multi-period observation of FAA waiver issuance timelines, EASA certification completion rates, and logistics fleet procurement patterns anchored the trend analysis, supplemented by interviews with embedded systems engineering directors, commercial drone fleet managers, defense procurement officers, and regulatory affairs specialists at civil aviation authorities. Secondary validation drew from FAA Remote ID compliance databases, EASA design approval registries, SEC filings of listed drone OEMs, and customs trade records for radar chipset and battery cell imports. Bottom-up unit shipment estimates across product categories triangulated against top-down market value reconstructions.
Input-output matrices mapped sensor technology costs, certification timeline assumptions, and fleet operator procurement budgets across the projection horizon. Segmentation dimensions modeled include product type, sensing modality, application context, end-user category, and regional regulatory cluster. CAGRs were derived from curve-fitting historical procurement trajectories against regulatory milestone schedules. Industry-specific forecast inputs incorporated FAA beyond-visual-line-of-sight waiver approval velocity and EASA Specific category risk assessment adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory fragmentation between FAA performance-based standards and EASA prescriptive equipment mandates, supply chain disruptions in East Asian semiconductor manufacturing, and talent scarcity in real-time embedded systems engineering. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Rodent Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respirator Filter Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Blast Monitoring Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market