
 Hand Protection Equipment Market | 2026-2036
Hand Protection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Protection Equipment Market Intelligence
Advanced synthetic fibers are displacing traditional leather and cotton, as the market is pivoting toward materials offering superior cut and abrasion resistance. This shift favors manufacturers with strong material science capabilities. Ansell Ltd. specializes in a diverse portfolio for both industrial and medical applications. Honeywell International Inc. leverages its advanced materials expertise to develop innovative protective fibers. Meanwhile, Top Glove Corporation Bhd dominates the high-volume disposable glove segment, particularly in latex and nitrile products for healthcare and food processing.
Hand protection equipment encompasses devices designed to shield hands and arms from workplace hazards like cuts, chemical exposure, thermal risks, and abrasions. Products are often certified against standards such as Europe's EN 388, which provides a quantitative rating for resistance to abrasion, cut, tear, and puncture. While disposable gloves used by healthcare professionals and food handlers represent a significant volume, durable mechanical gloves for construction and manufacturing lead in terms of value. The material segment shows steady interest in PVC and rubber for chemical resistance applications.
Compliance with standards set by the U.S. Occupational Safety and Health Administration (OSHA) and Europe's CE marking requirements is mandatory for market access. These regulatory frameworks dictate minimum performance levels for personal protective equipment, influencing product design and material choices. Navigating the evolving landscape of material sustainability and developing end-of-life recycling solutions for disposable gloves will be a defining challenge for manufacturers.
Market Dynamics
The market's central dynamic is the interplay between stringent occupational safety regulations and rapid material science innovation. Mandates from bodies like OSHA are pushing performance requirements higher, while advancements in synthetic fibers provide manufacturers the tools to meet and exceed these standards.
Growth Catalysts
- Stringent Safety Mandates:Regulations such as the U.S. Occupational Safety and Health Administration (OSHA) standards and Europe's EN 388 certification for mechanical risks compel broad equipment adoption across all industrial sectors to ensure worker safety.
- Healthcare Sector Expansion:Heightened hygiene protocols and infection control measures in medical facilities worldwide drive significant volume demand for disposable gloves, particularly nitrile and latex variants for healthcare professionals.
- Manufacturing Concentration:The geographic concentration of rubber production and glove manufacturing in nations like Malaysia creates efficient, high-volume supply chains that lower costs for disposable gloves, stimulating global consumption.
Market Restraints
- Raw Material Volatility:Prices for natural rubber latex and synthetic inputs like nitrile butadiene rubber (NBR) are subject to significant fluctuation, creating margin pressure and pricing instability for glove manufacturers.
- Supply Chain Concentration:Heavy reliance on Southeast Asian countries, particularly Malaysia, for the global supply of disposable gloves creates vulnerability to regional logistical disruptions, trade policy shifts, and localized capacity constraints.
- End-of-Life Waste Management:The vast quantity of single-use gloves generates substantial plastic and rubber waste, posing an environmental challenge and creating regulatory pressure for sustainable materials and recycling solutions.
Strategic Opportunities
- Biodegradable Materials:Developing and commercializing biodegradable or compostable glove materials presents a significant opportunity to address sustainability concerns, particularly in the high-volume disposable glove segment for food service and healthcare.
- Smart Glove Integration:Incorporating flexible sensors and IoT connectivity into protective gloves can create new value by enabling worksite safety monitoring, tracking hand-arm vibration, and improving ergonomic assessments in industrial settings.
- Emerging Market Penetration:Expanding into industrializing economies in Latin America and Africa, where safety standard adoption is rising, offers new growth frontiers for both durable and disposable hand protection equipment.
Industry Challenges
- Complex Global Certification:Navigating and maintaining compliance with a fragmented landscape of regional standards, such as Europe's CE marking and North America's ANSI/ISEA standards, requires significant and continuous investment in testing and documentation.
- Recycling Infrastructure Deficits:The lack of scalable, cost-effective recycling infrastructure for mixed-material and contaminated gloves remains a primary operational barrier to creating a circular economy for hand protection products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Protection Equipment Market |
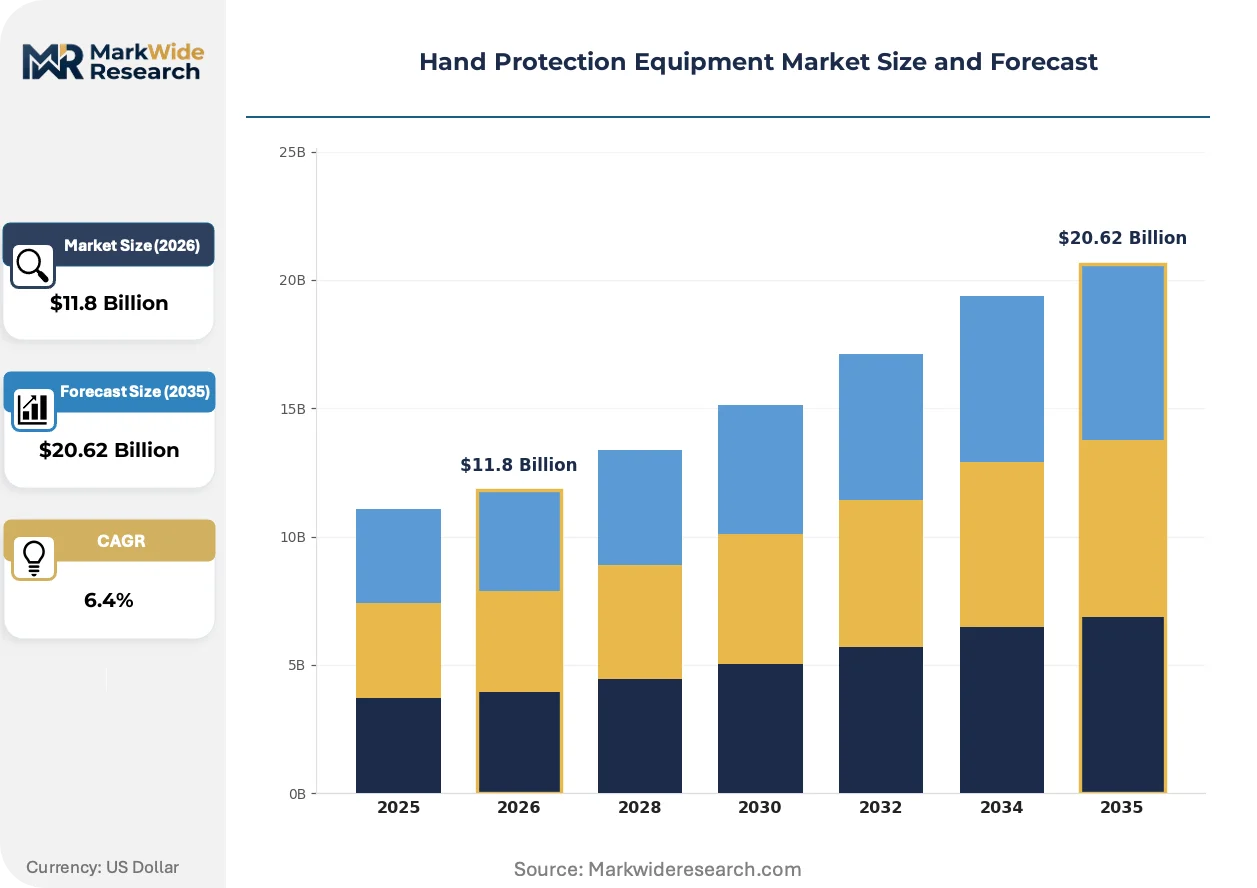
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Mitts, Finger Guards, Arm Guards Material: Leather, Rubber, PVC, Cotton Application: Construction, Manufacturing, Healthcare, Food Processing End User: Industrial Workers, Healthcare Professionals, Food Handlers, Maintenance Staff |
| Companies Covered | Top Glove Corporation Bhd, Hartalega Holdings Berhad, Superior Glove, Ansell Ltd., MCR Safety, SHOWA Group, Adenna LLC, 3M Company, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Protection Equipment Market Strategic Shifts & Innovations
Material science advancements are fundamentally reordering the market, prioritizing engineered performance over traditional materials. This pivot favors manufacturers capable of translating material properties like cut resistance and chemical impermeability into certified, task-specific protection, moving the basis of competition from price to performance.
Advanced synthetic fibers, including high-performance polyethylene (HPPE) and aramid, deliver superior protection against mechanical hazards. Industrial sectors like automotive assembly and metal fabrication are rapidly adopting gloves made from these materials. This technological shift is absorbing the market value previously held by traditional leather and cotton gloves, concentrating profit with specialized fiber and yarn producers.
Regulatory frameworks are becoming more prescriptive, defining product performance with greater specificity. Europe's EN 388 standard, for example, uses a quantitative rating system for abrasion, cut, tear, and puncture resistance that must be displayed on the product. This forces manufacturers to engineer to verifiable metrics, impacting the design of all durable mechanical gloves sold within the European Union.
Buyer behavior is evolving from unit-cost purchasing toward a total cost of ownership (TCO) analysis. This model, which factors in injury reduction and insurance savings, disrupts commodity-driven procurement in favor of consultative sales. The shift is most visible in large manufacturing and construction firms in North America, where high worker compensation costs justify investment in higher-performance protective equipment.
Hand Protection Equipment Market Segmentation
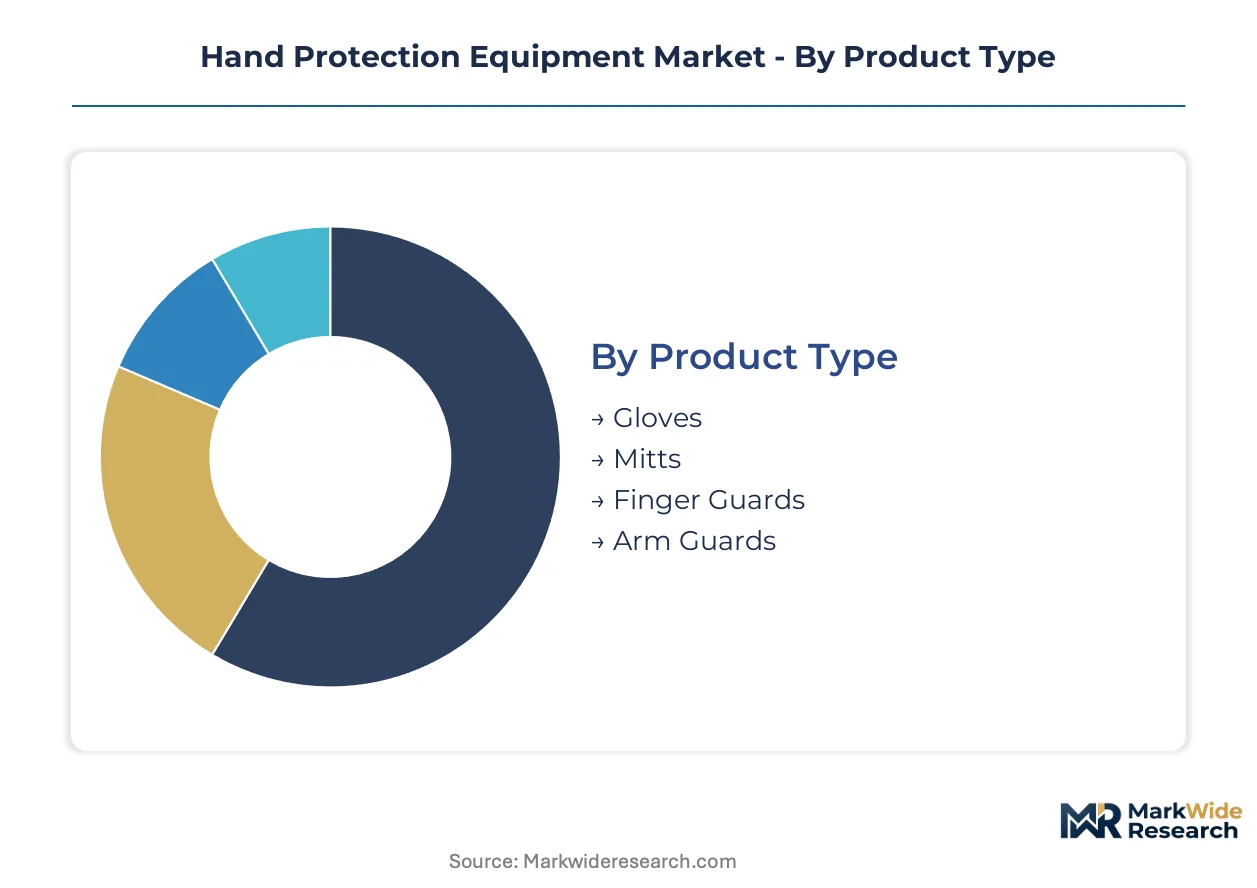
Market segmentation provides a structured view of the Hand Protection Equipment landscape, revealing specific demand drivers and regulatory influences across diverse product types, materials, applications, and end users. Understanding these distinctions is crucial for manufacturers to tailor product development and market penetration strategies effectively.
Product Type:
Product types in hand protection equipment face varying certification requirements, with some demanding rigorous testing for mechanical or chemical resistance, while others prioritize basic barrier protection.
- Gloves:These form the largest category, providing comprehensive hand coverage and come in numerous forms, from disposable examination gloves to heavy-duty industrial models. Demand concentrates heavily in healthcare and manufacturing, driven by stringent hygiene protocols and occupational safety mandates from OSHA and Europe's CE marking.
- Arm Guards:Designed to extend protection beyond the hand, these shield forearms from cuts, abrasions, and thermal hazards, often made from high-performance fibers. Adoption is increasing in metal fabrication and automotive assembly, where extended arm protection is critical for worker safety.
- Mitts:Offering less dexterity but superior thermal or impact protection, mitts are primarily used in extreme temperature environments or for heavy material handling. Found in foundries and cold storage facilities.
- Finger Guards:Small, specialized protectors designed to shield individual fingers from specific hazards like cuts, abrasions, or repetitive strain. Utilized in intricate assembly tasks or food processing.
Gloves sit at the top of the volume ranking, with Arm Guards climbing the fastest.
Material:
Material choices for hand protection equipment are dictated by specific performance characteristics and their underlying cost structures, influencing both durability and disposability.
- Rubber:Encompasses both natural rubber latex and synthetic rubbers like nitrile, offering excellent elasticity, chemical resistance, and barrier protection. Demand is concentrated in the healthcare sector and food processing, driven by the need for infection control and allergen-free options.
- PVC:Polyvinyl chloride materials provide strong chemical resistance against acids, bases, and oils, making them suitable for specific industrial applications. Adoption is steady in chemical handling and petrochemical industries, where robust chemical barriers are essential.
- Leather:A traditional material known for its durability, abrasion resistance, and comfort, typically used in heavy-duty industrial gloves for construction and welding. Demand remains consistent in rugged outdoor and heavy manufacturing environments.
- Cotton:Offers breathability and comfort, often used as a liner or for light-duty tasks, providing basic protection against dirt and minor abrasions. Employed in general assembly and warehousing operations.
Demand for Rubber materials is expanding most quickly, driven by healthcare sector needs, while Leather maintains a steady presence in industrial applications.
Application:
Applications for hand protection equipment are fundamentally shaped by the unique hazard exposure profiles present in each industry, from sharp objects to corrosive chemicals.
- Healthcare:This segment demands high volumes of disposable gloves for infection control, barrier protection, and handling biological hazards. Regulations from health authorities globally drive consistent procurement of certified medical-grade gloves.
- Manufacturing:Encompasses diverse sub-sectors like automotive, electronics, and machinery, requiring a wide range of gloves for cut, abrasion, chemical, and impact protection. Stringent occupational safety standards, such as those from OSHA, influence product selection.
- Construction:This sector requires durable, mechanical-resistant gloves for protection against cuts, punctures, abrasions, and impacts during heavy-duty tasks. Demand is consistent for robust gloves certified to standards like EN 388.
- Food Processing:Requires gloves that ensure hygiene and prevent contamination, often disposable latex or nitrile gloves, which must meet food-grade safety standards. Compliance with food safety regulations drives product specifications.
The Healthcare segment commands the largest share, while Construction shows consistent demand for durable protective solutions.
End User:
End user segments exhibit distinct procurement patterns and prioritize different attributes, ranging from bulk disposable volumes to highly specialized, durable gear.
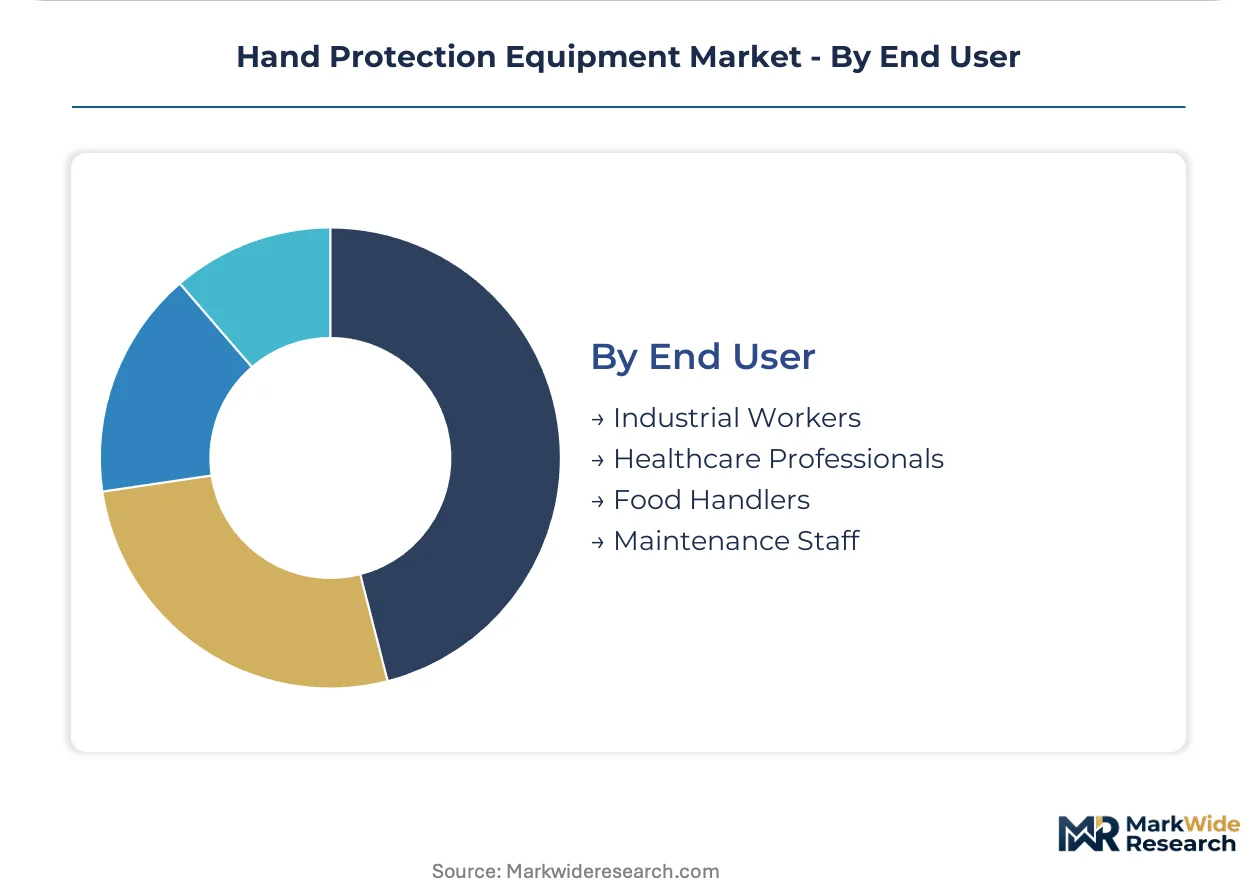
- Industrial Workers:This broad category includes professionals in manufacturing, construction, and utilities who require task-specific protection against mechanical, chemical, and thermal hazards. Their purchasing decisions are heavily influenced by safety compliance and product durability.
- Healthcare Professionals:Encompasses doctors, nurses, and laboratory technicians who rely on sterile or non-sterile disposable gloves for patient care, examinations, and handling medical materials. Infection control protocols and patient safety drive their high-volume consumption.
- Food Handlers:Workers in food service, processing, and preparation use gloves to maintain hygiene and prevent cross-contamination. Their primary concerns are food safety compliance and comfort for prolonged use.
- Maintenance Staff:These workers require versatile gloves that protect against dirt, chemicals, and minor cuts during routine repair and upkeep tasks across various environments. Durability and general-purpose protection are key considerations.
Industrial Workers drive significant value, while Healthcare Professionals represent a substantial volume segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's robust manufacturing concentration anchors the global supply of disposable hand protection equipment. This specialized production capacity supports diverse industries worldwide. Compliance with varying national safety standards drives localized product development.
Malaysia
Malaysia's strong rubber production base drives high-volume disposable glove manufacturing. The country's Department of Standards Malaysia mandates quality and safety for exported medical devices. Klang Valley and Penang host major glove production facilities, serving global healthcare and food processing sectors.
United States
Industrial workers in the United States demand durable mechanical gloves for construction and manufacturing. OSHA regulations compel broad adoption of personal protective equipment across all sectors. Major industrial hubs like the Great Lakes region focus on high-performance industrial safety solutions.
Germany
German industrial sectors prioritize advanced hand protection for precision manufacturing and chemical handling. Europe's EN 388 standard sets stringent performance requirements for mechanical risks. The Rhine-Ruhr area and Bavaria contain significant automotive and chemical industries requiring specialized gloves.
China
China's expanding manufacturing base and construction activities create substantial demand for both disposable and durable gloves. The country's GB standards increasingly align with international safety benchmarks for personal protective equipment. The Yangtze River Delta region is a major production and consumption hub for diverse hand protection types.
India
India's rapidly industrializing economy and growing healthcare sector fuel demand for affordable and certified hand protection. The Bureau of Indian Standards (BIS) formulates safety guidelines for industrial and medical protective gear. Cities like Mumbai and Chennai exhibit rising consumption due to expanding healthcare infrastructure and manufacturing.
Hand Protection Equipment Market Key Industry Players
Global majors compete with regional champions across performance tiers and material science capabilities. The market structure exhibits consolidation among top-tier providers and fragmentation within the high-volume disposable segment. Strategic archetypes include diversified industrial safety conglomerates and specialized material science innovators. Companies often engage in capacity expansion and strategic partnerships to secure raw material supply.
Within the high-volume disposable glove segment, Malaysia-based Top Glove Corporation Bhd exemplifies scale-driven manufacturing for healthcare and food processing. Ansell Ltd., an Australia-based entity, occupies a position as a diversified provider across both industrial and medical applications. Honeywell International Inc., a US-based industrial conglomerate, anchors advanced material innovation for high-performance protective fibers and integrated safety solutions.
| Leading Market Players |
|---|
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Superior Glove |
| Ansell Ltd. |
| MCR Safety |
| SHOWA Group |
| Adenna LLC |
| 3M Company |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
Outsourced production of disposable gloves, concentrated in Southeast Asia, anchors global supply and dictates pricing power for high-volume segments. This integration choice directly impacts the cost structure for manufacturers and the ultimate pricing for end-users across diverse applications.
Pricing Analysis
Input-cost pass-through remains a dominant feature, particularly for natural rubber latex and nitrile butadiene rubber. The market predominantly uses a per-unit transactional model for disposable gloves and contract-based pricing for durable industrial equipment. Price differentiation stems from certification levels like EN 388, material quality, and brand reputation. Pricing pressure stems from raw material volatility, impacting manufacturer margins. Food handlers exhibit the highest price sensitivity, while industrial workers prioritize performance and safety compliance over cost.
Supply Chain Analysis
Single-source vulnerability sits with Malaysia and China for high-volume disposable glove manufacturing. Geographic concentration in these nations creates dependencies for global supply. Raw material dependencies include natural rubber latex and nitrile butadiene rubber, which are subject to significant price fluctuations. Commodity price volatility presents a structural risk for manufacturers. Distribution runs through multi-tiered networks, involving specialized industrial safety distributors and medical supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market acts as a stable compounder, driven by the persistent and expanding need for occupational safety across industrializing economies.
For Market Incumbents: Anchor market share through continuous material science innovation, focusing on advanced synthetic fibers for superior cut and abrasion resistance. Invest in capacity expansion within diverse geographic locations to mitigate regional supply chain disruptions and regulatory changes. Counter the threat of traditional material displacement by developing certified, task-specific protection solutions. Prioritize certification investment for new product lines.
For New Entrants and Emerging Players: Digital-first distribution channels offer a direct route to market, circumventing established networks. Target underpenetrated emerging markets in Latin America and Africa, where safety standard adoption is rising. Focus on niche applications requiring specialized protection, such as smart gloves with integrated sensors for ergonomic assessments. Leverage an e-commerce go-to-market strategy emphasizing performance-based value propositions.
For Investors and Strategic Acquirers: Roll-up economics work for mid-sized manufacturers because fragmented regional markets create consolidation opportunities. Long-term viability is strong due to non-discretionary safety spending and evolving regulatory mandates. Identify acquisition targets with strong material science capabilities or established distribution networks in high-growth industrial sectors. The signal to watch is successful commercialization of biodegradable glove materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secures high-volume supply for global healthcare and industrial sectors. |
| Material R&D Investment | Drives superior cut and abrasion resistance for industrial applications. |
| Digital Channel Development | Expands reach to small and medium-sized enterprises globally. |
| Regional Market Penetration | Captures demand growth in industrializing economies like India. |
| Sustainability Certification | Addresses end-of-life waste concerns for disposable glove segments. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. The research methodology combines in-depth interviews with industry stakeholders and rigorous secondary data validation. Primary interviews involved safety managers, procurement officers, material scientists, and regulatory compliance specialists. Secondary sources included OSHA reports, EN 388 certification databases, and national trade statistics, triangulated with bottom-up and top-down analyses.
Modeling granularity extends across product type, material, application, and end-user segments, alongside regional demand patterns. The analytical framework projects market trajectory over the projection horizon. Compound annual growth rates were derived from historical trends and future demand drivers. Forecast inputs include industrial output growth rates and healthcare spending projections across the analysis window.
Raw material price volatility, evolving regulatory frameworks, and geopolitical trade shifts are the dominant revision risks for future projections. Forecasts reflect assumptions regarding economic stability and technological adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Military Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Public Address and Voice Alarm Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplementary Protectors Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market